
 Container Docking Stations Market | 2026-2036
Container Docking Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Container Docking Stations Market Analytics
A capital-intensity divergence between integrated electronics manufacturers and peripheral specialists is unwinding competitive dynamics in container docking stations. Dell Technologies leverages captive semiconductor sourcing and in-house firmware development to sustain margin resilience across enterprise contracts. CalDigit specializes in Thunderbolt-certified architectures, anchoring premium positioning among creative and logistics workflows requiring high-bandwidth data transfer.
Container docking stations are electromechanical interface hubs that consolidate power delivery, video output, and data connectivity through standardized ports such as USB-C or Thunderbolt 4, typically supporting 100W power pass-through and 40Gbps transfer rates for industrial computing environments. Their primary purpose is to streamline container management and inventory control operations by enabling single-cable connectivity between ruggedized field devices and backend enterprise systems. Multi-docking stations dominate volume in warehousing applications where simultaneous device charging and synchronization reduce operational downtime, while portable docking stations represent the fastest-expanding category as mobile logistics workforces abandon fixed workstation dependencies. USB-C technology leads unit shipments due to universal connector mandates from the EU and major OEMs, though Thunderbolt retains margin concentration in high-throughput shipping operations requiring daisy-chain display configurations.
The EU Green Deal and REACH chemical compliance frameworks restrict hazardous substances in connector plating and cable sheathing, compelling manufacturers to reformulate supply chains or forfeit European market access. The US FCC and EPA jointly influence electromagnetic interference thresholds and e-waste disposal requirements that shape product lifecycle obligations for docking station vendors. Stakeholders must monitor evolving port standardization battles between USB-IF and Thunderbolt certification bodies, as protocol dominance will determine which hardware architectures retain compatibility investments across the next decade of logistics infrastructure deployment.
Market Dynamics
USB-C standardization mandates from the EU and escalating e-commerce fulfillment velocity are compressing product refresh cycles and forcing modular architecture redesigns across the container docking station supply base.
Growth Catalysts
- E-Commerce Fulfillment Expansion:Last-mile logistics operators in Germany and the Netherlands are deploying multi-docking stations to synchronize ruggedized handhelds across warehouse floors, cutting device downtime during peak seasonal surges.
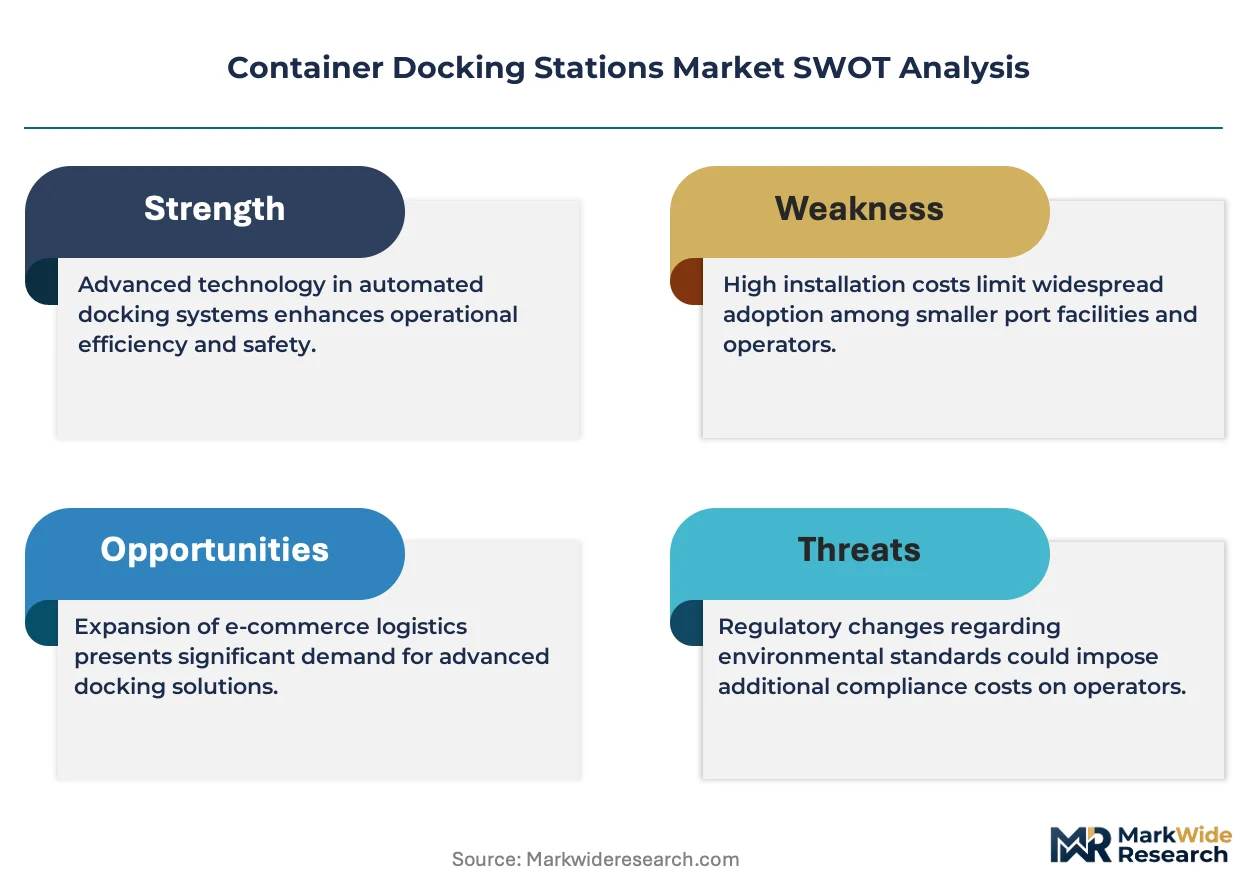
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based cooling in adjacent industrial electronics is redirecting procurement toward docking stations with passive thermal designs certified under updated energy efficiency frameworks.
- Thunderbolt 4 Adoption:High-throughput shipping terminals handling 4K surveillance feeds and real-time inventory telemetry are specifying 40Gbps daisy-chain architectures to collapse cabling complexity.
Market Restraints
- Controller Chip Concentration:Taiwan-based semiconductor fabricators supply the majority of USB-C PD controllers and Thunderbolt retimers, exposing vendors to single-source risk during foundry allocation cycles.
- REACH Compliance Costs:ECHA restrictions on cadmium and lead in connector plating force reformulation of supply chains serving European customers, adding 8-14 months to qualification timelines.
- Wireless Docking Substitution:Wi-Fi 6E and private 5G networks in greenfield logistics facilities are displacing cabled connectivity for non-power-critical applications, compressing addressable volume in mobile workforce segments.
Strategic Opportunities
- India Logistics Modernization:The country's PLI scheme for electronics manufacturing is attracting docking station assembly investments to serve domestic e-commerce growth and export-oriented SEZ operations.
- CE-MDR Convergence:Medical device logistics requiring sterile chain-of-custody tracking are creating demand for antimicrobial-certified docking stations with embedded RFID authentication modules.
- Solar-Powered Field Deployments:Off-grid container yards in Sub-Saharan Africa and Southeast Asia are specifying 100W PD pass-through stations with wide-input DC compatibility for photovoltaic integration.
Industry Challenges
- Thunderbolt Certification Bottlenecks:Intel's mandatory compliance testing for logo licensing creates 4-6 month validation queues that delay product launches and compress revenue recognition windows.
- Firmware Security Talent Scarcity:Enterprises now require SBOM disclosure and CVE patching SLAs, yet qualified embedded security engineers command premium compensation that mid-tier vendors struggle to match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Docking Stations Market |
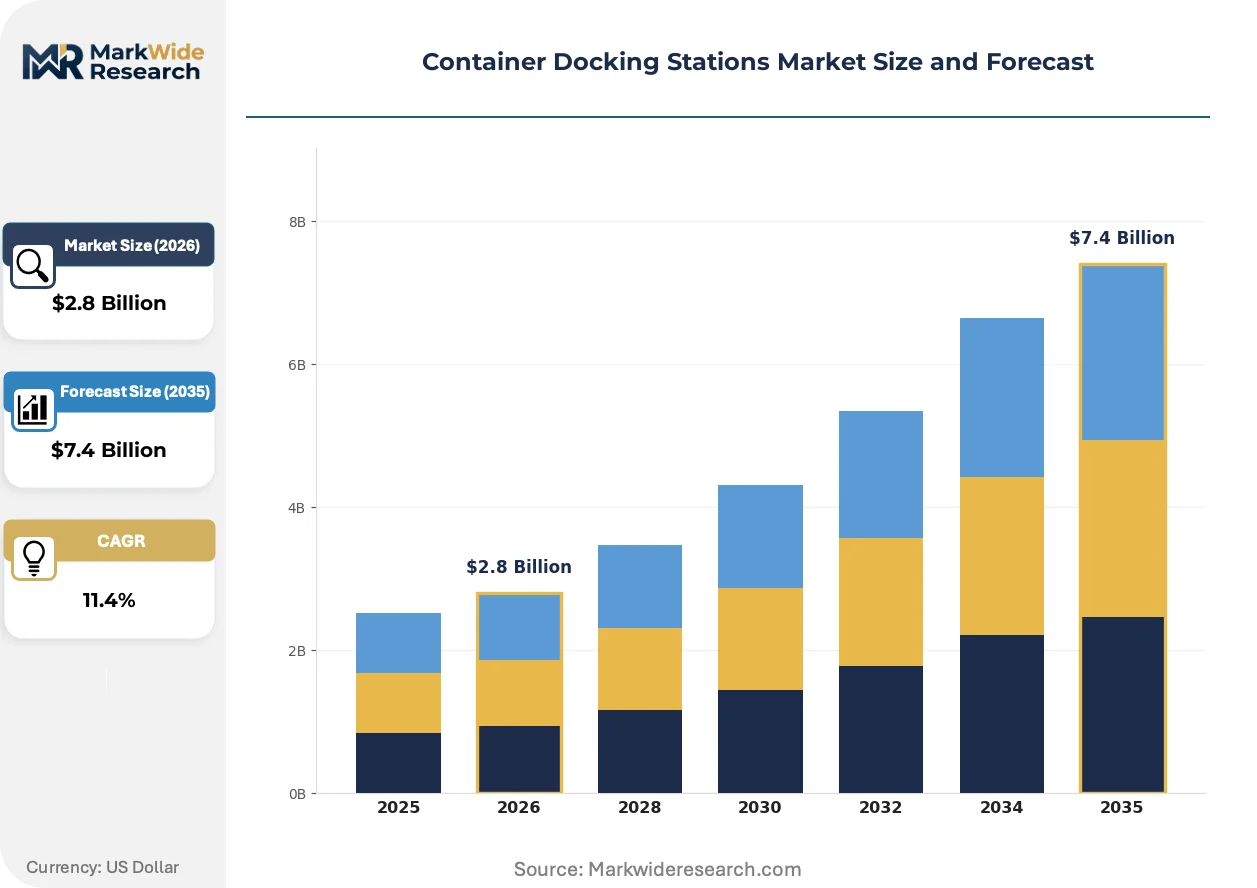
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Docking Station, Multi-Docking Station, Portable Docking Station, Fixed Docking Station Technology: USB-C, Thunderbolt, Ethernet, HDMI End User: Logistics Firms, Shipping Companies, Warehousing Providers, E-commerce Businesses Application: Container Management, Inventory Control, Shipping Operations, Data Transfer |
| Companies Covered | Dell Technologies, HP Inc., Lenovo Group Ltd., Targus, Kensington Technology Group, Plugable Technologies, Belkin International, CalDigit, StarTech.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Docking Stations Market Evolving Landscape
Gallium nitride power semiconductors and software-defined port configuration are collapsing physical footprints while expanding functional density in next-generation docking architectures.
GaN-based power delivery controllers are miniaturizing thermal management requirements in 100W-class docking stations, enabling fanless designs that withstand particulate contamination in container yard environments. Third-party logistics operators in Rotterdam and Singapore are specifying these compact units for mobile cart deployments where space constraints previously mandated larger, actively cooled alternatives. The technology is miniaturizing enclosure volumes by 40-60% versus silicon MOSFET predecessors, allowing vendors to embed additional sensor arrays without expanding physical footprint.
REACH and RoHS amendments from ECHA are mandating halogen-free flame retardants in cable sheathing and PCB substrates, compelling manufacturers to qualify phosphorus-nitrogen compounds that alter dielectric properties. European distributors now require batch-level compliance documentation for all interconnect products, shifting procurement evaluation criteria toward traceability systems rather than purely technical specifications. Medical and food logistics segments within the EU are absorbing premium pricing for fully certified architectures to avoid downstream liability exposure.
Direct procurement relationships between large e-commerce fulfillment operators and original design manufacturers are disintermediating traditional distribution channels for volumes exceeding 10,000 units annually. Amazon, Zalando, and regional logistics platforms in Germany are engaging ODMs in Shenzhen and Taoyuan for custom firmware loads and co-branded enclosures, compressing margin capture for value-added resellers. This concentration is most visible in Hamburg and Duisburg, where port modernization budgets are consolidating vendor panels to three or fewer approved suppliers per terminal operator.
Container Docking Stations Market Segmentation
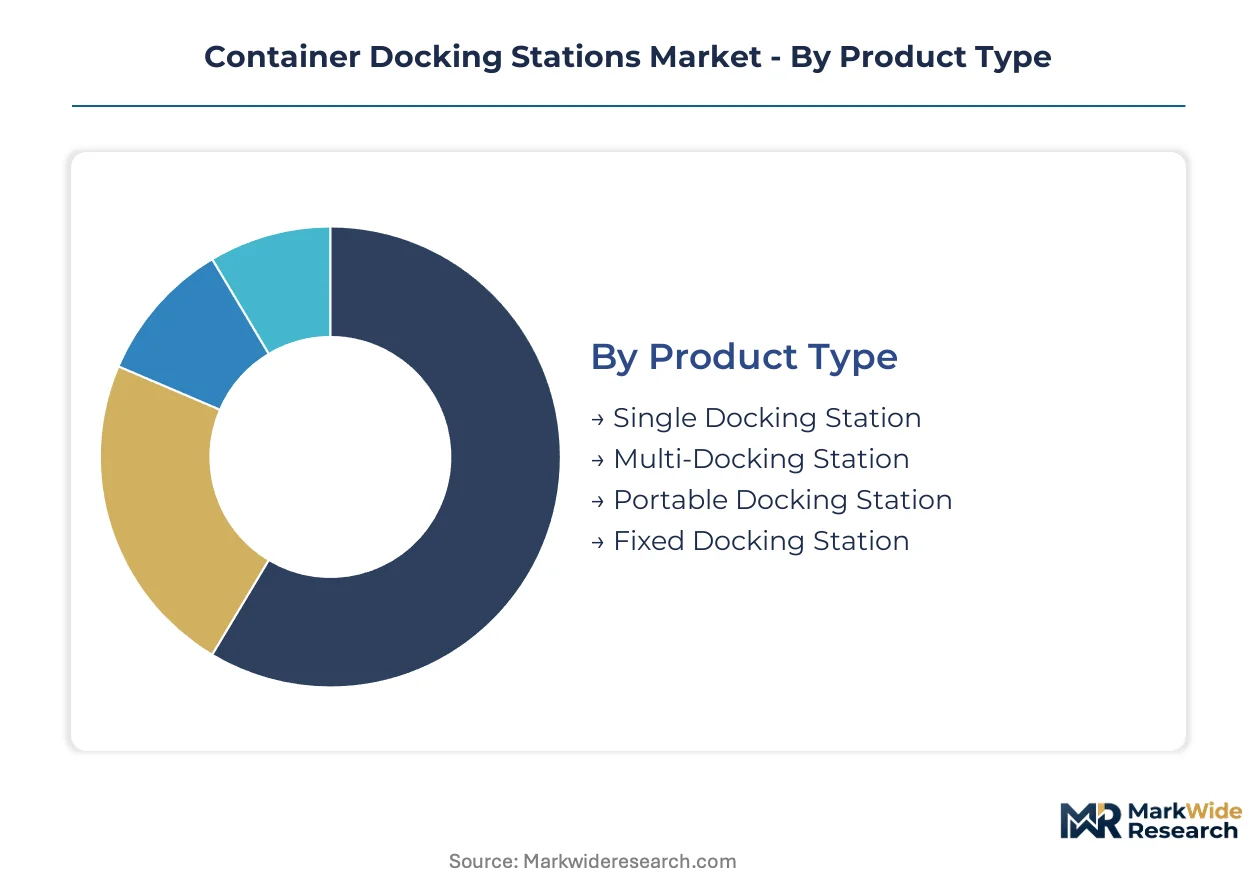
Segmentation in container docking stations reveals how procurement criteria diverge across regulatory environments and operational intensities. Product architecture, connectivity protocol, and end-use workflow each impose distinct compliance burdens and performance thresholds that reshape vendor positioning.
Product Type:
REACH and RoHS amendments from ECHA mandate halogen-free flame retardants and cadmium-free connector plating, forcing enclosure redesigns that favor passive thermal architectures over actively cooled alternatives.
- Multi-Docking Station:These units consolidate simultaneous charging and synchronization for 8-16 ruggedized handhelds through integrated USB-C PD hubs. Rotterdam and Singapore port operators specify these for warehouse floor deployments where seasonal volume surges demand minimal device downtime. ECHA batch-level documentation requirements now dominate procurement evaluations over pure technical specifications.
- Portable Docking Station:Compact 100W-class units with GaN power controllers enable fanless operation in particulate-heavy container yards. Mobile logistics workforces across Germany and the Netherlands are abandoning fixed workstation dependencies, driving specification of wide-input DC compatibility for solar integration in off-grid deployments.
- Single Docking Station:Individual-device units serving field maintenance crews requiring isolated connectivity for telemetry uploads.
- Fixed Docking Station:Permanently installed rack-mount systems anchoring backend enterprise integration in automated terminal operations.
Multi-docking stations handle the majority of throughput; portable docking stations are expanding most quickly on share.
Technology:
Cost tier differentiation separates premium-certified architectures from commodity interconnects, with Intel's mandatory Thunderbolt compliance testing creating 4-6 month validation queues that compress revenue recognition windows for logo-bearing products.
- USB-C:Universal Power Delivery controllers dominate unit shipments through EU mandate alignment and OEM standardization. Taiwan-based foundries supply the majority of PD controllers, exposing vendors to single-source allocation risk during fab capacity constraints.
- Thunderbolt:40Gbps daisy-chain architectures with retimer chips command margin concentration in high-throughput terminals handling 4K surveillance and real-time inventory telemetry. Intel's certification bottlenecks delay launches, forcing vendors to pre-validate designs 8-14 months ahead of procurement windows.
- Ethernet:Wired backbone connectivity for non-power-critical applications in legacy facility retrofits.
- HDMI:Video output specification for local display mirroring in container yard supervision stations.
USB-C captures the volume base; Thunderbolt claims the steepest expansion trajectory in value terms.
End User:
Customer type concentration is redirecting distribution channels, with direct procurement relationships between large fulfillment operators and Shenzhen ODMs disintermediating traditional resellers for volumes exceeding 10,000 units annually.
- E-commerce Businesses:Amazon, Zalando, and regional German platforms engage ODMs for custom firmware loads and co-branded enclosures. Hamburg and Duisburg port modernization budgets consolidate vendor panels to three or fewer approved suppliers per terminal operator.
- Logistics Firms:Third-party operators in Rotterdam specify GaN-based compact units for mobile cart deployments where space constraints previously mandated larger alternatives.
- Shipping Companies:Vessel-to-shore synchronization requirements driving marine-grade enclosure specifications.
- Warehousing Providers:Peak seasonal surge handling through multi-device synchronization across distributed floor operations.
E-commerce businesses concentrate procurement leverage; logistics firms are climbing the fastest on technology refresh intensity.
Application:
Margin structure varies by workflow criticality, with medical and food logistics segments absorbing premium pricing for fully certified architectures to avoid downstream liability exposure under EU traceability mandates.
- Container Management:Electromechanical interface hubs streamlining yard operations through single-cable connectivity between ruggedized field devices and backend systems. Sub-Saharan African and Southeast Asian off-grid yards specify 100W PD pass-through with photovoltaic DC compatibility.
- Inventory Control:Real-time telemetry synchronization requiring 40Gbps throughput for RFID authentication modules in sterile chain-of-custody tracking. CE-MDR convergence is creating demand for antimicrobial-certified docking stations in medical device logistics.
- Shipping Operations:Vessel manifest synchronization and customs documentation upload workflows.
- Data Transfer:Bulk telemetry offload from container sensors to enterprise ERP systems.
Container management anchors procurement volume; inventory control is gaining share fastest on compliance-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's port modernization clusters while cost-sensitive procurement dominates Indian logistics corridors. This asymmetry reflects divergent regulatory stringency and infrastructure investment cycles across major economies.
Germany
Hamburg's container terminal automation and Duisburg's inland port digitization anchor European procurement intensity for multi-docking stations. The EU F-Gas Regulation and REACH compliance frameworks mandate halogen-free flame retardants and cadmium-free plating, extending qualification timelines by 8-14 months. Bavaria's industrial electronics fabricators supply passive thermal architectures to Hamburg operators seeking fanless designs for particulate-heavy yard environments.
United States
Amazon's fulfillment network and third-party logistics operators drive specification of GaN-based compact units for mobile cart deployments. FCC electromagnetic interference thresholds and EPA e-waste disposal requirements shape product lifecycle obligations for docking station vendors. The Pacific Northwest's tech manufacturing clusters and Southeast distribution hubs concentrate procurement leverage among large fulfillment operators engaging ODMs directly.
China
Shenzhen and Taoyuan-based ODMs capture direct procurement relationships with global e-commerce platforms exceeding 10,000-unit annual volumes. MIIT standardization efforts and dual carbon goals pressure manufacturers toward energy-efficient controller architectures. The Yangtze River Delta's semiconductor packaging facilities supply USB-C PD controllers that dominate unit economics across mid-tier product lines.
India
Domestic e-commerce growth and export-oriented SEZ operations under the PLI scheme attract docking station assembly investments from multinational vendors. BIS certification requirements and DGFT import regulations create friction for unqualified product entries. Maharashtra's logistics corridors and Gujarat's port modernization projects concentrate demand for wide-input DC compatible units serving solar-powered field deployments.
Singapore
High-throughput transshipment terminals specify Thunderbolt-certified architectures for 4K surveillance and real-time inventory telemetry workflows. The country's national electronics regulator enforces IEC standards alignment that exceeds baseline ASEAN requirements. The Tuas mega-port development consolidates vendor panels to three or fewer approved suppliers per terminal operator, compressing margin capture for peripheral specialists.
Container Docking Stations Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the container docking station supply base. Integrated electronics manufacturers leverage captive semiconductor sourcing and in-house firmware development to sustain margin resilience across enterprise contracts. Peripheral specialists concentrate on certification-intensive niches requiring Thunderbolt validation or medical-grade antimicrobial specifications. The competitive arena exhibits tiered consolidation with two dominant moves: direct ODM engagement by large fulfillment operators disintermediating traditional distribution, and GaN semiconductor adoption collapsing thermal management footprints.
Within the integrated systems tier, Dell Technologies and HP Inc. exemplify players with backward integration into controller chip sourcing and enterprise firmware stacks. CalDigit occupies a position among certification-focused specialists anchoring premium positioning through Thunderbolt logo licensing. These three represent divergent strategic postures—scale-driven supply chain control versus compliance-intensive niche concentration—rather than direct segment overlap.
| Leading Market Players |
|---|
| Dell Technologies |
| HP Inc. |
| Lenovo Group Ltd. |
| Targus |
| Kensington Technology Group |
| Plugable Technologies |
| Belkin International |
| CalDigit |
| StarTech.com |
| Others |
Value Network & Pricing Analysis
Intel's Thunderbolt certification regime gates both supply qualification timelines and price differentiation simultaneously, forcing vendors to absorb 4-6 month validation queues that separate logo-bearing premium architectures from unbranded commodity alternatives. This certification bottleneck compresses revenue recognition windows for certified suppliers while amplifying margin capture for those who clear the compliance hurdle.
Pricing Analysis
Configured-to-order pricing for custom firmware loads and co-branded enclosures commands a 30-50% premium over standard catalog units in the container docking station market. Three-tier pricing structure across premium Thunderbolt-certified, standard USB-C PD, and economy unbranded tiers reflects certification investment amortization and volume scale. Cost compression in the economy tier is intensifying because direct ODM engagement by Amazon and Zalando disintermediates traditional distribution markups. Logistics firms in Rotterdam and Singapore exhibit lowest price sensitivity due to downtime cost calculus, while Indian domestic e-commerce operators remain most price-sensitive.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for USB-C PD controllers and Thunderbolt retimer chips that feed downstream assembly. The supply chain draws from gallium nitride substrates for power semiconductors, halogen-free flame retardants for REACH-compliant cable sheathing, and precision connector plating free of cadmium and lead. Single-source vulnerability concentrates in Taiwan-based foundry allocation cycles during semiconductor capacity crunches. Distribution runs through direct procurement relationships between large fulfillment operators and Shenzhen ODMs for volumes exceeding 10,000 units annually, bypassing traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in container docking stations as e-commerce fulfillment operators abandon fixed workstation dependencies and specify mobile-compatible architectures, creating niche openings for GaN-specialized and solar-integrated product lines.
For Market Incumbents: Fortify certification moats by pre-validating Thunderbolt designs 8-14 months ahead of procurement windows to offset Intel's compliance bottlenecks. Deepen backward integration into controller chip sourcing to reduce exposure to Taiwan foundry allocation volatility. Anchor enterprise contracts with SBOM disclosure and CVE patching SLAs that mid-tier vendors cannot match. For New Entrants and Emerging Players: Lead with antimicrobial-certified architectures targeting CE-MDR medical device logistics where sterile chain-of-custody tracking creates compliance-driven replacement cycles. Solar-powered field deployments in Sub-Saharan Africa and Southeast Asia offer the most penetrable white space given off-grid container yard requirements. Pursue co-development partnerships with Indian PLI scheme beneficiaries to access domestic e-commerce growth and export-oriented SEZ operations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across GaN-based portable docking architectures as miniaturized thermal management collapses enclosure volumes and working capital requirements. Long-term viability over a 5-10 year window favors acquisition targets with captive firmware development capabilities and direct ODM relationships bypassing distribution intermediaries. Watch for Intel's Thunderbolt 5 specification timeline as the critical inflection signal determining which certification investments retain compatibility relevance.| Strategic Initiative | Industry Significance |
|---|---|
| Thunderbolt 4/5 Certification Investment | Intel's mandatory compliance testing creates 4-6 month validation queues that delay product launches and compress revenue recognition windows. |
| GaN Semiconductor Adoption | Gallium nitride power controllers miniaturize thermal management by 40-60% versus silicon MOSFET predecessors, enabling fanless designs for particulate-heavy container yards. |
| Direct ODM Engagement | Amazon and Zalando bypass traditional distribution channels for volumes exceeding 10,000 units annually, consolidating vendor panels to three or fewer approved suppliers per terminal operator. |
| REACH Compliance Reformulation | ECHA restrictions on cadmium and lead in connector plating force 8-14 month qualification timeline extensions, shifting procurement evaluation criteria toward batch-level traceability systems. |
| Solar-Compatible DC Architecture Development | Off-grid container yards in Sub-Saharan Africa and Southeast Asia specify 100W PD pass-through stations with wide-input DC compatibility for photovoltaic integration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and semiconductor foundry capacity disclosures to establish supply-side constraints. Primary interviews engaged procurement directors at German port operators, firmware engineers at Thunderbolt-certified vendors, and logistics technology leads at Rotterdam and Singapore terminals. Secondary validation drew from ECHA REACH amendment documentation, Intel certification bulletins, and EU F-Gas Regulation implementation guidance. Bottom-up unit shipment estimates triangulated against top-down port modernization budget allocations across Hamburg, Duisburg, and Tuas mega-port development.
Segmentation dimensions modeled include product architecture (multi-docking, portable, single, fixed), connectivity protocol (USB-C, Thunderbolt, Ethernet, HDMI), and end-use workflow (container management, inventory control, shipping operations, data transfer) across the analysis window. CAGRs were derived from logistic operator capital expenditure trajectories and e-commerce fulfillment velocity indices. Industry-specific forecast inputs incorporated EU mandate alignment timelines for USB-C standardization and passive thermal design certification thresholds under updated energy efficiency frameworks.
Forecasts assume regulatory continuity in EU REACH, RoHS, and F-Gas regimes; material policy shifts would require re-modeling supply chain qualification timelines and procurement evaluation criteria. Forecasts also assume stable Taiwan foundry allocation for USB-C PD controllers and Thunderbolt retimers; geopolitical disruption or capacity constraints would necessitate demand destruction scenarios. Recalibration cycles align with material shifts in port automation investment schedules and Intel's Thunderbolt specification roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Europe Offshore Support Vessels Market