
 Ship Plate Market | 2026-2036
Ship Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Plate Market Analysis
Long-term steel supply agreements with embedded price-adjustment clauses is repositioning how shipyards contract for hull materials. Nippon Steel leverages its integrated blast furnace network to sustain premium-grade AH36 and EH36 output for Japanese naval contractors. POSCO anchors its competitive stance through captive raw material access and dedicated plate mills at Pohang. ArcelorMittal competes across European shipyards with specialized thermomechanically rolled products certified for ice-class hulls.
Ship plate denotes hot-rolled structural steel sheet manufactured to marine classification society standards, typically featuring yield strengths from 355 MPa to 690 MPa with through-thickness toughness tested down to minus 40 degrees Celsius. These plates form the load-bearing hull shell, deck structures, and bulkheads of commercial and naval vessels where weldability and fatigue resistance govern operational lifespan. AH36 and DH36 material grades dominate current order books due to their balance of strength and formability for bulk carrier and tanker construction. The 10mm and 12mm thickness bands capture the majority of value as they serve primary hull girder applications where classification rules mandate minimum scantlings. Military ship end-use commands superior margin pools despite lower volumes, driven by ballistic protection requirements and specialized alloy specifications.
IMO's Energy Efficiency Existing Ship Index and the EU Emissions Trading System extension to maritime transport are reshaping newbuild specifications toward lighter, higher-strength hull designs. Japan's METI enforces JIS G 3106 standards that align with Class NK rules, while China's MIIT mandates GB 712 compliance for domestic yard steel sourcing. South Korea's KR classification society certifies plate suppliers under harmonized IACS procedures that govern export eligibility. Stakeholders must monitor divergence between regional carbon accounting methodologies and their cascading effects on steel procurement qualification criteria.
Market Dynamics
IMO's carbon intensity regulations are forcing hull material upgrades across commercial fleets, redirecting procurement toward higher-grade steel specifications and reshaping mill-certification requirements worldwide.
Growth Catalysts
- Fleet Modernization:NATO-aligned naval programs are expanding hull replacement schedules, creating sustained demand for ballistic-grade plate specifications.
- IMO EEXI Compliance:The Energy Efficiency Existing Ship Index mandates lighter hull designs, accelerating adoption of high-strength AH36 and EH36 grades.
- South Korean Shipbuilding Clusters:Concentrated yard capacity at Hyundai Heavy Industries and Samsung Heavy Industries suppliers anchors regional plate consumption.
Market Restraints
- Iron Ore Volatility:Blast furnace input costs swing with Australian and Brazilian mining output, compressing mill margins unpredictably.
- Supplier Concentration Risk:Premium-grade plate capacity clusters among integrated producers with captive raw material access, limiting buyer alternatives.
- Weldability Trade-offs:Ultra-high-strength grades above 690 MPa yield strength require specialized welding protocols that slow yard throughput.
Strategic Opportunities
- Arctic Ice-Class Certification:Thermomechanically rolled products for polar routes remain underserved, with only ArcelorMittal and POSCO holding dominant certifications.
- EU ETS Maritime Extension:Carbon pricing inclusion creates premium positioning for low-emission steel production methods.
- Digital Mill Certification:Blockchain-traceable plate documentation is emerging as a procurement differentiator for risk-averse shipowners.
Industry Challenges
- Welding Technician Scarcity:Specialized skills for high-strength grade joining are concentrated among aging workforces at Japanese and South Korean yards.
- Classification Society Divergence:JIS G 3106, GB 712, and KR harmonization gaps create compliance friction for multi-source procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Plate Market |
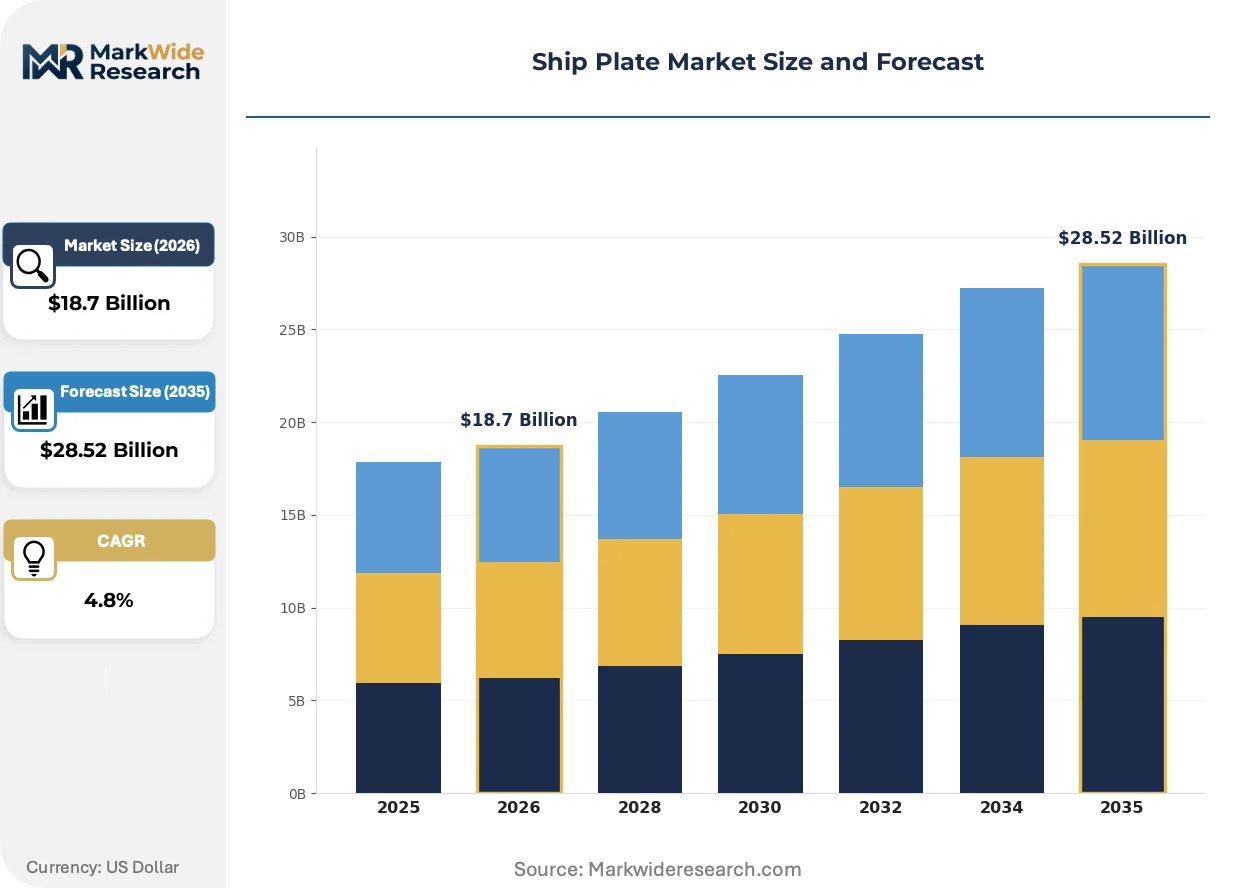
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Grade: AH36, DH36, EH36, ABS Thickness: 6mm, 8mm, 10mm, 12mm End Use: Cargo Ships, Tankers, Fishing Vessels, Military Ships Manufacturing Process: Hot Rolled, Cold Rolled, Blanking, Cutting |
| Companies Covered | Nippon Steel, Shougang Group, Baosteel Group, Tata Steel, Ansteel Group, POSCO, ArcelorMittal, SSAB, JFE Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Plate Market Emerging Trajectories
Thermomechanical rolling processes and digital certification systems are restructuring how plate quality is verified and valued, compressing traditional specification hierarchies.
Direct-quenched and tempered (DQ&T) plate production is overtaking conventional normalized rolling for ice-class hull applications. Norwegian and Finnish shipyards are specifying DQ&T grades for LNG carrier membrane tank supports. The process is overtaking legacy methods by delivering equivalent toughness at reduced alloy content, compressing material cost structures for Arctic-rated newbuilds.
EU Emissions Trading System extension to maritime transport is forcing mill-level carbon disclosure. Shipyards now require Environmental Product Declarations for hull steel, with Class NK and Lloyd's Register developing verification protocols. European owners are responding by qualifying low-emission plate suppliers ahead of 2026 compliance deadlines.
Long-term offtake agreements with embedded price-adjustment clauses are displacing spot procurement at major yards. Korean shipbuilders are locking five-year supply contracts with POSCO and Hyundai Steel, replacing quarterly tendering. This pattern is most visible in bulk carrier and tanker segments where fleet renewal programs concentrate demand predictability.
Ship Plate Market Segmentation
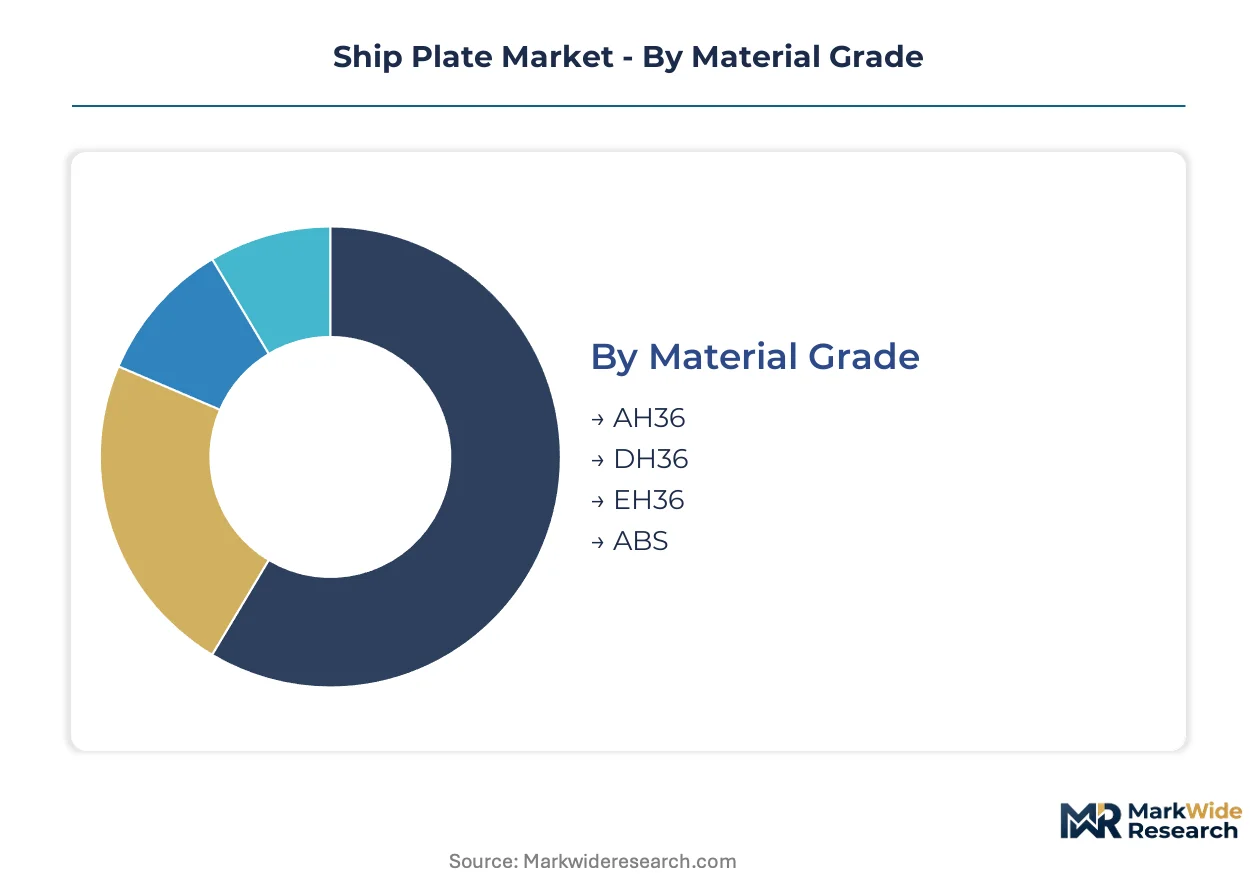
Ship plate procurement strategies diverge sharply across specification tiers, with material grade and thickness bands governing contract structures, mill certification requirements, and price-adjustment mechanisms. Classification society rules tie directly to segment selection, creating rigid qualification pathways that reshape supplier relationships.
Material Grade:
Yield strength thresholds segment this category from standardized commercial grades through specialized naval specifications, with customization intensity rising alongside toughness requirements and through-thickness ductility demands.
- AH36:Standard high-strength structural steel with 355 MPa minimum yield serves bulk carrier and container ship primary hull girder applications. Demand concentrates at South Korean yards building standardized merchant fleets where IMO EEXI compliance drives lighter scantling designs. POSCO and Hyundai Steel anchor supply through captive blast furnace output.
- DH36:Identical yield strength to AH36 but certified for minus 20 degrees Celsius toughness, capturing tanker and chemical carrier segments where low-temperature cargo exposure governs material selection. Japanese yards at Imabari and Oshima specify DH36 for LNG-ready tanker newbuilds.
- EH36:Minus 40 degrees Celsius certification suits polar route vessels and ice-class hulls where Arctic operational windows extend sailing seasons. Norwegian and Finnish owners mandate EH36 for Baltic and Barents Sea routes.
- ABS:American Bureau of Ships-certified specialty grades encompass ballistic protection specifications for naval end-use, with alloy additions of nickel and chromium for blast resistance. US Navy procurement locks suppliers into multi-year qualification cycles.
Leading the category by volume: AH36. Growing fastest: EH36.
Thickness:
Scantling rules from IACS member societies create discrete demand bands, with cost-per-tonne economics shifting nonlinearly as plate gauge moves from secondary structure to primary load-bearing elements.
- 10mm:Dominant specification for deck plating and shell envelope where classification minimums intersect with welding productivity. Korean bulk carrier series production at Hyundai Heavy Industries consumes 10mm bands in continuous campaigns.
- 12mm:Primary hull girder bottom shell and sheer strake applications require this gauge for longitudinal strength compliance. Japanese shipbuilders specify 12mm for Panamax and Capesize hulls under Class NK supervision.
- 6mm:Superstructure, bulkhead non-tight boundaries, and secondary stiffening employ this lighter gauge where weight reduction trumps structural redundancy. Chinese yards leverage 6mm for cost-competitive feeder container ships.
- 8mm:Intermediate specification bridges primary and secondary applications, appearing in tween deck structures and machinery space boundaries. European repair yards specify 8mm for mid-life hull renewal projects.
10mm and 12mm together anchor procurement volumes. Steepest expansion trajectory: 6mm as lightweight hull designs proliferate.
End Use:
Margin structures invert across this category, with lowest-volume segments commanding premium positioning through specialized certification burdens and extended supplier qualification timelines.
- Cargo Ships:Bulk carriers and container vessels drive standardized AH36 and DH36 consumption at scale, with Korean and Chinese yards optimizing plate nesting software to minimize remnant waste. Fleet renewal programs concentrate demand in 2024-2026 contracting windows.
- Military Ships:Naval surface combatants and submarines require ABS-certified ballistic grades with controlled through-thickness properties, locking procurement into sole-source or dual-source supply arrangements. NATO expansion programs are extending hull replacement schedules.
- Tankers:Crude and product carriers specify DH36 and EH36 for cargo temperature exposure, with IMO environmental regulations accelerating double-hull replacement demand. Greek and Norwegian owners dominate contracting.
- Fishing Vessels:Smaller hulls and ice-strengthened trawlers employ mixed grade specifications, with Nordic builders specializing in compact EH36 applications for North Atlantic operations.
Cargo ships lead absolute tonnage. Military end-use expands most quickly amid fleet modernization cycles.
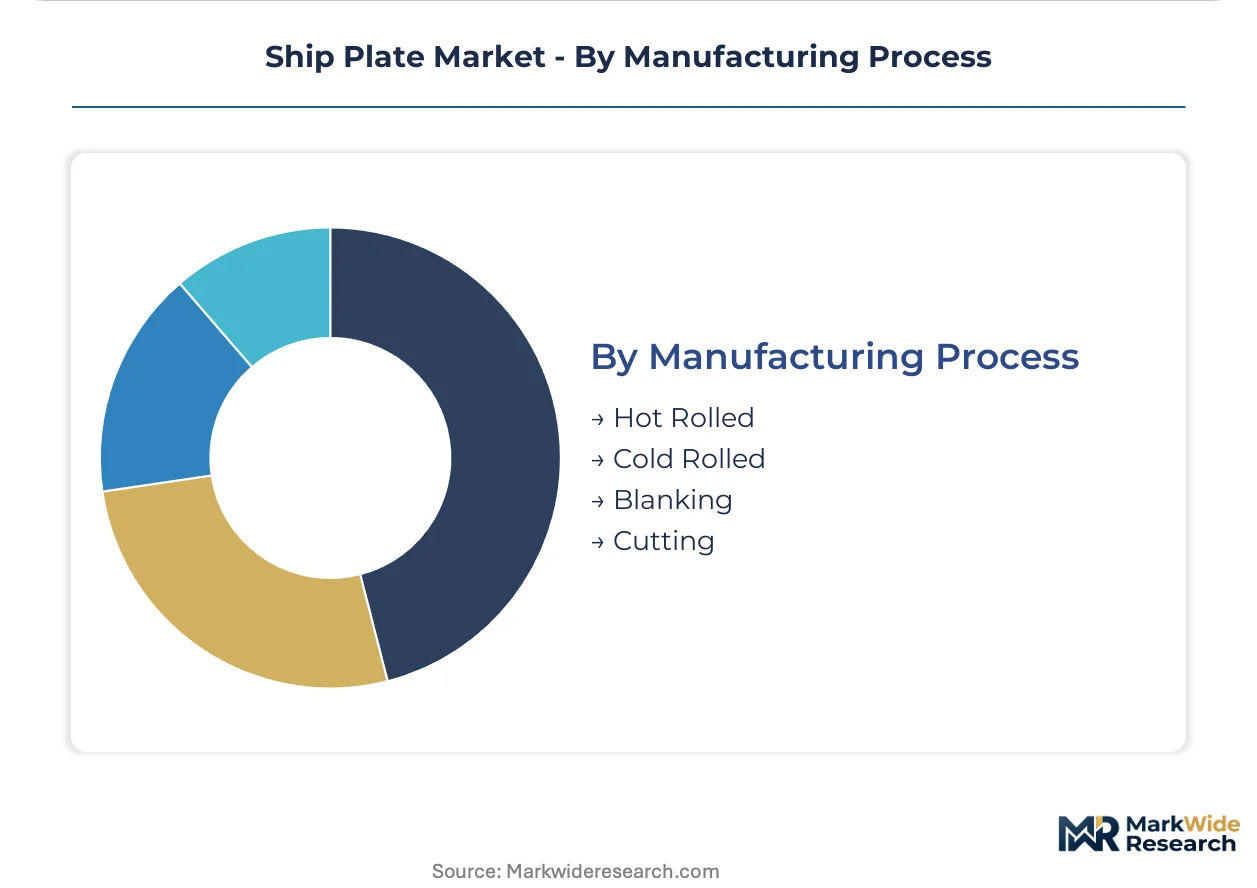
Manufacturing Process:
Process selection governs surface finish, dimensional tolerance, and downstream fabrication economics, with thermomechanical advances displacing legacy normalized rolling in premium segments.
- Hot Rolled:Conventional rolling above recrystallization temperature produces as-rolled surface finish suitable for submerged-arc welding in primary hull assembly. Integrated mills at Pohang and Fukuyama anchor output.
- Cold Rolled:Room-temperature reduction delivers tighter thickness tolerance and superior surface quality for visible superstructure applications where paint adhesion governs lifecycle maintenance.
- Blanking:Precision shearing of plate to nested hull panel shapes reduces yard cutting torch labor, with automated blanking lines installed at Japanese service centers supplying just-in-time to Osaka and Nagasaki yards.
- Cutting:Plasma and laser cutting of master plates into stiffener flanges and bracket details completes the fabrication chain, with Korean plate processors investing in high-definition plasma for complex edge preparations.
Hot rolled dominates tonnage. Blanking gains share fastest as yard automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian integrated steelworks while consumption spreads across shipbuilding clusters in South Korea, China, and Japan. European mills serve ice-class specifications for Baltic and North Sea routes. North American demand flows predominantly through naval procurement channels.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor plate consumption through dedicated supply contracts with POSCO and Hyundai Steel. The Ministry of Trade, Industry and Energy enforces KR classification society alignment with IACS harmonized rules. Busan-Ulsan shipbuilding clusters consume AH36 and EH36 grades in continuous campaigns for container ship and LNG carrier newbuilds.
China
State-owned yards at Dalian, Shanghai, and Guangzhou drive standardized bulk carrier construction requiring GB 712-certified plate. MIIT mandates domestic steel sourcing quotas for naval and commercial hull programs. Jiangsu province shipbuilding clusters source from Baosteel and Shougang mills under long-term offtake agreements with embedded price-adjustment clauses.
Japan
Imabari and Oshima Shipbuilding specify DH36 and EH36 grades for LNG-ready tanker newbuilds under Class NK supervision. METI enforces JIS G 3106 standards that govern mill certification and through-thickness toughness testing. Fukuyama and Kashima steelworks sustain premium-grade output through integrated blast furnace networks serving naval contractors.
Norway
Arctic-rated newbuilds for polar route LNG carriers demand EH36 and thermomechanically rolled ice-class specifications. The Norwegian Maritime Authority implements strict Environmental Product Declaration requirements ahead of EU ETS maritime extension deadlines. Stavanger and Bergen shipyards qualify plate suppliers based on carbon disclosure protocols and low-emission production methods.
United States
Naval Surface Warfare Center procurement locks suppliers into multi-year qualification cycles for ABS-certified ballistic grades. The Department of Defense sustains hull replacement schedules for destroyer and submarine programs through sole-source arrangements. Ingalls Shipbuilding at Pascagoula and Bath Iron Works in Maine concentrate demand for nickel-alloyed plate with controlled through-thickness properties.
Ship Plate Market Vendor Landscape
Capital-heavy integrated producers compete with specialized mini-mill operators across distinct specification tiers. The vendor base clusters around blast furnace-equipped mills with captive iron ore access and dedicated plate rolling capacity. Three archetypes dominate: Korean-Japanese integrated champions with naval certification depth, Chinese state-backed volume producers, and European specialists in thermomechanically rolled Arctic grades. Competitive moves center on backward integration into raw material security and five-year offtake contracting with major shipyards.
Among East Asian integrated producers, Nippon Steel and POSCO exemplify the certification-intensive archetype serving naval and premium commercial segments. JFE Steel occupies a position within the Japanese mill cluster supplying Class NK-certified grades. ArcelorMittal represents the European specialist tier with dominant ice-class certification holdings for polar route applications.
| Leading Market Players |
|---|
| Nippon Steel |
| Shougang Group |
| Baosteel Group |
| Tata Steel |
| Ansteel Group |
| POSCO |
| ArcelorMittal |
| SSAB |
| JFE Steel |
| Others |
Supply Flow & Price Mechanics
Thermomechanical rolling adoption is compressing alloy content requirements while concentrating premium-grade output among blast furnace-equipped mills with captive iron ore access, simultaneously lowering material cost structures and tightening supplier oligopoly. This production-method transition feeds directly into contract pricing power at Korean and Japanese integrated producers serving naval and ice-class segments.
Pricing Analysis
Margin tightening in EH36 and ABS-certified grades reflects extended mill-qualification timelines and limited dual-source availability for NATO naval programs. Three-tier pricing structure across premium ballistic-grade, standard high-strength, and economy commercial-grade levels stratifies procurement pools, with certification level and volume scale as primary differentiation drivers. Cost-down pressure on AH36 accelerates because Chinese state-backed mills are absorbing margin compression to secure fleet-renewal offtake. Greek and Norwegian tanker owners exhibit highest price sensitivity in spot procurement, while US Naval Surface Warfare Center contracts demonstrate lowest sensitivity due to sole-source security requirements.
Supply Chain Analysis
Domestic-content mandates from China's MIIT and Japan's METI are reshaping sourcing patterns, forcing foreign-owned yards to qualify local mills or absorb tariff exposure on imported plate. Supply concentrates in South Korea, China, and Japan, with integrated blast furnace networks at Pohang, Baosteel, and Fukuyama anchoring premium-grade output. Raw material dependencies draw from Australian iron ore, Brazilian pellet feed, and Indonesian nickel for alloy additions. Single-source vulnerability intensifies where ABS ballistic certification locks suppliers into multi-year qualification cycles with the US Navy. Distribution runs through mill-direct long-term offtake agreements displacing spot procurement at Hyundai Heavy Industries and Samsung Heavy Industries clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ship plate supply is consolidating around integrated producers with naval certification depth, as IMO carbon regulations and alloy-cost volatility force merchant-grade specialists toward exit or acquisition.
For Market Incumbents: Acquire captive iron ore port access and pelletizing capacity to secure blast furnace input cost stability against Australian mining output swings. Defensive consolidation moves center on locking five-year offtake agreements with Korean shipbuilders before Chinese state-backed mills undercut pricing, and investing in direct-quenched and tempered process certification for Arctic ice-class positioning against ArcelorMittal and POSCO. For New Entrants and Emerging Players: Blockchain-traceable mill certification systems offer a technology-first wedge into risk-averse European shipowner procurement committees ahead of EU ETS maritime extension deadlines. White-space targets concentrate on thermomechanically rolled EH36 for Baltic route fishing vessels and compact Arctic trawlers, where Nordic builders face limited qualified supplier alternatives. Go-to-market positioning should lead with Environmental Product Declaration compliance and Class NK verification protocols rather than price competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by East Asian integrated champions seeking naval certification depth or European ice-class specialization. Long-term viability favors mills with backward integration into raw material security and established KR or Class NK qualification pipelines. Acquisition target archetype: mid-cap Japanese or Korean plate specialists with dormant ABS certification that can be reactivated for NATO procurement expansion. The signal to watch is US Navy hull replacement schedule acceleration announced through Naval Sea Systems Command budgeting.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year offtake contracts with POSCO and Hyundai Steel lock in Korean yard demand visibility. |
| Backward Integration | Captive iron ore pelletizing at Pohang and Fukuyama insulates margins against Australian mining volatility. |
| Green Manufacturing Transition | Low-emission steel production methods qualify suppliers for EU ETS maritime extension and Norwegian EPD requirements. |
| Capacity Expansion | Dedicated EH36 and DQ&T plate mill investments serve Arctic ice-class certification gaps at Norwegian and Finnish yards. |
| Joint Venture | Classification society partnerships with Lloyd's Register and Class NK accelerate mill certification for polar route specifications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with shipyard procurement directors, steel mill technical sales leads, classification society surveyors, and naval program contracting officers. Secondary sources encompassed IACS harmonized rule publications, KR and Class NK certification databases, IMO EEXI compliance filings, and Korean Ministry of Trade customs export records. Bottom-up plate consumption estimates by grade and thickness band were cross-validated against top-down shipbuilding orderbook projections from commercial fleet renewal programs and NATO naval procurement schedules.
Data-stream reconciliation across mill output certifications, shipyard material requisitions, and classification society approval logs enabled segmentation modeling by material grade, thickness specification, end-use category, and manufacturing process. Analytical framework approach projected demand evolution across the analysis window through linked modeling of IMO regulatory compliance deadlines, fleet age profiles, and regional shipbuilding capacity utilization. CAGRs were derived from weighted regression of historical orderbook patterns against projected newbuild contracting intensity, with explicit incorporation of iron ore cost pass-through elasticities and welding technician availability constraints at Japanese and Korean yards.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting steel import tariffs, unscheduled naval program cancellations, and breakthroughs in aluminum or composite hull materials displacing steel specifications. Forecasts reflect documented assumptions regarding classification society rule harmonization progress and carbon accounting methodology convergence between EU ETS and IMO frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Breaking Market