
 Cargo Ship Repair and Maintenance Services Market | 2026-2036
Cargo Ship Repair and Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Ship Repair and Maintenance Services Market Insights
Class ABS-grade hull integrity standards is collapsing the gap between routine yard visits and major refit cycles, forcing owners to front-load structural investments. Mercury Ship Repairs leverages its Gulf of Mexico positioning to capture Jones Act vessel work. SHM Group anchors its portfolio on Southeast Asian dry-docking capacity. Chowgule Lavgan Ship Repair dominates India's west coast repair corridor.
Cargo ship repair and maintenance services encompass hull steel renewal, machinery overhaul, and coating preservation performed in graving docks, floating docks, or alongside berths, typically requiring steel plate thickness surveys and cathodic protection system verification to restore seaworthiness certificates. Engine overhaul commands premium labor rates due to specialist technician scarcity, while routine maintenance generates recurring revenue streams with lower margin volatility. Fabrication work absorbs fluctuating steel prices directly, compressing yard margins when alloy costs spike. Emergency repairs attract port-state control scrutiny under SOLAS compliance frameworks, elevating documentation burdens.
IMO's Ballast Water Management Convention and the International Convention for the Prevention of Pollution from Ships (MARPOL) Annex VI drive retrofit demand across oceangoing fleets, with port state control regimes in Singapore, Rotterdam, and Long Beach enforcing detention risks for non-compliant vessels. The EU Emissions Trading System extension to maritime transport from 2024 tightens operational expenditure calculations for European-flagged and European-trading cargo ships. Stakeholders must weigh scrubber retrofit obsolescence against alternative fuel engine conversions as regulatory pathways diverge.
Market Dynamics
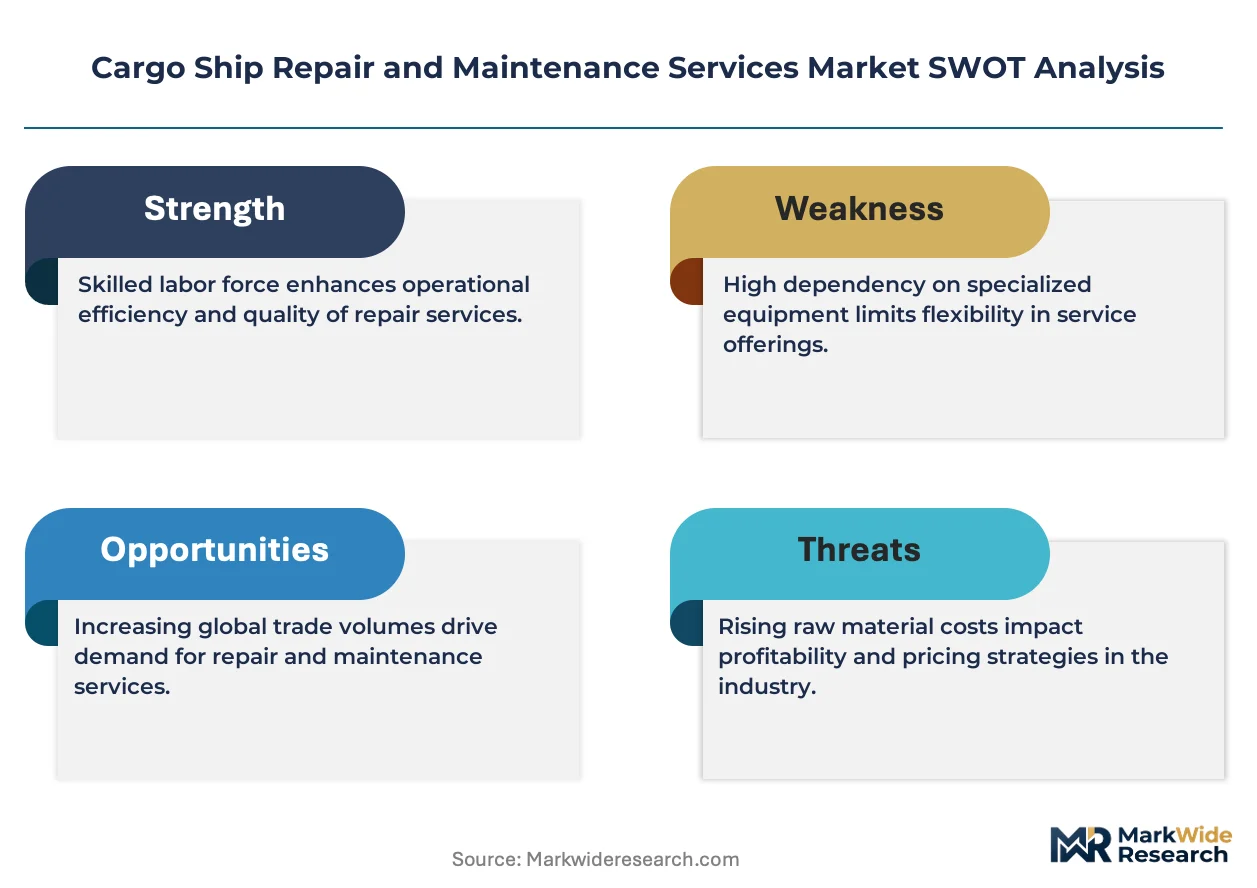
Stricter IMO environmental mandates are collapsing the traditional cycle between routine maintenance and major refits, forcing shipowners to front-load structural investments and compress yard scheduling windows.
Growth Catalysts
- Ballast Water Management Convention retrofit deadlines:Port state control regimes in Singapore, Rotterdam, and Long Beach enforce detention risks, compelling fleet-wide system installations.
- Scrubber installation demand:Owners of Panamax and Capesize bulk carriers invest in exhaust gas cleaning to comply with MARPOL Annex VI sulfur caps while extending vessel economic life.
- East Asian dry-dock clustering:Singapore, South Korea, and China's port cities concentrate specialized graving dock capacity, attracting cross-regional vessel positioning.
Market Restraints
- Specialist technician scarcity:Engine overhaul labor rates surge as marine diesel mechanic training pipelines fail to match fleet expansion.
- Steel price volatility:Fabrication work absorbs fluctuating alloy costs directly, compressing yard margins during nickel and manganese spikes.
- Alternative fuel conversion uncertainty:Scrubber retrofit obsolescence risk rises as ammonia and methanol pathway investments diverge.
Strategic Opportunities
- Indian west coast repair corridor:Underpenetrated dry-dock capacity at Goa and Mumbai offers cost arbitrage against East Asian yard congestion.
- EU Emissions Trading System maritime extension:European-flagged vessels face operational expenditure recalculation, creating demand for energy efficiency retrofit advisory.
- Digital hull monitoring convergence:Integration of ultrasonic thickness sensors with predictive analytics enables condition-based maintenance contracts.
Industry Challenges
- Cathodic protection certification complexity:SOLAS compliance documentation burdens escalate for emergency repairs attracting port-state control scrutiny.
- Graving dock capex intensity:New floating dock construction requires heavy capital deployment amid uncertain scrubber-to-alternative-fuel transition timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Ship Repair and Maintenance Services Market |
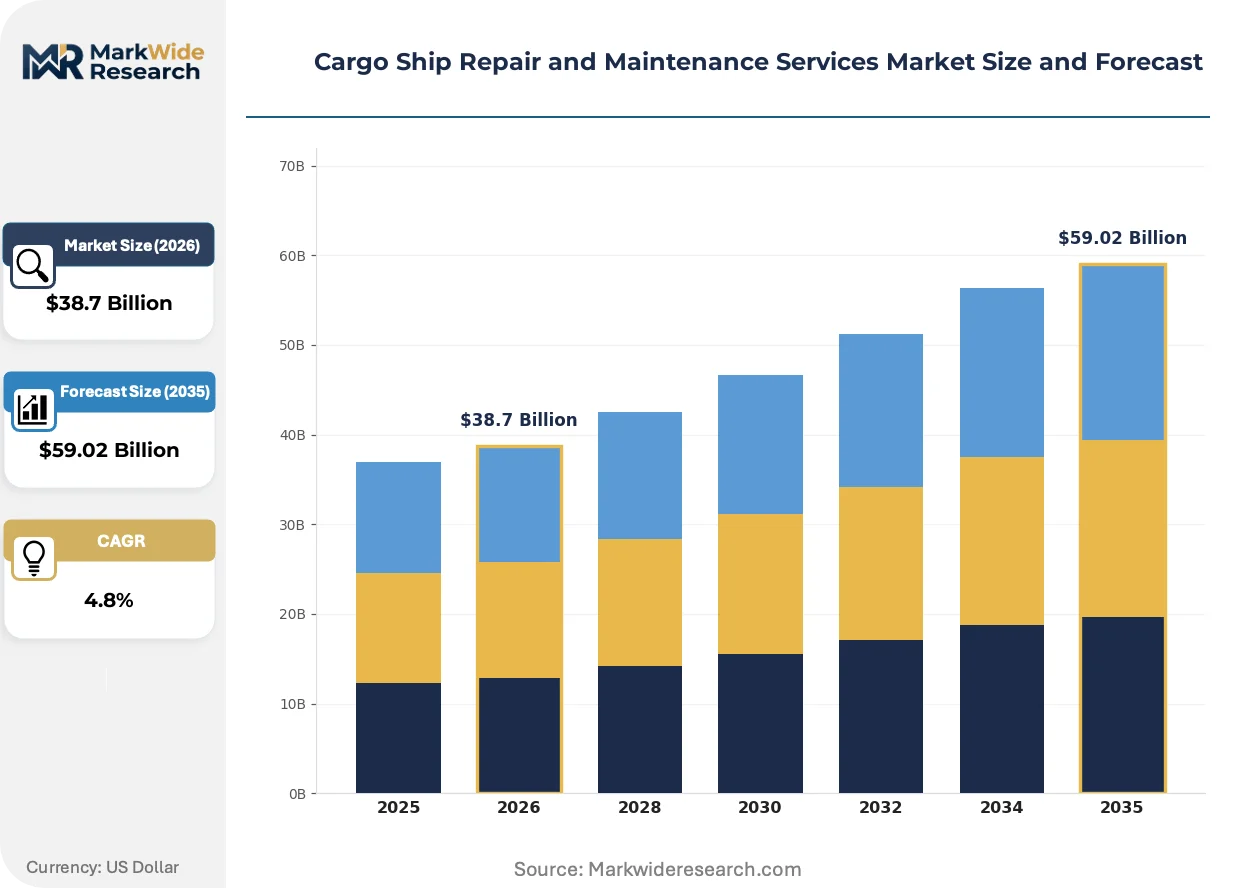
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dry Docking, Routine Maintenance, Emergency Repairs, Engine Overhaul Repair Method: Welding, Sandblasting, Coating, Fabrication End User: Shipping Companies, Freight Operators, Charters, Government Agencies Material Used: Steel, Aluminum, Composites, Marine Paints |
| Companies Covered | Mercury Ship Repairs, SHM Group, Chowgule Lavgan Ship Repair, Thakur Engineering and Maintenance Services, Skanda Maritime Engineering Co., Indo Marine, Nautai Marine Services and Trading, Varren Marines Shipping, Marine Outfitting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Ship Repair and Maintenance Services Market Trends and Innovations
Repair yard operations are digitizing inspection workflows and reconfiguring service portfolios around regulatory compliance rather than traditional mechanical overhaul.
Ultrasonic thickness monitoring systems now enable continuous hull integrity assessment without dry-docking interruption. Container shipping lines operating Singapore-flagged vessels deploy these sensors across Panamax fleets. The technology is miniaturizing sensor packages for retroactive installation on legacy hulls, compressing the inspection cycle from annual to real-time.
REACH restrictions on hexavalent chromium coatings are forcing European yards to adopt trivalent alternatives and ceramic-based hull protection. The industrial consequence extends coating application windows and requires retraining of spray technician workforces. German and Dutch repair facilities face the steepest compliance curves as their national regulators enforce ahead of EU harmonization deadlines.
Shipowners now unbundle after-sales service contracts from original equipment manufacturer tie-ins, seeking independent yard pricing for machinery overhaul. This procurement fragmentation disrupts Wärtsilä and MAN Energy Solutions service networks in the Mediterranean and Middle East. Greek and Cypriot-flagged bulk carriers lead this disaggregation, sourcing engine work to lowest-bid independent facilities.
Cargo Ship Repair and Maintenance Services Market Segmentation
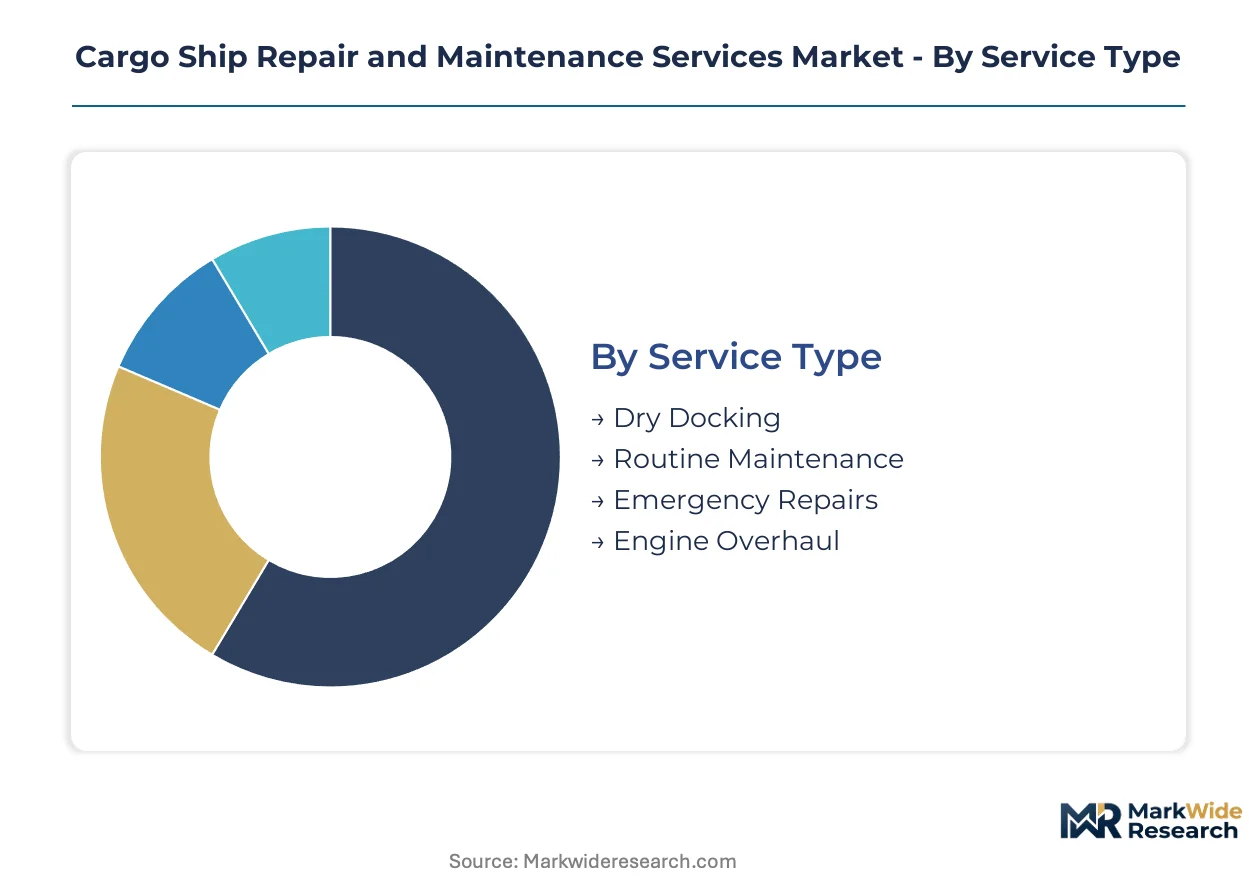
Cargo ship repair and maintenance services fragment across four distinct dimensions that reshape procurement patterns and margin capture. Service type and repair method determine capital intensity and labor specialization, while end-user concentration and material specifications drive geographic clustering and supply chain vulnerability.
Service Type:
Margin pools concentrate in scheduled interventions that require certified documentation and extended yard occupation.
- Dry Docking:Comprehensive hull inspection and steel renewal performed in graving docks or floating docks with ABS-grade certification requirements. Demand clusters around Singapore and South Korean yards where Panamax container fleets queue for simultaneous ballast water treatment and scrubber retrofit installations.
- Engine Overhaul:Complete disassembly and rebuild of marine diesel propulsion systems requiring specialist technicians with MAN Energy Solutions or Wärtsilä factory credentials. Labor rates surge 40% above routine work due to training pipeline shortages concentrated in Hamburg and Shanghai technician pools.
- Routine Maintenance:Scheduled steel preservation, machinery lubrication, and cathodic protection verification performed alongside berths without dry-docking interruption.
- Emergency Repairs:Unscheduled hull welding and machinery replacement triggered by port-state control detention risks or collision damage.
The dominant share belongs to Dry Docking, while Engine Overhaul is closing the gap fastest as sulfur regulation compliance extends vessel economic life calculations.
Repair Method:
Application context determines whether yards compete on speed, precision, or environmental compliance.
- Welding:Hull steel replacement and crack repair using certified procedures under SOLAS structural integrity standards. Greek and Cypriot-flagged bulk carriers source this work to independent Mediterranean facilities unbundled from OEM service networks.
- Sandblasting:Surface preparation for coating adhesion using automated blasting equipment that compresses turnaround times.
- Coating:Anti-corrosive and anti-fouling paint application now dominated by trivalent chromium alternatives as REACH restrictions phase out hexavalent formulations in Rotterdam and Hamburg yards.
- Fabrication:Custom steel component production absorbing direct nickel and manganese price volatility that compresses yard margins during alloy cost spikes.
Welding commands the largest volume share, though Coating is expanding most quickly amid regulatory substitution mandates.
End User:
Customer type structures payment terms, contract duration, and geographic flexibility in yard selection.
- Shipping Companies:Container lines and bulk operators with fleet-wide maintenance agreements leveraging Singapore-flagged vessel concentration for regional yard negotiations.
- Freight Operators:Third-party logistics providers chartering vessel capacity on short-term contracts with fragmented repair procurement.
- Charters:Voyage charterers and time charterers passing repair liability through hire clauses with minimal direct yard relationships.
- Government Agencies:Naval and coast guard fleets with security-cleared yard requirements and extended procurement cycles.
Shipping Companies retain the dominant procurement volume, while Government Agencies demonstrate the steepest contract value expansion as Jones Act vessel renewal accelerates.
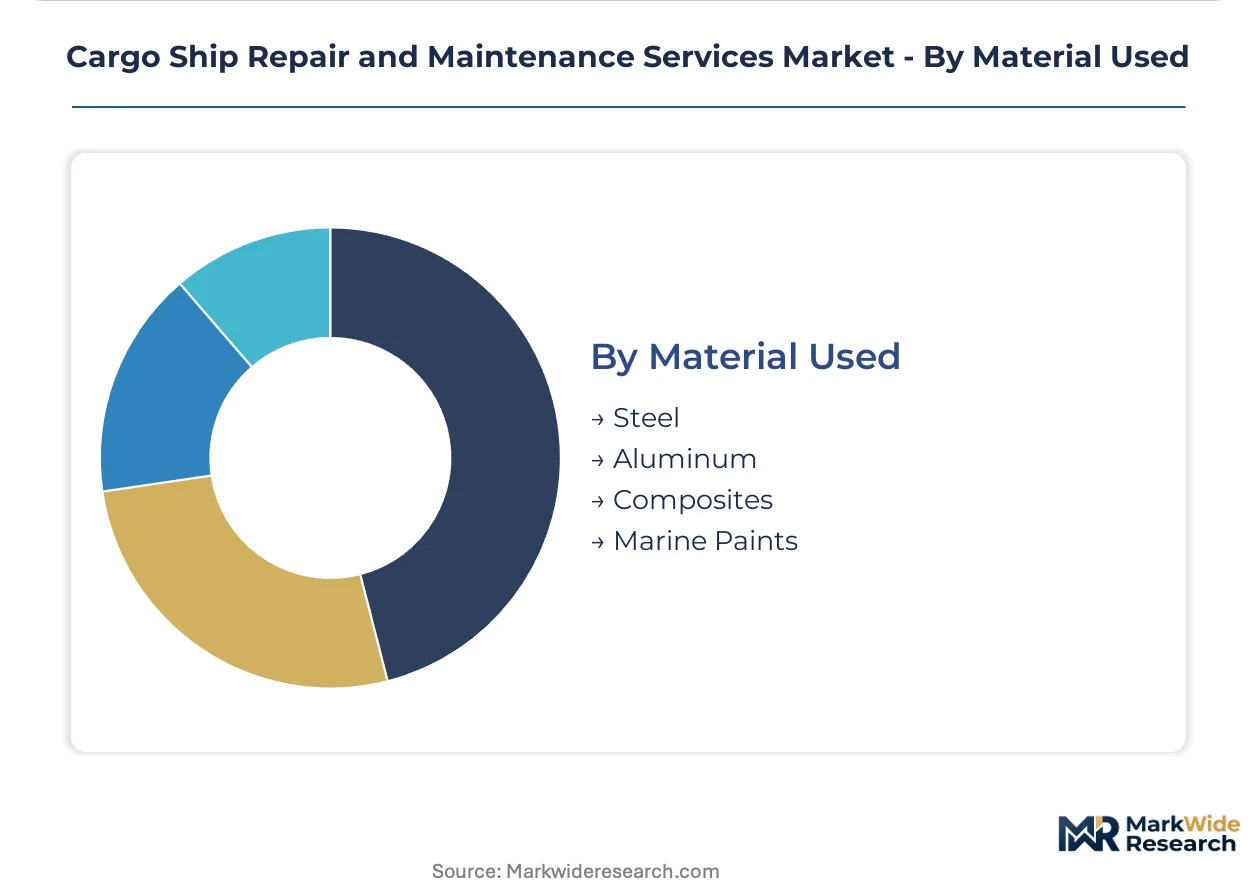
Material Used:
Supply concentration and price volatility differentiate margin stability across material categories.
- Steel:Primary hull renewal material with pricing tied to Shanghai Futures Exchange fluctuations that yards cannot hedge effectively.
- Aluminum:Superstructure and specialized component fabrication for high-speed cargo vessels with limited yard processing capability.
- Composites:Non-structural component replacement in accommodation modules and piping systems with nascent repair technician training.
- Marine Paints:Anti-fouling and anti-corrosive coatings representing 15-20% of dry-dock material expenditure with ceramic-based alternatives gaining share.
Steel dominates absolute consumption, while Marine Paints are gaining share fastest through regulatory-driven formulation turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean yards service container fleets transiting the transpacific route to Long Beach and Oakland. Singapore facilities capture scrubber retrofit work from European-flagged bulk carriers. Chinese graving docks absorb Panamax vessel overflow from congested East Asian queues.
Singapore
Port state control detention risks under MARPOL Annex VI drive ballast water system installations. The Maritime and Port Authority enforces compliance timelines that compress yard scheduling windows. Tuas shipyard cluster concentrates graving dock capacity for simultaneous hull renewal and exhaust gas cleaning retrofits.
South Korea
Hyundai Heavy and Samsung Heavy anchor fleet renewal programs for transpacific container lines. The Ministry of Oceans and Fisheries coordinates technician training pipelines to address marine diesel specialist scarcity. Busan-Ulsan industrial corridor hosts floating dock operations for Capesize bulk carrier engine overhauls.
China
Shanghai Futures Exchange steel price volatility absorbs yard margin compression during nickel spikes. The Ministry of Ecology and Environment implements MARPOL Annex VI sulfur enforcement at Ningbo-Zhoushan and Qingdao ports. Yangtze River Delta shipyards queue Panamax vessels diverted from Singapore dry-dock congestion.
United States
Jones Act vessel work concentrates repair demand for domestic cargo fleets. The Coast Guard enforces SOLAS structural integrity standards at Gulf of Mexico facilities. Houston-Galveston corridor captures emergency hull welding triggered by port-state control scrutiny.
India
Underpenetrated dry-dock capacity at Goa and Mumbai offers cost arbitrage against East Asian yard rates. The Directorate General of Shipping administers seaworthiness certification for emergency repairs. Chowgule Lavgan Ship Repair anchors the west coast repair corridor with graving dock operations serving Suez-route bulk carriers.
Cargo Ship Repair and Maintenance Services Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic positioning. The vendor base splits between scale-driven integrated yards and independent facilities unbundled from OEM service networks. Three archetypes dominate: Gulf of Mexico Jones Act specialists, Southeast Asian dry-dock cluster operators, and Indian west coast cost-arbitrage players. Capacity expansion and procurement fragmentation represent the dominant competitive vectors reshaping service relationships.
Within the regional specialist tier, Mercury Ship Repairs exemplifies Gulf of Mexico positioning for Jones Act vessel work. SHM Group and Chowgule Lavgan Ship Repair occupy complementary positions across Southeast Asian and Indian subcontinent dry-dock capacity. These three entities represent the geographic diversification strategy that shipowners employ to navigate yard congestion and regulatory compliance timelines across Singapore, South Korea, China, and India.
| Leading Market Players |
|---|
| Mercury Ship Repairs |
| SHM Group |
| Chowgule Lavgan Ship Repair |
| Thakur Engineering and Maintenance Services |
| Skanda Maritime Engineering Co. |
| Indo Marine |
| Nautai Marine Services and Trading |
| Varren Marines Shipping |
| Marine Outfitting |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between container shipping lines and Singapore dry-dock clusters lock in both steel plate supply access and labor rate visibility, insulating yards from Shanghai Futures Exchange volatility while committing owners to fixed pricing through IMO compliance retrofit cycles.
Pricing Analysis
Current-generation scrubber retrofit pricing diverges sharply from legacy hull renewal rates and emerging ammonia-ready conversion quotes. Three-tier pricing structure across ABS-grade certification, routine maintenance, and emergency repair tiers reflects specialist technician scarcity and SOLAS documentation burdens. Cost compression in routine maintenance is intensifying because shipowners unbundle OEM service contracts and source to independent Mediterranean facilities. Freight operators demonstrate highest price sensitivity due to fragmented procurement and short-term charter liability structures, while government agencies accept premium rates for security-cleared yard access.
Supply Chain Analysis
Inbound logistics costs through the Strait of Malacca and container availability at Busan-Ulsan corridors shape steel plate delivery timelines to graving dock facilities. Supply concentrates in China, South Korea, and Japan for specialist marine diesel components and high-grade hull steel. Raw material dependencies rest on nickel and manganese alloys for cathodic protection systems, trivalent chromium formulations for REACH-compliant coatings, and certified welding consumables. Single-source vulnerability persists for MAN Energy Solutions and Wärtsilä factory-credentialed technician pools. Distribution runs through shipping company fleet maintenance agreements and spot procurement at port-state control detention points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against alternative fuel vessel obsolescence, as ammonia and methanol pathway investments threaten scrubber retrofit demand and compress residual value for conventionally powered tonnage.
For Market Incumbents: Fortify technician training pipelines in Hamburg and Shanghai to defend against marine diesel specialist scarcity, while securing backward integration into cathodic protection system manufacturing to capture margin from alloy price spikes. Anchor capacity reservation contracts with Singapore-flagged container lines to lock in yard utilization through regulatory compliance cycles. For New Entrants and Emerging Players: Differentiate on digital hull monitoring integration, offering condition-based maintenance contracts that compress inspection cycles from annual to real-time. Target the Indian west coast repair corridor at Goa and Mumbai for cost arbitrage against East Asian yard congestion, leveraging underpenetrated dry-dock capacity and Suez-route bulk carrier positioning. For Investors and Strategic Acquirers: Capital is best deployed toward independent facilities unbundled from OEM service networks, particularly those with EU ETS maritime advisory capabilities and floating dock flexibility for alternative fuel conversion timing. Monitor divergent regulatory pathway commitments between scrubber retrofit and ammonia-ready engine conversion as the inflection signal for asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Pipeline Expansion | Addresses marine diesel specialist scarcity concentrated in Hamburg and Shanghai credentialing pools. |
| Digital Hull Monitoring Integration | Enables condition-based maintenance contracts compressing inspection cycles for Panamax fleets. |
| Backward Integration into Coatings | Captures margin from REACH-driven trivalent chromium substitution and ceramic-based formulation turnover. |
| Floating Dock Capacity Addition | Provides flexibility for uncertain scrubber-to-alternative-fuel transition timing in East Asian clusters. |
| EU ETS Advisory Service Launch | Creates revenue from European-flagged vessel operational expenditure recalculation requirements. |
Research Methodology
Desk research of Lloyd's Register classification databases, IMO convention implementation schedules, and port-state control detention records preceded structured interviews with dry-dock operations managers, marine diesel technician training directors, shipping company fleet maintenance executives, and coating formulation specialists. Secondary validation drew from Maritime and Port Authority compliance bulletins, ABS hull integrity standards documentation, and Shanghai Futures Exchange steel pricing archives. Bottom-up yard capacity utilization estimates triangulated against top-down fleet renewal program announcements.
Variance decomposition across service type, repair method, end-user concentration, and material specification dimensions shaped analytical framework construction throughout the projection horizon. CAGRs derived from segmented demand modeling incorporating ballast water treatment retrofit deadlines, sulfur cap enforcement timelines, and alternative fuel conversion investment curves. Forecast inputs included graving dock queue lengths at Singapore and South Korean facilities, plus technician pipeline graduation rates from Hamburg and Shanghai credentialing programs.
Material uncertainties — divergent regulatory pathway adoption between scrubber retrofit and ammonia-ready conversion, plus extreme steel price volatility events — sit outside the modeled envelope. Forecasts reflect assumptions regarding IMO enforcement consistency and container fleet renewal program continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
United States Offshore Support Vessels Market