
 Ship Stabilizers Market | 2026-2036
Ship Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Stabilizers Market Insights
Multi-source procurement of fin actuators and gyroscopic rotors is expanding as shipyards diversify supplier bases beyond traditional single-source contracts. Kongsberg Maritime leverages its integrated vessel control platform to bundle stabilizers with dynamic positioning systems. Seakeeper sustains dominance in the recreational yacht segment through compact vacuum-sealed gyro units. Naiad Dynamics anchors the commercial workboat sector with hydraulically actuated fin systems engineered for harsh sea states.
Ship stabilizers are mechanical or gyroscopic devices that reduce vessel roll motion through hydrodynamic force generation or angular momentum exchange, typically achieving 70-90% roll reduction in operational sea states. Their primary purpose is to improve crew safety, fuel efficiency, and equipment functionality across maritime platforms. Gyroscopic stabilizers command premium positioning in the luxury yacht and military ship segments where space constraints and zero-speed performance justify higher unit costs. Active fin stabilizers retain volume leadership in commercial vessels and retrofit installations where hull form compatibility and maintenance accessibility drive selection. Passive bilge keel systems occupy the economy tier of fishing boats and coastal cargo carriers with minimal capital outlay requirements.
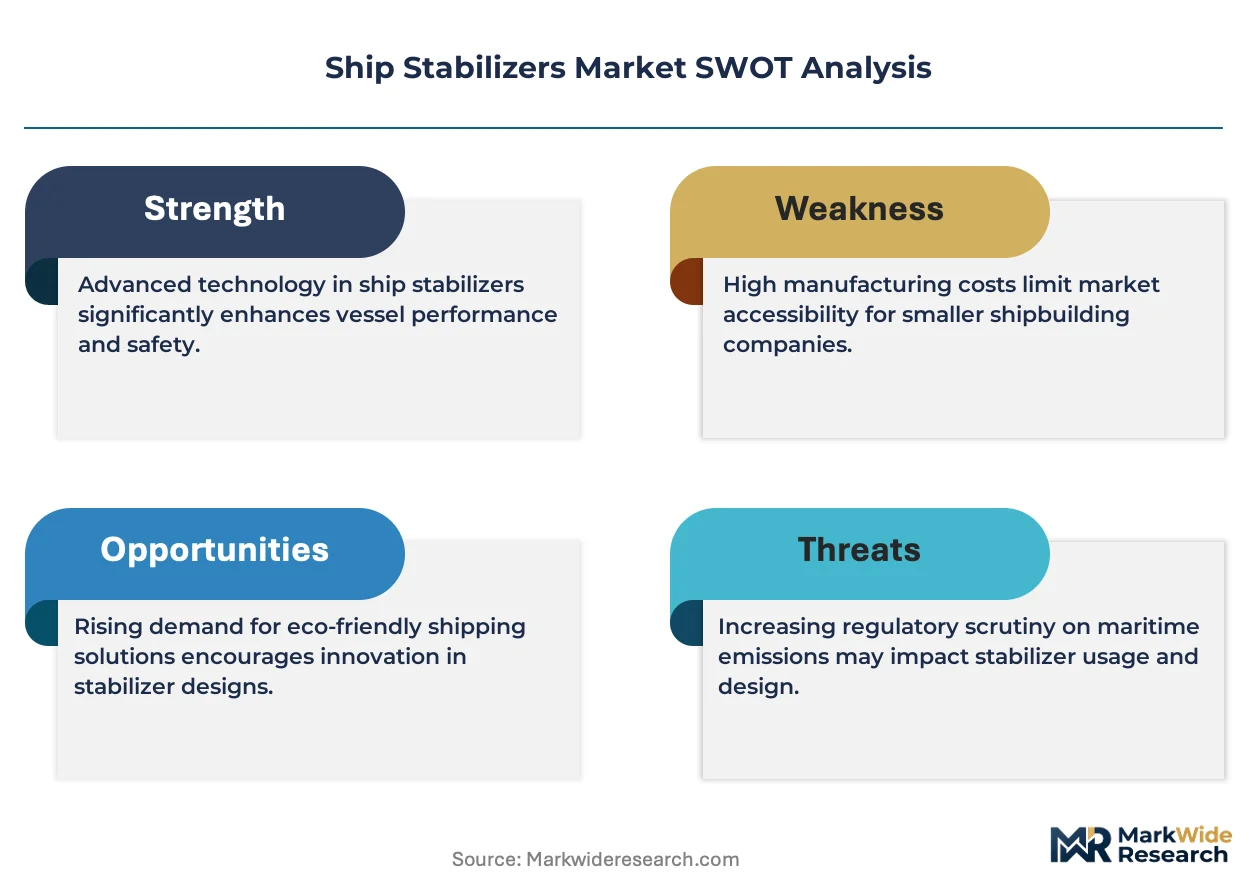
IMO's Energy Efficiency Existing Ship Index compels shipping companies to evaluate stabilizer retrofits as part of hull and machinery optimization programs. Classification societies including Lloyd's Register and DNV specify structural integration standards for active fin housings and gyro foundation loads in newbuild specifications. The US Coast Guard enforces stability criteria under 46 CFR that influence stabilizer sizing for passenger vessels operating in domestic routes. Stakeholders must monitor evolving cybersecurity mandates for digitally controlled stabilizer systems as maritime autonomy protocols extend to ride control functions.
Market Dynamics
IMO's Energy Efficiency Existing Ship Index is forcing shipping operators to retrofit active stabilization systems as part of hull optimization programs, compressing replacement cycles and expanding the aftermarket beyond newbuild demand.
Growth Catalysts
- Energy Efficiency Mandates:IMO regulations compel fleet operators to install active stabilizers that reduce fuel consumption through optimized hull performance in rough seas.
- Naval Modernization Programs:NATO member states are procuring integrated stabilization systems for next-generation combat vessels requiring zero-speed stabilization capabilities.
- Luxury Yacht Specification:South Korean shipyards around Ulsan and Geoje now specify gyroscopic stabilizers as standard fitment on superyacht and offshore support vessel contracts.
Market Restraints
- Specialized Component Scarcity:Precision-machined fin actuators and vacuum-sealed gyroscopic rotors depend on a concentrated supplier base in Germany and Japan.
- Structural Retrofit Costs:Active fin housing integration requires dry-dock hull modification exceeding the capital allocation thresholds of smaller ferry operators.
- Technical Performance Trade-offs:Passive bilge keel systems remain the default for fishing fleets where capital constraints override roll reduction performance requirements.
Strategic Opportunities
- Autonomous Vessel Integration:Digitally controlled stabilizer systems are converging with maritime autonomy protocols to enable ride control without crew intervention.
- Coastal Cargo Electrification:Battery-electric short-sea shipping routes in Norway and Denmark create demand for lightweight gyroscopic units that preserve payload capacity.
- Classification Society Certification:Lloyd's Register and DNV structural integration standards are creating preferred vendor status for early-compliant stabilizer manufacturers.
Industry Challenges
- Marine Hydrodynamics Talent Gap:Naval architects with specialized expertise in seakeeping analysis and stabilizer control algorithm development command premium compensation.
- Legacy System Interoperability:Retrofit installations must integrate with existing vessel management software through proprietary API protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Stabilizers Market |
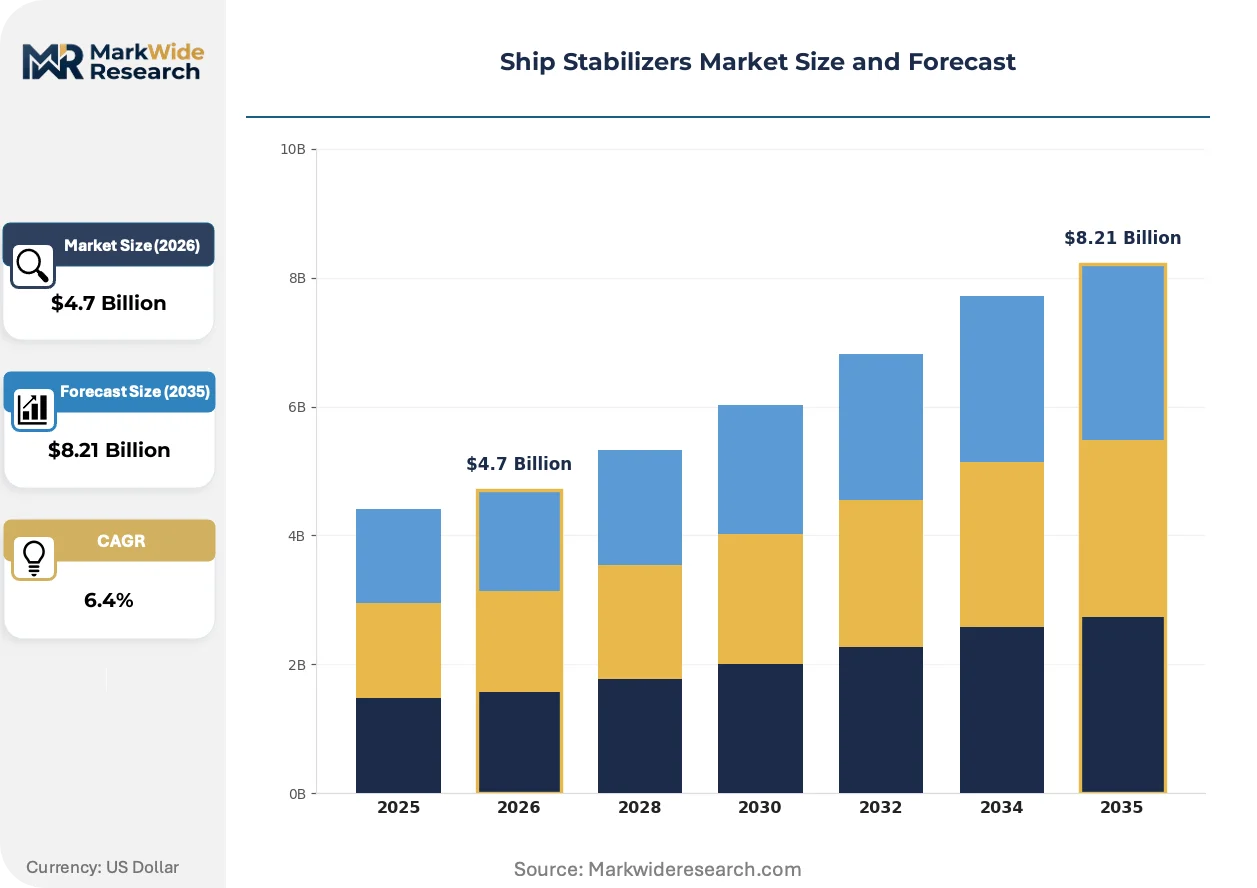
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Stabilizers, Passive Stabilizers, Gyroscopic Stabilizers, Bilge Keel Stabilizers Installation Type: Retrofit, Standard, Custom, Integrated Application: Commercial Vessels, Luxury Yachts, Fishing Boats, Military Ships End User: Shipbuilders, Shipping Companies, Government Agencies, Marine Research Institutes |
| Companies Covered | Naiad Dynamics, Kongsberg Maritime, Seakeeper, CMC Marine, VEEM Gyros, SKF Group, Quantum Marine Stabilizers, Quick, Fincantieri S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Stabilizers Market Trends and Innovations
Digital twin technology is reshaping how stabilizer performance is validated before sea trials, compressing development timelines and reducing physical prototype requirements across naval and commercial programs.
Predictive maintenance algorithms are integrating with sensor-equipped fin actuators to enable condition-based servicing rather than calendar-driven overhaul schedules. Cruise operators and offshore vessel owners are adopting these systems fastest, driven by charter penalty clauses for equipment downtime. The technology is integrating vessel control platforms with shore-based diagnostic centers, enabling remote troubleshooting that reduces technician dispatch costs.
DNV's updated rules for classification of dynamically positioned vessels now mandate redundancy in stabilization systems for operations in harsh environments. Shipyards in Norway and Finland are redesigning superstructure layouts to accommodate dual gyroscopic units. Arctic expedition cruise operators are responding by specifying redundant configurations that maintain passenger comfort standards during ice navigation.
Charter fleet operators are unbundling stabilizer maintenance from original equipment supplier contracts, creating independent service provider networks in Mediterranean and Caribbean yachting hubs. Third-party technical managers in Palma de Mallorca and Fort Lauderdale are building captive gyroscopic rotor balancing capabilities. This shift is most visible in the 40-80 meter yacht segment where owners prioritize cost transparency over single-source warranty coverage.
Ship Stabilizers Market Segmentation
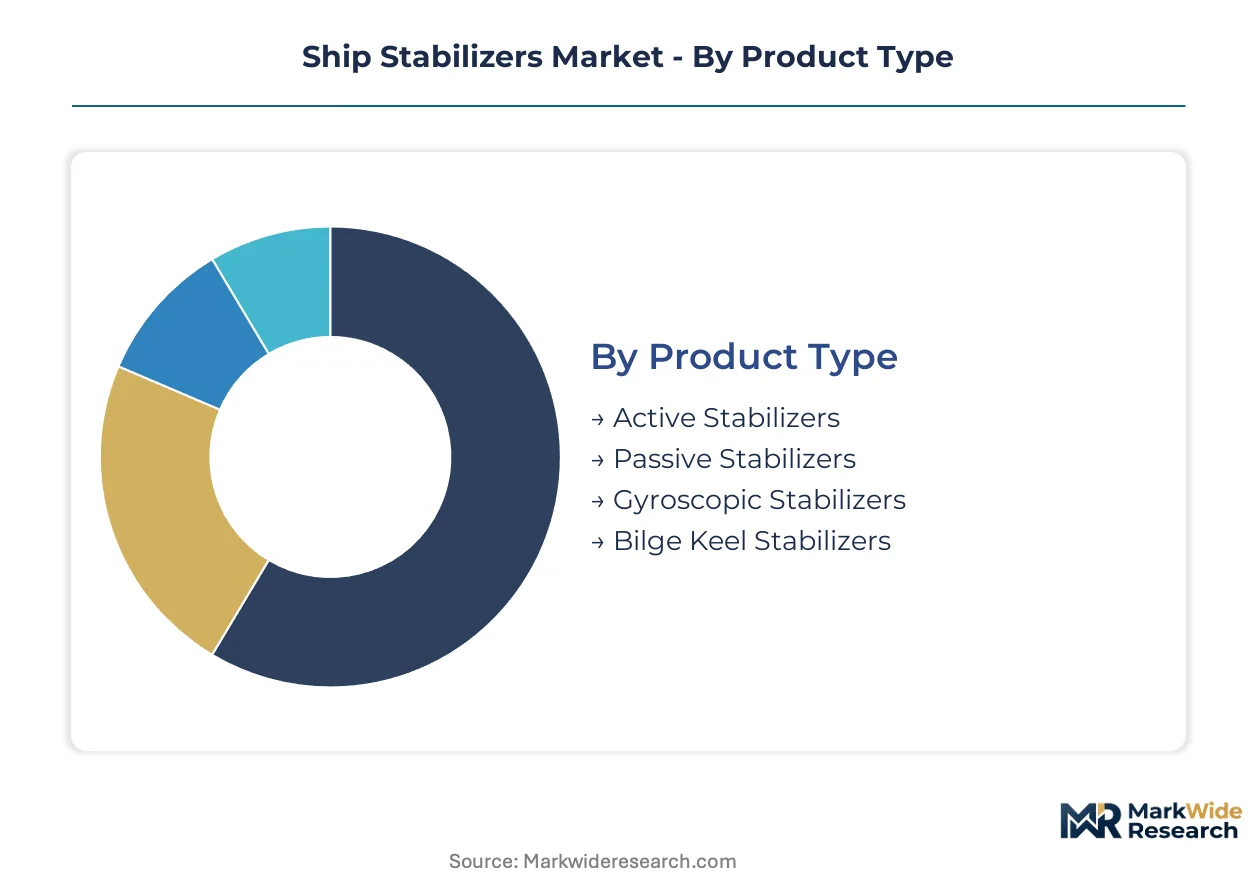
Segmentation in the Ship Stabilizers Market reveals how capital allocation, vessel specifications, and regulatory compliance reshape procurement patterns across maritime platforms. Understanding these divisions exposes where technology premiums concentrate and where standardization drives volume.
Product Type:
Capital intensity varies sharply across stabilization technologies, with gyroscopic systems demanding precision manufacturing infrastructure and vacuum-sealing capabilities that passive alternatives bypass entirely.
- Active Stabilizers:Hydraulically actuated fin systems generate real-time counter-forces through sensor-fed control loops. Commercial ferry operators in Norway and Denmark specify these units to meet IMO energy efficiency mandates while maintaining passenger comfort standards in North Sea routes.
- Gyroscopic Stabilizers:Vacuum-sealed spinning rotors exchange angular momentum to dampen roll without hull penetration. South Korean shipyards at Ulsan and Geoje specify these as standard fitment on superyacht contracts where zero-speed stabilization justifies premium positioning.
- Passive Stabilizers:Fixed hull appendages rely on hydrodynamic resistance without powered actuation.
- Bilge Keel Stabilizers:Welded steel fins along the turn of bilge provide economy-tier roll reduction.
Most installed capacity flows through Active Stabilizers. Expansion is steepest in Gyroscopic Stabilizers.
Installation Type:
Retrofit complexity and yard scheduling constraints fragment demand between newbuild specification and aftermarket hull modification programs.
- Retrofit:Dry-dock hull cutting and structural reinforcement accommodate fin housing integration on existing vessels. Greek and Turkish ferry operators pursue these installations to extend fleet service life under tightening EU emissions regulations.
- Standard:Catalog-configured stabilizer packages ship with predictable lead times and documented classification society approval.
- Custom:Tailored actuator sizing and control algorithm tuning match unconventional hull forms.
- Integrated:Stabilization systems bundled with dynamic positioning and vessel management platforms reduce interface engineering.
Standard configurations dominate current order books. Integrated packages are climbing the fastest as shipyards consolidate supplier relationships.
Application:
Vessel operating profiles determine whether stabilization serves passenger comfort, crew safety, weapons platform stability, or fuel optimization objectives.
- Commercial Vessels:Roll reduction systems on container ships and cruise liners cut fuel consumption by maintaining optimal hull attitude in seaways. Operators on Asia-Europe routes retrofit active fins to comply with IMO's Energy Efficiency Existing Ship Index.
- Military Ships:Zero-speed stabilization enables helicopter operations and weapons firing accuracy in high sea states. NATO procurement programs specify redundant gyroscopic configurations for next-generation combatants.
- Luxury Yachts:Owner expectations for onboard amenity performance drive specification of compact gyro units.
- Fishing Boats:Capital constraints limit adoption to passive bilge keels on coastal trawlers.
Commercial Vessels absorb the largest share of installation volume. Military Ships show the steepest expansion trajectory as naval modernization accelerates.
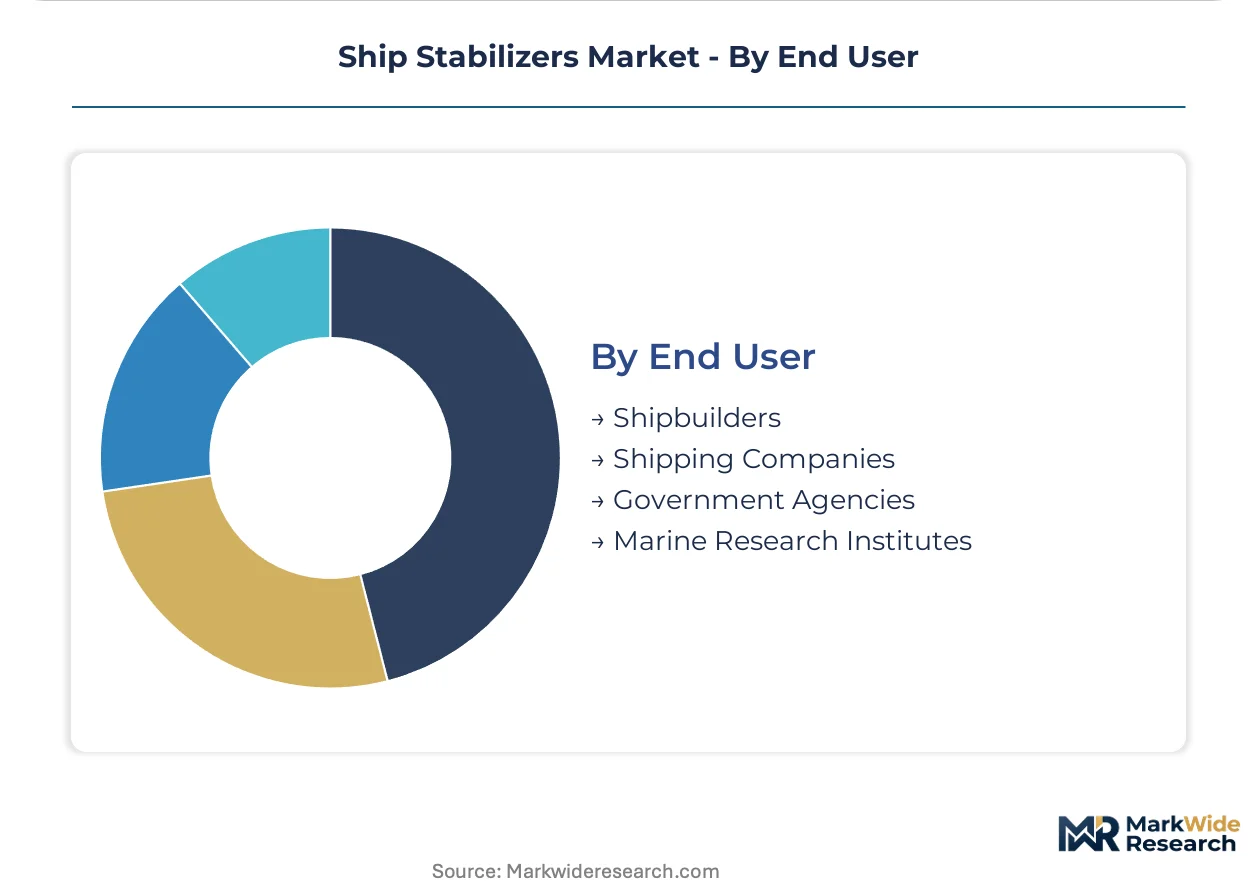
End User:
Procurement authority and technical specification control sit differently with builders, operators, government buyers, and research institutions.
- Shipbuilders:Newbuild specification power concentrates at South Korean yards and Northern European specialists who set stabilization standards for entire vessel series. Ulsan and Geoje clusters negotiate multi-unit gyro contracts that shape supplier pricing.
- Shipping Companies:Fleet retrofit decisions respond to charterer requirements and regulatory compliance deadlines. Mediterranean cruise operators lead adoption of predictive maintenance-enabled stabilizer systems.
- Government Agencies:Naval procurement offices mandate integrated stabilization for combatant hulls.
- Marine Research Institutes:Scientific vessel operators prioritize minimal acoustic signature and precise station-keeping.
Shipbuilders control the largest channel for new capacity. Shipping Companies are gaining specification influence fastest as retrofit cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan and Geoje anchor global ship stabilizer procurement, with South Korean shipyards specifying gyroscopic units as standard fitment on superyacht and offshore support vessel contracts. Naval modernization programs and commercial fleet retrofits are redistributing demand across maritime manufacturing clusters worldwide.
South Korea
DSME and Hyundai Heavy Industries drive specification authority for integrated stabilization systems on LNG carriers and naval combatants. The country's national industrial regulator enforces structural integration standards through Korean Register classification rules. The Ulsan-Geoje corridor concentrates gyroscopic unit procurement, with shipyards negotiating multi-year supply contracts that shape global pricing benchmarks.
Norway
Battery-electric short-sea shipping routes generate demand for lightweight gyroscopic units that preserve payload capacity on coastal cargo vessels. The Norwegian Maritime Authority implements strict stability criteria for passenger vessels operating in North Sea conditions. Bergen and Stavanger host specialist integrators bundling stabilizers with dynamic positioning systems for offshore support fleets.
United States
Coast Guard stability enforcement under 46 CFR influences stabilizer sizing for domestic passenger routes and Great Lakes operators. The US Navy's next-generation combatant programs specify redundant gyroscopic configurations for zero-speed helicopter operations. Gulf Coast shipyards in Louisiana and Texas retrofit active fin systems on existing offshore supply vessels to extend service life.
Germany
Precision-machined fin actuator manufacturing concentrates in Bavarian and Baden-Württemberg industrial zones, supplying shipyards across Northern Europe. Germanischer Lloyd classification standards shape structural housing specifications for active stabilization retrofits. Hamburg and Bremen harbor districts host technical service providers maintaining gyroscopic rotor balancing capabilities for Mediterranean charter fleets.
Japan
Commercial ferry operators retrofit active stabilizers to comply with IMO energy efficiency mandates on aging hulls serving domestic island routes. The country's maritime classification society, Nippon Kaiji Kyokai, updates seakeeping performance standards that influence newbuild specifications. Osaka-Kobe shipbuilding clusters integrate stabilizer procurement with LNG-fueled vessel construction programs.
Ship Stabilizers Market Competitive Landscape
Global majors compete with regional champions across technology integration and aftermarket service networks. The vendor base organizes around three tiers: diversified maritime systems conglomerates with integrated vessel control platforms; specialist gyroscopic manufacturers with vacuum-sealing capabilities; and hydraulics-focused fin actuator suppliers serving commercial workboat segments. Competitive positioning depends on classification society pre-approval, dry-dock service network density, and bundling relationships with dynamic positioning providers. M&A activity targets predictive maintenance software capabilities, while capacity expansion concentrates in South Korean and Northern European shipbuilding corridors.
Within the diversified systems tier, Kongsberg Maritime exemplifies platform-level integration strategies, while Seakeeper occupies a position defining compact gyroscopic architectures for recreational applications. Naiad Dynamics anchors the hydraulically actuated fin segment with commercial workboat specialization. These three represent distinct archetypes: control-system bundlers, precision gyroscopic specialists, and ruggedized fin system engineers.
| Leading Market Players |
|---|
| Naiad Dynamics |
| Kongsberg Maritime |
| Seakeeper |
| CMC Marine |
| VEEM Gyros |
| SKF Group |
| Quantum Marine Stabilizers |
| Quick |
| Fincantieri S.p.A. |
| Others |
Pricing and Supply Chain Analysis
IMO's Energy Efficiency Existing Ship Index is compelling fleet operators to specify active stabilization systems as standard fitment, forcing suppliers to scale precision-machined component output and compressing margins on catalog-configured units.
Pricing Analysis
Input-cost pass-through from specialized steel alloys and precision bearings drives pricing stratification across three performance tiers. Certification grade from Lloyd's Register or DNV commands substantial premiums over uncertified alternatives, while volume-scale contracts at South Korean shipyards extract double-digit discounts from actuator manufacturers. Pricing pressure stems from charter fleet operators unbundling maintenance contracts and demanding parts-only sourcing. Commercial ferry operators in the Mediterranean exhibit highest price sensitivity, whereas naval procurement offices prioritize zero-speed performance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Bavaria and Baden-Württemberg limit expansion of precision-machined fin actuator capacity, while vacuum-sealing technician shortages around Osaka-Kobe constrain gyroscopic rotor output. Manufacturing draws from German and Japanese industrial clusters, with secondary assembly in South Korea. Critical inputs include marine-grade aluminum forgings, high-tensile steel castings, and proprietary hydraulic fluid formulations. Single-source vulnerability concentrates in vacuum-sealed gyro bearing production. Distribution runs through shipyard-integrated procurement offices and specialized marine equipment distributors serving retrofit yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as zero-speed stabilization becomes mandatory specification on superyacht and naval contracts, displacing price-competitive passive alternatives.
For Market Incumbents: Cement classification society pre-approval advantages by accelerating DNV and Lloyd's Register certification for next-generation integrated control platforms. Threat from digitally-native autonomy specialists demands defensive patent filing in predictive maintenance algorithms. Backward integration into precision bearing manufacturing secures component supply against German and Japanese supplier concentration. For New Entrants and Emerging Players: Begin with predictive maintenance software layers that unbundle from hardware-specific OEM contracts, targeting Mediterranean and Caribbean charter fleet operators in Palma de Mallorca and Fort Lauderdale. Coastal cargo electrification in Norway offers the most penetrable wedge, with lightweight gyroscopic units specified for battery-electric short-sea routes. Go-to-market through technical service partnerships with existing dynamic positioning integrators. For Investors and Strategic Acquirers: Asymmetric upside sits with specialist gyroscopic manufacturers possessing vacuum-sealing capabilities and established shipyard relationships at Ulsan and Geoje. Long-term viability hinges on naval modernization program continuity and IMO regulatory enforcement stringency. Acquisition targets should demonstrate Lloyd's Register or DNV pre-approval status and captive service network density. Watch for inflection in NATO combatant procurement announcements as demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Pre-Approval Investment | DNV and Lloyd's Register certification creates preferred vendor status for shipyard specification teams. |
| Predictive Maintenance Software Development | Condition-based servicing algorithms reduce charter penalty exposure for cruise and offshore operators. |
| Backward Integration into Precision Bearings | In-house production of vacuum-sealed gyro components mitigates single-source supplier risk. |
| Autonomous Vessel Control Integration | Maritime autonomy protocol convergence enables ride control without crew intervention. |
| Service Network Expansion in Yachting Hubs | Third-party technical capabilities in Palma de Mallorca and Fort Lauderdale capture unbundled maintenance demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with naval architects, shipyard procurement directors, stabilizer system engineers, and aftermarket service managers with secondary validation through Lloyd's Register classification databases, DNV technical rule filings, IMO regulatory circulars, and customs trade records for marine equipment. Bottom-up vessel order book analysis triangulated against top-down fleet retrofit projections.
Comparable-period anchoring established baseline stabilization system penetration rates across commercial, naval, and recreational vessel categories before projecting forward across the analysis window. Segmentation dimensions modeled include product type, installation configuration, vessel application, and end-user procurement authority, with CAGRs derived from regression analysis of historical specification trends and forward-looking order pipeline visibility. Industry-specific inputs incorporated naval modernization program announcements and IMO energy efficiency compliance deadlines.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to cybersecurity mandates for digitally controlled systems, abrupt shifts in NATO defense procurement priorities, and commodity price volatility in marine-grade aluminum and high-tensile steel. Forecasts reflect assumptions about continued enforcement of IMO's Energy Efficiency Existing Ship Index and sustained shipbuilding activity at South Korean yards. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Plate Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Reefer Container Market