
 North America MUV Rental Market | 2026-2036
North America MUV Rental Market Size, Share, and Industry Trends Forecast 2026-2036
North America MUV Rental Market Insights
Premium-grade MUV specifications is bifurcating the competitive landscape. Enterprise Holdings, Inc. leverages its neighborhood network density to sustain fleet turnover advantages. Avis Budget Group, Inc. anchors corporate account relationships through long-term contract structures. Hertz Global Holdings, Inc. differentiates via technology leadership in digital fleet management platforms.
A multi-use vehicle rental supplies sport utility vehicles, minivans, pickups, and crossovers on temporary contractual terms, typically featuring seating capacity of seven to eight passengers and towing capability exceeding 3,500 pounds for commercial and leisure transport. The vehicle type dimension shows SUVs and crossovers capturing the dominant margin pool as family and business segments prioritize fuel efficiency against payload flexibility. Rental duration patterns reveal short-term and weekly categories as the fastest-growing structural segments, driven by event-based tourism and project-specific corporate mobility needs.
The EPA, NHTSA, and state-level zero-emission vehicle mandates in California and New York shape fleet composition requirements and capital deployment timelines for rental operators. The Department of Transportation's safety recall protocols and insurance rate structures further constrain vehicle sourcing flexibility across the region. Stakeholders must monitor evolving state-level emissions thresholds and charging infrastructure density to align electrification roadmaps with utilization economics.
Market Dynamics
Corporate fleet managers across the United States and Canada are systematically substituting capital-intensive vehicle ownership with flexible rental structures, compressing traditional asset-heavy business models into utilization-based service relationships.
Growth Catalysts
- EPA Emissions Standards:The EPA's tightened light-duty truck regulations accelerate fleet turnover toward cleaner MUVs, forcing rental operators to refresh inventories with compliant vehicles faster than ownership models permit.
- Suburban Infrastructure Expansion:Texas and Florida sustain the highest utilization rates through sprawling metropolitan development and tourism corridors that demand versatile passenger and cargo capacity.
- Telematics Integration:Real-time fleet tracking and predictive maintenance systems reduce downtime costs and enable dynamic pricing algorithms that maximize revenue per vehicle-day.
Market Restraints
- Semiconductor Supply Concentration:Persistent chip shortages concentrated in Asian manufacturing hubs delay new vehicle deliveries and inflate per-unit acquisition costs for rental operators.
- Insurance Rate Volatility:NHTSA safety recall protocols and regional accident frequency data trigger premium spikes that erode margin structures on high-utilization commercial fleets.
- Residual Value Uncertainty:Accelerated electrification timelines and shifting consumer preferences toward EVs depress secondary market valuations for internal combustion MUVs.
Strategic Opportunities
- California ZEV Mandates:State-level zero-emission vehicle requirements create first-mover advantages for operators deploying electric MUVs ahead of 2035 phase-out deadlines.
- Event-Based Tourism Channels:Short-term rental partnerships with sports venues, convention centers, and music festivals capture premium pricing during demand spikes.
- Last-Mile Commercial Convergence:Hybrid MUV configurations serving both passenger transport and light commercial delivery expand addressable market beyond traditional leisure segments.
Industry Challenges
- Electrification Skill Gaps:Maintenance technicians trained on internal combustion powertrains require reskilling for high-voltage battery systems and regenerative braking diagnostics.
- Interoperable Charging Infrastructure:Fragmented payment networks and connector standards across Canadian provinces and US states complicate seamless fleet electrification roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America MUV Rental Market |
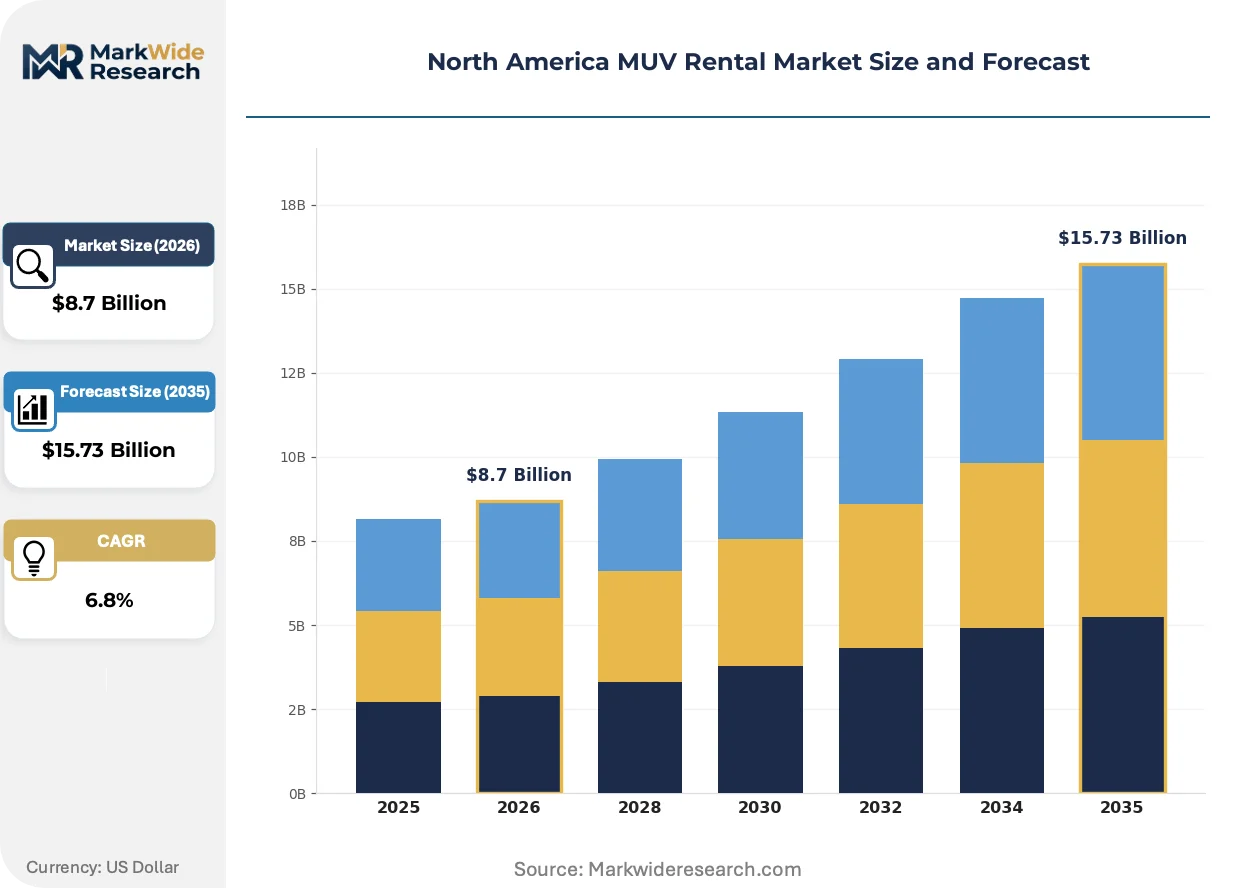
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Minivan, Pickup, Crossover Rental Duration: Short-term, Long-term, Daily, Weekly Customer Segment: Tourists, Business Travelers, Families, Corporates Rental Channel: Online, Offline, Travel Agencies, Corporate Partnerships |
| Companies Covered | Enterprise Holdings, Inc., Avis Budget Group, Inc., Hertz Global Holdings, Inc., SIXT SE, Airport Van Rental, Alamo, Penske Corporation, Inc., Budget Rent A Car System, Inc., DTG Operations, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America MUV Rental Market Trends and Innovations
Digital platforms and powertrain electrification are restructuring how rental operators acquire, deploy, and monetize multi-use vehicle assets across North American markets.
Telematics-driven fleet management is decomposing traditional fixed-location rental models into distributed, app-enabled vehicle access. Enterprise customers in construction and field services now expect real-time availability visibility and one-hour delivery windows. This capability compression forces operators to maintain smaller, more geographically dispersed inventories rather than centralized airport hubs.
The EPA's phased emissions standards for model years 2027 through 2032 are mandating substantial fleet composition changes. Rental operators must accelerate procurement of hybrid and electric powertrains to avoid penalties and maintain corporate account eligibility. California and New York operators face the steepest compliance curves due to overlapping state ZEV mandates.
Project-specific procurement patterns are displacing annual corporate fleet contracts. Energy sector clients in Texas and logistics operators near Canadian port cities now rent MUVs for defined contract durations tied to construction timelines or seasonal volume spikes. This behavioral shift concentrates revenue volatility in Q2 and Q3, requiring operators to build counter-cyclical leisure tourism buffers.
North America MUV Rental Market Segmentation
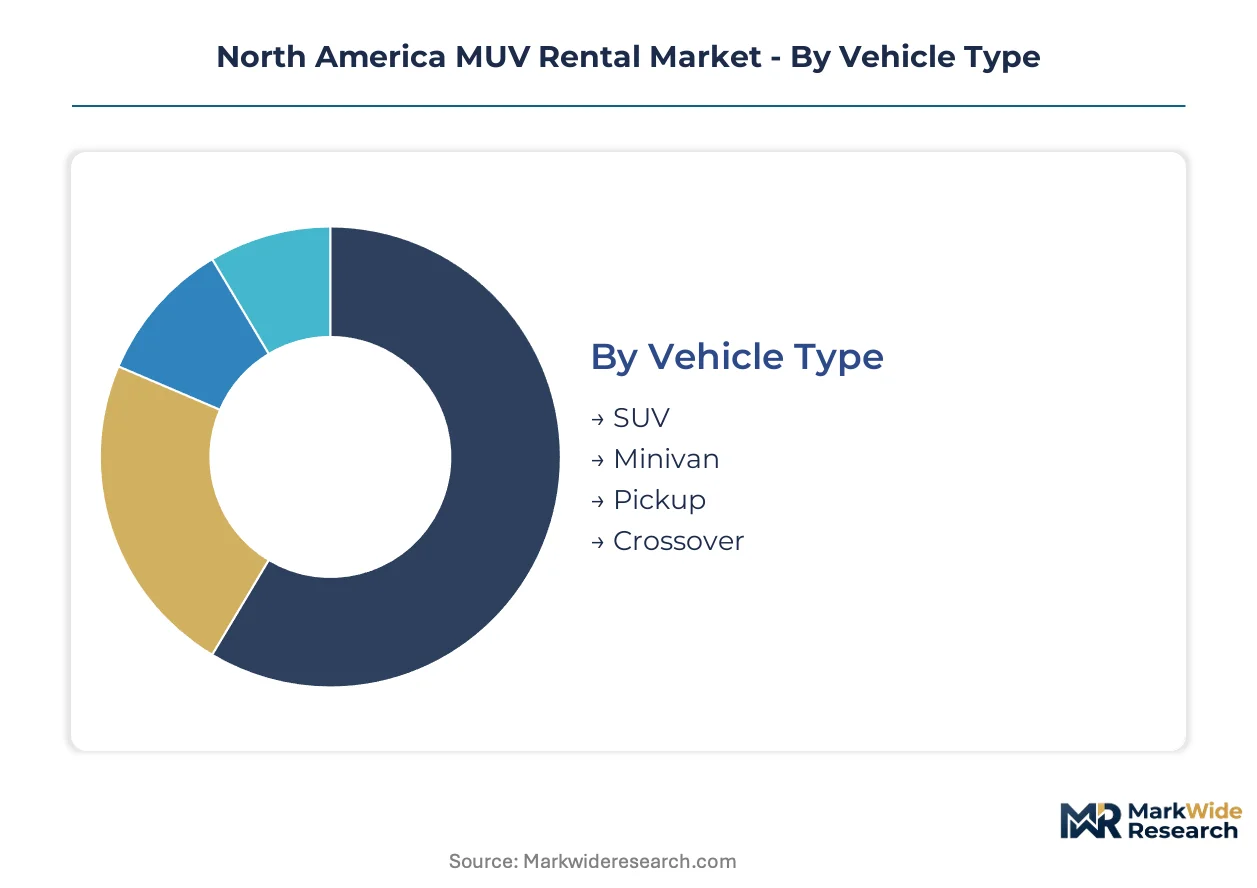
Segmentation in the North America MUV rental market exposes divergent utilization economics across vehicle configurations and customer procurement patterns. Rental operators calibrate fleet composition and pricing architectures to match duration-based demand volatility against regional regulatory constraints.
Vehicle Type:
Domestic demand concentrates on utility-forward configurations suited to Texas energy corridors and Florida tourism infrastructure, while cross-border fleet movements into Canada favor all-weather capability specifications.
- SUV:Three-row configurations with 5,000-pound towing capacity dominate corporate field service deployments across Alberta oil sands and Permian Basin operations. EPA emissions compliance timelines accelerate turnover toward hybrid powertrains in California and New York metro fleets.
- Crossover:Compact unibody architectures with 30-plus highway MPG ratings capture family leisure demand along Interstate 95 corridor and Great Lakes summer tourism circuits. Fleet managers prioritize crossovers for airport hub rotation due to lower per-mile fuel overhead.
- Minivan:Stow-and-go seating systems serve multi-generational family groups at Orlando and Anaheim destination clusters.
- Pickup:Crew cab configurations with bed utility anchor construction sector rentals in Houston, Dallas-Fort Worth, and Calgary metropolitan zones.
SUV commands the established base. The steepest expansion runs through Crossover.
Rental Duration:
Cost tier stratification separates premium weekly rates from compressed daily yields, with contract structures determining capital recovery timelines.
- Short-term:Event-driven bookings tied to sports championships, music festivals, and convention calendars command 40-60% rate premiums over baseline during demand spikes. Operators in Las Vegas, Nashville, and Austin deploy surge algorithms to capture this volatility.
- Weekly:Seven-day minimums with bundled mileage packages attract extended family vacationers and project-based corporate mobility. Canadian operators near Vancouver and Toronto report weekly contracts as the margin-accretive standard for summer tourism windows.
- Daily:Single-day transactions concentrate at airport facilities with high turnover velocity and minimal idle inventory.
- Long-term:Month-plus arrangements substitute for corporate fleet ownership in California and Washington state regulatory environments.
Weekly contracts anchor margin structures. Short-term rentals gain share fastest during seasonal demand compression.
Customer Segment:
Volume concentration tilts toward leisure procurement, though corporate accounts deliver superior yield predictability through negotiated rate floors.
- Families:Multi-passenger requirements with child safety seat compatibility drive SUV and minivan selection at Orlando, San Diego, and Vancouver destination markets. School vacation calendars create predictable Q2 and Q4 demand waves.
- Corporates:Procurement departments at energy, construction, and logistics firms negotiate master service agreements with utilization guarantees. Texas and Alberta-based operators report corporate accounts as the counter-cyclical stabilizer against leisure seasonality.
- Tourists:International arrivals at Miami, Los Angeles, and Toronto Pearson airports generate inbound demand for navigation-equipped vehicles.
- Business Travelers:Individual road warriors prioritize airport proximity and express checkout over vehicle specification.
Families generate the volume base. Corporate accounts deliver the steadiest expansion trajectory through contract renewals.
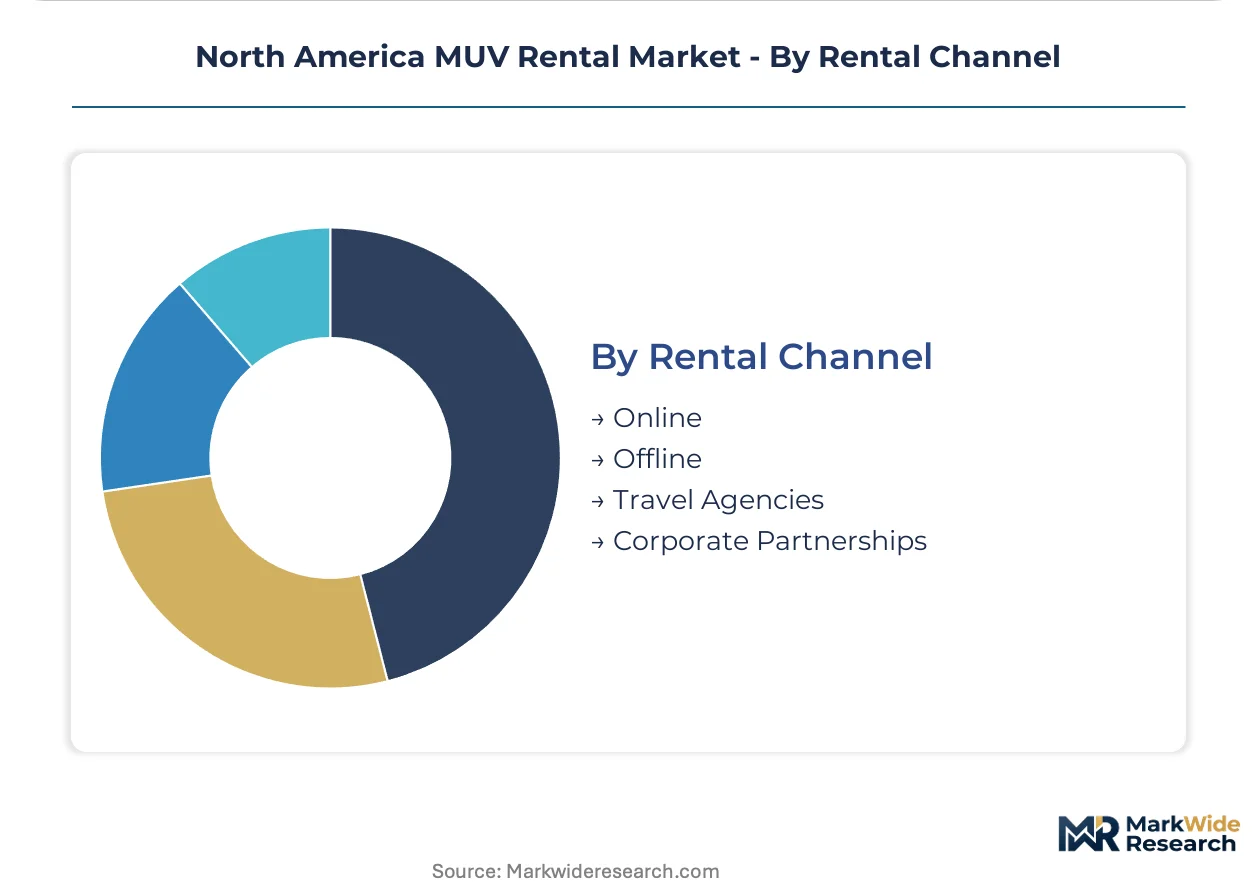
Rental Channel:
Customer type determines channel preference, with digital-native segments forcing platform investment while legacy relationships sustain offline throughput.
- Online:Mobile-first booking engines with real-time inventory visibility capture 35-and-under demographics. Hertz and Enterprise digital platforms enable one-hour delivery windows to construction sites and residential addresses.
- Corporate Partnerships:Direct agreements with Fortune 500 procurement departments bypass aggregator fees and establish volume commitments. Avis Budget Group anchors multi-year contracts with insurance and consulting sector clients.
- Offline:Walk-up transactions at neighborhood locations serve underbanked customers and emergency replacement needs.
- Travel Agencies:Package bundling with air and hotel reservations concentrates at Orlando and Hawaiian destination markets.
Corporate partnerships defend the established revenue base. Online channels climb the fastest as mobile penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian operators export fleet capacity into northern U.S. energy corridors during seasonal demand spikes. Cross-border utilization patterns concentrate in Alberta-to-Texas and Ontario-to-Michigan corridors.
United States
Texas and Florida sustain the highest MUV utilization rates through sprawling suburban infrastructure and tourism density. EPA emissions standards for model years 2027 through 2032 force rental operators toward accelerated fleet turnover. Houston and Dallas-Fort Worth anchor construction-sector demand for crew cab pickups with bed utility specifications.
Canada
Alberta oil sands operations and Vancouver-Toronto tourism circuits drive SUV and crossover procurement. Environment and Climate Change Canada federal regulations overlap with provincial zero-emission mandates in British Columbia and Quebec. Calgary metropolitan operators report corporate accounts as counter-cyclical stabilizers against leisure seasonality.
Mexico
Cross-border logistics corridors near Tijuana and Matamoros generate commercial MUV demand for last-mile freight convergence. SEMARNAT emissions protocols and NOM-044 standards shape fleet composition requirements. Mexico City metro operators face congestion pricing and Hoy No Circula restrictions that favor rental substitution over private ownership.
North America MUV Rental Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and fleet scale dimensions. The market consolidates around three national operators with neighborhood network density advantages against regional specialists. Strategic archetypes separate scale-driven full-service networks, technology-forward digital platforms, and niche event-rental specialists. Dominant competitive moves include telematics integration investments and long-term corporate contract structures that lock utilization guarantees.
Within the full-service network tier, Enterprise Holdings, Inc. and Avis Budget Group, Inc. exemplify scale-driven operators with established procurement relationships. Hertz Global Holdings, Inc. occupies a position emphasizing digital fleet management capabilities. These three entities represent the consolidated core against which regional specialists and event-rental operators differentiate through localized service models.
| Leading Market Players |
|---|
| Enterprise Holdings, Inc. |
| Avis Budget Group, Inc. |
| Hertz Global Holdings, Inc. |
| SIXT SE |
| Airport Van Rental |
| Alamo |
| Penske Corporation, Inc. |
| Budget Rent A Car System, Inc. |
| DTG Operations, Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day fleet procurement lead times compress pricing power for rental operators while amplifying cost pass-through sensitivity to semiconductor availability and EPA compliance deadlines. This inventory-to-regulation coupling forces MUV rental fleets into accelerated depreciation schedules that reshape margin structures across weekly and short-term contract tiers.
Pricing Analysis
Corporate fleet managers anchor contract-based pricing structures with volume-committed rate floors and utilization guarantees that insulate operators from daily-rate volatility. Price differentiation separates premium weekly packages with bundled mileage from compressed daily yields at airport hubs, with certification-grade telematics integration commanding rate premiums. Pricing pressure stems from insurance rate spikes triggered by NHTSA safety recall protocols, eroding margin structures on high-utilization commercial segments. Leisure tourists exhibit the highest price sensitivity, while energy sector corporate accounts absorb rate premiums for crew cab pickup specifications and real-time availability visibility.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and Vancouver anchors inbound logistics cost volatility for MUV fleet procurement, with container availability swings amplifying vehicle delivery uncertainty. OEM supply concentrates in the United States, Mexico, and Japan for light-duty truck platforms, with Mexican assembly plants feeding Texas and Florida demand corridors. Semiconductor chipsets, lithium-ion battery packs, and advanced driver-assistance sensors constitute critical component dependencies. Single-source vulnerability in Asian semiconductor manufacturing hubs poses structural supply chain risk. Distribution runs through neighborhood network nodes rather than centralized airport hubs, reflecting telematics-enabled fleet dispersion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America MUV rental market tracks a cyclical recovery anchored to construction sector capital expenditure cycles and seasonal tourism demand compression. Energy sector project timelines and suburban infrastructure expansion in Texas and Florida sustain utilization rate floors through demand troughs.
For Market Incumbents: Consolidate neighborhood network density in Houston, Dallas-Fort Worth, and Calgary metropolitan zones to defend against digital-native entrants. Lock multi-year corporate master service agreements with energy and logistics procurement departments to secure utilization guarantees. Accelerate EPA-compliant fleet turnover ahead of model year 2027 emissions thresholds to preempt compliance penalties and maintain account eligibility.
For New Entrants and Emerging Players: California ZEV certification fast-track programs unlock first-mover positioning in electric MUV deployment ahead of 2035 phase-out mandates. Target event-based tourism white space in Las Vegas, Nashville, and Austin with surge-pricing algorithms tied to sports and music festival calendars. Pursue direct corporate partnerships with construction and field services operators rather than competing for airport hub share.
For Investors and Strategic Acquirers: Long-term, this sits as a utility-like infrastructure play because fleet utilization economics tether to irreplaceable suburban mobility demand and regulatory-mandated turnover cycles. Acquisition targets should display dense neighborhood network footprints and established corporate account books in Texas or Alberta energy corridors. Monitor EPA emissions standard enforcement intensity and state-level ZEV mandate acceleration as inflection indicators for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time fleet tracking enables dynamic pricing algorithms that maximize revenue per vehicle-day across dispersed inventory nodes. |
| EPA Compliance Fleet Turnover | Accelerated procurement of hybrid and electric powertrains maintains corporate account eligibility under tightening emissions standards. |
| Corporate Partnership Expansion | Direct procurement agreements with energy sector clients bypass aggregator fees and establish counter-cyclical utilization buffers. |
| Event-Based Tourism Channel Development | Short-term rental partnerships with sports venues and convention centers capture 40-60% rate premiums during demand spikes. |
| Charging Infrastructure Partnership | Interoperable payment network agreements resolve fragmented connector standards that complicate seamless fleet electrification roadmaps. |
Research Methodology
Desk research of EPA regulatory filings, NHTSA safety recall databases, and state-level ZEV mandate documentation preceded structured interviews with fleet procurement managers at energy and logistics firms, rental operator fleet directors, telematics platform engineers, and insurance underwriters specializing in commercial auto coverage. Secondary validation drew from Department of Transportation utilization statistics, SEC 10-K disclosures from listed rental operators, and cross-border trade data tracking fleet movements between Alberta and Texas. Bottom-up segment sizing triangulated against top-down market value estimates derived from fleet inventory counts and average revenue per vehicle-day assumptions.
Variance decomposition across vehicle type, rental duration, customer segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from regression-based trending of historical utilization rates against fleet expansion trajectories and emissions compliance timelines. Modeled inputs incorporated EPA phase-in schedules for model years 2027 through 2032, suburban population growth projections in target metropolitan zones, and corporate fleet outsourcing elasticity estimates.
Decision-makers should treat outputs as directional under sustained suburban infrastructure expansion and stable energy sector capital expenditure assumptions; material deviation in construction activity or accelerated ZEV mandate enforcement would warrant model refresh. Forecasts embed assumptions regarding semiconductor supply normalization and insurance rate stabilization that remain exposed to exogenous shocks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Train Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Luxury Vehicles Market