
 North America Vehicle Rental Market | 2026-2036
North America Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vehicle Rental Market Analytics
Airport concession agreements is fragmenting as municipal authorities renegotiate exclusive operating rights and open terminals to additional operators. Enterprise Rent-A-Car leverages its neighborhood branch network to sustain local market density beyond airport catchments. Hertz competes through technology leadership in electric vehicle fleet deployment. Avis Car Rental anchors its position via corporate account relationships and centralized billing infrastructure.
North America Vehicle Rental encompasses the short-term and long-term provision of automobiles, light trucks, and vans through commercial transactions involving daily, weekly, or monthly rate structures, fleet maintenance protocols, and insurance bundling. The primary commercial purpose centers on providing mobility access without capital ownership burden for leisure travelers, business commuters, and institutional procurement officers. Traditional service type retains the largest revenue pool, though peer-to-peer platforms capture the fastest expansion trajectory among service categories. Commercial customer type commands premium rate structures and longer average rental durations compared to leisure segments.
FAA oversight of airport concession agreements, state-level zero-emission vehicle mandates such as California's ACT rule, and NHTSA safety recall compliance requirements collectively reshape fleet procurement timelines and capital allocation decisions. EPA emissions standards for light-duty vehicles directly influence model-year composition available to rental operators across the United States and Canada. Stakeholders must monitor how state-by-state regulatory divergence affects cross-border fleet standardization and remarketing residual values.
Market Dynamics
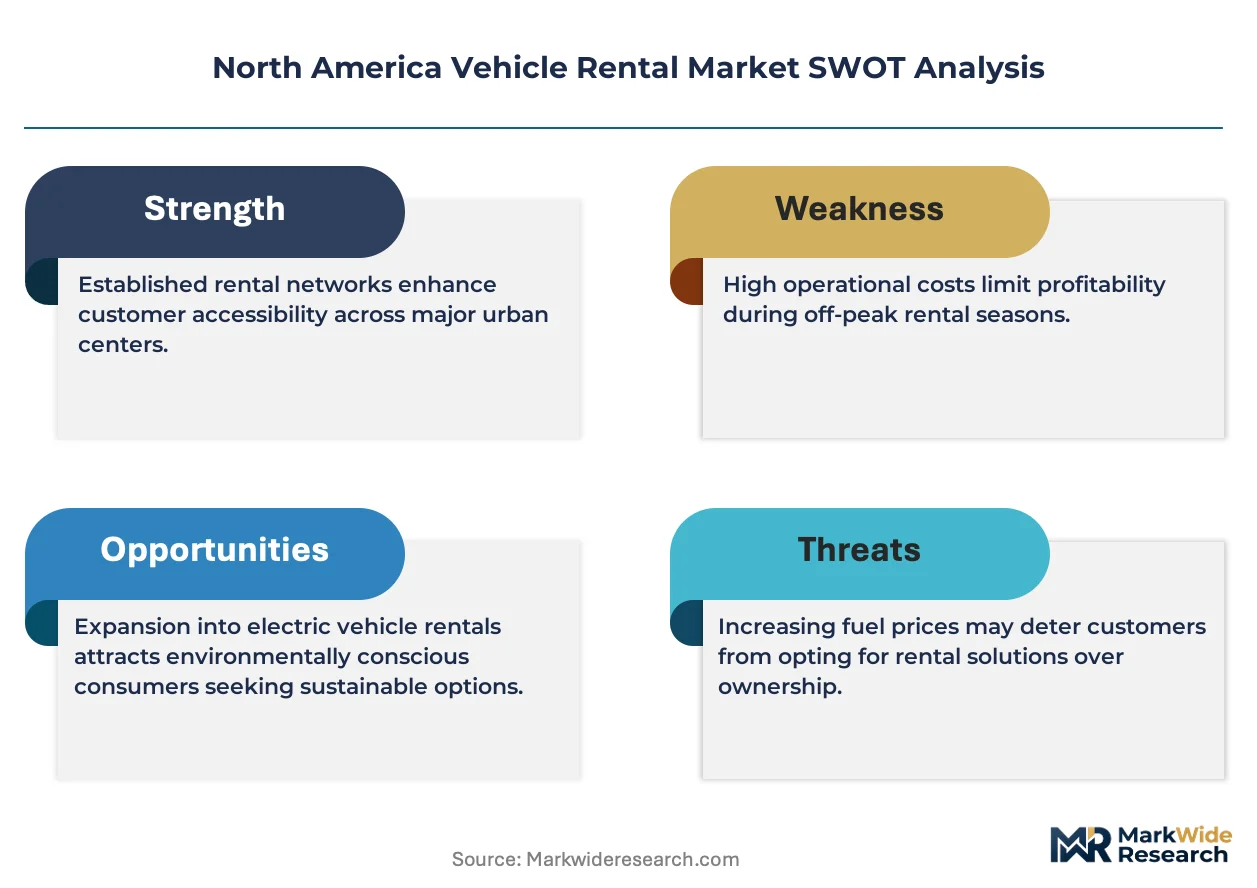
Fleet electrification mandates are compressing capital replacement cycles across North American rental operators, forcing simultaneous vehicle procurement and charging infrastructure deployment.
Growth Catalysts
- California ACT Regulation:Zero-emission truck procurement quotas create guaranteed demand pull for electric commercial van and light truck rentals through 2035.
- Energy Sector Concentration:Permian Basin and Gulf Coast business travel sustains above-average commercial utilization rates in Texas metropolitan hubs.
- Neighborhood Network Density:Urban branch proximity to residential and commercial districts captures local replacement demand outside airport catchments.
Market Restraints
- Residual Value Volatility:Rapid powertrain technology turnover compresses remarketing windows for internal combustion fleet assets.
- Charging Infrastructure Gap:Uneven DC fast-charging availability across rural interstate corridors limits electric fleet deployment flexibility.
- Lithium Supply Concentration:Battery raw material sourcing dependence on concentrated overseas processing creates input cost instability.
Strategic Opportunities
- Corporate Fleet Substitution:Long-term rental commitments displace direct vehicle ownership among mid-market enterprise procurement officers.
- Peer-to-Peer Platform Integration:Asset-light marketplace models unlock underutilized private vehicle inventory for rental availability.
- IRA Commercial EV Credits:Federal tax incentives reduce effective acquisition cost for battery electric rental fleet additions.
Industry Challenges
- Technician Certification Lag:High-voltage battery maintenance and repair training pipelines fail to match electric fleet scaling requirements.
- Airport Concession Fragmentation:Municipal renegotiation of exclusive operating rights forces incumbent operators into competitive bidding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vehicle Rental Market |
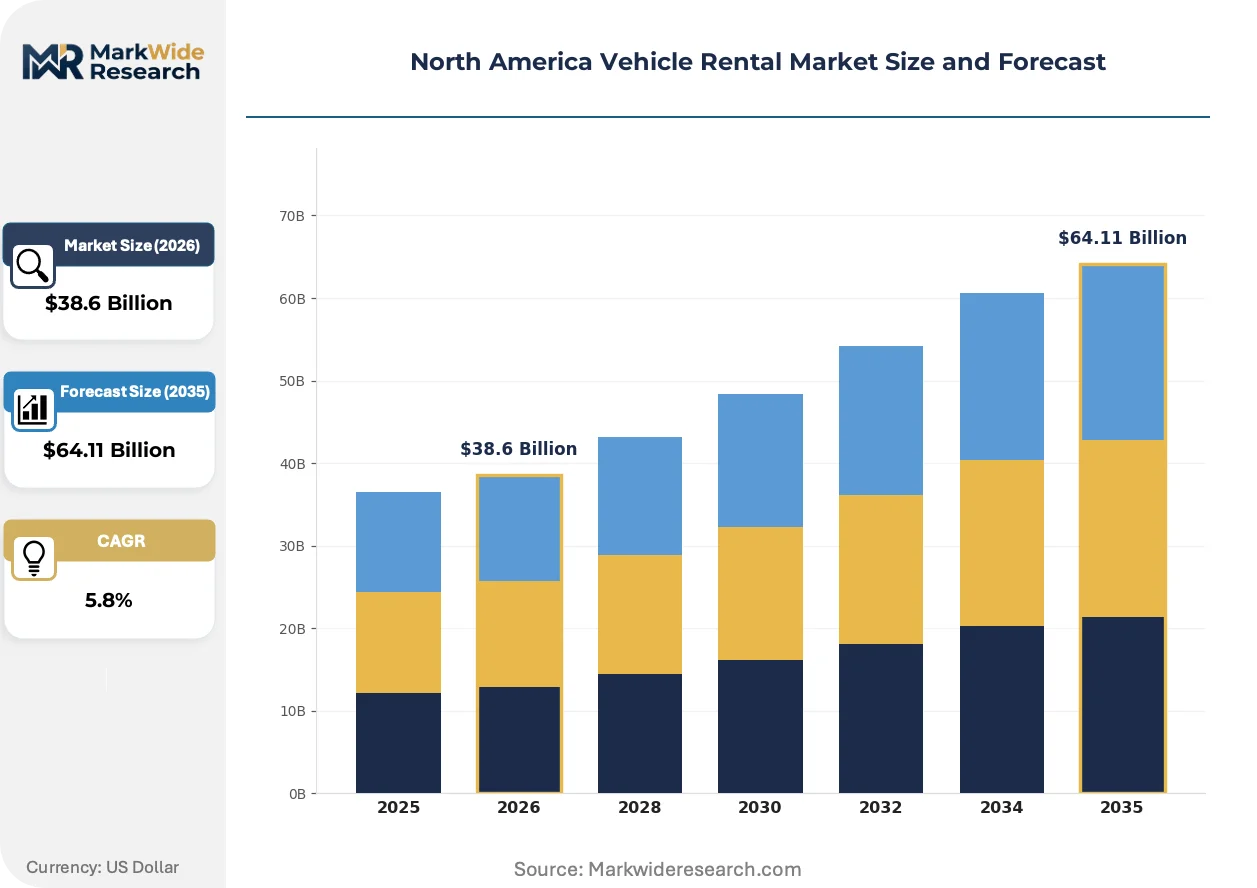
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Traditional, Luxury, Commercial Vehicle Type: SUV, Sedan, Van, Truck Rental Duration: Short-Term, Long-Term, Daily, Weekly Customer Type: Leisure, Business, Government, Corporate |
| Companies Covered | Budget, Alamo Rent A Car, Enterprise Rent-A-Car, Thrifty Car Rental, Sixt, Hertz, National Car Rental, Dollar Rent A Car, Avis Car Rental, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vehicle Rental Market Evolving Landscape
Connected fleet management systems and automated rental workflows are compressing transaction friction and enabling predictive asset deployment across distributed branch networks.
Telematics-integrated reservation platforms is rendering obsolete manual vehicle condition documentation and fuel-level reconciliation at return. Enterprise procurement teams now expect real-time fleet visibility and automated expense allocation. This compression of administrative overhead is shifting competitive differentiation toward software execution rather than physical asset scale.
EPA light-duty emissions standards are tightening model-year eligibility for rental fleet composition, accelerating powertrain diversification timelines. NHTSA safety recall compliance mandates compress vehicle hold periods and accelerate remarketing velocity. Rental operators in California and Quebec face the most acute procurement pressure due to overlapping federal and provincial zero-emission requirements.
Subscription-based mobility access is displacing traditional daily-rate structures among urban corporate accounts. Fleet managers in technology and professional services verticals now prioritize all-inclusive monthly fees over transaction-by-transaction billing. This preference shift concentrates in California and New York metropolitan corridors where parking scarcity amplifies ownership avoidance.
North America Vehicle Rental Market Segmentation
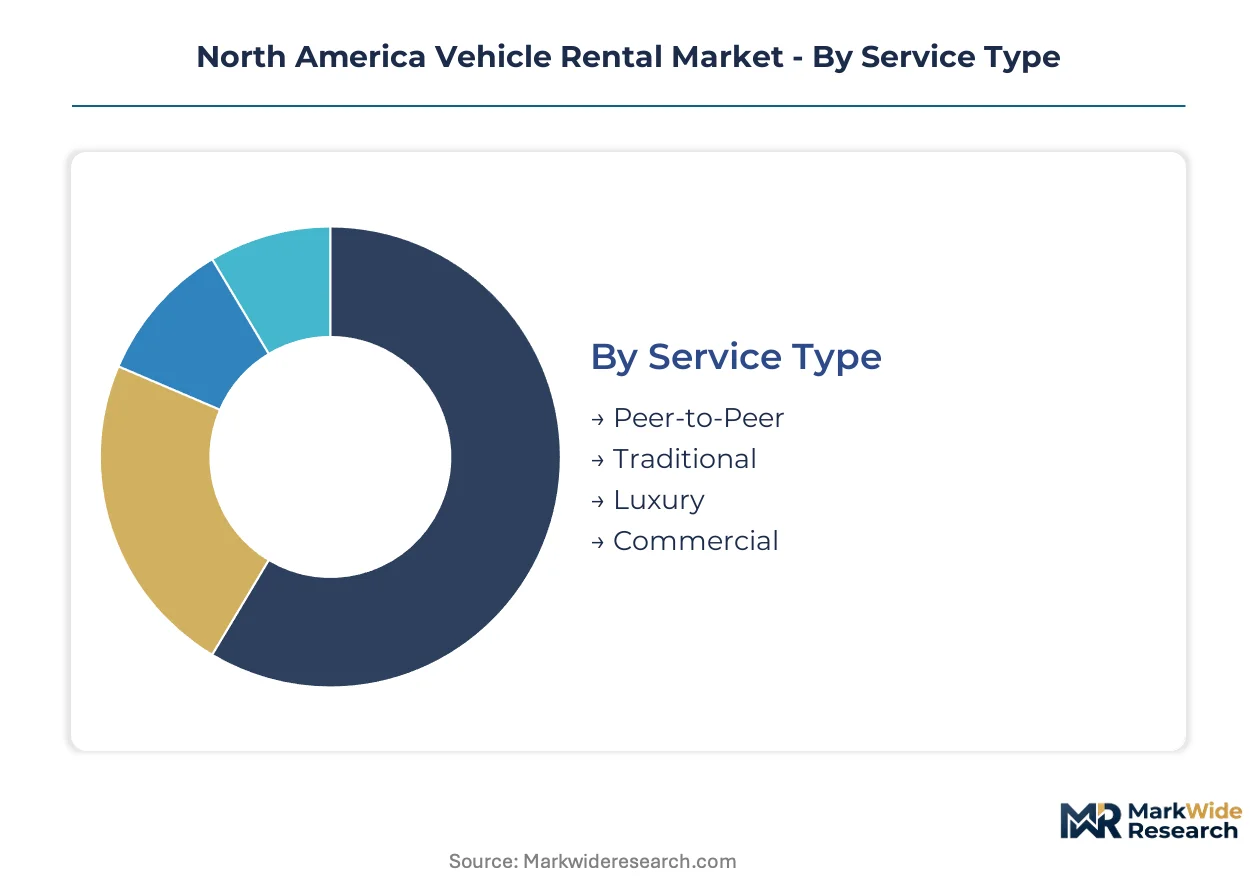
Segmentation in vehicle rental reveals how procurement patterns diverge across mobility use cases. Fleet operators calibrate pricing, insurance bundling, and maintenance protocols to match the risk profiles and utilization intensity of each category.
Service Type:
Cost tier differentiation separates asset-light platforms from capital-intensive fleet ownership models.
- Traditional:Corporate-owned vehicle pools with standardized daily and weekly rate structures dominate airport and neighborhood locations. Insurance bundling and fleet maintenance protocols generate recurring revenue streams. Texas energy corridor accounts anchor commercial utilization in this tier.
- Peer-to-Peer: Asset-light marketplace platforms match private vehicle owners with short-term renters through mobile applications. California's urban density and parking scarcity amplify owner willingness to monetize idle vehicles. Regulatory friction with municipal authorities constrains airport proximity operations.
- Luxury: Premium marques with concierge delivery and white-glove service protocols command rate multiples above standard fleet.
- Commercial: Light truck and van configurations serve contractor, logistics, and last-mile delivery procurement officers.
Traditional service commands the established base. The steepest expansion runs through Peer-to-Peer.
Vehicle Type:
Application requirements dictate powertrain selection and cabin configuration across rental portfolios.
- SUV:Elevated seating position and cargo flexibility capture family leisure demand and suburban business travel. Permian Basin energy sector contractors favor four-wheel-drive variants for remote site access. EPA emissions standards compress model-year eligibility for this high-volume category.
- Sedan: Fuel-efficient compact and mid-size configurations serve cost-conscious business commuters and urban leisure travelers. California's zero-emission mandates accelerate battery electric sedan procurement into rental fleets. Residual value volatility pressures remarketing timelines for internal combustion variants.
- Van: Passenger and cargo configurations address group travel and light commercial logistics needs.
- Truck: Half-ton and heavy-duty pickups serve construction, agriculture, and energy sector field operations.
SUV retains the volume anchor. Sedan is climbing the fastest on electrification tailwinds.
Rental Duration:
Customer type and procurement authority determine commitment length and rate structure negotiation leverage.
- Long-Term:Monthly and multi-month commitments displace direct fleet ownership among mid-market enterprise procurement officers. Corporate account relationships with centralized billing infrastructure lock in predictable utilization. Enterprise procurement teams in technology and professional services verticals prioritize all-inclusive fee structures.
- Short-Term: Daily and weekly transactions serve leisure travelers and intermittent business mobility needs. Airport concession agreements concentrate demand capture for this duration tier. Municipal renegotiation of exclusive operating rights fragments incumbent positioning.
- Daily: Single-day transactions dominate insurance replacement and emergency mobility scenarios.
- Weekly: Seven-day blocks optimize vacation travel and project-based business assignments.
Long-Term holds the revenue concentration. Short-Term is gaining share fastest on airport volume recovery.
Customer Type:
Margin structure and rate sensitivity diverge sharply across leisure, commercial, and institutional procurement.
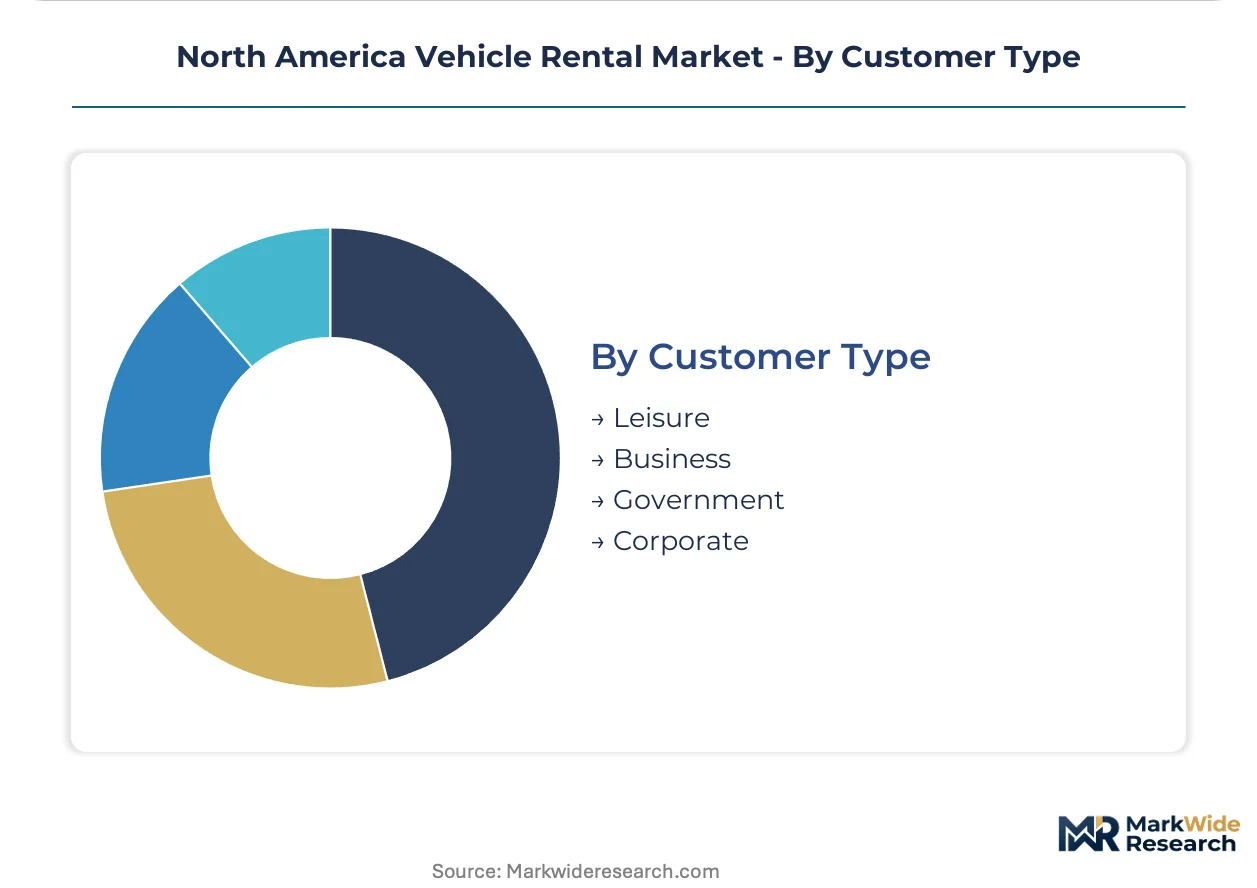
- Business:Corporate travel managers negotiate volume commitments with centralized billing and negotiated rate tiers. Above-average rental duration and reduced price elasticity sustain premium margin structures. Energy sector concentration in Texas metropolitan hubs sustains above-average utilization.
- Corporate: Fleet substitution programs displace direct vehicle ownership through long-term rental commitments. Subscription-based mobility access with all-inclusive monthly fees displaces transaction-by-transaction billing. California and New York metropolitan corridors concentrate this procurement preference.
- Leisure: Price-sensitive vacation travelers drive seasonal demand fluctuation and promotional rate competition.
- Government: Federal and state procurement vehicles with mandated small business set-asides and compliance reporting requirements.
Business commands the rate premium. Corporate is expanding most quickly on fleet substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA oversight of airport concession agreements anchors fleet deployment decisions across the United States, while provincial zero-emission mandates in Quebec and California's ACT regulation compress procurement timelines throughout the region.
United States
Texas energy corridor business travel sustains above-average commercial utilization rates in Houston and Dallas-Fort Worth metropolitan hubs. EPA light-duty emissions standards tighten model-year eligibility for rental fleet composition nationwide. California's Advanced Clean Trucks regulation pushes operators toward zero-emission commercial van procurement through 2035.
Canada
Quebec's provincial zero-emission vehicle mandates overlap with federal EPA-aligned standards to accelerate battery electric fleet turnover. Health Canada and PMRA oversee safety compliance across vehicle imports and commercial operations. Toronto and Vancouver concentrate corporate account demand for long-term rental substitutions.
Mexico
Cross-border logistics corridors generate commercial van and light truck rental demand for maquiladora supply chain operations. The country's national automotive regulator enforces safety and emissions alignment with USMCA trade provisions. Mexico City metropolitan area anchors leisure and business travel volume.
North America Vehicle Rental Market Competitive Landscape
Airport-centric operators and neighborhood network specialists split the market into distinct territorial domains with limited overlap in customer acquisition. Consolidation pressure concentrates among legacy brands holding municipal concession agreements, while asset-light platforms erode share in urban leisure segments. Two strategic archetypes dominate: integrated fleet owners with centralized billing infrastructure, and technology-forward operators prioritizing electric vehicle deployment. Competitive moves center on concession agreement renegotiation and charging infrastructure partnerships.
Within the integrated fleet tier, Enterprise Rent-A-Car and Avis Car Rental exemplify archetypes built on corporate account density and centralized procurement relationships. Hertz occupies a position emphasizing technology leadership in electrification. These three operators represent the dominant competitive anchors shaping rate structures and fleet composition standards across the region.
| Leading Market Players |
|---|
| Budget |
| Alamo Rent A Car |
| Enterprise Rent-A-Car |
| Thrifty Car Rental |
| Sixt |
| Hertz |
| National Car Rental |
| Dollar Rent A Car |
| Avis Car Rental |
| Others |
Value Network & Pricing Analysis
Lithium supply concentration in Chile, Australia, and China generates input cost instability that compresses electric fleet procurement timelines while widening spreads between standard internal-combustion rate cards and premium zero-emission offerings. This raw-material chokepoint forces rental operators to pre-position capital across multiple pricing tiers and supply chain configurations simultaneously.
Pricing Analysis
The customization-premium spread separates configured-to-order long-term corporate subscriptions from transactional daily-rate walk-ups. Three-tier pricing structure across premium, standard, and economy levels anchors airport and neighborhood rate cards, with electrified SUVs commanding rate multiples above internal-combustion equivalents. Cost compression in the standard tier is intensifying because IRA commercial EV credits reduce effective acquisition costs for battery electric fleet additions. Leisure travelers exhibit the highest price sensitivity, while corporate fleet substitution programs show reduced elasticity due to bundled maintenance and centralized billing value.
Supply Chain Analysis
Supplier-financing facilities from battery OEMs extend payment terms for rental fleet operators scaling electric vehicle procurement. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells, while semiconductor content for telematics systems draws from Taiwan and the United States. Single-source vulnerability in cathode active material processing creates exposure to export licensing shifts. Distribution runs through OEM-direct fleet allocation channels and multi-brand wholesale auctions for remarketing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician certification pipelines for high-voltage battery maintenance lag electric fleet scaling requirements, creating a capability gap that constrains operator expansion velocity and inflates service costs.
For Market Incumbents: Pre-empt peer-to-peer platform encroachment by embedding telematics-integrated reservation systems into corporate account workflows. Deepen vertical integration into charging infrastructure partnerships along Texas interstate corridors and California metropolitan hubs. Secure exclusive technician training partnerships with community colleges before competitor talent acquisition accelerates. For New Entrants and Emerging Players: Build out asset-light marketplace models targeting California urban density where parking scarcity amplifies owner willingness to monetize idle vehicles. White-space concentration sits in last-mile commercial van rentals for logistics contractors underserved by legacy fleet operators. Go-to-market execution should prioritize mobile-first condition documentation to bypass incumbent administrative overhead advantages. For Investors and Strategic Acquirers: California's Advanced Clean Trucks regulation reshapes the acquisition landscape toward operators with demonstrated zero-emission fleet procurement capability and charging infrastructure deployment experience. Long-term viability centers on integrated fleet owners with centralized billing infrastructure and corporate account density. Watch for municipal airport concession renegotiation outcomes as inflection indicators for incumbent positioning stability.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | DC fast-charging network access unlocks electric fleet deployment flexibility across rural interstate corridors. |
| Corporate Subscription Platform | All-inclusive monthly fee structures displace transaction-by-transaction billing for technology sector procurement teams. |
| Technician Certification Pipeline | High-voltage battery maintenance training capacity determines electric fleet scaling velocity and service cost structure. |
| Airport Concession Defense | Municipal renegotiation of exclusive operating rights demands competitive bidding preparation and local political relationship investment. |
| Telematics Integration Investment | Real-time fleet visibility and automated expense allocation satisfy enterprise procurement team software execution expectations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC operator filings, and EPA emissions compliance records. Fleet managers at Enterprise, Hertz, and Avis procurement divisions, airport concession directors at Dallas-Fort Worth and Los Angeles International, and energy sector travel coordinators in Houston provided operational perspective. Bottom-up branch-level utilization modeling and top-down regional fleet composition analysis triangulate volume estimates.
Forecast inputs span vehicle class, propulsion architecture, rental duration tier, and customer type segmentation dimensions. CAGRs derive from regression against historical fleet turnover rates, regulatory compliance timelines, and corporate account contract renewal patterns. Electric vehicle adoption curves, residual value volatility assumptions, and charging infrastructure buildout pace inform projection sensitivity.
Stress conditions across lithium carbonate price bands, IRA credit extension scenarios, and airport concession renewal failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and technology cost curves. Macroeconomic contraction, accelerated zero-emission mandate phase-ins, or breakthrough battery chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Multispace Parking Meter Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
India Taxi Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Bike Rental Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
United States Car Rental Market