
 Europe Luxury Car Market | 2026-2036
Europe Luxury Car Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Car Market Analysis
EURO 7 emission standards is redrawing engineering investment priorities across European luxury marques. BMW sustains R&D intensity in solid-state battery architectures for its forthcoming electric flagship lines. Mercedes-Benz anchors its position through captive supply of high-performance powertrain components from German in-house plants. Porsche differentiates via motorsport-derived hybrid systems that satisfy both regulatory thresholds and enthusiast expectations.
The Europe luxury car comprises passenger vehicles engineered to premium specifications with advanced materials, superior powertrain performance, and refined cabin appointments serving affluent consumers and corporate users. SUVs now dominate volume contribution within the product type dimension, while electric technology within the technology dimension captures the fastest margin expansion as OEMs reallocate platform development budgets. Sedans retain structural importance in corporate fleet procurement, though convertibles occupy a narrowing niche concentrated among collector buyers.
The EU Green Deal, EMA carbon accounting protocols, and Germany's KBA type-approval requirements collectively tighten market access for non-compliant powertrains. REACH chemical restrictions further constrain interior material sourcing, pushing manufacturers toward certified sustainable supply chains. Stakeholders must monitor how delegated acts under the EU AI Act reshape autonomous driving feature deployment timelines and liability frameworks.
Market Dynamics
EURO 7 emission standards are compressing engineering timelines while forcing simultaneous investment in solid-state battery architectures and motorsport-derived hybrid systems across Stuttgart, Munich, and Ingolstadt production clusters.
Growth Catalysts
- EU Green Deal fleet mandates:Corporate procurement departments face binding CO2 reduction targets that electrify luxury fleet replacement cycles.
- Solid-state battery maturation:German in-house R&D programs are achieving energy density thresholds that enable extended-range electric flagship architectures.
- KBA type-approval pathways:Streamlined certification processes for hybrid powertrains accelerate model-to-market intervals for performance variants.
Market Restraints
- REACH chemical compliance:Interior material sourcing faces restricted substance lists that eliminate legacy leather tanning and synthetic finishing processes.
- German production cluster concentration:Powertrain component manufacturing concentrates in Baden-Württemberg and Bavaria, creating single-point vulnerability to energy cost volatility.
- Lithium-ion raw material dependency:Cell cathode supply chains remain anchored to non-European refining capacity, exposing margin compression from input price swings.
Strategic Opportunities
- EMA carbon accounting protocols:Verified lifecycle emissions documentation creates premium pricing justification for certified sustainable supply chains.
- EU AI Act delegated acts:Autonomous driving feature liability frameworks will reward early regulatory compliance with first-mover deployment windows.
- Nordic corporate fleet electrification:Norwegian and Swedish buyers maintain accelerated replacement cycles that outpace continental European averages.
Industry Challenges
- Solid-state manufacturing scale-up:Dry electrode coating and ceramic electrolyte handling require cleanroom infrastructure absent from legacy lithium-ion plants.
- Powertrain software integration:Motorsport-derived hybrid control systems demand embedded systems engineering talent concentrated among Formula 1 supplier networks.
- Multi-homologation complexity:Divergent EU member state interpretations of EURO 7 implementation timelines fragment production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Car Market |
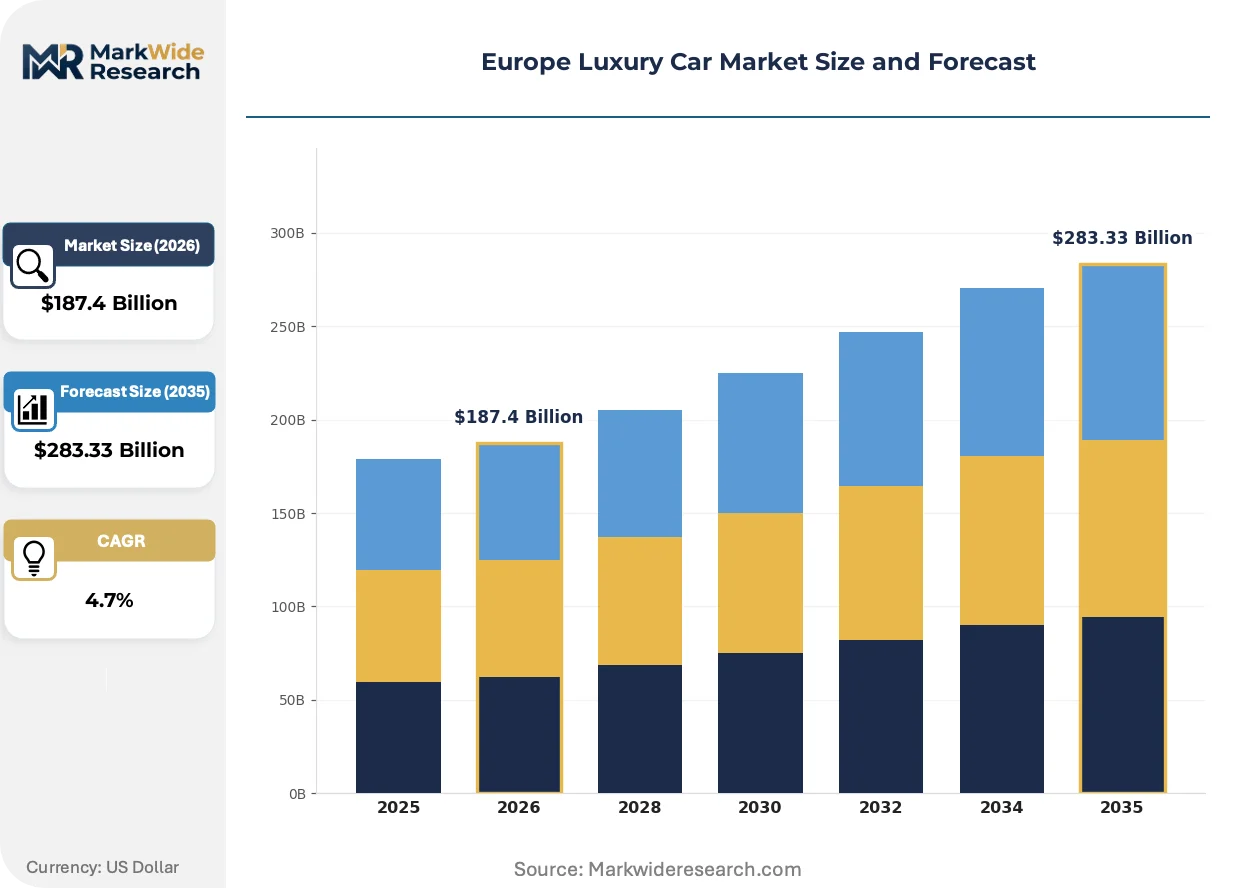
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Coupes, Convertibles End User: Affluent Individuals, Corporate Fleets, Luxury Rentals, Car Collectors Technology: Hybrid, Electric, Autonomous, Performance Sales Channel: Dealerships, Online Platforms, Auctions, Direct Sales |
| Companies Covered | Audi, Lamborghini, BMW, Aston Martin, Bentley, Mercedes-Benz, Ferrari, Rolls-Royce, Porsche, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Car Market Emerging Trajectories
Electrification architectures are converging with digital cockpit systems to redefine how European luxury marques engineer performance credentials and cabin differentiation simultaneously.
Solid-state battery cell chemistry is miniaturizing thermal management hardware requirements while preserving energy density targets. German luxury OEMs are integrating these cells into skateboard platforms ahead of volume production timelines. The technology is miniaturizing packaging constraints that previously forced SUV form factors over sedan proportions.
EURO 7 emission standards are mandating real-world driving emission monitoring hardware across all combustion-assisted powertrains. Engineering departments must now certify hybrid systems under standardized RDE test cycles rather than laboratory conditions. Performance-oriented segments face the steepest compliance cost escalation as thermal efficiency thresholds tighten.
Corporate fleet buyers are consolidating procurement authority into centralized sustainability departments with binding electrification quotas. Traditional dealer channel relationships face displacement by direct manufacturer fleet agreements with lifecycle service bundling. Nordic markets demonstrate the most advanced procurement centralization, with Swedish and Norwegian corporate buyers leading contract structure innovation.
Europe Luxury Car Market Segmentation
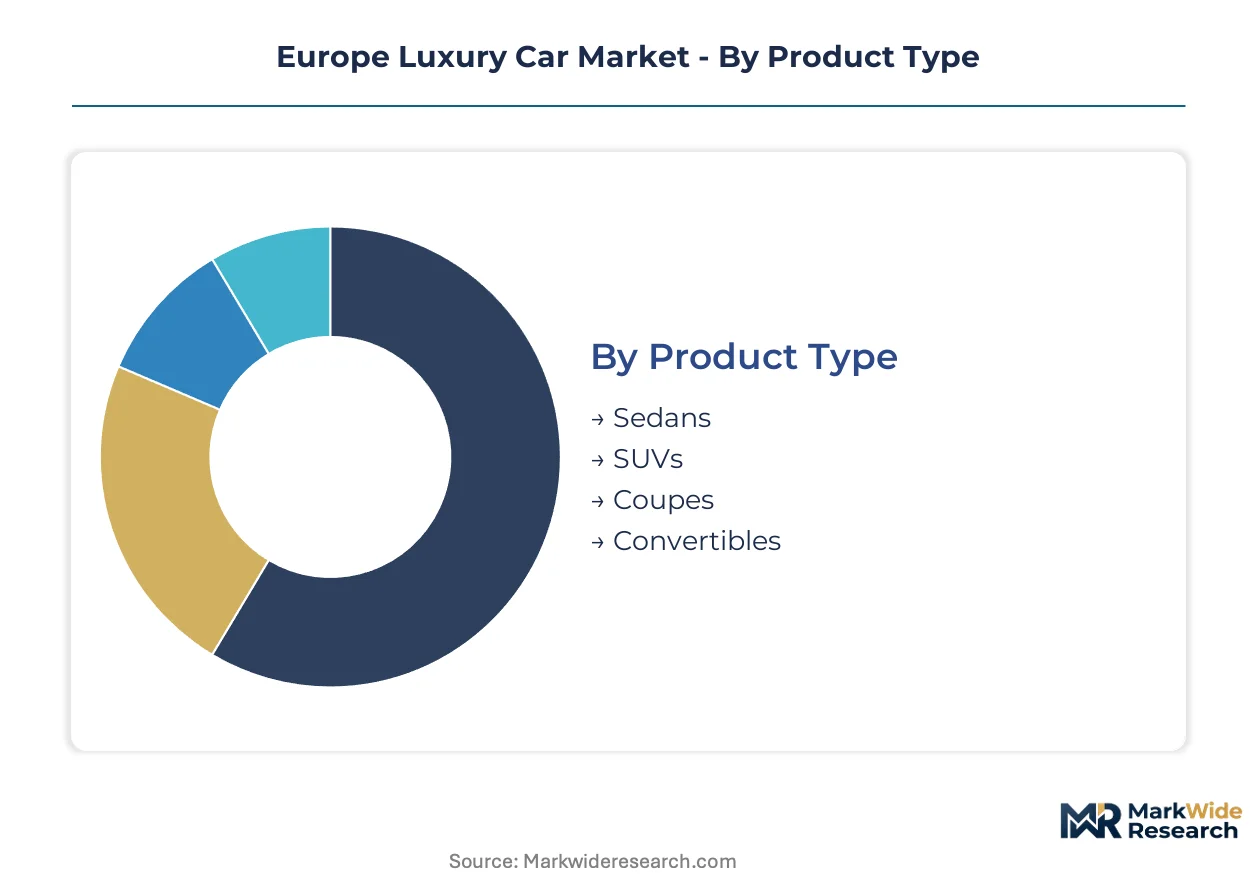
Segmentation in the Europe luxury car market determines how engineering priorities align with divergent buyer economics. Corporate procurement departments and individual collectors operate on fundamentally different replacement cycles, forcing OEMs to configure powertrain portfolios and distribution investments accordingly.
Product Type:
SUVs flow primarily through dealership networks serving corporate fleet managers, while sedans and convertibles concentrate in direct manufacturer relationships with individual collectors.
- SUVs:These vehicles integrate elevated seating positions with electrified powertrain packaging that accommodates battery skateboard architectures beneath the cabin floor. Demand concentrates among German corporate fleet buyers subject to EU Green Deal CO2 reduction mandates, with Stuttgart and Munich production clusters prioritizing extended-range electric variants for this channel.
- Sedans:Lower rooflines and aerodynamic profiles preserve thermal efficiency advantages under EURO 7 real-world driving emission test cycles. Corporate procurement departments in Nordic markets maintain structural demand for this form factor, though volume is shifting toward electrified powertrains that challenge traditional hood-length proportions.
- Coupes:Two-door configurations with fixed roofs serve enthusiast buyers prioritizing chassis rigidity and weight distribution.
- Convertibles:Retractable roof mechanisms occupy a narrowing niche concentrated among collector buyers in Mediterranean markets.
SUVs dominate installed base. Electric variants within SUVs are where expansion concentrates.
End User:
Cost tiers stratify sharply across these segments, with corporate fleets commanding volume discounts that individual collectors cannot access.
- Corporate Fleets:Centralized procurement departments negotiate lifecycle service bundling with binding electrification quotas under EMA carbon accounting protocols. Swedish and Norwegian buyers lead contract structure innovation, accelerating replacement cycles beyond continental European averages.
- Affluent Individuals:Direct manufacturer relationships increasingly displace traditional dealer channels, particularly for electric flagship pre-orders requiring deposit structures.
- Luxury Rentals:Fleet turnover economics demand residual value predictability that favors hybrid powertrains with established secondary markets.
- Car Collectors:Limited-production combustion variants command auction premiums as EURO 7 implementation timelines clarify future scarcity.
Corporate Fleets dominate installed base. Affluent Individuals are where margin expansion concentrates.
Technology:
Application requirements diverge between urban autonomous systems and autobahn-performance powertrains, splitting R&D budget allocation.
- Electric:Solid-state battery architectures from German in-house R&D programs achieve energy density thresholds that enable extended-range flagship platforms. Demand concentrates among corporate fleet buyers facing binding CO2 reduction targets, with KBA type-approval pathways streamlining certification timelines.
- Hybrid:Motorsport-derived systems satisfy EURO 7 regulatory thresholds while preserving enthusiast performance expectations through thermal efficiency optimization.
- Autonomous:EU AI Act delegated acts reshape liability frameworks and deployment timelines for Level 3+ highway assistance features.
- Performance:Internal combustion variants face steepest compliance cost escalation as real-world driving emission monitoring hardware adds weight and complexity.
Hybrid dominates installed base. Electric is where expansion concentrates.
Sales Channel:
Geography determines channel viability, with Nordic markets demonstrating the most advanced procurement centralization favoring direct manufacturer relationships.
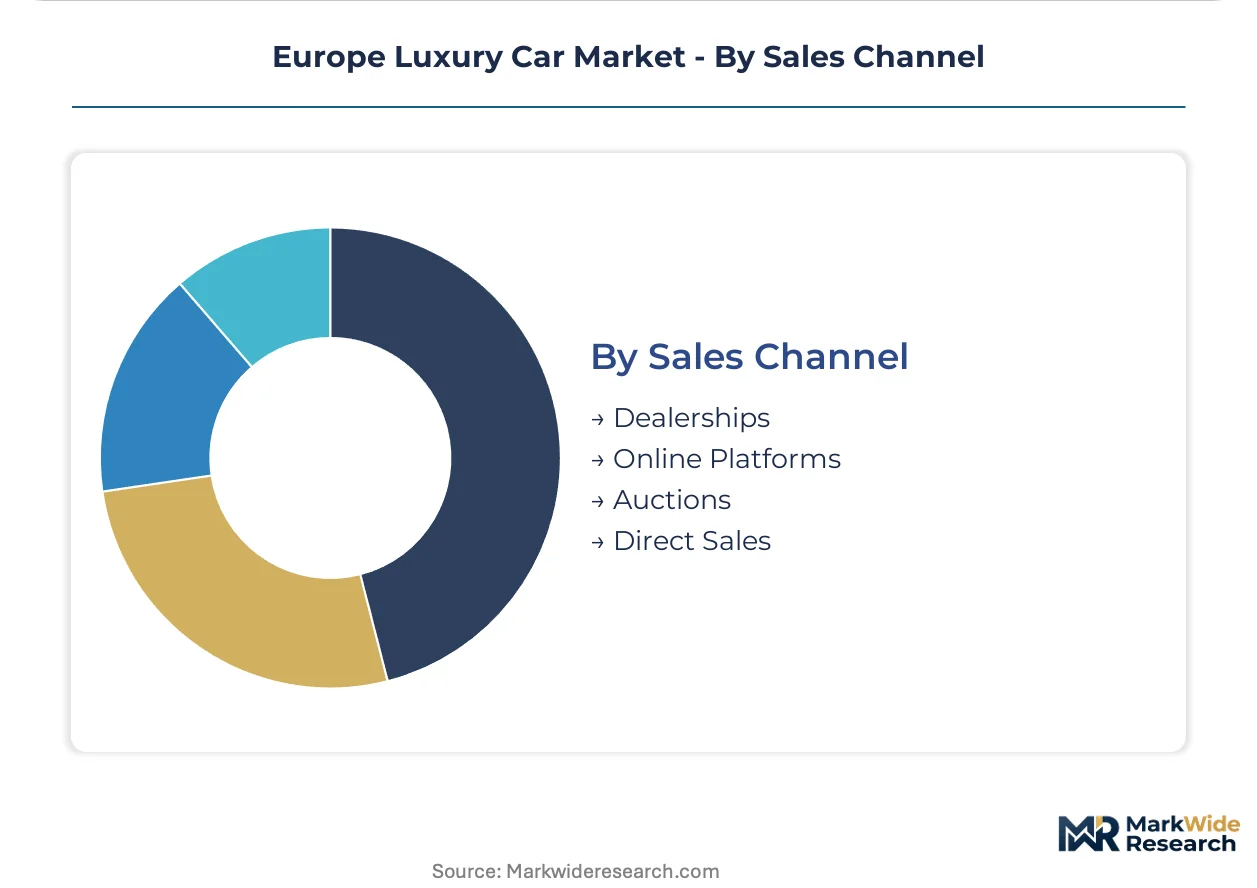
- Dealerships:Traditional franchise networks face displacement as OEMs consolidate corporate fleet authority into direct manufacturer agreements with lifecycle service bundling.
- Online Platforms:Digital configuration tools with deposit-based pre-order structures capture affluent individual buyers for electric flagship launches.
- Auctions:Collector market liquidity concentrates in specialized venues serving limited-production combustion variants facing EURO 7 scarcity premiums.
- Direct Sales:Manufacturer-owned channels bypass franchise margin structures, particularly for corporate fleet contracts with centralized sustainability departments.
Dealerships dominate installed base. Direct Sales are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal fleet mandates are redrawing procurement patterns across European corporate buyers, with binding CO2 reduction targets accelerating electrified vehicle replacement cycles in high-income markets.
Germany
Corporate fleet buyers in Stuttgart, Munich, and Ingolstadt production clusters face the strictest KBA type-approval requirements under EURO 7 emission standards. German manufacturers anchor regional supply through captive in-house powertrain component plants concentrated in Baden-Württemberg and Bavaria. Stuttgart's engineering corridors sustain solid-state battery R&D programs that feed extended-range electric flagship architectures.
United Kingdom
Collector buyers in London and the Southeast concentrate demand for limited-production combustion variants facing EURO 7 scarcity premiums. The UK's Vehicle Certification Agency aligns with EURO 7 implementation timelines while maintaining distinct type-approval pathways for low-volume manufacturers. Crewe and Gaydon production facilities specialize in hand-finished coachbuilt variants serving auction liquidity channels.
Italy
Enthusiast demand in Lombardy and Emilia-Romagna preserves structural preference for motorsport-derived hybrid systems. Italian regulators under the Ministry of Infrastructure and Transport coordinate EURO 7 adoption with carve-outs for heritage powertrain architectures. Maranello and Sant'Agata Bolognese engineering clusters anchor thermal efficiency optimization programs for performance-oriented segments.
Sweden
Corporate procurement centralization in Stockholm and Gothenburg leads Nordic contract structure innovation with binding electrification quotas. Swedish Transport Agency carbon accounting protocols under EMA frameworks reward verified lifecycle emissions documentation. Trollhättan and Gothenburg technical centers accelerate replacement cycles beyond continental European averages through direct manufacturer fleet agreements.
France
Luxury rental fleet operators in Paris and the Île-de-France region prioritize residual value predictability through hybrid powertrain procurement. French environmental regulators enforce REACH chemical restrictions that constrain interior material sourcing for leather and synthetic finishing processes. Sochaux and Mulhouse manufacturing corridors adapt platform engineering to accommodate battery skateboard architectures beneath SUV cabin floors.
Europe Luxury Car Market Vendor Landscape
Listed leaders compete with private specialists across powertrain technology and distribution channel dimensions. Stuttgart, Munich, and Ingolstadt production clusters concentrate engineering talent and captive component supply, creating tiered competitive positions around electrification readiness and motorsport heritage. Three archetypes dominate: integrated manufacturing groups with in-house battery R&D, specialist marques dependent on external powertrain sourcing, and heritage coachbuilders serving collector auction channels. Competitive moves concentrate on direct sales channel expansion and solid-state battery manufacturing partnerships.
Within the integrated manufacturing tier, BMW AG and Mercedes-Benz Group AG exemplify scale-driven electrification strategies, while Porsche AG occupies a position bridging motorsport-derived hybrid specialization with volume platform economics. These Stuttgart and Munich-based entities anchor German production cluster concentration through Baden-Württemberg and Bavaria in-house component plants.
| Leading Market Players |
|---|
| Audi |
| Lamborghini |
| BMW |
| Aston Martin |
| Bentley |
| Mercedes-Benz |
| Ferrari |
| Rolls-Royce |
| Porsche |
| Others |
Supply Flow & Price Mechanics
Long-term fleet offtake agreements with corporate sustainability departments lock in both battery cell allocation and fixed-price visibility across EU Green Deal compliance cycles. These contracts concentrate procurement power among Nordic corporate buyers while insulating German manufacturers from spot lithium price volatility.
Pricing Analysis
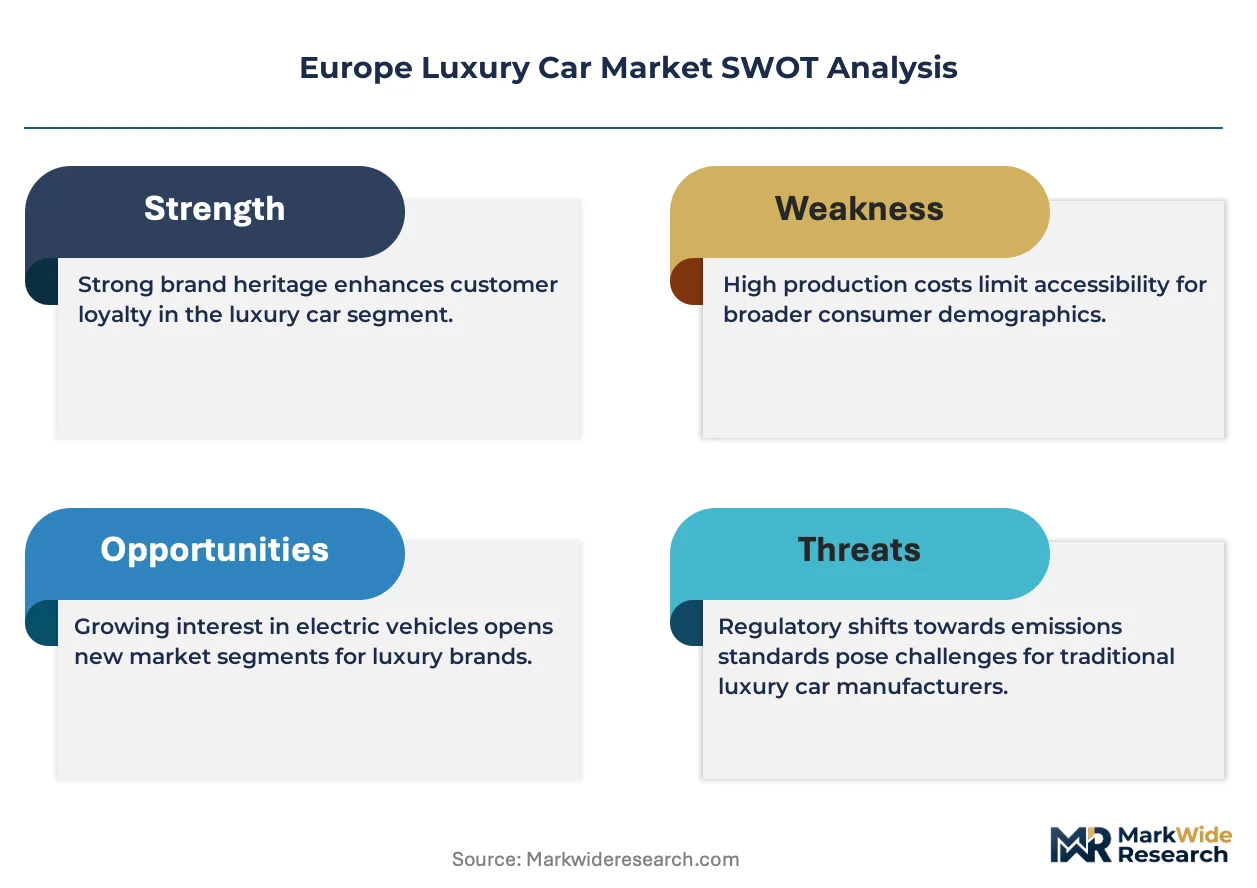
Certification level under EURO 7 and REACH compliance creates the primary spread between premium and standard tier positioning. Three-tier pricing structure across certified sustainable, conventional premium, and legacy combustion variants reflects differential compliance cost burdens. Pricing pressure stems from lithium-ion raw material dependency on non-European refining capacity. Corporate fleet buyers exhibit lowest price sensitivity due to binding CO2 mandate timelines, while luxury rental operators face highest sensitivity around residual value predictability.
Supply Chain Analysis
Extended lead times for solid-state battery ceramic electrolyte handling now stretch eighteen to twenty-four months for cleanroom infrastructure commissioning. German in-house plants in Baden-Württemberg and Bavaria anchor powertrain component supply, drawing from Chinese and South Korean cell cathode refining capacity. Single-source vulnerability concentrates in Baden-Württemberg energy-intensive manufacturing clusters exposed to electricity cost volatility. Distribution runs through direct manufacturer fleet agreements displacing traditional franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization among Nordic corporate sustainability departments has shifted buyer power decisively toward fleet aggregators commanding volume discounts and lifecycle service bundling.
For Market Incumbents: Shield margin position through captive in-house production of high-performance powertrain components in Bavaria and Baden-Württemberg clusters. Accelerate solid-state battery manufacturing partnerships ahead of volume scale-up bottlenecks. Deepen backward integration into certified sustainable interior material supply chains to neutralize REACH compliance cost escalation.
For New Entrants and Emerging Players: Lead with direct sales channel establishment targeting Swedish and Norwegian corporate fleet procurement centralization. The most penetrable white space sits in extended-range electric sedan architectures serving Nordic replacement cycles ahead of continental European adoption curves. Pursue KBA type-approval pathway specialization for streamlined hybrid certification timelines.
For Investors and Strategic Acquirers: Specialist marques with motorsport-derived hybrid intellectual property and established auction liquidity channels represent priority acquisition targets. Long-term viability hinges on electrification platform economics converging with heritage brand equity preservation. Watch EU AI Act delegated act implementation timelines as autonomous driving liability framework inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Manufacturing Partnership | Secures cleanroom infrastructure and ceramic electrolyte handling capacity ahead of EURO 7 compliance deadlines. |
| Direct Fleet Sales Channel Expansion | Bypasses franchise margin structures to capture centralized Nordic corporate procurement with lifecycle bundling. |
| REACH-Compliant Interior Material Sourcing | Eliminates legacy leather tanning processes through certified sustainable supply chains under ECHA restrictions. |
| Motorsport Hybrid System Commercialization | Translates Formula 1 thermal efficiency optimization into EURO 7-compliant performance variants for enthusiast segments. |
| Autonomous Driving Regulatory Pre-Compliance | Positions early movers for first-mover deployment windows under EU AI Act delegated act liability frameworks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, corporate fleet sustainability directors, and KBA certification specialists; and secondary validation through vehicle production databases, IHS Markit registration data, EU regulatory filings, and SEC automotive segment disclosures. Bottom-up unit economics triangulated against top-down market sizing across propulsion architecture and regional production cluster dimensions.
Across the analysis window, forecasts model vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation dimensions. CAGRs derive from regression analysis against historical replacement cycle patterns and regulatory compliance cost curves. Key inputs include EU Green Deal fleet mandate enforcement schedules and solid-state battery energy density achievement timelines from German in-house R&D programs.
Forecasts assume regulatory continuity in EURO 7 implementation and EU AI Act delegated act pathways; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Automotive Luxury Vehicle Market