
 Small Suvs Market | 2026-2036
Small Suvs Market Size, Share, and Industry Trends Forecast 2026-2036
Small Suvs Market Intelligence
Aluminum is repositioning body-in-white economics as manufacturers substitute stamped steel panels to shave curb weight and extend electric range. Toyota leverages its hybrid architecture leadership to anchor premium pricing across compact and crossover formats. Ford sustains North American production scale while competing on truck-derived design language that differentiates its Bronco Sport and Escape lines.
Small SUVs span vehicles roughly 4.1 to 4.5 meters in length with unibody construction, ground clearance between 180 and 220 millimeters, and seating for five occupants; they bridge passenger car efficiency with utility vehicle cargo flexibility for suburban and urban duty cycles. Crossover configurations dominate volume sales due to car-like ride quality and lower step-in height, while electric powertrains represent the fastest-expanding engine category as battery costs decline and charging infrastructure proliferates. All-wheel-drive variants command higher transaction prices and margin pools in snowy or mountainous markets.
The EPA Corporate Average Fuel Economy standards and the EU F-Gas Regulation on mobile air conditioning refrigerants shape powertrain development timelines and thermal system design across export programs. China's MIIT new-energy vehicle credit system and India's BIS safety crash-test protocols further fragment homologation requirements for multinational platforms. Stakeholders must monitor how divergent emissions compliance calendars across Washington, Brussels, and Beijing force regional product differentiation rather than global commonality.
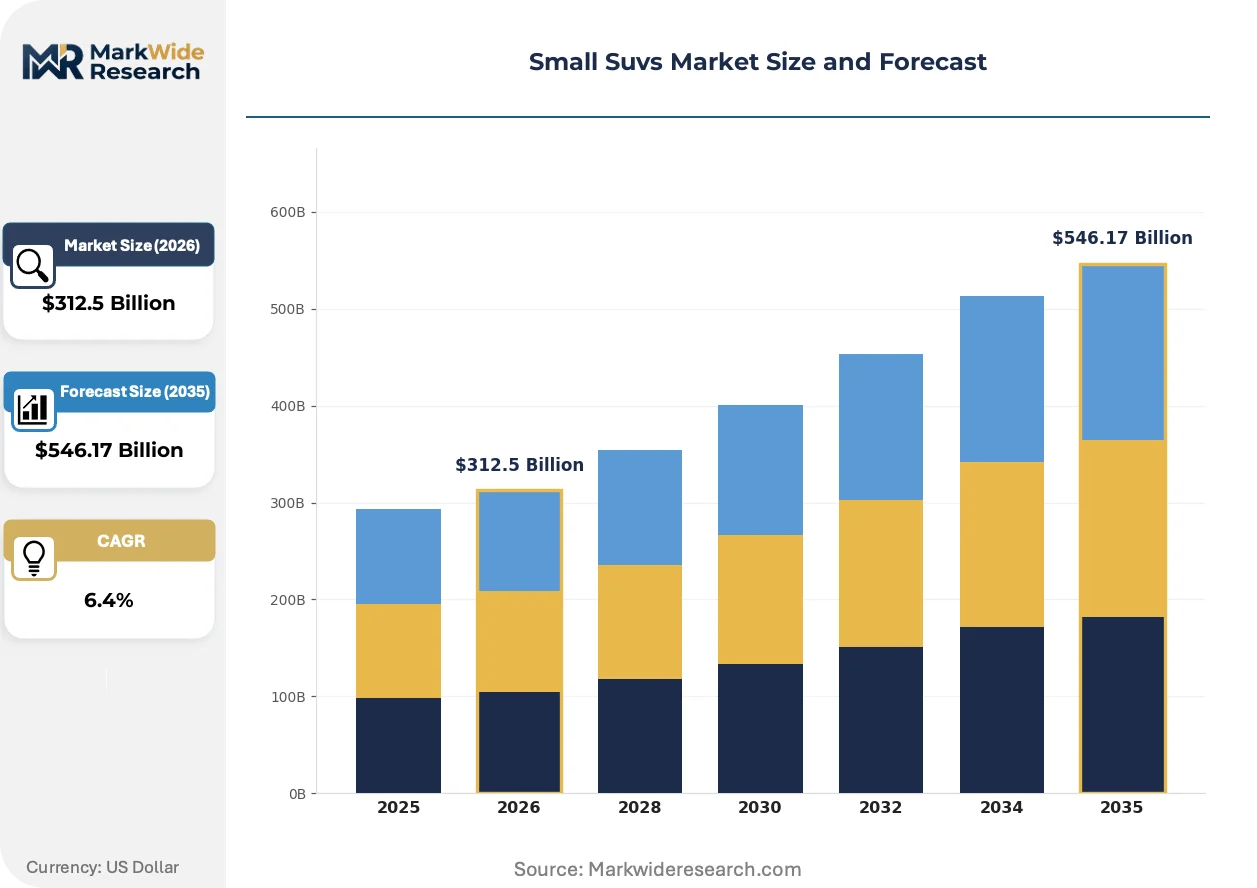
Market Dynamics
Aluminum-intensive body structures and battery-electric powertrains are compressing traditional platform economics as manufacturers redesign unibody architectures to accommodate dual energy-storage layouts and lighter stamped panels simultaneously.
Growth Catalysts
- EU F-Gas Regulation:Mobile air conditioning refrigerant phase-down rules accelerate thermal system redesigns that favor heat-pump-equipped small SUVs with lower greenhouse-gas leakage profiles.
- First-time SUV buyers in China:Domestic joint ventures capture volume through localized electrified platforms priced beneath import tariffs, expanding addressable household penetration.
- Heat-pump thermal management:Cold-climate range preservation technology enables battery-electric small SUVs to compete in Scandinavian and Canadian markets previously dominated by internal combustion.
Market Restraints
- Lithium carbonate volatility:Battery cell input cost swings compress margin visibility for electric powertrain variants below the 50 kWh threshold.
- Semiconductor foundry concentration:Taiwan and South Korea supply concentration creates exposure for powertrain control module availability across just-in-time assembly schedules.
- Homologation fragmentation:Divergent EPA, EU F-Gas, and MIIT compliance calendars force platform divergence rather than scale economies on single global architectures.
Strategic Opportunities
- India BIS safety protocols:Upcoming crash-test mandates create first-mover advantage for manufacturers pre-homologating compact SUVs to exceed structural rigidity minimums.
- Subscription-based feature activation:Over-the-air monetization of heated seats, advanced driver-assistance, and battery preconditioning creates recurring revenue streams detached from initial transaction prices.
- Vehicle-to-grid integration:Bidirectional charging capability converges with residential solar installations, positioning small electric SUVs as distributed energy assets in California and Germany.
Industry Challenges
- Software-defined vehicle integration:Legacy tier-one supplier relationships conflict with in-house operating system development, creating contractual friction over intellectual property ownership.
- Skilled battery technician scarcity:High-voltage certification programs lag deployment volumes, constraining dealer service throughput for warranty and collision repair.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Suvs Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $546.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compact SUV, Crossover, Mini SUV, Subcompact SUV Engine Type: Gasoline, Diesel, Hybrid, Electric Transmission: Automatic, Manual, CVT, Dual-Clutch Drive Type: AWD, FWD, RWD, 4WD |
| Companies Covered | Toyota, Honda, Ford, Hyundai, Kia, Chevrolet, Nissan, Volkswagen, Subaru, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Suvs Market Strategic Shifts & Innovations
Powertrain electrification and software-defined architectures are collapsing the traditional boundary between automotive and consumer electronics supply chains, forcing new competency acquisition in semiconductor sourcing and cloud infrastructure.
Cell-to-pack battery architectures are expanding into small SUV segments previously limited to modular designs. Korean and Chinese cell suppliers now deliver integrated floor pan assemblies directly to assembly plants, compressing pack assembly labor and improving volumetric energy density. This integration is expanding into cost-sensitive segments by eliminating redundant module housings and cooling hardware.
California's Advanced Clean Cars II regulation mandates zero-emission vehicle sales thresholds that cascade through 2035, compelling powertrain portfolio reallocation toward battery-electric and fuel-cell variants. Manufacturers serving the US West Coast must now engineer thermal management and charging compatibility for extreme heat and altitude conditions rarely encountered in European homologation cycles.
Fleet procurement departments now specify total cost of ownership metrics that depreciate residual value risk and charging infrastructure investment alongside sticker prices. Corporate and rental buyers in Germany and the Netherlands increasingly source small electric SUVs through mobility-as-a-service contracts that bundle maintenance, insurance, and energy, displacing traditional three-year lease structures with usage-based alternatives.
Small Suvs Market Segmentation
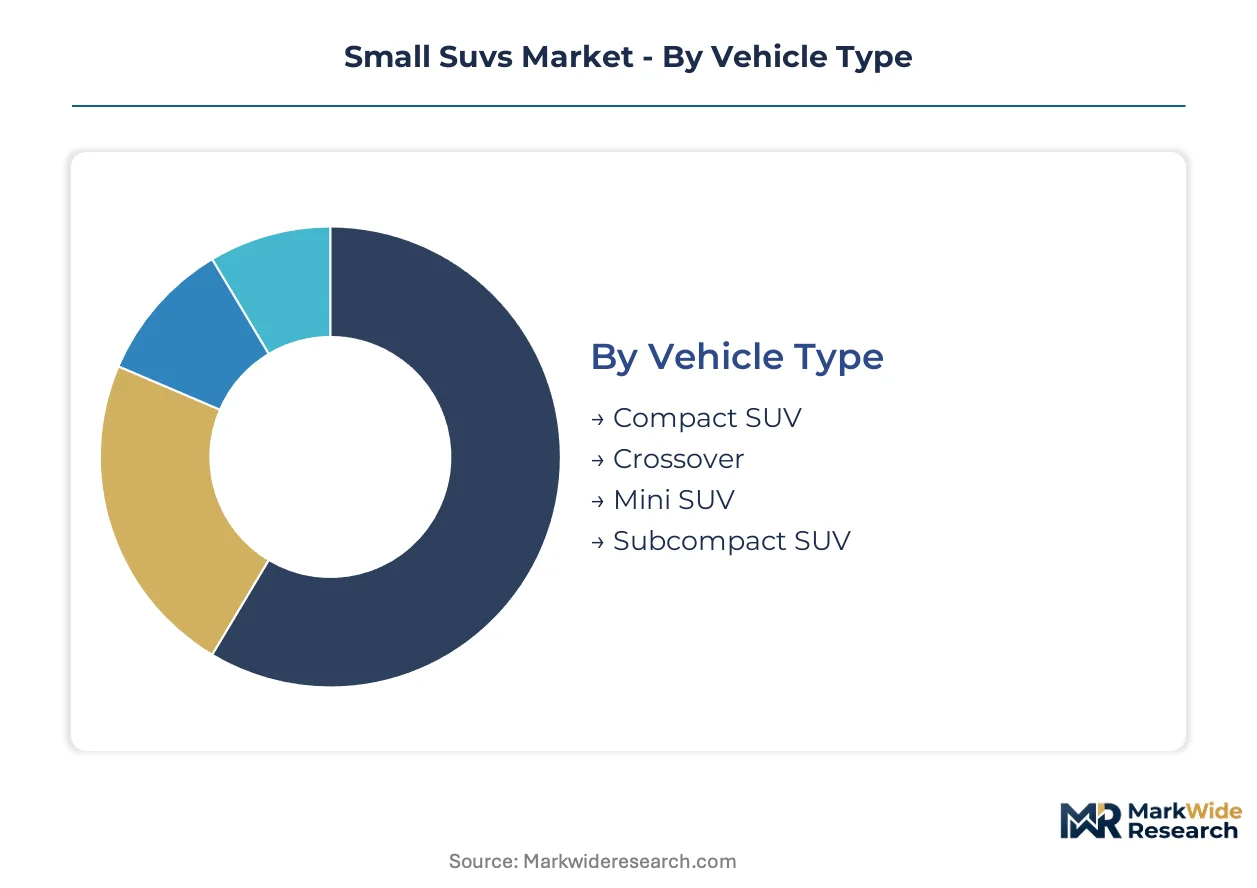
Segmentation in the Small SUVs Market reveals how manufacturers balance unibody platform economics against divergent powertrain and drivetrain configurations demanded by distinct duty cycles and regulatory environments.
Vehicle Type:
Supply concentration in crossover stamping capacity has tilted assembly plant allocation toward car-derived architectures that share supplier tooling with sedan programs.
- Crossover:Unibody construction with car-like ride height and lower center of gravity dominates suburban household penetration in the United States and Germany. Toyota and Ford anchor production scale here, capturing volume through shared platforms with mid-size sedans.
- Compact SUV:Slightly elevated ground clearance and boxier proportions serve fleet procurement in Canada and Scandinavia where snow-belt utility commands premium pricing. Heat-pump thermal management is becoming standard specification.
- Mini SUV:Sub-four-meter lengths target congested urban centers in India and Japan with tax-advantaged footprint regulations.
- Subcompact SUV:Entry pricing beneath compact segments attracts first-time SUV buyers in China through domestic joint venture production.
Today's leader: Crossover. Tomorrow's challenger: Compact SUV.
Engine Type:
Cost tier stratification separates powertrain portfolios, with battery-electric variants commanding upstream cell supply commitments that compress margin pools below the 50 kWh threshold.
- Electric:Cell-to-pack architectures from Korean and Chinese suppliers now integrate directly into floor pan assemblies, eliminating module housings and improving volumetric energy density for California and EU compliance markets.
- Hybrid:Toyota's dual-motor planetary gear systems anchor premium pricing across North American and Japanese lineups, leveraging two decades of thermal management refinement.
- Gasoline:Downsized turbocharged three- and four-cylinder engines retain volume share in markets with sparse charging infrastructure.
- Diesel:Compression-ignition variants concentrate in Indian and European fleet procurement where highway fuel economy drives total cost of ownership calculations.
Electric variants are gaining share fastest in markets with zero-emission mandates; hybrid systems retain margin leadership where charging infrastructure remains underdeveloped.
Transmission:
Application-specific torque delivery requirements shape supplier concentration, with CVT specialists and dual-clutch module producers competing for platform integration contracts.
- Automatic:Conventional torque-converter units dominate towing-specification small SUVs in the United States and Australia, preserving durability margins for boat and trailer duty cycles.
- CVT:Steel-belt continuously variable transmissions from Japanese suppliers optimize fuel economy certification in China and Japan where urban congestion dominates test cycles.
- Dual-Clutch:Wet-clutch DCT modules serve performance-oriented European variants with rapid shift timing.
- Manual:Three-pedal configurations retain niche share in Indian and Eastern European markets with cost-sensitive entry segments.
Automatic transmissions hold current volume leadership; CVT systems present the steepest expansion trajectory in hybrid-electric powertrain pairings.
Drive Type:
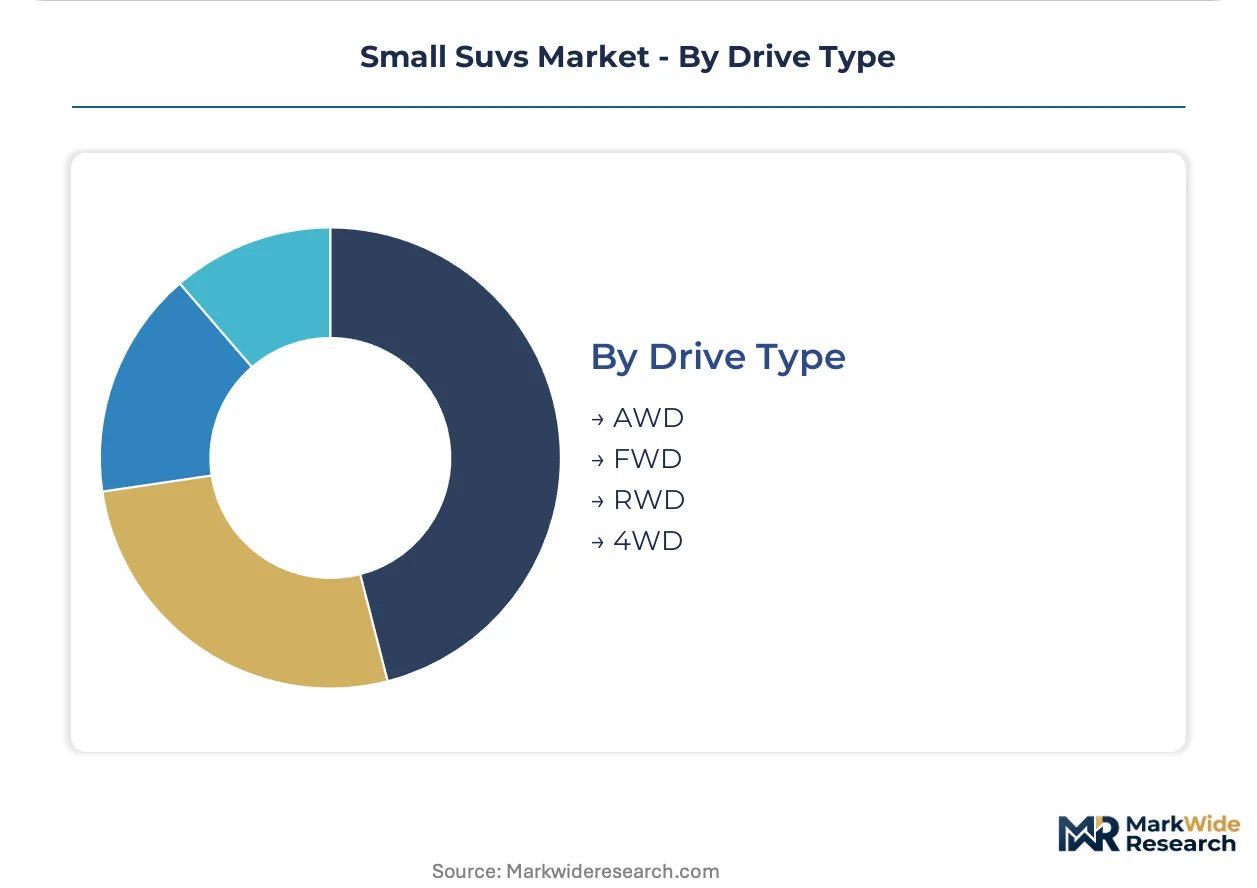
Customer type and geography jointly determine drivetrain specification, with all-wheel-drive variants capturing margin premiums in snow-belt and mountainous markets.
- AWD:On-demand torque-vectoring systems from BorgWarner and Magna command higher transaction prices in Colorado, Norway, and the Alps where traction confidence drives purchase decisions.
- FWD:Transverse-engine front-drive architectures minimize weight and cost for Sun Belt American and Mediterranean European urban operators where snow exposure is minimal.
- 4WD:Part-time four-wheel-drive with low-range gearing serves off-road recreation segments in Utah, Morocco, and Australian outback markets.
- RWD:Longitudinal rear-drive layouts concentrate in performance-tuned variants from BMW and Mercedes-AMG targeting enthusiast segments.
Front-wheel-drive retains cost-optimized volume leadership; all-wheel-drive variants are climbing fastest in electrified platforms where dual-motor torque distribution replaces mechanical differentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit-Windsor automotive corridor anchors small SUV engineering and assembly for North American distribution networks. Regional production clusters specialize in unibody platform manufacturing with integrated electrification capabilities.
United States
California's Advanced Clean Cars II regulation mandates escalating zero-emission vehicle sales thresholds through 2035. Michigan and Ohio assembly plants retool for dual-energy architectures serving West Coast compliance markets. Ford anchors Bronco Sport and Escape production in Louisville, Kentucky with truck-derived design differentiation.
Germany
Corporate fleet procurement through mobility-as-a-service contracts displaces traditional leasing in the Netherlands-bordering Rhine-Ruhr industrial zone. EU F-Gas Regulation on mobile air conditioning refrigerants forces thermal system redesigns favoring heat-pump integration. Volkswagen Group concentrates crossover development in Wolfsburg with premium-mid-economy pricing stratification across Audi, VW, and SEAT marques.
China
First-time SUV buyers in tier-two cities drive volume through domestic joint venture platforms priced beneath import tariffs. MIIT new-energy vehicle credit system forces powertrain portfolio reallocation toward battery-electric variants. BYD and GAC anchor production in Guangzhou and Shenzhen with cell-to-pack battery integration from Korean and Chinese suppliers.
Japan
Hybrid powertrain retention dominates where charging infrastructure remains underdeveloped in rural Honshu prefectures. METI carbon neutrality roadmaps accelerate solid-state battery research timelines. Toyota leverages dual-motor planetary gear systems from Tsutsumi and Tahara plants to anchor premium pricing across compact formats.
India
Sub-four-meter mini SUVs exploit tax-advantaged footprint regulations in Maharashtra and Gujarat manufacturing zones. BIS safety crash-test protocols create first-mover structural rigidity requirements for export programs. Tata Motors and Mahindra pre-homologate compact SUVs in Pune and Nashik for domestic and African market distribution.
Small Suvs Market Key Industry Players
Platform diversification dominates the current landscape as manufacturers redesign unibody architectures for dual energy-storage layouts. The vendor base separates into three tiers: full-line global OEMs with captive hybrid systems, regional specialists with cost-optimized local platforms, and emerging electric-native challengers with direct-to-consumer distribution. Consolidation pressure concentrates among mid-scale players lacking battery cell supply commitments. Capacity expansion and strategic partnerships represent the dominant competitive vectors for securing cell supply and thermal management technology.
Within the full-line global tier, Toyota Motor Corporation and Ford Motor Company exemplify divergent electrification strategies. Toyota anchors hybrid architecture leadership with two decades of thermal management refinement, while Ford sustains North American production scale through truck-derived design language. Hyundai Motor Group occupies a position between these archetypes with integrated battery-electric and fuel-cell development from South Korean engineering centers.
| Leading Market Players |
|---|
| Toyota |
| Honda |
| Ford |
| Hyundai |
| Kia |
| Chevrolet |
| Nissan |
| Volkswagen |
| Subaru |
| Others |
Cost & Logistics Intelligence
Cell-to-pack battery integration is compressing module assembly labor while simultaneously concentrating tier-one supplier leverage in Korean and Chinese cell manufacturers. This production-method transition simultaneously reshapes cost economics and supply concentration as OEMs surrender pack integration margins to upstream cell suppliers with direct floor-pan delivery capabilities.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility dominates margin visibility for electric powertrain variants below the 50 kWh threshold. Three-tier pricing structure across premium, standard, and economy levels separates heat-pump-equipped variants from base thermal management and fleet-specification units. Cost compression in entry segments is intensifying because domestic joint ventures in China price beneath import tariff floors. Fleet procurement departments exhibit lowest price sensitivity due to total cost of ownership calculations, while first-time retail buyers in tier-two Chinese cities drive highest discount pressure.
Supply Chain Analysis
China's MIIT domestic-content mandates for new-energy vehicle credits are reshaping sourcing patterns toward localized cell and thermal component production. Supply concentrates in China, South Korea, and Japan for battery cells, with Germany and Mexico anchoring stamping and assembly capacity. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare-earth permanent magnets for electric drivetrains. Single-source vulnerability from Taiwan and South Korea semiconductor foundry concentration creates exposure for powertrain control modules. Distribution runs through regional assembly plants with just-in-time supplier park co-location.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Small SUVs Market reads as a late-cycle quality story as urban households in North America and Europe trade up to heat-pump-equipped and all-wheel-drive specifications. This demand-shift toward premium thermal and traction capabilities justifies selective capacity investment despite volume commoditization at entry tiers.
For Market Incumbents: To counter margin compression from Chinese domestic joint ventures, anchor hybrid architecture leadership through captive thermal management refinement and secure cell supply via long-term offtake agreements with Korean suppliers. Prioritize platform standardization across crossover and compact formats to amortize electrification development costs. For New Entrants and Emerging Players: Solid-state battery research partnerships represent a technology-first wedge into premium segments where incumbents carry legacy pack assembly infrastructure. Target India's BIS pre-homologation window for compact SUV structural rigidity certification. Pursue direct-to-consumer distribution in California and Germany where zero-emission mandates accelerate adoption velocity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists lacking battery cell supply commitments but holding homologated platforms for African and Southeast Asian export markets. Five-to-ten-year viability hinges on securing thermal management technology access. Monitor cell-to-pack adoption rates as inflection indicator for supplier leverage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtakes with Korean suppliers anchor margin visibility for EU and California compliance variants. |
| Software-Defined Vehicle Investment | In-house operating system development reduces tier-one supplier IP friction and enables subscription revenue streams. |
| Platform Standardization | Unibody architecture sharing between crossover and compact formats amortizes electrification R&D across higher volumes. |
| Geographic Manufacturing Footprint | Assembly plant placement in Michigan, Guangzhou, and Wolfsburg optimizes regional homologation and tariff exposure. |
| Charging Infrastructure Partnership | Bidirectional vehicle-to-grid integration with residential solar installers positions electric SUVs as distributed energy assets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, thermal management specialists, and dealership operations heads with secondary validation from vehicle production databases, IHS Markit registration data, EPA certification filings, and EU F-Gas regulatory disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Comparable-period anchoring to historical production and registration data established baseline trajectory calibration across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, drivetrain configuration, and regional production cluster. CAGRs were derived from trend extrapolation adjusted for regulatory compliance phase-in schedules and battery cost decline curves. Forecast inputs incorporated MIIT credit system thresholds and California ACC II mandate cascades.
The model holds under stable lithium carbonate supply and continued semiconductor foundry capacity expansion; deviation in trade policy or raw material nationalization would shift electric powertrain penetration timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Train Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Train Seat Market