
 North American Lightweight Car Market | 2026-2036
North American Lightweight Car Market Size, Share, and Industry Trends Forecast 2026-2036
North American Lightweight Car Market Analytics
Dealer networks and direct-to-consumer digital platforms are reshaping how lightweight cars reach buyers across North America. Ford Motor Company leverages its vertically integrated aluminum supply chain to control costs on F-150 and Mustang variants. General Motors competes through proprietary Ultium battery architecture that reduces platform weight for electric sedans. Honda Motor Co., Ltd. anchors its North American position with high-strength steel and aluminum hybrid structures manufactured in Ohio.
A lightweight car integrates advanced materials and structural optimization to achieve curb weights substantially below segment averages, typically employing aluminum-intensive body structures, carbon fiber reinforced panels, or magnesium powertrain components to improve fuel efficiency and handling dynamics. The primary purpose centers on regulatory compliance with fuel economy mandates while preserving safety performance and passenger comfort. Material composition segments reveal aluminum dominating current production volumes due to established stamping infrastructure, while carbon fiber concentrates in luxury and sports variants where margin pools remain deepest. Electric powertrains within the power source category are accelerating fastest as battery mass penalties create urgent demand for compensatory weight reduction elsewhere in vehicle architecture.
The EPA enforces Corporate Average Fuel Economy standards that tighten fleet-wide efficiency requirements, compelling OEMs to adopt lightweighting across all vehicle types. NHTSA crashworthiness protocols and California Air Resources Board zero-emission mandates together shape material selection and powertrain portfolios available to North American consumers. Stakeholders must monitor how forthcoming EPA rulemakings and potential state-level regulatory divergence between California and federal standards alter platform development timelines and supplier qualification requirements.
Market Dynamics
Aluminum-intensive body architectures are forcing a wholesale reconfiguration of North American stamping capacity as OEMs retool legacy steel lines to handle higher-grade alloys and thinner-gauge panels.
Growth Catalysts
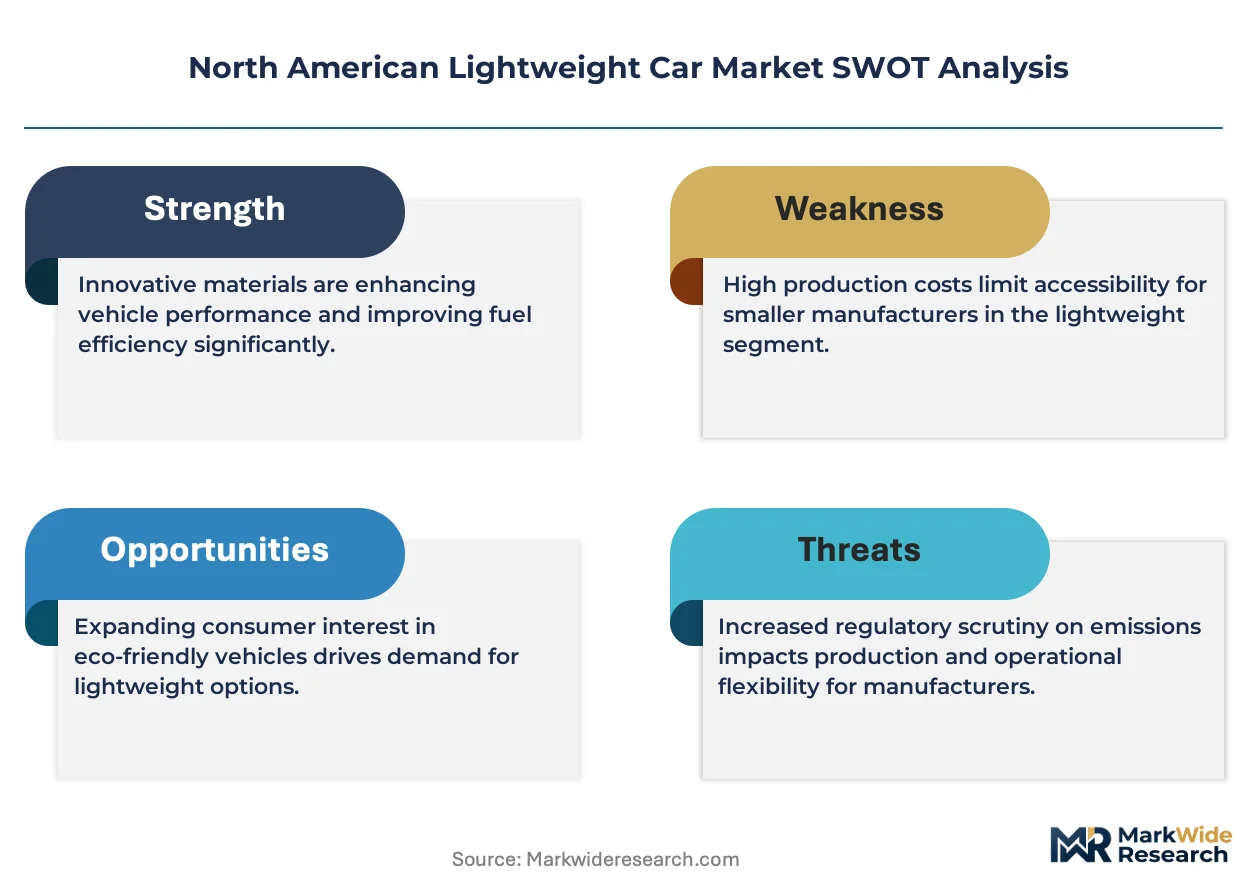
- EPA Corporate Average Fuel Economy standards:Fleet-wide efficiency mandates compel manufacturers to shed vehicle mass across all segments, creating sustained pull for advanced materials.
- Great Lakes manufacturing corridor concentration:Proximity of Tier-1 stamping and casting suppliers to Detroit, Cleveland, and Windsor assembly plants reduces logistics friction for lightweight component delivery.
- Multi-material joining technologies:Friction stir welding and structural adhesives enable hybrid aluminum-steel architectures previously unmanufacturable at scale.
Market Restraints
- Primary aluminum price volatility:Midwest spot premiums and LME pricing swings compress margin predictability for body-in-white programs committed years ahead of production.
- Carbon fiber precursor supply concentration:Acrylonitrile and PAN fiber production clusters in Texas and South Carolina create single-point vulnerability for luxury segment panels.
- NHTSA crashworthiness protocol complexity:Offset frontal and side-pole testing requirements limit how aggressively mass can be removed from critical load paths without redesign.
Strategic Opportunities
- Mexico assembly expansion:New capacity in Aguascalientes and San Luis Potosí offers tariff-advantaged export platforms for lightweight compact cars bound for US markets.
- Battery enclosure aluminum extrusions:Electric skateboard platforms demand novel hollow-profile structures that merge crash management with thermal protection.
- California Air Resources Board zero-emission mandates:ZEV credit banking and pooling mechanisms subsidize lightweighting investments that extend electric range.
Industry Challenges
- Multi-material repair certification gaps:Collision shops lack trained technicians and OEM-authorized equipment to service aluminum-intensive structures, depressing residual values.
- Die tryout and formability simulation:High-strength aluminum grades exhibit springback behavior that defies legacy stamping simulation software, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North American Lightweight Car Market |
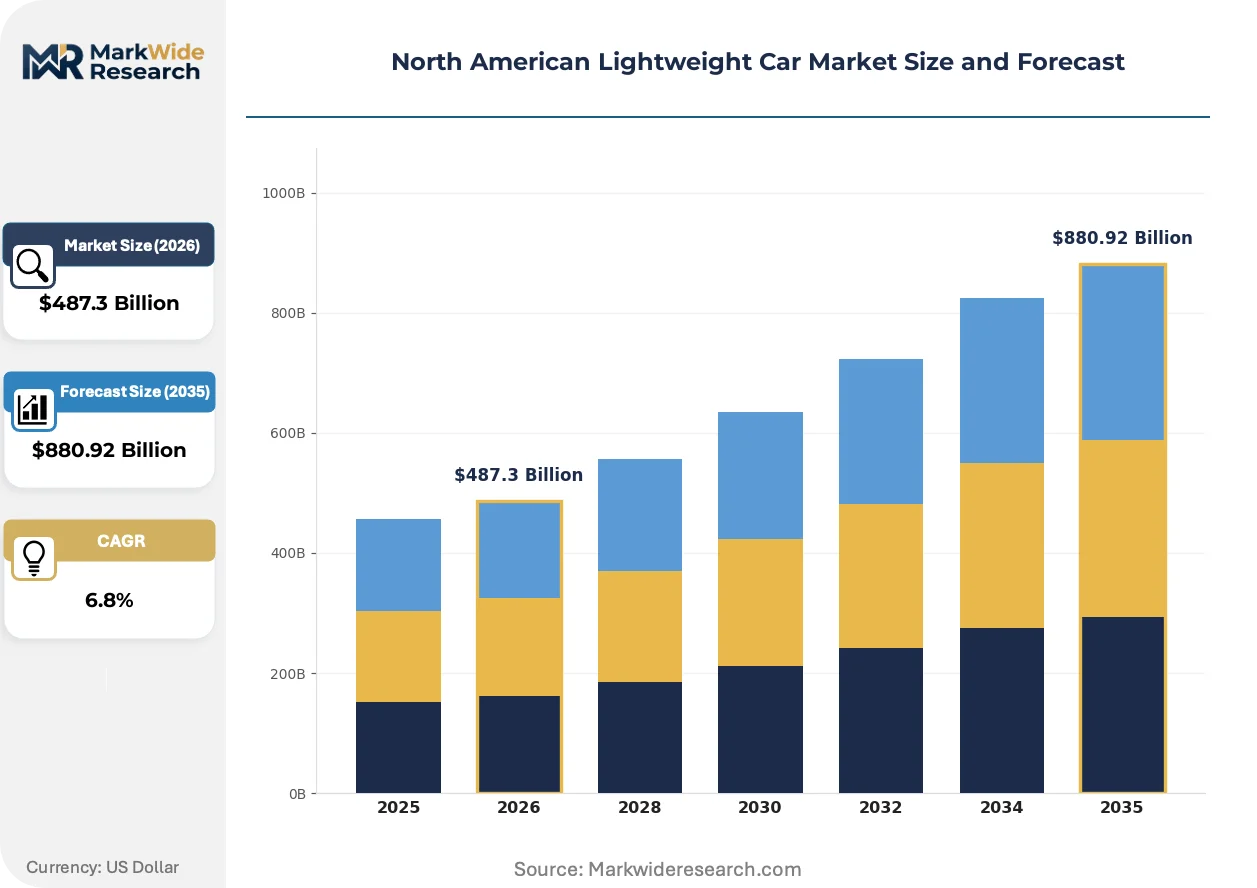
| Market Size in 2026 | $487.3 Billion |
| Market Size in 2035 | $880.92 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Coupes, Sedans, Hatchbacks, Convertibles Material Composition: Aluminum, Carbon Fiber, Magnesium, Composites Power Source: Gasoline, Diesel, Hybrid, Electric Market Segment: Luxury, Economy, Sports, Compact |
| Companies Covered | Ford Motor Company, Honda Motor Co., Ltd., General Motors, Toyota Motor Corporation, Nissan Motor Co., Ltd., Mazda Motor Corporation, Chevrolet, Volkswagen AG, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North American Lightweight Car Market Evolving Landscape
Digital thread integration from alloy specification through vehicle assembly is compressing development timelines while enabling real-time mass tracking against regulatory targets.
Hot-stamped boron-aluminum hybrid blanks are collapsing the mass penalty historically associated with structural reinforcements in B-pillars and roof rails. Tier-1 suppliers in Ohio and Michigan are qualifying these tailored blanks for 2027 platform launches. The technology is collapsing the trade-off between occupant protection and weight reduction that has constrained sedan architectures for two decades.
The EPA's pending light-duty vehicle greenhouse gas standards for model years 2027-2032 tighten fleet-average CO2 limits by approximately one-third from current levels. OEMs must deploy mass reduction at scale rather than relying solely on powertrain efficiency gains. Full-size pickup and SUV segments face the steepest compliance burden, accelerating aluminum closure panel adoption beyond current penetration rates.
Fleet procurement departments are consolidating lightweight vehicle sourcing through direct manufacturer agreements that bypass traditional dealer networks. Corporate sustainability officers in logistics and rental verticals now specify curb weight thresholds in RFPs alongside fuel economy. This concentration is most visible in California and Washington state, where state fleet electrification mandates intersect with corporate Scope 3 emission reduction commitments.
North American Lightweight Car Market Segmentation
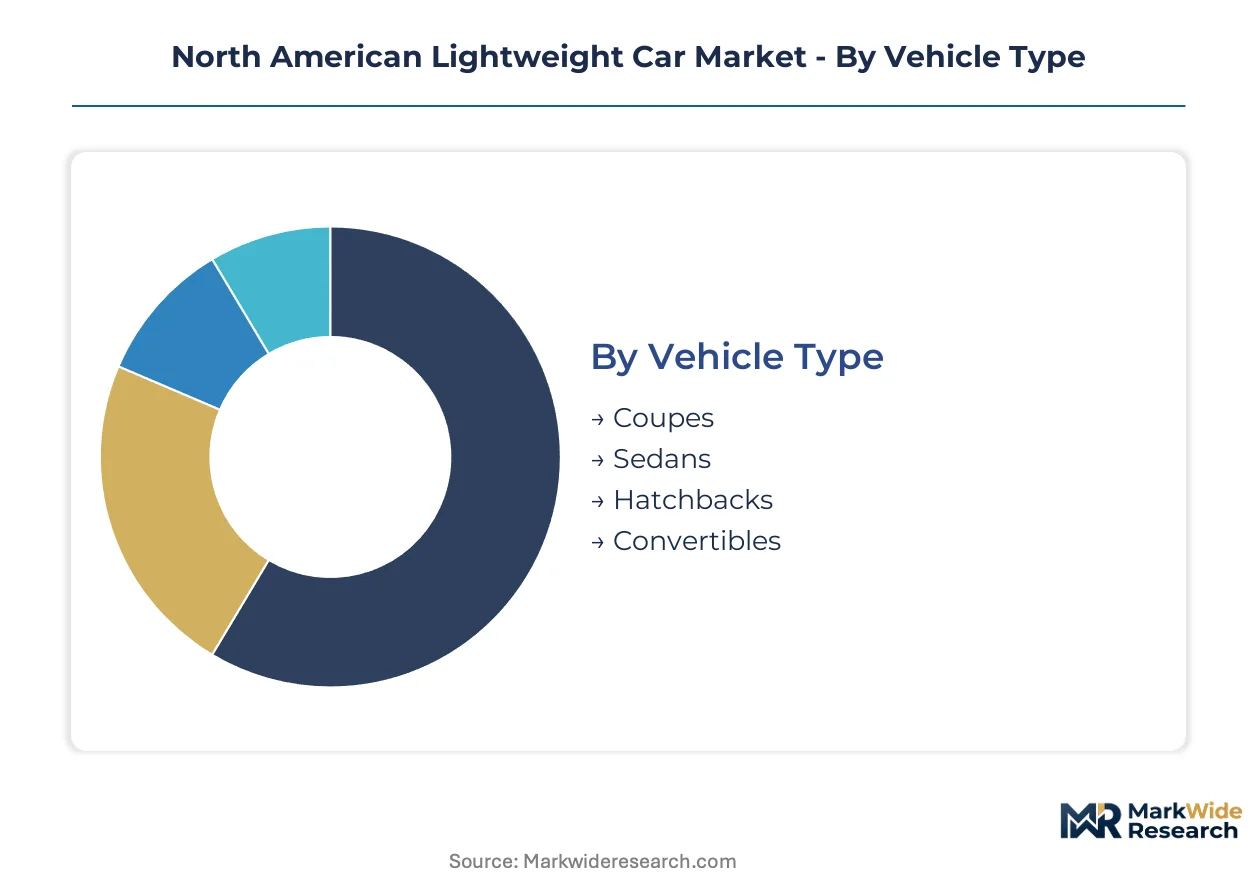
Lightweight car segmentation reveals how material choices, powertrain strategies, and price positioning intersect with regulatory pressure across the United States and Canada. Understanding these dimensions helps stakeholders allocate engineering resources and procurement budgets against compliance deadlines.
Vehicle Type:
Body style selection determines the mass reduction potential and aerodynamic efficiency targets that shape platform engineering priorities.
- Sedans:Three-box architectures dominate corporate fleet procurement in Michigan, Ohio, and Ontario, where EPA fuel economy mandates concentrate demand for aluminum-intensive unibody structures that preserve trunk capacity while cutting curb weight.
- Hatchbacks:Two-box designs with integrated cargo areas attract urban buyers in California and Washington state, where ZEV credit mechanisms and parking constraints favor compact footprints combined with electric powertrain packaging efficiency.
- Coupes:Fixed-roof two-door variants serve enthusiast segments with stiffer chassis structures that exploit weight savings for handling gains rather than fuel economy alone.
- Convertibles:Retractable roof mechanisms impose structural mass penalties that demand compensatory material upgrades, limiting volume to premium price tiers.
Established volume favors sedans; emerging adoption favors hatchbacks.
Material Composition:
Cost tiers separate mass-production feasibility from performance-premium positioning across stamping and casting supply chains.
- Aluminum:5xxx and 6xxx series alloys dominate body-in-white production through established Great Lakes corridor stamping infrastructure, with Ford's F-150 and Mustang programs proving scale viability for closure panels and structural nodes.
- Carbon Fiber:PAN-based prepreg systems concentrate in luxury sports variants where Texas and South Carolina precursor supply feeds autoclave-cured panels, with repair network limitations constraining residual value and volume expansion.
- Magnesium:AZ91D and AM60B alloys reduce powertrain and interior component mass through high-pressure die casting, though corrosion protection requirements limit exterior applications.
- Composites:Glass-reinforced thermoplastics and SMC formulations serve non-structural panels where cost sensitivity excludes aluminum or carbon fiber solutions.
Cost efficiency favors aluminum; performance differentiation favors carbon fiber.
Power Source:
Application urgency varies by how battery mass penalties and thermal management requirements reshape lightweighting priorities.
- Electric:Skateboard platforms demand compensatory mass reduction in body structures to offset battery pack weight, with General Motors' Ultium architecture illustrating how proprietary cell-to-pack designs interact with aluminum enclosure extrusions.
- Hybrid:Dual-powertrain packaging constraints favor high-strength steel and aluminum hybrid structures that protect high-voltage components while maintaining crashworthiness.
- Gasoline:Internal combustion efficiency gains from reduced rolling mass and improved power-to-weight ratios sustain demand in price-sensitive segments.
- Diesel:Compression-ignition variants retain niche presence in highway-focused applications where torque density and thermal efficiency justify higher powertrain mass.
Technology transition favors electric; infrastructure maturity favors gasoline.
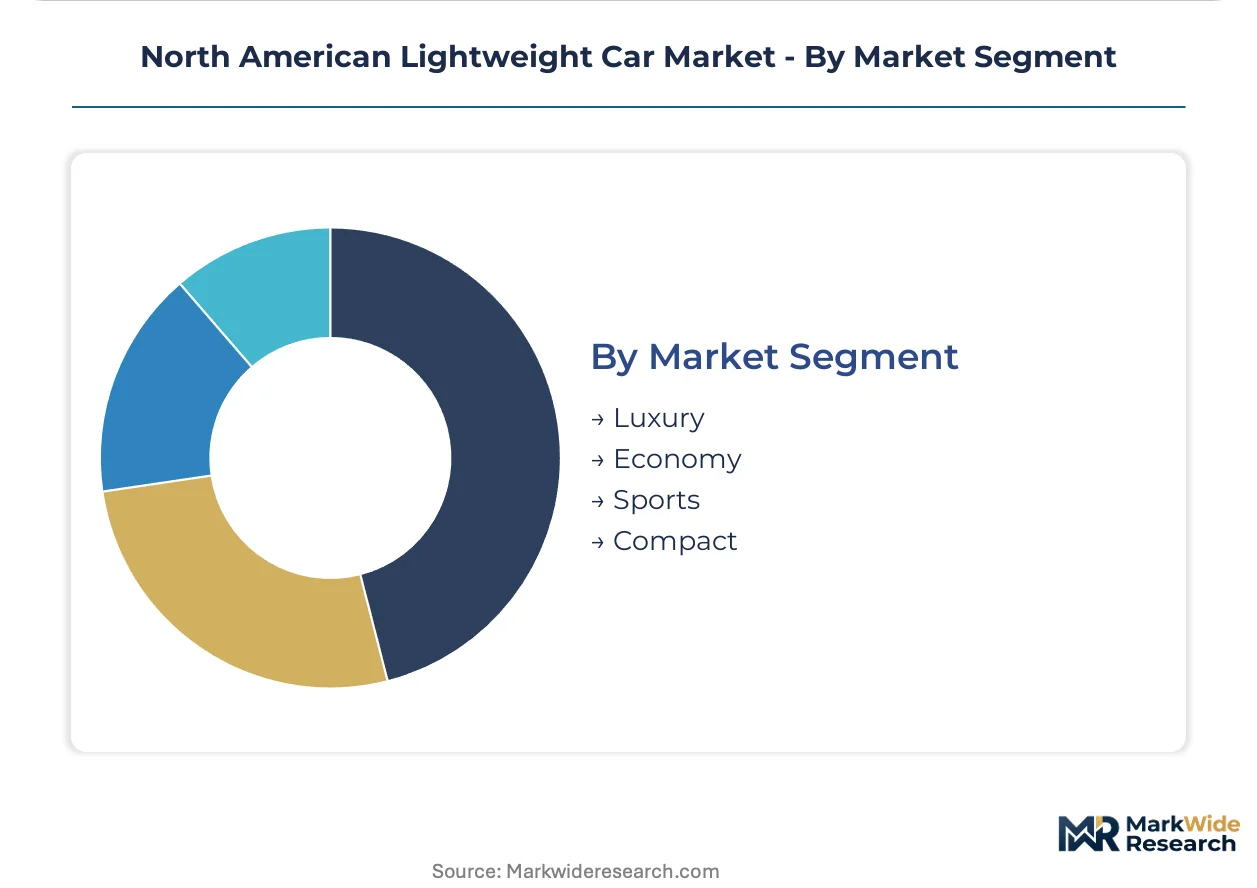
Market Segment:
Customer type and margin structure determine how aggressively OEMs deploy advanced materials against price elasticity limits.
- Luxury:Price-insufficient buyers absorb carbon fiber and magnesium content that would destroy margins in mass-market applications, with California and Washington state accounting for disproportionate share of flagship sedan and SUV variants.
- Compact:Entry-level positioning constrains material selection to aluminum and high-strength steel, though EPA fleet averaging compels meaningful mass reduction even at low price points.
- Sports:Performance credibility depends on power-to-weight ratios that justify exotic material investments regardless of volume economics.
- Economy:Thin margins limit lightweighting to high-volume aluminum stampings and strategic component substitution rather than architecture-level redesign.
Margin depth favors luxury; regulatory compliance favors compact.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor rail tunnel and Ambassador Bridge corridor handles over $400 billion in annual automotive trade, underwriting North America's lightweight vehicle production network. This infrastructure connects Great Lakes stamping capacity to Mexican assembly plants and Canadian aluminum smelters.
United States
Fleet electrification mandates in California and Washington state drive aluminum-intensive platform procurement. EPA Corporate Average Fuel Economy standards tighten through 2032, compelling Detroit automakers to shed mass. The Michigan-Ohio manufacturing corridor concentrates Tier-1 stamping suppliers serving aluminum body-in-white programs.
Canada
Ontario assembly plants export lightweight sedans under USMCA tariff preferences. Quebec's aluminum smelters supply primary metal to Great Lakes automotive stamping operations. The Windsor-Detroit production cluster integrates Canadian extrusion capacity with Michigan vehicle assembly.
Mexico
Aguascalientes and San Luis Potosí assembly capacity expands to serve US compact car demand. Mexican manufacturing platforms leverage labor cost advantages for lightweight vehicle export programs. The Bajío region attracts aluminum component suppliers co-locating with OEM final assembly.
North American Lightweight Car Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying materials and joining technologies. The market exhibits moderate consolidation among full-line OEMs with fragmented specialty material suppliers. Three archetypes dominate: vertically integrated aluminum processors, multi-material architecture developers, and electric skateboard platform specialists. Competitive intensity centers on captive supply chain control and regulatory compliance speed.
Among Detroit-based platform integrators, Ford Motor Company and General Motors occupy positions defined by aluminum body structure investments. Honda Motor Co., Ltd. exemplifies the hybrid-material approach with its Ohio manufacturing concentration. These three anchors represent distinct strategic postures on lightweighting investment timing and material portfolio breadth.
| Leading Market Players |
|---|
| Ford Motor Company |
| Honda Motor Co., Ltd. |
| General Motors |
| Toyota Motor Corporation |
| Nissan Motor Co., Ltd. |
| Mazda Motor Corporation |
| Chevrolet |
| Volkswagen AG |
| Hyundai Motor Company |
| Others |
Value Network & Pricing Analysis
Quebec's aluminum smelter concentration feeds directly into Great Lakes stamping operations, concentrating margin capture among integrated processors capable of tolling primary metal into body-in-white panels. This upstream geography locks pricing power with alloy processors in Ontario and Michigan who command premium terms from non-integrated assemblers in Mexico and the southern United States.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from retail transactions, with corporate buyers in California and Washington state extracting 12-18% reductions on aluminum-intensive sedan orders above 500 units. Price differentiation rests on certification grade for EPA compliance and geographic delivery cost to assembly plants. Cost compression in economy segments is intensifying because thin margins exclude architecture-level redesign. Fleet procurement departments demonstrate lowest price sensitivity; independent dealers in Texas and Florida face highest margin pressure.
Supply Chain Analysis
Upstream feedstock flows from Canadian primary aluminum smelters, Texas acrylonitrile precursor plants, and South Carolina PAN fiber facilities. The supply chain draws from high-grade bauxite ore, petroleum-based chemical feedstocks, and magnesium alloy ingots. Single-source vulnerability concentrates in carbon fiber precursor production clustered along the Gulf Coast. Distribution runs through the Detroit-Windsor rail corridor connecting Tier 1 stamping suppliers to final assembly across Michigan, Ohio, and Ontario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material tiers and powertrain architectures creates niche opportunities as fleet electrification mandates splinter demand specifications across state lines.
For Market Incumbents: Insulate aluminum body-in-white margins through backward integration into Quebec smelter capacity or tolling arrangements with Ohio extrusion specialists. Defensive consolidation around multi-material joining patents blocks emerging entrants from qualifying hybrid architectures for EPA fleet compliance. Priority rests on controlling 6xxx series alloy specification rights as NHTSA crashworthiness protocols tighten. For New Entrants and Emerging Players: Pursue battery enclosure aluminum extrusion contracts for electric skateboard platforms, where General Motors' Ultium architecture demonstrates unmet demand for hollow-profile crash management structures. White-space concentrates in Mexico assembly expansion serving California ZEV credit markets. Go-to-market positioning should emphasize thermal-protection-integrated structural components over commodity stamping. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive aluminum tolling capacity and OEM-qualified friction stir welding equipment. Long-term viability over the next decade hinges on regulatory compliance speed rather than scale economics. Watch for EPA rulemaking divergence between federal and California standards as the inflection signal for platform development timeline shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Joining Patent Acquisition | Friction stir welding IP from Ohio suppliers locks out competitors from hybrid aluminum-steel architectures. |
| Quebec Smelter Toll Agreement | Captive 6xxx series alloy supply insulates Ford and GM from LME price volatility in body-in-white programs. |
| Battery Enclosure Extrusion Capacity | Hollow-profile aluminum structures merge NHTSA crash management with thermal protection for Ultium-class platforms. |
| Mexico Assembly Footprint Expansion | Aguascalientes capacity leverages USMCA tariff advantages for lightweight compact exports to California fleet buyers. |
| Collision Shop Certification Network | OEM-authorized aluminum repair training preserves residual values for F-150 and Mustang variants in Texas markets. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier production schedules anchors the qualitative findings in this study. Primary interviews with body-in-white program managers, aluminum procurement directors at stamping operations, EPA regulatory affairs leads, and fleet sustainability officers combined with secondary validation from NHTSA crash test databases, EPA CAFE compliance filings, and IHS Markit vehicle production data. Bottom-up build from material content per vehicle and top-down triangulation against regional registration volumes ensured coverage consistency.
Calibration against historical platform development cycles and regulatory phase-in timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, material composition tier, powertrain architecture, and regional production cluster. CAGRs derived from regression analysis of aluminum content trajectories in sedan and hatchback segments, with electric powertrain penetration and EPA stringency indices as core forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum LME pricing, USMCA tariff enforcement, or California ZEV credit valuation would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timing and supplier qualification periods. Cross-checking against EPA proposed rulemaking comment filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Family Car Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Train Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Global SUV Market