
 Asia Pacific Luxury Cars Market | 2026-2036
Asia Pacific Luxury Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Luxury Cars Market Outlook
Subscription-based vehicle leasing and battery-as-a-service financing is reshaping competitive entry barriers across the Asia Pacific Luxury Cars Market. BMW leverages captive finance arms to lock in affluent repeat buyers across China's eastern seaboard. Mercedes-Benz anchors its position through vertically controlled retail networks in India and South Korea. Genesis differentiates via concierge ownership models that reduce upfront capital burdens for younger enterprise fleets.
Asia Pacific luxury cars encompass premium automobiles engineered with advanced powertrains, lightweight aluminum-intensive architectures, and cabin technologies exceeding baseline regulatory thresholds, serving status-driven mobility and chauffeured executive transport. SUVs dominate volume contribution due to ground clearance preferences across India's deteriorating urban road surfaces and Australia's rural estate access requirements. Electric technology segments capture disproportionate investment flow as MIIT production quotas in China and METI hydrogen corridor plans in Japan force powertrain portfolio rebalancing. Sedans retain residual strength in Japan's corporate reimbursement culture and South Korea's government procurement protocols.
China's MIIT enforces NEV credit mandates that compel luxury manufacturers to electrify model lineups, while India's BIS certification delays for imported EV components constrain launch velocity. Japan's METI coordinates charging infrastructure standards that determine market access feasibility for non-domestic premium brands. Stakeholders must calibrate powertrain portfolios against divergent national electrification timelines while preserving brand equity in combustion heritage segments.
Market Dynamics
China's MIIT NEV credit mandates are forcing luxury manufacturers to rebalance powertrain portfolios toward electrification while preserving combustion heritage equity in tier-one cities.
Growth Catalysts
- Dual carbon goals:China's MEE emissions targets compel fleet operators to accelerate electric vehicle procurement across Beijing, Shanghai, and Shenzhen metropolitan corridors.
- Subscription financing models:Battery-as-a-service structures reduce upfront capital burdens for younger enterprise buyers expanding chauffeured executive transport operations.
- SUV ground clearance preferences:India's deteriorating urban road surfaces and Australia's rural estate access requirements sustain disproportionate demand for elevated body architectures.
Market Restraints
- Import component certification delays:India's BIS clearance timelines for EV powertrain parts constrain launch velocity for non-domestic premium brands entering metropolitan markets.
- Charging infrastructure fragmentation:Japan's METI standard-setting process creates access feasibility barriers for European and Korean manufacturers lacking domestic partnerships.
- Aluminum-intensive architecture costs:Lightweight material processing expenses compress margin structures for low-volume heritage combustion variants.
Strategic Opportunities
- Hydrogen corridor alignment:Japan's METI infrastructure investments create white space for fuel-cell powertrain differentiation in executive fleet segments.
- Concierge ownership penetration:Vietnam and Indonesia's underdeveloped luxury retail networks enable direct-to-consumer channel innovation bypassing traditional dealer structures.
- Corporate reimbursement culture:South Korea's government procurement protocols sustain sedan residual demand against SUV volume dominance elsewhere.
Industry Challenges
- Powertrain engineering talent scarcity:Electric motor and solid-state battery specialists command premium compensation across China's eastern seaboard engineering clusters.
- Dual-platform capex intensity:Simultaneous combustion heritage maintenance and electrification ramp-up strains R&D allocation for mid-tier luxury portfolios.
- Retrofit integration complexity:Legacy dealership management systems resist seamless incorporation of battery health monitoring and over-the-air update architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Luxury Cars Market |
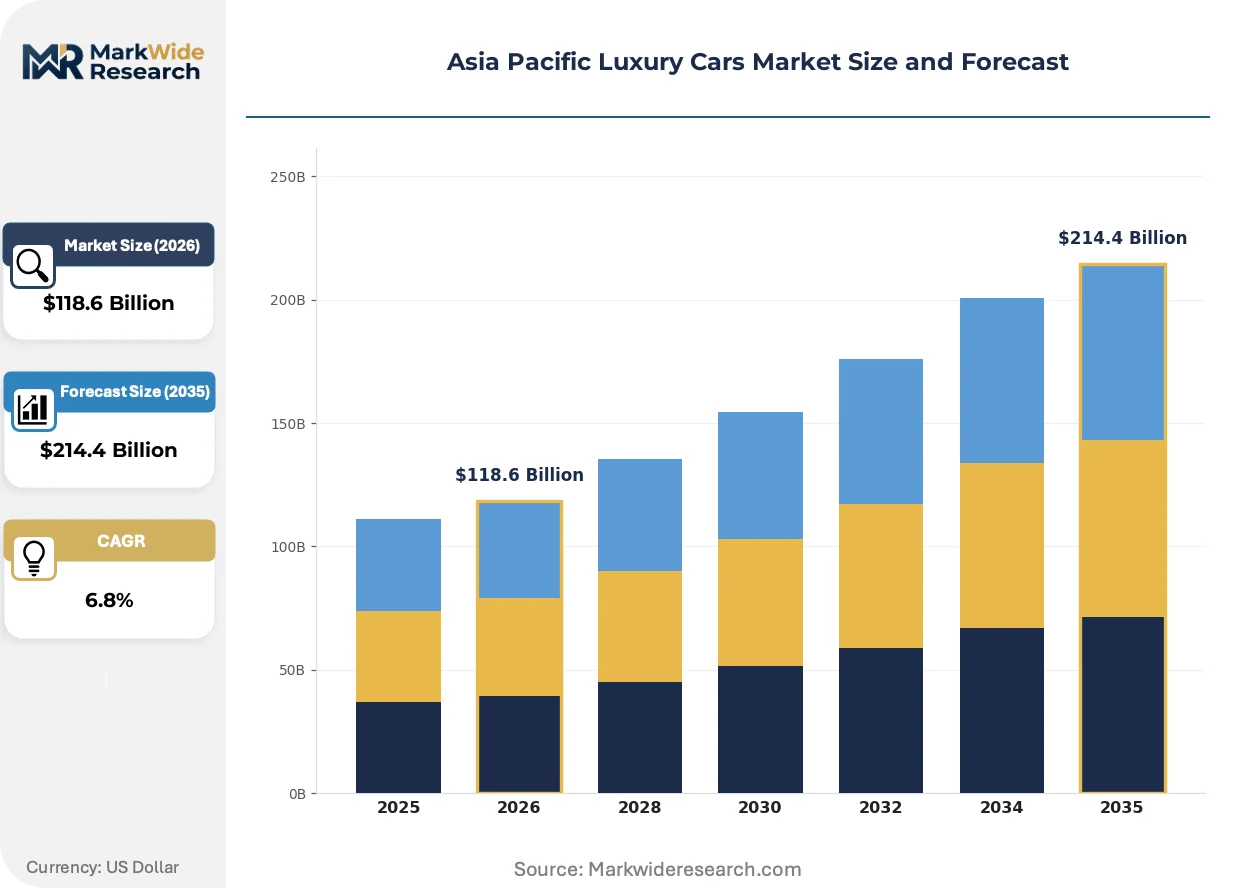
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Coupes, Convertibles End User: Affluent Individuals, Enterprises, Governmental Agencies, Personal Chauffeurs Technology: Hybrid, Electric, Internal Combustion, Autonomous Distribution Channel: Dealerships, Online Platforms, Auctions, Direct Sales |
| Companies Covered | Lexus, Genesis, Audi, Volvo, BYD, BMW, Jaguar Land Rover, Lamborghini, Mercedes-Benz, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Luxury Cars Market Strategic Shifts
Electrification mandates and ownership model experimentation are compressing traditional vehicle lifecycle economics while fragmenting distribution control across Asia Pacific luxury markets.
Solid-state battery chemistries with lithium-metal anodes and ceramic electrolytes are rendering obsolete liquid-cooled lithium-ion architectures in premium electric segments. Korean and Japanese battery suppliers are accelerating pilot production for 2026-2027 platform integration. This transition is compressing residual value horizons for incumbent nickel-cobalt-manganese cell investments.
China's MIIT NEV credit mandate enforcement tightens annually, compelling luxury manufacturers to maintain minimum electric sales ratios or purchase compliance credits from domestic pure-play competitors. The policy is accelerating powertrain portfolio rebalancing among German and Japanese heritage brands. Tier-one city dealerships are responding by consolidating floor space toward battery-electric demonstrators.
Enterprise fleet procurement teams are consolidating vehicle sourcing through captive finance arms rather than traditional outright purchase or operating lease structures. Subscription-based models with bundled maintenance and insurance are displacing conventional ownership in younger executive demographic segments. This behavioral shift is most visible across China's eastern seaboard technology corridor and India's Bangalore-Hyderabad metropolitan axis.
Asia Pacific Luxury Cars Market Segmentation
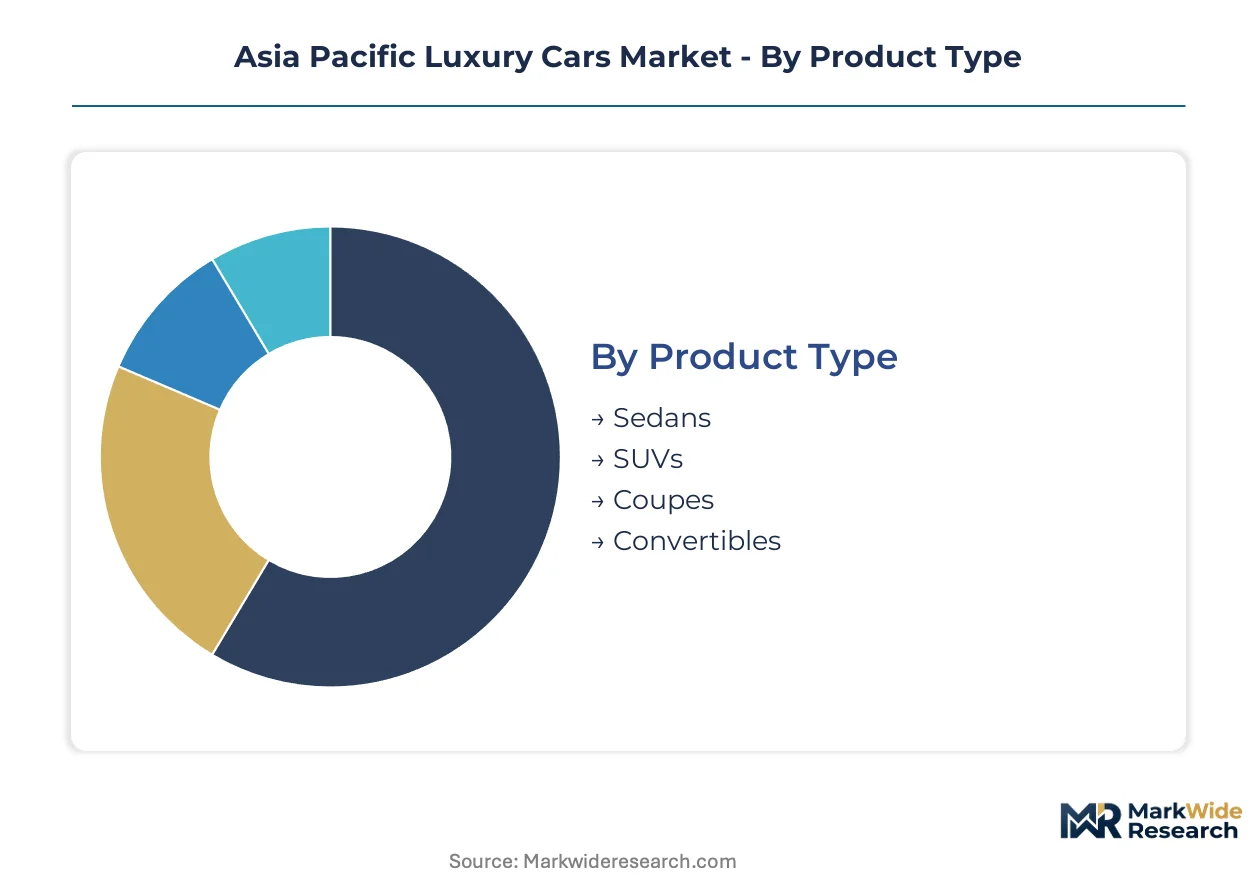
Segmentation in the Asia Pacific Luxury Cars Market reveals how powertrain mandates, ownership models, and distribution infrastructure vary sharply across buyer archetypes. After-sales service intensity differs dramatically between battery-electric platforms requiring specialized technician certification and combustion heritage vehicles with established maintenance networks.
Product Type:
After-sales service intensity varies substantially across body architectures, with aluminum-intensive SUVs demanding specialized collision repair capabilities and sedans leveraging mature dealer technician training pipelines.
- SUVs:Elevated body architectures with aluminum-intensive construction dominate volume across India's deteriorating urban road surfaces and Australia's rural estate access requirements. Ground clearance preferences sustain disproportionate demand in tier-one Chinese cities and Indian metropolitan corridors despite electrification transitions.
- Sedans:Traditional three-box configurations retain residual strength in Japan's corporate reimbursement culture and South Korea's government procurement protocols. Chauffeured executive transport operations in China's eastern seaboard favor extended-wheelbase variants for rear passenger accommodation.
- Coupes:Two-door performance variants serve status-driven individual buyers with lower after-sales frequency but higher per-service expenditure on specialized components.
- Convertibles:Retractable roof architectures capture seasonal demand in Australia's temperate coastal markets and Southeast Asian leisure destinations with limited volume concentration.
By volume, SUVs lead. By growth pace, electric powertrain variants within the SUV category are climbing the fastest as MIIT quotas reshape manufacturer portfolio allocations.
End User:
Cost tier differentiation separates enterprise fleet procurement with captive finance integration from individual buyers navigating battery-as-a-service financing structures.
- Affluent Individuals:Status-driven mobility seekers concentrate in China's tier-one cities and India's metropolitan corridors, with subscription-based models reducing upfront capital burdens for younger demographics entering premium segments.
- Enterprises:Corporate fleet operators across China's eastern seaboard technology corridor and India's Bangalore-Hyderabad metropolitan axis consolidate sourcing through captive finance arms. Chauffeured executive transport operations drive extended-wheelbase sedan and SUV procurement with bundled maintenance requirements.
- Governmental Agencies:South Korea's procurement protocols sustain sedan residual demand against regional SUV dominance, with METI hydrogen corridor alignment influencing fuel-cell pilot programs in Japan.
- Personal Chauffeurs:Professional driver services in Vietnam and Indonesia's underdeveloped retail networks enable direct-to-consumer channel innovation bypassing traditional dealer structures for fleet acquisition.
By volume, Enterprises lead procurement. By growth pace, Affluent Individuals adopting subscription financing are expanding most quickly.
Technology:
Application-driven powertrain selection reflects divergent national electrification timelines, with MIIT NEV credit mandates compelling portfolio rebalancing while combustion heritage equity preservation competes for R&D allocation.
- Electric:Battery-electric platforms with solid-state chemistry transitions are capturing disproportionate investment flow as MIIT production quotas force manufacturer compliance. China's dual carbon goals from MEE accelerate metropolitan fleet procurement across Beijing, Shanghai, and Shenzhen corridors.
- Hybrid:Transitional powertrains bridge infrastructure gaps in India's BIS certification-constrained import environments and Japan's METI standard-setting fragmentation, serving buyers requiring range flexibility.
- Internal Combustion:Heritage combustion variants face margin compression from aluminum-intensive architecture costs and technician retraining requirements, retaining residual demand in corporate reimbursement cultures.
- Autonomous:Self-driving capability integration concentrates in chauffeured enterprise segments across China's technology corridor, with over-the-air update architectures demanding dealership management system retrofit investment.
By volume, Hybrid configurations lead current procurement. By growth pace, Electric powertrains are gaining share fastest under regulatory mandate pressure.
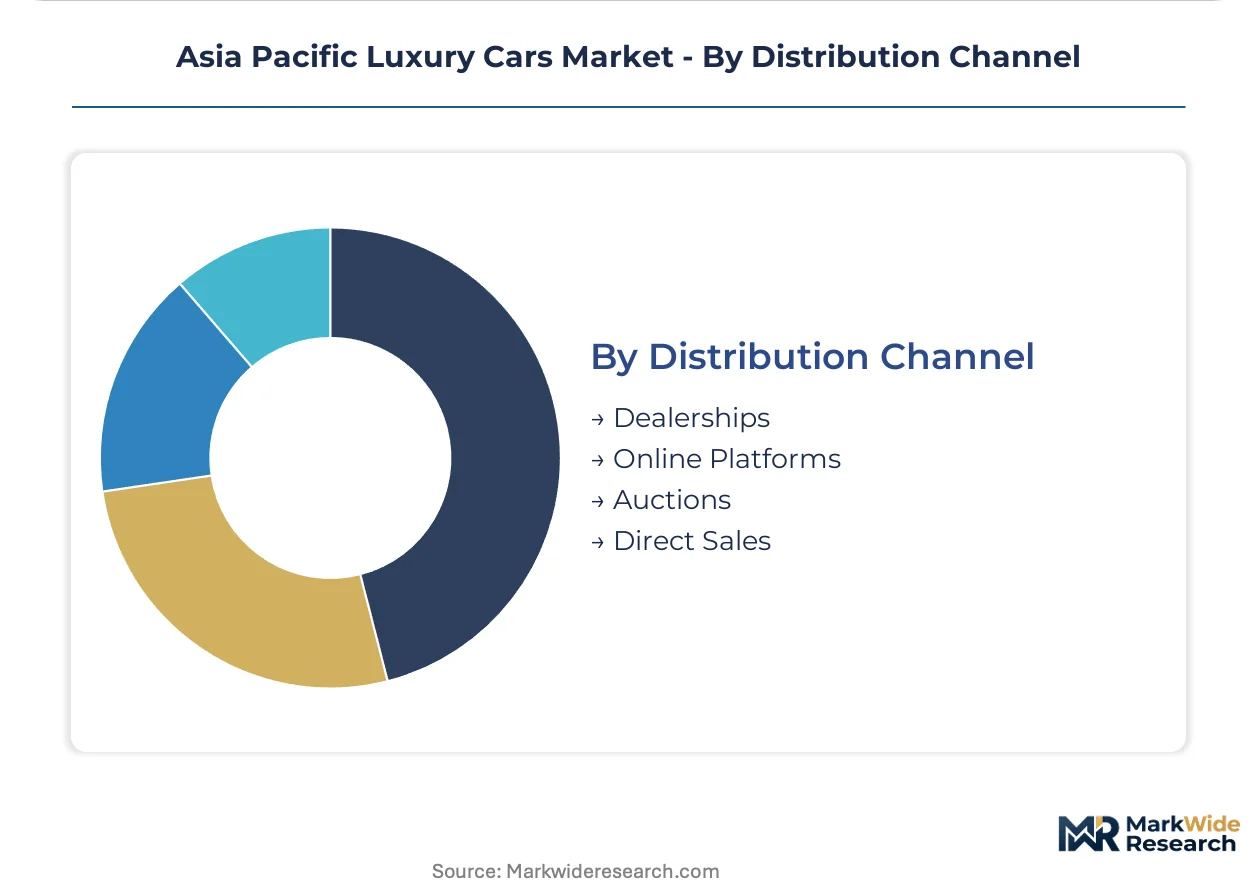
Distribution Channel:
Geography determines channel viability, with vertically controlled retail networks in India and South Korea competing against direct-to-consumer innovation in Southeast Asian underdeveloped markets.
- Dealerships:Vertically controlled retail networks anchor Mercedes-Benz positioning in India and South Korea, with floor space consolidation toward battery-electric demonstrators responding to MIIT mandate tightening.
- Online Platforms:Digital sales infrastructure enables subscription-based vehicle leasing penetration across China's eastern seaboard, reducing friction for younger enterprise fleet buyers.
- Auctions:Secondary market channels serve heritage combustion vehicle disposition as electrification transitions compress residual value horizons for incumbent battery chemistries.
- Direct Sales:Manufacturer-controlled channels bypass traditional dealer structures in Vietnam and Indonesia, supporting concierge ownership models that reduce upfront capital burdens.
By volume, Dealerships lead transaction flow. By growth pace, Online Platforms are climbing the fastest as subscription financing reshapes buyer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for battery-electric powertrain components tilts the regional trade balance toward net import status across most Asia Pacific markets, with only China approaching component self-sufficiency through domestic cell and motor production.
China
MIIT NEV credit mandates compel luxury manufacturers to maintain minimum electric sales ratios or purchase compliance credits from domestic pure-play competitors. Dual carbon goals from MEE accelerate fleet procurement across Beijing, Shanghai, and Shenzhen metropolitan corridors. The Yangtze River Delta engineering clusters concentrate solid-state battery pilot production for 2026-2027 platform integration.
Japan
METI hydrogen corridor investments create white space for fuel-cell powertrain differentiation in executive fleet segments. Corporate reimbursement culture sustains sedan residual demand against regional SUV dominance. The Kanto region around Tokyo anchors captive finance integration for enterprise procurement teams consolidating vehicle sourcing.
India
BIS certification delays for imported EV powertrain components constrain launch velocity for non-domestic premium brands entering metropolitan markets. Deteriorating urban road surfaces sustain disproportionate SUV demand across tier-one cities. The Bangalore-Hyderabad metropolitan axis drives subscription-based vehicle leasing penetration among younger enterprise fleet buyers.
South Korea
Government procurement protocols sustain sedan residual demand against regional SUV volume dominance. METI-influenced charging infrastructure standards create technical alignment opportunities for domestic premium brands. The Seoul Capital Area concentrates vertically controlled retail networks anchoring manufacturer positioning.
Australia
Rural estate access requirements sustain elevated body architecture preferences across temperate coastal markets. Seasonal demand for convertible architectures captures leisure destination buyers with limited volume concentration. The New South Wales and Victoria corridors anchor direct-to-consumer channel innovation bypassing traditional dealer structures.
Asia Pacific Luxury Cars Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying battery cells, electric motors, and aluminum-intensive body structures. The vendor base concentrates among heritage German and Japanese manufacturers with captive finance arms, mid-tier Korean challengers with concierge ownership models, and emerging Chinese pure-plays leveraging domestic supply chain control. Three archetypes dominate: vertically integrated legacy brands, finance-centric platform operators, and battery-electric native specialists. Competitive moves center on floor space consolidation toward battery-electric demonstrators and subscription financing infrastructure buildout.
Within the heritage luxury tier, BMW and Mercedes-Benz occupy positions as vertically integrated legacy representatives with established captive finance operations. Genesis exemplifies the finance-centric challenger archetype through concierge ownership models reducing upfront capital burdens. Among battery-electric specialists, BYD anchors the domestic pure-play position leveraging component self-sufficiency.
| Leading Market Players |
|---|
| Lexus |
| Genesis |
| Audi |
| Volvo |
| BYD |
| BMW |
| Jaguar Land Rover |
| Lamborghini |
| Mercedes-Benz |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta engineering clusters concentrate solid-state battery pilot production capacity, feeding downstream pricing power to manufacturers with captive cell supply against import-dependent competitors facing BIS certification delays and margin compression.
Pricing Analysis
Enterprise fleet buyers anchor subscription-based pricing structures across China's eastern seaboard and India's metropolitan corridors. Three-tier pricing stratifies across concierge ownership, captive finance bundles, and traditional outright purchase with after-sales service differentiation. Cost compression in combustion heritage variants intensifies as aluminum-intensive architecture expenses collide with technician retraining requirements. Individual buyers navigating battery-as-a-service financing exhibit highest price sensitivity, while enterprise procurement teams with consolidated sourcing demonstrate lowest.
Supply Chain Analysis
Lithium-metal anode feedstock and ceramic electrolyte precursors draw from China, South Korea, and Japan for solid-state platform integration. Electric motor laminations, high-grade aluminum sheet, and semiconductor power modules constitute critical component dependencies. Single-source vulnerability concentrates in Korean and Japanese battery supplier relationships for non-domestic luxury brands. Distribution runs through vertically controlled retail networks in India and South Korea, with direct-to-consumer channels gaining share in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects through battery-as-a-service interoperability, where captive finance arms and concierge ownership models restructure asset-light access against traditional title transfer.
For Market Incumbents: Build captive finance moats through subscription infrastructure locking enterprise fleet procurement into recurring revenue streams. Consolidate floor space toward battery-electric demonstrators responding to MIIT mandate tightening. Defend against Genesis-style concierge challengers by integrating over-the-air update architectures into legacy dealership management systems. For New Entrants and Emerging Players: Pursue white-space penetration in Vietnam and Indonesia's underdeveloped luxury retail networks through direct-to-consumer channel innovation. Target personal chauffeur fleet segments with bundled maintenance offerings bypassing traditional dealer structures. Anchor go-to-market strategy around hydrogen corridor alignment with Japan's METI infrastructure investments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent national electrification timelines create portfolio rebalancing opportunities across MIIT, METI, and BIS jurisdictions. Acquisition targets cluster around battery-electric native specialists with component self-sufficiency and solid-state chemistry pipelines. Watch MIIT NEV credit mandate enforcement tightening as inflection signal for compliance credit market dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-metal cell allocation from Yangtze River Delta pilot production clusters. |
| Software-Defined Vehicle Investment | Enables over-the-air powertrain optimization responding to MIIT compliance requirements. |
| Charging Infrastructure Partnership | Resolves METI standard-setting fragmentation blocking European brand market access. |
| Geographic Manufacturing Footprint | Localizes assembly circumventing India's BIS certification delays for imported EV components. |
| Platform Standardization | Reduces dual-platform capex intensity straining mid-tier heritage portfolio R&D allocation. |
Study Parameters
Desk research of vehicle production databases, IHS Markit registration data, and MIIT NEV credit disclosure filings preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations heads, and captive finance executives. Primary fieldwork combined with secondary validation across customs records and regulatory filing repositories. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring.
Assumptions held MIIT mandate enforcement trajectories, METI hydrogen corridor deployment schedules, and BIS certification timeline norms fixed while varying electrification adoption curves and subscription financing penetration rates. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, OEM tier, and regional production cluster. CAGRs derived from regression analysis against historical powertrain transition patterns with inputs from solid-state battery chemistry readiness and charging infrastructure density buildout.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility affecting imported component costs or commodity price swings in lithium and aluminum would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement consistency and technology cost reduction curves. Material shifts in MIIT NEV credit mandate stringency or METI hydrogen infrastructure commitment levels would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Convertible Vehicles Market