
 Bale Openers Market | 2026-2036
Bale Openers Market Size, Share, and Industry Trends Forecast 2026-2036
Bale Openers Market Analytics
Modular equipment configurations with interchangeable feeding and pre-opening units is broadening buyer choice across mid-cap textile recyclers. Rieter leverages its integrated spinning systems expertise to anchor premium positions in automated fiber preparation lines. Trutzschler sustains technology leadership through deep R&D investment in precision opening rollers and foreign-particulate detection. Laroche SA specializes in air-recycling bale openers for nonwoven applications, occupying a defensible niche in technical textile feedstock preparation.
A bale opener is a mechanical device designed to break compressed fiber bales into loose, homogeneous tufts through controlled tearing action, typically processing cotton, synthetic, or recycled textile bales at throughput rates exceeding 1,500 kg per hour. Its primary industrial purpose is to ensure consistent fiber feed quality for subsequent carding, blending, or nonwoven web formation stages. Rotary bale openers dominate installed base volumes due to proven reliability in high-throughput cotton ginning and textile mill operations, though automated bale openers represent the fastest-expanding segment as recyclers pursue labor reduction and batch-to-batch consistency. End-use demand from the recycling industry is intensifying fastest, driven by post-consumer textile collection mandates and brand-owner recycled-content commitments that require precise fiber characterization at the opening stage.
EU Green Deal circular-economy regulations and REACH chemical compliance standards shape equipment specifications by requiring contaminant detection and dust containment systems in fiber preparation lines. FDA guidelines for pharmaceutical-grade nonwoven applications and OSHA workplace exposure limits for textile dust further constrain design choices and create compliance-driven replacement cycles. Stakeholders must monitor how pending extended-producer-responsibility frameworks for textiles in the European Union and individual US state-level recycling mandates redirect capital toward automated opening and sorting infrastructure.
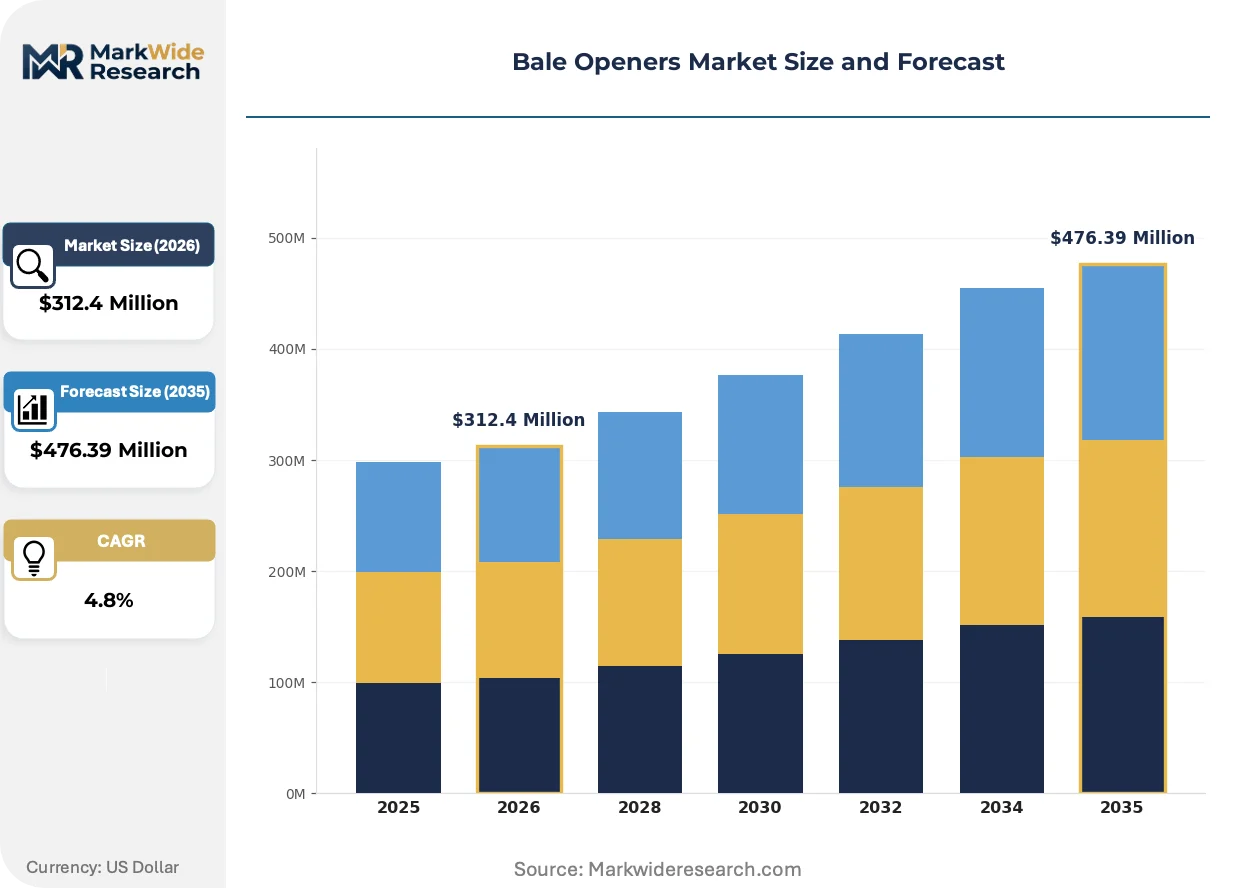
Market Dynamics
Mechanical textile recyclers in Germany and Belgium are consolidating fiber preparation lines around automated bale opening systems to satisfy EU Green Deal circularity mandates and brand-owner recycled-content specifications.
Growth Catalysts
- EU Green Deal circular-economy mandates:Post-consumer textile collection targets in Germany and France require high-throughput fiber preparation infrastructure capable of processing contaminated feedstock at scale.
- Mechanical recycling clusters:Concentrated investment near Frankfurt and Cologne creates localized demand for precision opening equipment with integrated contaminant detection.
- Synthetic fiber recovery:Polyester-cotton blend separation technologies expand addressable feedstock for automated bale openers in technical textile applications.
Market Restraints
- Specialized alloy supply:Precision opening rollers require hardened steel alloys concentrated among German and Austrian metallurgical suppliers, creating input cost volatility.
- REACH chemical compliance:Dust containment and fiber characterization systems must satisfy evolving ECHA substance restrictions, extending equipment validation timelines.
- Manual sorting substitution:Low-wage textile sorting operations in Eastern Europe and North Africa compete with capital-intensive automation for certain feedstock grades.
Strategic Opportunities
- Nonwoven technical textiles:Air-recycling bale opener configurations for geotextile and filtration applications remain underpenetrated relative to spunbond capacity expansion.
- Extended producer responsibility frameworks:Pending EU textile EPR regulations will redirect brand-owner capital toward automated opening and sorting infrastructure investments.
- Near-infrared spectroscopy convergence:Integration of NIR fiber identification with opening stages enables real-time polymer sorting, compressing downstream processing steps.
Industry Challenges
- Mechatronics engineering scarcity:Equipment manufacturers face acute shortages of specialists capable of integrating precision roller dynamics with automated feeding systems.
- Legacy carding line integration:Retrofitting automated bale openers into existing spinning mills requires custom mechanical interfaces and control system harmonization.
- OSHA dust exposure compliance:Workplace exposure limit enforcement demands continuous monitoring system upgrades, complicating equipment commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bale Openers Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Bale Openers, Stationary Bale Openers, Portable Bale Openers, Hydraulic Bale Openers End Use Industry: Agricultural, Recycling, Industrial, Pharmaceutical Technology: Mechanical, Electrical, Pneumatic, Automated Distribution Channel: Direct Sales, Online Retail, Distributors, Partnering Dealers |
| Companies Covered | Rieter, Trutzschler, Laroche SA, Bianco, Beneks Makina, Bonino Carding Machines, Canlar Mekatronik, Cross Wrap Oy Ltd, Lindner Recyclingtech GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bale Openers Market Evolving Landscape
Digital fiber characterization and modular system architecture are compressing equipment replacement cycles while elevating technical performance specifications across European recycling infrastructure.
Automated bale opening systems with interchangeable feeding units and pre-opening modules are modularizing equipment procurement for mid-cap textile recyclers. German mechanical recycling clusters near Frankfurt and Cologne are adopting these configurations to match heterogeneous feedstock quality without dedicated lines. This architecture is modularizing capital deployment by allowing incremental capacity expansion and technology refresh without full line replacement.
REACH chemical compliance standards and evolving EU Green Deal circular-economy regulations are mandating contaminant detection and dust containment in fiber preparation stages. Equipment specifications now require integrated metal detection, polymer identification, and exhaust filtration systems as baseline configurations. Recycling operations in Belgium and the Netherlands are responding earliest, retrofitting existing lines with compliant subsystems ahead of enforcement phase-ins.
Service-based equipment access models are displacing outright purchase for smaller recyclers entering post-consumer textile processing. German equipment financiers and manufacturer captive leasing programs now bundle maintenance, spare parts, and software updates into per-tonne processing fees. This shift concentrates most visibly among entrants in the Netherlands and Denmark where capital constraints meet stringent regulatory timelines.
Bale Openers Market Segmentation
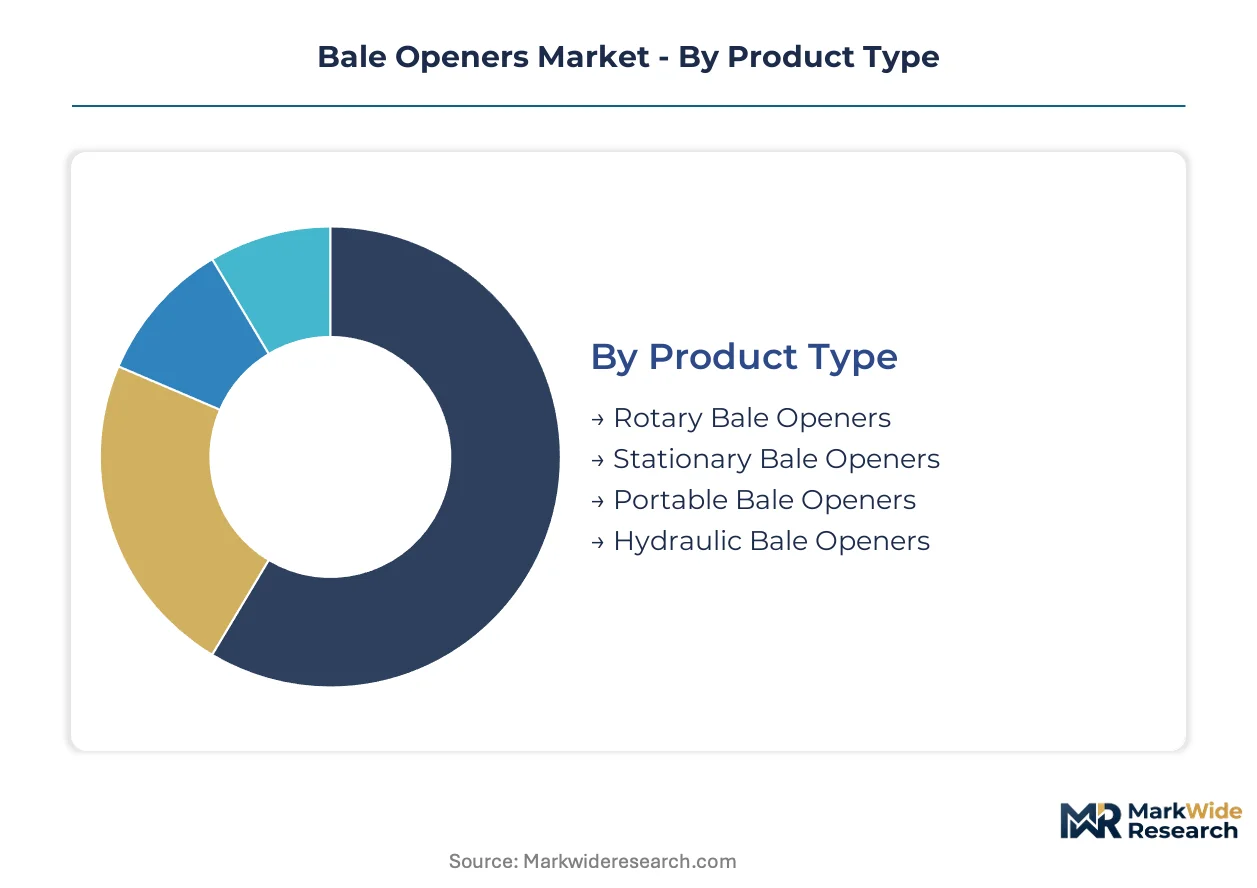
Segmentation in the Bale Openers Market reveals how equipment specifications diverge across fiber preparation workflows. Product architecture, automation level, and channel access each create distinct competitive arenas with diverging margin structures and replacement cycles.
Product Type:
Supply concentration in precision roller manufacturing favors established rotary configurations, while portable and hydraulic variants address fragmented, low-volume demand pockets.
- Rotary Bale Openers:Employ cylindrical opening drums with hardened steel alloy teeth that tear compressed bales through controlled rotational action. German mechanical recycling clusters near Frankfurt and Cologne anchor demand for these high-throughput systems as EU Green Deal mandates require processing contaminated post-consumer textiles at scale.
- Stationary Bale Openers:Fixed-base installations with integrated feeding conveyors and pre-opening stages dominate cotton ginning and large-scale spinning mill operations. Belgian and Dutch recyclers are retrofitting these with REACH-compliant dust containment and metal detection subsystems ahead of enforcement phase-ins.
- Portable Bale Openers:Compact, wheeled units serve agricultural co-operatives and small-batch textile processors with intermittent fiber preparation needs.
- Hydraulic Bale Openers:High-force systems for dense synthetic bales and technical textile feedstocks occupy niche positions in industrial nonwoven applications.
Today's leader: Rotary Bale Openers. Tomorrow's challenger: Automated configurations within this category.
End Use Industry:
Cost tier segmentation separates capital-intensive automated installations from manual-equipment markets, with recycling commanding premium pricing for contaminant-detection integration.
- Agricultural:Cotton ginning operations and fiber co-operatives require robust, low-maintenance opening equipment for seasonal harvest processing.
- Recycling:Post-consumer textile collection mandates in Germany and France are driving automated bale opening adoption for heterogeneous, contaminated feedstocks requiring integrated polymer identification and dust containment systems.
- Industrial:Nonwoven manufacturers and technical textile producers demand precision opening for geotextile and filtration applications with consistent fiber tuft specifications.
- Pharmaceutical:FDA-compliant fiber preparation for medical-grade nonwovens requires validated cleaning protocols and batch traceability systems.
Recycling commands the steepest expansion trajectory as EPR frameworks redirect brand-owner capital toward automated infrastructure.
Technology:
Volume concentration favors mechanical and electrical systems, though pneumatic and automated technologies are gaining share in labor-constrained European operations.
- Mechanical:Gear-driven tearing mechanisms with manual feed control dominate legacy installed bases and price-sensitive agricultural markets.
- Electrical:Variable-speed motor drives enable throughput adjustment for heterogeneous fiber qualities, serving mid-cap recyclers with mixed feedstock profiles.
- Pneumatic:Air-assisted fiber transport and opening systems from Laroche SA and specialized European manufacturers address technical nonwoven applications with delicate fiber handling requirements.
- Automated:Sensor-integrated systems with programmable logic controllers and fiber characterization modules are expanding most quickly among German recyclers pursuing labor reduction and batch-to-batch consistency.
Mechanical and electrical systems retain installed base dominance. Automated configurations are climbing the fastest as labor costs and compliance complexity rise.
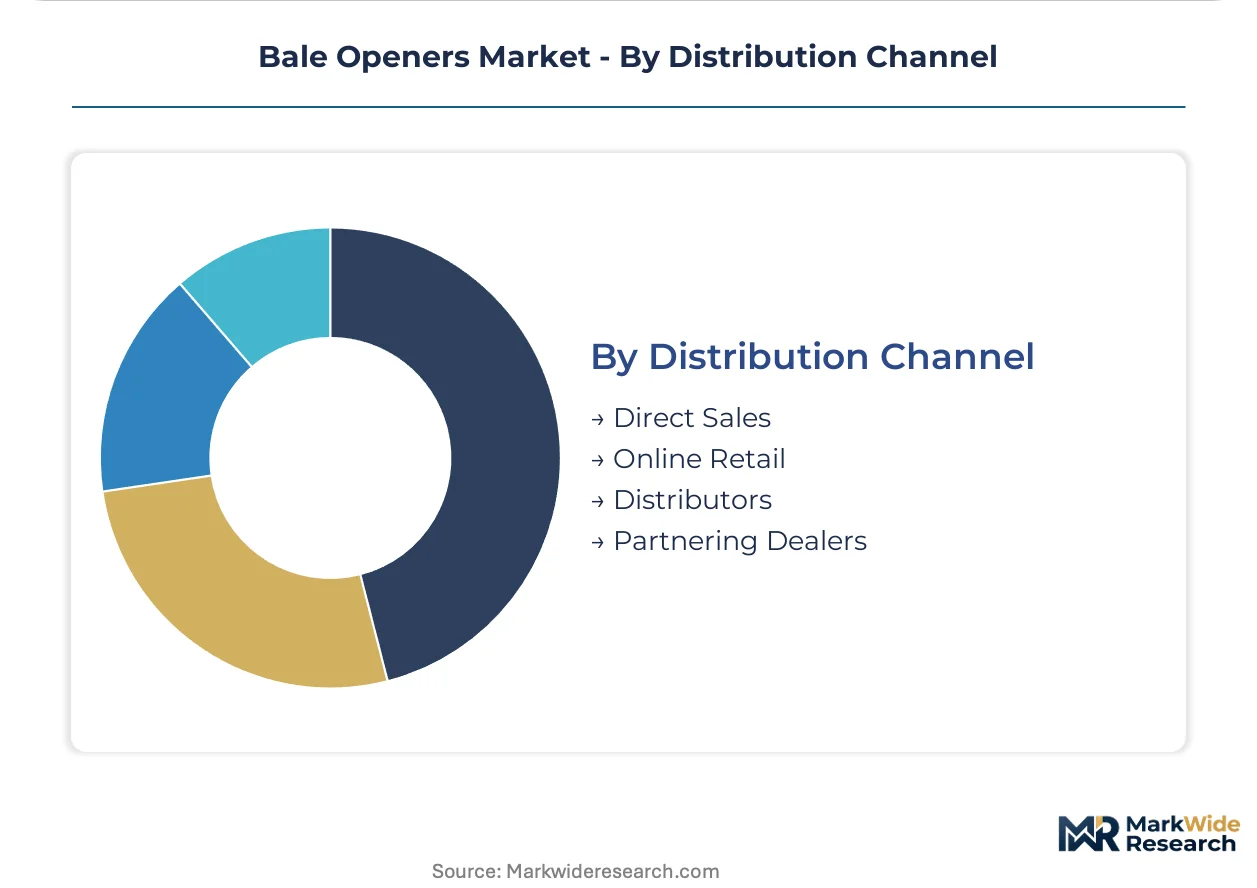
Distribution Channel:
Customer type segmentation separates large recyclers with direct manufacturer relationships from smaller entrants accessing equipment through financed service models.
- Direct Sales:Large mechanical recycling clusters and multinational textile groups negotiate integrated fiber preparation lines with manufacturers like Rieter and Trutzschler.
- Online Retail:Spare parts, consumables, and small portable units move through manufacturer e-commerce portals and industrial equipment marketplaces.
- Distributors:Regional equipment houses with local service capabilities serve mid-cap recyclers and agricultural processors across Eastern Europe and North Africa.
- Partnering Dealers:German equipment financiers and manufacturer captive leasing programs bundle maintenance and software updates into per-tonne processing fees for capital-constrained entrants in the Netherlands and Denmark.
Direct sales capture the highest-value contracts. Partnering dealers are expanding fastest among regulatory-driven market entrants with constrained balance sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale mechanical textile recycling infrastructure during the 1990s packaging waste directive era, establishing the technical foundation that now spreads across European circular-economy mandates.
Germany
Mechanical recycling clusters near Frankfurt and Cologne drive automated bale opening adoption for post-consumer textile processing at scale. EU Green Deal circularity mandates require integrated contaminant detection and dust containment systems in all new fiber preparation installations. North Rhine-Westphalia hosts the densest concentration of high-throughput equipment deployments serving brand-owner recycled-content specifications.
Belgium
Textile recyclers in Flanders are retrofitting legacy fiber preparation lines with REACH-compliant subsystems ahead of enforcement phase-ins. ECHA substance restrictions extend equipment validation timelines for dust containment and fiber characterization technologies. The Port of Antwerp corridor anchors specialized nonwoven feedstock preparation operations for technical textile applications.
Netherlands
Capital-constrained recycling entrants access automated bale opening through service-based equipment models bundling maintenance into per-tonne fees. National extended producer responsibility frameworks redirect brand-owner capital toward automated sorting infrastructure. Amsterdam-Rotterdam corridor operations lead early adoption of air-recycling configurations for heterogeneous post-consumer feedstocks.
France
Post-consumer textile collection targets in the Île-de-France and Hauts-de-France regions require high-throughput fiber preparation infrastructure capable of processing contaminated material streams. ANSM workplace exposure guidelines complement EU-level chemical compliance standards for dust containment system specifications. Lille metropolitan area recyclers are consolidating fiber preparation lines around automated opening systems to meet circular-economy deadlines.
Denmark
Regulatory timelines for textile circularity outpace capital availability among market entrants, accelerating manufacturer captive leasing program adoption. National climate commitments prioritize labor-reducing automation in fiber preparation stages. Copenhagen-area operations concentrate pilot deployments of near-infrared spectroscopy integration with opening stages for real-time polymer sorting.
Bale Openers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and regulatory compliance certification. The vendor base organizes into three tiers: integrated spinning systems specialists, precision component technology leaders, and regional fabrication houses serving price-sensitive agricultural markets. Market structure rewards deep R&D investment in mechatronics engineering and hardened alloy metallurgy. Consolidation pressure concentrates among mid-scale European recyclers seeking turnkey fiber preparation line integration.
Among Swiss-anchored integrated systems specialists, Rieter represents the premium-tier archetype through its spinning systems heritage. German precision technology leaders include Trutzschler, which exemplifies deep component-level R&D investment in opening roller dynamics. Laroche SA occupies the specialized niche position for air-recycling configurations in technical nonwoven applications. These three anchors illustrate how technology depth, geographic proximity to recycling clusters, and application specialization stratify competitive positioning across European fiber preparation infrastructure procurement.
| Leading Market Players |
|---|
| Rieter |
| Trutzschler |
| Laroche SA |
| Bianco |
| Beneks Makina |
| Bonino Carding Machines |
| Canlar Mekatronik |
| Cross Wrap Oy Ltd |
| Lindner Recyclingtech GmbH |
| Others |
Value Network & Pricing Analysis
Automated fiber characterization integration is compressing equipment replacement cycles while simultaneously elevating precision roller metallurgy requirements, concentrating cost pressures among German and Austrian alloy suppliers and amplifying pricing power for integrated systems specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Rieter's integrated spinning lines from Trutzschler's precision component systems and regional fabrication houses serving agricultural markets. Price differentiation rests on automation depth and REACH compliance certification, with recycling-sector buyers showing lowest sensitivity due to EPR-mandated investment timelines. Cost compression in mid-tier electrical systems is intensifying because portable and hydraulic variants from Turkish and Italian manufacturers compete on delivery cost for intermittent-use buyers.
Supply Chain Analysis
Direct-to-recycler channels handle high-volume automated system deployments for German mechanical recycling clusters near Frankfurt and Cologne. Manufacturing concentration in Germany, Switzerland, and Austria draws from hardened steel alloy feedstock and precision mechatronics components sourced from regional metallurgical specialists. Single-source vulnerability in specialized roller manufacturing creates exposure to ECHA substance restriction delays. Distribution runs through captive leasing programs for capital-constrained entrants in the Netherlands and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bale Openers Market functions as a regulatory compounder where EU Green Deal circularity mandates and pending textile EPR frameworks guarantee demand visibility for automated fiber preparation infrastructure.
For Market Incumbents: Extend service-based equipment access models into per-tonne processing contracts that bundle maintenance, spare parts, and software updates, capturing capital-constrained recyclers in the Netherlands and Denmark. Deepen backward integration into precision roller metallurgy to defend margin position against alloy supply volatility from German and Austrian suppliers. Anchor premium positioning through integrated contaminant detection and NIR spectroscopy convergence. For New Entrants and Emerging Players: Mid-cap textile recyclers in Belgium and France represent the most penetrable buyer archetype, requiring modular configurations with interchangeable feeding units to match heterogeneous feedstock without dedicated lines. Air-recycling bale openers for geotextile and filtration applications remain underpenetrated relative to spunbond capacity expansion. Pursue partnering dealer relationships with German equipment financiers to bypass direct sales channel barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication houses serving price-sensitive agricultural markets, yet long-term viability over a five-to-ten-year window favors precision technology leaders with REACH compliance certification depth. Target acquisition profiles center on mechatronics engineering capabilities and hardened alloy metallurgy expertise. Monitor enforcement phase-ins of extended producer responsibility frameworks as the primary inflection signal for capital redirection toward automated infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Roller Manufacturing | Captive alloy supply from German metallurgical specialists reduces input cost volatility for high-throughput systems. |
| Near-Infrared Spectroscopy Module Integration | Real-time polymer identification at opening stages compresses downstream sorting steps for EU Green Deal compliance. |
| Service-Based Equipment Access Launch | Per-tonne fee structures unlock capital-constrained recyclers in the Netherlands and Denmark under EPR timelines. |
| REACH-Compliant Subsystem Retrofit Program | Dust containment and metal detection upgrades capture replacement demand from Belgian and Dutch legacy line operators. |
| Air-Recycling Configuration Development | Technical nonwoven applications for geotextiles and filtration remain underserved relative to spunbond capacity expansion. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with plant engineers at mechanical recycling facilities, OEM procurement teams at spinning mill operators, aftermarket service heads, and technical R&D directors at precision component manufacturers were validated against secondary sources including ECHA substance restriction databases, EU Green Deal implementation progress reports, customs trade data for textile machinery, and SEC filings from listed textile equipment manufacturers. Triangulation across these inputs ensures segmentation integrity across product type, automation level, and channel access dimensions.
Historical trendline analysis of rotary and automated bale opener deployments established baseline penetration rates across agricultural, recycling, industrial, and pharmaceutical end uses. The projection framework models volume and value outputs across the analysis window through segment-specific CAGRs derived from regulatory enforcement timelines, brand-owner recycled-content commitments, and replacement cycle compression from digital fiber characterization adoption. Industry-specific forecast inputs include EPR framework implementation schedules and mechatronics engineering labor availability constraints.
Inputs from ECHA regulatory filings and EU member state implementation progress were available through the study window; gaps in real-time equipment commissioning data from captive leasing programs introduce uncertainty bands around near-term adoption trajectories in the Netherlands and Denmark. Forecasts reflect assumptions regarding REACH enforcement consistency and alloy supply stability from German and Austrian metallurgical suppliers. Periodic stress-testing of base assumptions against EPR framework legislative developments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Truck Crane Market
Construction Equipment
Road Roller Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Self-Drilling Screws Market