
 Manual Welding Positioner Market | 2026-2036
Manual Welding Positioner Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Welding Positioner Market Insights
Maintenance and recalibration service contracts is expanding as a recurring revenue layer that reshapes how positioner vendors monetize hardware. Pemamek anchors its Nordic footprint through dedicated field-service teams that reduce customer downtime. ALM Positioners differentiates by specializing in custom-engineered solutions for non-standard workpiece geometries. Midwest Engineered Systems controls regional distribution channels across the upper Midwest fabrication corridor.
A manual welding positioner is a mechanical fixture that supports, tilts, or rotates a workpiece through a hand-cranked or lever-actuated gearbox, typically accommodating loads from 100 kg to over 10,000 kg to present optimal joint access for stick, MIG, or TIG welding. Rotating positioners lead unit shipments due to their versatility in circular seam applications, while adjustable positioners capture expanding interest from job shops handling variable part sizes. Fabrication applications dominate volume, though repair and maintenance segments yield stronger margin pools as downtime-sensitive customers prioritize rapid turnaround over capital expenditure.
OSHA welding fume standards and the EU Machinery Directive shape product design by mandating integrated fume-extraction interfaces and emergency-stop compliance for operator safety. ISO 3834 quality requirements for fusion welding push end users toward certified positioner configurations that support weld procedure qualification. Stakeholders must monitor how evolving carbon-footprint disclosure rules in Europe and North America affect sourcing decisions for steel castings and geared drive components.
Market Dynamics
Fabrication workshops across Germany and the US retrofit manual positioners to meet OSHA welding fume exposure limits and EU Machinery Directive safety mandates, creating sustained replacement demand that favors vendors with integrated fume-extraction interfaces and certified configurations.
Growth Catalysts
- OSHA welding fume standards:US fabrication workshops face mandatory exposure limit compliance, forcing equipment upgrades that position vendors with certified fume-extraction-ready models to capture retrofit contracts.
- Ergonomic load-bearing prioritization:Small-to-mid fabricators in Germany's industrial clusters invest in adjustable positioners to reduce operator strain and extend workforce retention in tight labor markets.
- ISO 3834 quality requirements:Fusion welding certification mandates push end users toward qualified positioner configurations that support weld procedure qualification and traceability documentation.
Market Restraints
- Steel casting input volatility:Geared drive component production depends on foundry capacity concentrated in specific industrial regions, exposing positioner manufacturers to raw material price swings and extended lead times.
- Technical limitation in precision repeatability:Hand-cranked gearboxes lack the closed-loop control of automated systems, restricting adoption in applications demanding sub-millimeter seam consistency for aerospace or nuclear components.
- Substitution threat from cobot welding cells:Collaborative robot arms with integrated positioners displace pure manual equipment in mid-volume production environments where labor cost arbitrage justifies capital investment.
Strategic Opportunities
- Underpenetrated repair and maintenance segment:Downtime-sensitive customers in power generation and maritime sectors prioritize rapid turnaround over capital expenditure, creating premium service contract potential.
- EU Green Deal carbon-footprint disclosure rules:Evolving sourcing transparency requirements favor positioner vendors with documented low-carbon steel supply chains and localized geared component manufacturing.
- Technology convergence with IoT condition monitoring:Retrofit sensor packages that track gearbox wear and load cycles enable predictive maintenance offerings that differentiate hardware suppliers.
Industry Challenges
- Certified welder-operator shortage:Fabrication shops struggle to staff positioner-equipped stations with personnel holding current ASME or EN ISO 9606 qualifications, constraining equipment utilization rates.
- Integration complexity with legacy fume extraction:Older downdraft tables and arm systems require mechanical interface adaptations that extend installation timelines and inflate project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Welding Positioner Market |
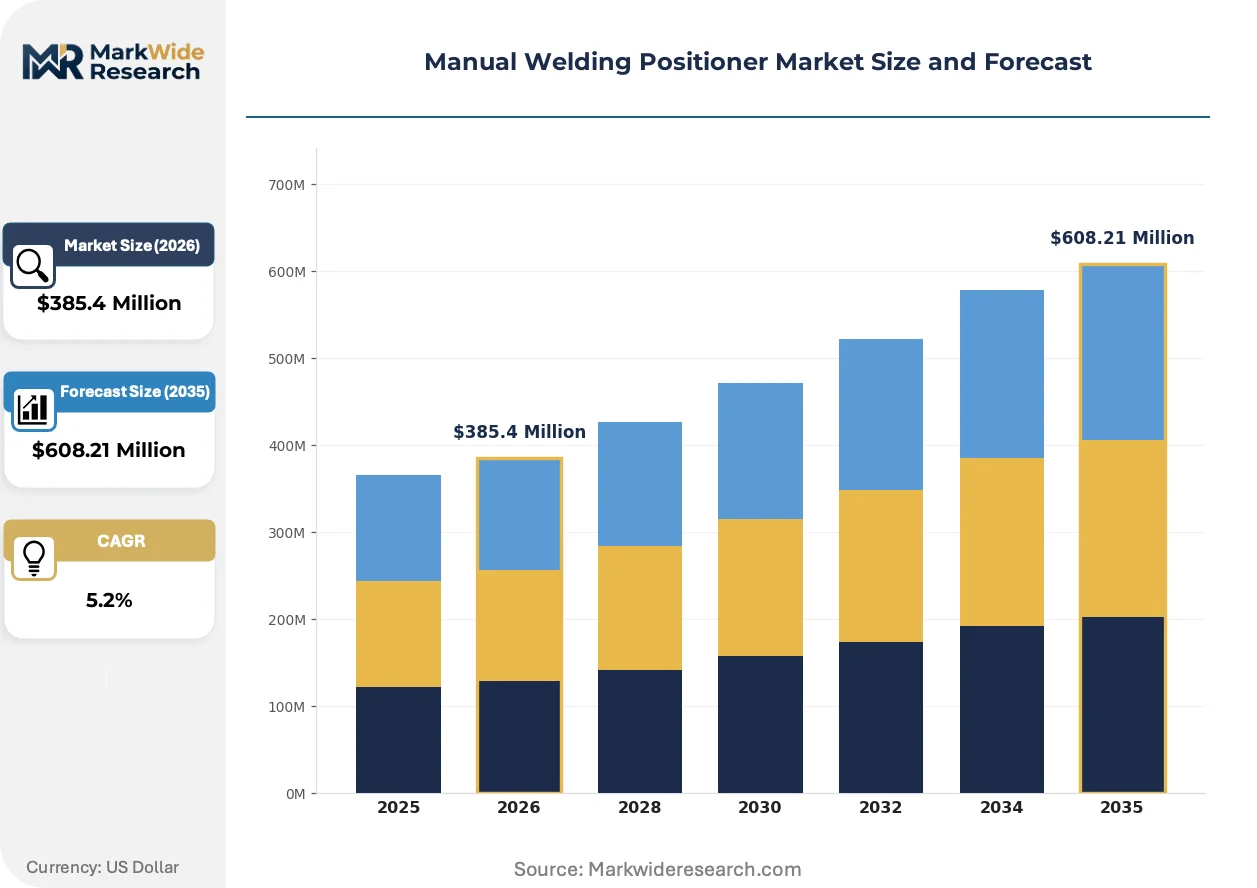
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Positioners, Rotating Positioners, Standard Positioners, Adjustable Positioners End User: Aerospace, Shipbuilding, Construction, Automotive Technology: Electric, Manual, Pneumatic, Hydraulic Application: Fabrication, Repair, Maintenance, Assembly |
| Companies Covered | Key Plant Automation, LazerArc, ALM Positioners, Ergotronix, Unidex Corporation, Align Production Systems, Pemamek, Bancroft Engineering, Midwest Engineered Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Welding Positioner Market Trends and Innovations
Equipment architecture is fragmenting into interoperable subsystems that let fabricators reconfigure positioners for varying part geometries without complete replacement, while regulatory pressure and procurement evolution reshape how vendors monetize hardware.
Positioner frame construction is modularizing around standardized bolt patterns and interchangeable headstock-tailstock units. Job shops in the US upper Midwest adopt these configurations to switch between 500 kg and 2,000 kg capacity setups within single shifts. This adaptability compresses capital deployment cycles and reduces redundant equipment holdings.
REACH substance restrictions and the EU Machinery Directive's updated emergency-stop harmonization standards force redesigns of control enclosures and cable routing. German fabricators now specify positioners with pre-integrated CE-marked safety modules to accelerate site acceptance testing and reduce third-party certification delays.
Service unbundling is accelerating as maintenance contracts separate from initial equipment sales. Nordic fabrication clusters increasingly procure positioners without bundled service, instead negotiating regional field-service agreements with dedicated response-time guarantees. This disintermediation pressures traditional distributors to add technical service capabilities or cede margin to specialized service providers.
Manual Welding Positioner Market Segmentation
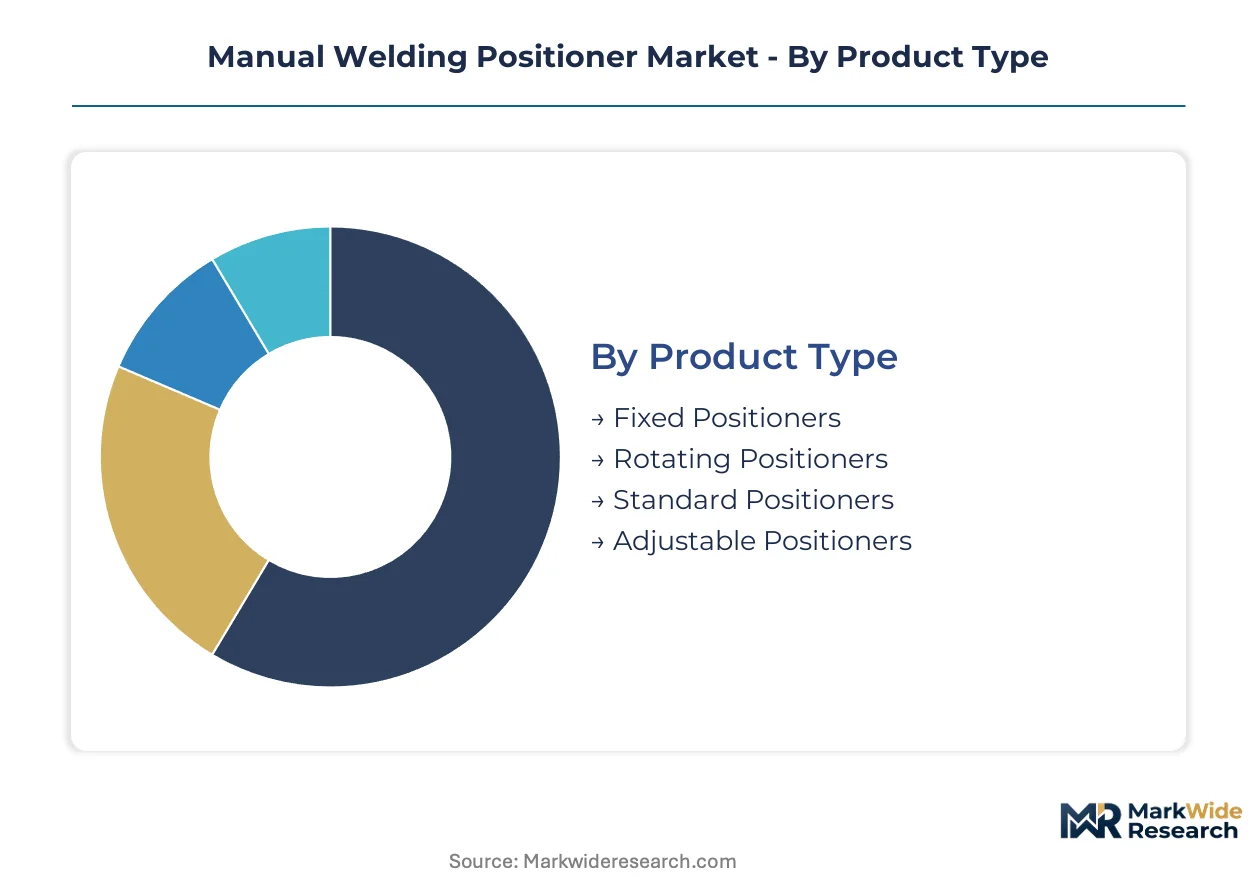
Positioner purchasing patterns diverge sharply between standalone retrofit installations and embedded production-line configurations. Understanding these integration contexts reveals which segments command premium pricing versus volume-driven replacement cycles.
Product Type:
Standalone positioners dominate retrofit demand in OSHA-compliant workshops, while embedded configurations integrate into automated fabrication cells requiring certified fume-extraction interfaces.
- Rotating Positioners:These units incorporate motorized or hand-cranked rotary tables that present circular seams at optimal angles for stick, MIG, or TIG welding. Demand concentrates in German industrial clusters where small-to-mid fabricators prioritize versatile equipment for variable batch sizes. OSHA welding fume exposure mandates accelerate replacement of legacy units lacking integrated extraction ports.
- Adjustable Positioners:Modular headstock-tailstock designs accommodate workpieces from 100 kg to over 10,000 kg through reconfigurable bolt patterns. US upper Midwest job shops adopt these to switch capacity setups within single shifts, compressing capital deployment cycles. Ergonomic load-bearing prioritization extends operator retention in tight labor markets.
- Fixed Positioners:Stationary bench-mounted units serve dedicated high-volume production lines with consistent part geometries.
- Standard Positioners:Conventional tilt-rotate configurations target entry-level fabrication shops with predictable welding schedules.
Rotating positioners lead volumes today; adjustable positioners are gaining share fastest.
End User:
Margin profiles vary dramatically between downtime-sensitive repair operations and capital-constrained production environments, reshaping vendor pricing architectures.
- Construction:Field fabrication of structural steel and infrastructure components demands portable, ruggedized positioners with rapid setup capabilities. US bridge and building contractors drive replacement cycles as OSHA mandates force equipment upgrades. The segment tolerates higher per-unit costs for certified configurations that accelerate site acceptance testing.
- Shipbuilding:Maritime repair and maintenance operations prioritize rapid turnaround over capital expenditure, creating premium service contract potential. Downtime-sensitive drydock operators in Nordic clusters negotiate regional field-service agreements with dedicated response-time guarantees. ISO 3834 fusion welding certification mandates push procurement toward qualified positioner configurations.
- Aerospace:Precision repeatability requirements restrict manual positioner adoption to non-critical subassemblies, with automated systems dominating flight-critical components.
- Automotive:Mid-volume production environments face substitution pressure from cobot welding cells with integrated positioners where labor cost arbitrage justifies capital investment.
Construction leads volumes today; shipbuilding climbs the fastest on service-contract expansion.
Technology:
Drive mechanism selection reflects workshop electrification infrastructure and compressed air availability across regional industrial clusters.
- Manual:Hand-cranked or lever-actuated gearboxes dominate retrofit demand in facilities lacking three-phase power distribution. German fabrication workshops favor these units for their independence from pneumatic or hydraulic infrastructure. Technical limitations in sub-millimeter repeatability restrict adoption in aerospace and nuclear applications.
- Electric:Servo-driven positioners with variable speed control integrate into semi-automated fabrication cells requiring precise stop-start positioning. US workshops upgrading for OSHA compliance specify electric drives for compatibility with modern fume-extraction interfaces. Steel casting input volatility for geared components exposes manufacturers to raw material price swings.
- Pneumatic:Compressed-air actuation suits explosion-sensitive environments and facilities with existing compressor infrastructure.
- Hydraulic:High-torque hydraulic drives address extreme load-bearing requirements above 10,000 kg in heavy fabrication.
Manual technology leads volumes today; electric drives are expanding most quickly on automation convergence.
Application:
Procurement patterns separate capital-intensive new fabrication from recurring maintenance revenue streams with divergent vendor margin structures.
- Repair:Downtime-sensitive power generation and maritime customers prioritize rapid turnaround over capital expenditure, creating premium pricing power. Nordic fabrication clusters increasingly unbundle service contracts from initial equipment sales, negotiating standalone regional field-service agreements. Predictive maintenance offerings through IoT condition monitoring differentiate hardware suppliers.
- Maintenance:Scheduled equipment overhaul programs in industrial facilities drive recurring calibration and recalibration service contracts. German fabricators specify positioners with pre-integrated CE-marked safety modules to reduce third-party certification delays. Certified welder-operator shortages constrain equipment utilization rates across fabrication shops.
- Fabrication:New production work dominates unit shipments but yields thinner margins on competitive bid procurement.
- Assembly:Final integration applications favor lighter-capacity positioners with quick-change fixture interfaces.
Fabrication leads volumes today; repair shows the steepest expansion trajectory on service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as fabricators migrate toward jurisdictions with clearer compliance pathways and established industrial service networks. Cost-of-compliance gaps between OSHA-mandated US workshops and EU Machinery Directive-aligned European facilities are accelerating cross-border equipment sourcing patterns.
United States
Fabrication workshops across the upper Midwest and Gulf Coast retrofit legacy positioners to meet OSHA welding fume exposure limits. The EPA's National Emission Standards for Hazardous Air Pollutants indirectly pressure equipment procurement toward fume-extraction-ready configurations. Chicago-Milwaukee industrial corridor shops prioritize rapid turnaround capabilities for bridge and infrastructure contracts.
Germany
Small-to-mid fabricators in industrial clusters prioritize ergonomic load-bearing equipment to extend workforce retention amid certified welder shortages. EU Machinery Directive emergency-stop harmonization standards force control enclosure redesigns. Ruhr Valley and Bavarian fabrication districts specify CE-marked safety modules to accelerate site acceptance testing.
China
Domestic foundry capacity for steel castings and geared drive components concentrates procurement decisions around localized supply chains. GB standards for welding equipment safety shape product design requirements. Yangtze River Delta fabrication hubs adopt modular positioner configurations to accommodate variable batch sizes in export-oriented production.
Japan
Precision manufacturing traditions restrict manual positioner adoption to non-critical subassemblies, with automated systems dominating flight-critical and nuclear applications. METI industrial productivity initiatives encourage ergonomic equipment upgrades. Nagoya-Toyota industrial corridor maintains demand for high-reliability configurations supporting ISO 3834 quality documentation.
India
Infrastructure construction drives field fabrication demand for portable, ruggedized positioners with rapid setup capabilities. BIS certification requirements for industrial machinery influence procurement specifications. Maharashtra and Gujarat industrial zones exhibit growing interest in adjustable positioners for variable part-size handling in job shop environments.
Manual Welding Positioner Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers commanding premium positioning in certified configurations while regional fabricators capture volume in standard-duty equipment. The vendor base organizes around three archetypes: Nordic field-service specialists with dedicated response teams, custom-engineering boutiques serving non-standard geometries, and Midwest distribution channel controllers. M&A activity concentrates on service capability acquisition, while geographic expansion through regional field-service agreements represents the dominant competitive move.
Among the named specialists, Pemamek anchors Nordic fabrication clusters through dedicated field-service infrastructure, ALM Positioners occupies the custom-engineering tier for non-standard workpiece applications, and Midwest Engineered Systems exemplifies regional distribution channel control across the upper Midwest fabrication corridor. These three represent distinct strategic postures rather than overlapping competitive positioning, with each archetype serving different procurement contexts and customer risk tolerances.
| Leading Market Players |
|---|
| Key Plant Automation |
| LazerArc |
| ALM Positioners |
| Ergotronix |
| Unidex Corporation |
| Align Production Systems |
| Pemamek |
| Bancroft Engineering |
| Midwest Engineered Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Germany's Ruhr Valley and Bavarian industrial clusters anchor supply discipline through multi-generational supplier relationships that resist price volatility. Their ownership structure buffers pricing power against private-equity-rolled competitors by prioritizing workforce retention over quarterly margin extraction. This stability feeds into how positioner vendors negotiate steel casting contracts and field-service agreements.
Pricing Analysis
Capacity additions in China's Yangtze River Delta foundry clusters are reshaping price floors for geared drive components across the manual welding positioner market. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified configurations with integrated fume-extraction interfaces from basic OSHA-compliant models and entry-level fixed positioners. Cost compression in the standard tier is intensifying because Chinese foundry output is expanding faster than German fabrication demand. Small-to-mid US job shops exhibit highest price sensitivity, while Nordic shipbuilding drydock operators prioritize rapid-response service guarantees over per-unit capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with German foundry capacity for precision-machined gearbox housings that feed both domestic fabricators and export markets. Steel casting inputs draw from China, Germany, and India, while servo motor assemblies rest on Japanese and South Korean component ecosystems. Tariff exposure runs through transatlantic shipments of CE-marked safety modules destined for US retrofit installations. Distribution runs through regional fabrication equipment distributors who bundle installation with aftermarket calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
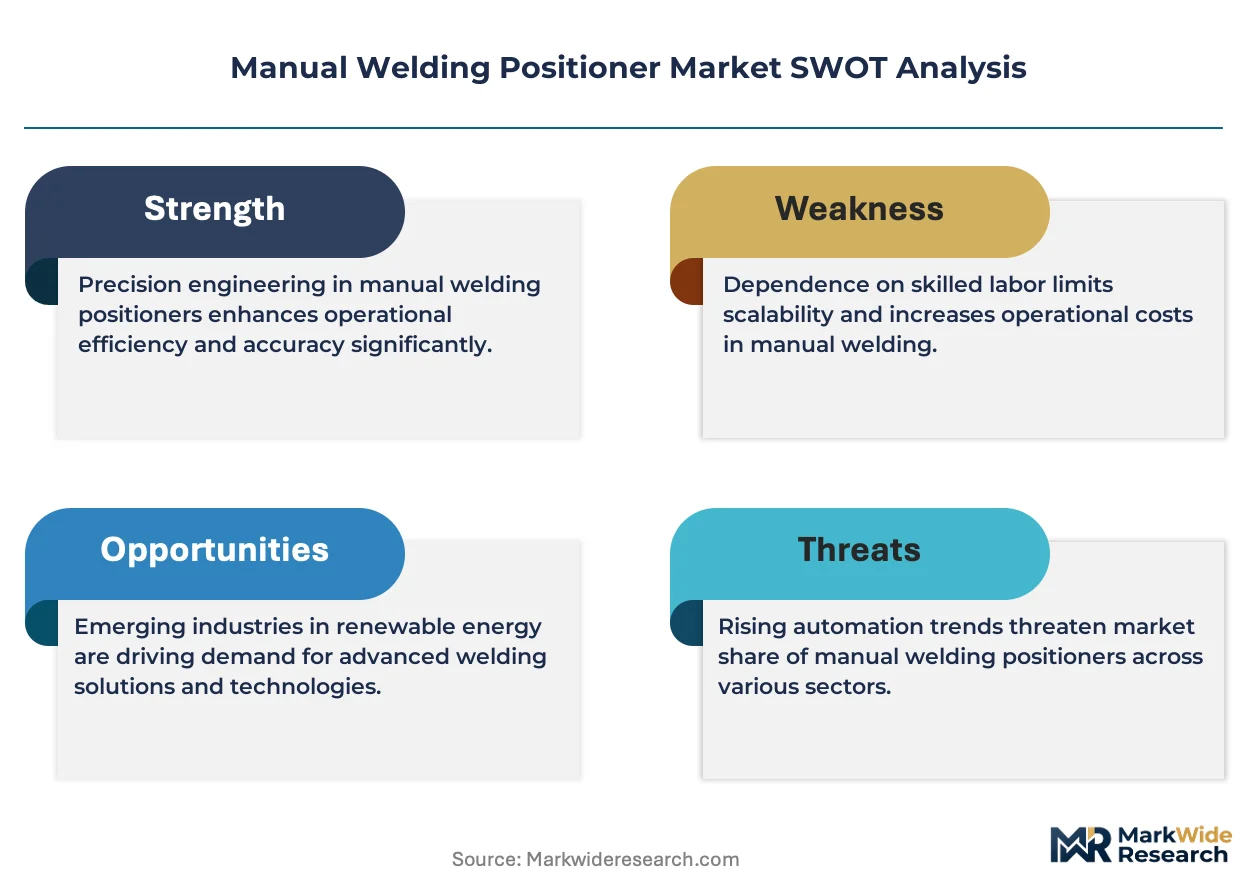
The manual welding positioner market functions as a regulatory compounder where OSHA welding fume exposure mandates and EU Machinery Directive emergency-stop harmonization create sustained replacement cycles independent of industrial production volatility.
For Market Incumbents: Anticipate substitution pressure from cobot welding cells by deepening field-service infrastructure in Nordic maritime repair clusters where downtime sensitivity preserves premium pricing. Anchor backward integration into steel casting supply through long-term offtake agreements with Ruhr Valley foundries to buffer raw material volatility. Defend certification moats by accelerating CE-marked safety module pre-integration that compresses customer site acceptance timelines. For New Entrants and Emerging Players: Capture the underpenetrated repair and maintenance segment in US power generation facilities where predictive maintenance IoT retrofit packages command service-contract premiums. Target India's Maharashtra and Gujarat industrial zones with portable, ruggedized positioners designed for infrastructure field fabrication. Lead with rapid-setup capabilities and BIS certification pathway expertise to differentiate from established European vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution channel controllers lacking dedicated technical service capabilities. Long-term viability hinges on regulatory compliance complexity deepening rather than automation displacement accelerating. Monitor cobot welding cell price points as the critical inflection signal—threshold crossing below mid-volume fabricator capital budgets would compress manual positioner replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Casting | Ruhr Valley foundry partnerships reduce gearbox housing lead-time exposure and tariff vulnerability. |
| IoT Condition Monitoring Retrofit Packages | Predictive maintenance offerings differentiate hardware suppliers in Nordic service-contract negotiations. |
| CE-Marked Safety Module Pre-Integration | Accelerated site acceptance testing reduces German fabricator third-party certification delays. |
| Regional Field-Service Agreement Expansion | Dedicated response-time guarantees capture premium pricing in shipbuilding drydock operations. |
| Modular Headstock-Tailstock Platform Standardization | Interchangeable capacity configurations compress US Midwest job shop capital deployment cycles. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market gathered through structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at fabrication equipment distributors. Secondary validation draws from OSHA enforcement data, EU Machinery Directive harmonization standards, customs records for steel casting trade flows, and SEC filings from publicly traded industrial equipment manufacturers. Bottom-up unit demand estimates triangulate against top-down industrial production indices.
Granularity-level modeling extends to product type, end-use industry, drive technology, and application context across the projection horizon. Segmentation dimensions include rotating versus adjustable versus fixed positioner architectures, construction versus shipbuilding versus aerospace end-use allocations, and manual versus electric versus pneumatic drive mechanisms. CAGRs derive from regression analysis against industrial fabrication output, regulatory compliance deadline clustering, and substitution elasticity estimates for cobot welding cells. Industry-specific forecast inputs incorporate certified welder shortage severity by geography and fume-extraction interface adoption curves.
Steel casting price volatility, cobot welding cell cost trajectories, and evolving carbon-footprint disclosure requirements under the EU Green Deal are the dominant revision risks that could shift equipment replacement timing and vendor selection criteria. Forecasts reflect documented assumptions about regulatory enforcement intensity and labor market tightness persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
North America Drilling Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Global Excavators Market