
 North America Drilling Market | 2026-2036
North America Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drilling Market Analytics
The EPA's updated methane emissions standards for new and modified oil and gas sources is broadening the addressable market for low-leakage drilling systems across the United States. Schlumberger Limited leverages its integrated drilling and evaluation portfolio to capture retrofit demand from operators facing compliance deadlines. Baker Hughes Company sustains technology leadership through its automated well construction platform. Halliburton Company anchors its position via extensive pressure pumping and directional services infrastructure in the Permian and Bakken.
North America drilling encompasses the mechanical penetration of subsurface formations using rotary, percussion, auger, or directional methods to create boreholes for hydrocarbon extraction, geothermal access, or mineral recovery, typically achieving depths from hundreds to tens of thousands of feet depending on geological targets and employing drill strings, mud systems, and bottom-hole assemblies engineered to withstand high-pressure, high-temperature downhole conditions. Directional drilling commands premium margins as operators target laterally extensive unconventional reservoirs where precision trajectory control maximizes contact with pay zones. Automation technology represents the fastest-expanding segment as rig contractors deploy closed-loop systems to reduce crew exposure, improve rate of penetration, and satisfy insurer requirements for remote-operation readiness. Conventional mechanical drilling retains substantial installed base across mature onshore fields where capital constraints limit technology refresh cycles.
The Bureau of Land Management governs federal onshore leasing and drilling permit timelines, while Alberta's Alberta Energy Regulator enforces well integrity and abandonment standards that shape Canadian operator capital allocation. OSHA mandates govern worker safety on US drilling rigs, influencing equipment specification and training expenditures across the contractor base. Stakeholders must monitor how evolving EPA methane rules and state-level bonding requirements for orphaned wells reshape the economics of drilling fleet deployment and retirement decisions.
Market Dynamics
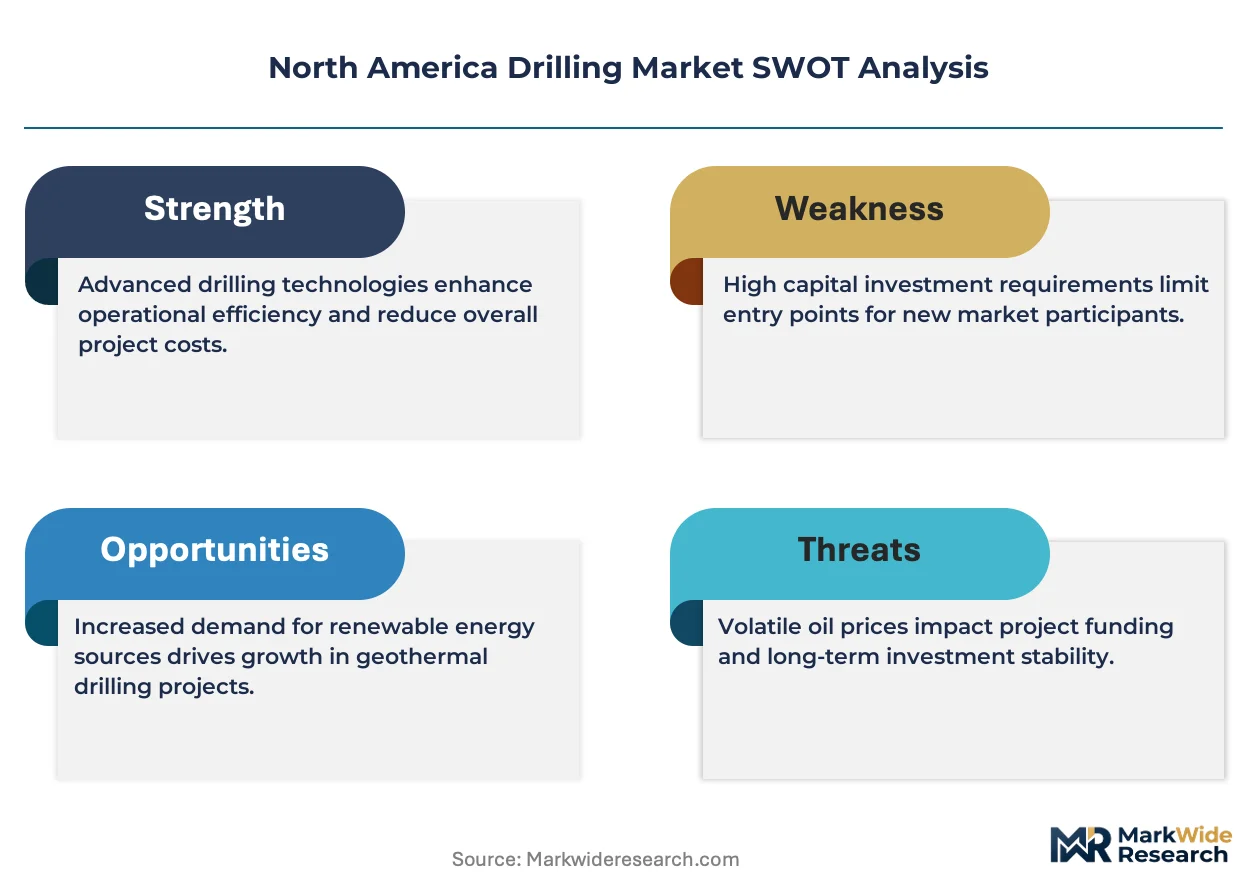
Directional drilling automation is compressing crew requirements while expanding lateral reach capabilities across Permian and Bakken unconventional plays. This technological inflection is redistributing capital toward closed-loop rig systems and away from conventional mechanical fleets.
Growth Catalysts
- EPA Methane Standards:New source performance standards mandate low-leakage completions, expanding retrofit demand for green completions equipment and vapor recovery units across US shale basins.
- Lateral Length Extension:Extended-reach horizontal drilling in the Delaware and Midland sub-basins maximizes reservoir contact per wellbore, improving capital efficiency per barrel.
- Geothermal Co-production:Sedimentary heat extraction from depleted oil fields creates dual-use infrastructure opportunities in Texas and Alberta.
Market Restraints
- Steel Input Volatility:Drill pipe and casing costs fluctuate with scrap metal and alloy pricing, compressing rig contractor margins during procurement cycles.
- Permitting Delays:Bureau of Land Management environmental review timelines for federal acreage extend spud-to-production intervals beyond operator hurdle rates.
- Electrification Infrastructure Gaps:Grid capacity constraints in West Texas and Southeast New Mexico limit field power substitution for diesel prime movers.
Strategic Opportunities
- Orphaned Well Plugging:State-level bonding requirement enforcement in Texas, Louisiana, and Alberta creates demand for specialized plugging and abandonment rigs.
- CCUS Drilling:Carbon capture utilization and storage site characterization requires deep saline formation access, opening new service lines for pressure control specialists.
- Remote Operations Centers:Real-time drilling optimization from centralized facilities reduces crew exposure and satisfies insurer risk transfer requirements.
Industry Challenges
- Directional Driller Shortage:Specialized trajectory control expertise remains scarce as experienced hands exit the workforce faster than training programs replenish supply.
- Legacy SCADA Integration:Closed-loop automation systems face interoperability friction with decades-old rig instrumentation architectures.
- OSHA Silica Enforcement:Respirable crystalline silica exposure limits during hydraulic fracturing operations necessitate engineering controls and respiratory protection expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drilling Market |
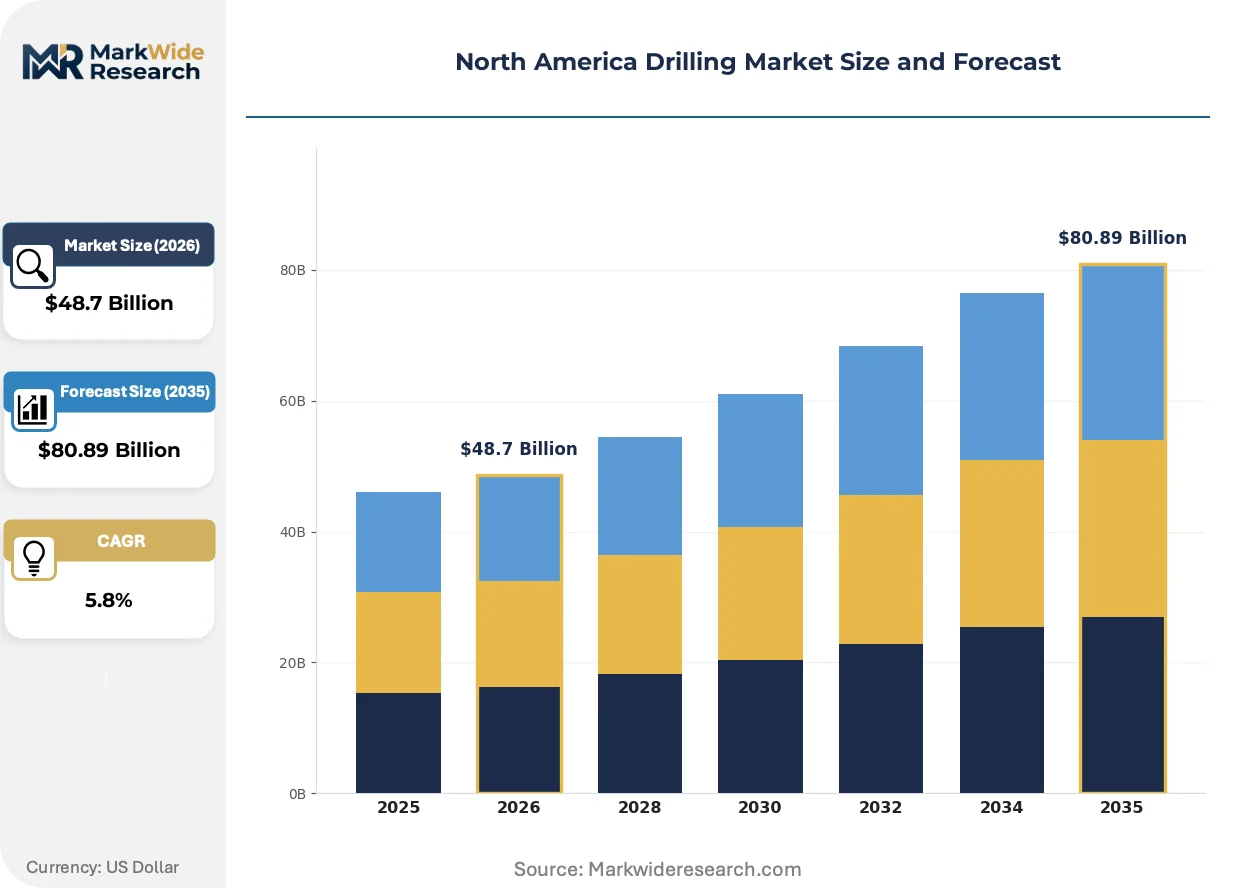
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rotary, Percussion, Auger, Directional Application: Oil Extraction, Gas Extraction, Geothermal, Mining Technology: Conventional, Hydraulic, Wireless, Automation End User: Energy Producers, Mining Companies, Construction Firms, Contractors |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, Chevron Corporation, ConocoPhillips, Nabors Industries Ltd., Helmerich & Payne Inc., National Oilwell Varco, Weatherford International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drilling Market Evolving Landscape
Digital twin technology is collapsing the feedback loop between downhole conditions and surface decision-making. This convergence of physics modeling and real-time telemetry is compressing non-productive time while enabling predictive maintenance regimes.
Pad drilling automation is decentralizing rig deployment patterns across the Permian Basin. Multi-well pad configurations now dominate greenfield development, with operators clustering 12-24 wells per surface location. This density is decentralizing supply chain logistics toward centralized sand, water, and equipment staging yards rather than single-well mobilizations.
The EPA's updated methane emissions standards are forcing equipment refresh cycles across the US onshore fleet. Compressor station upgrades, pneumatic controller replacements, and leak detection and repair protocols now shape capital allocation timelines. Smaller private operators in the Anadarko and DJ basins face disproportionate compliance burdens relative to integrated majors with dedicated environmental teams.
Integrated service contracting is consolidating vendor relationships among Permian-focused independents. Bundled drilling, completions, and production services reduce transaction overhead but compress supplier margins through volume commitments. This procurement consolidation is most pronounced among Permian-focused independents seeking operational simplicity over specialized point solutions.
North America Drilling Market Segmentation
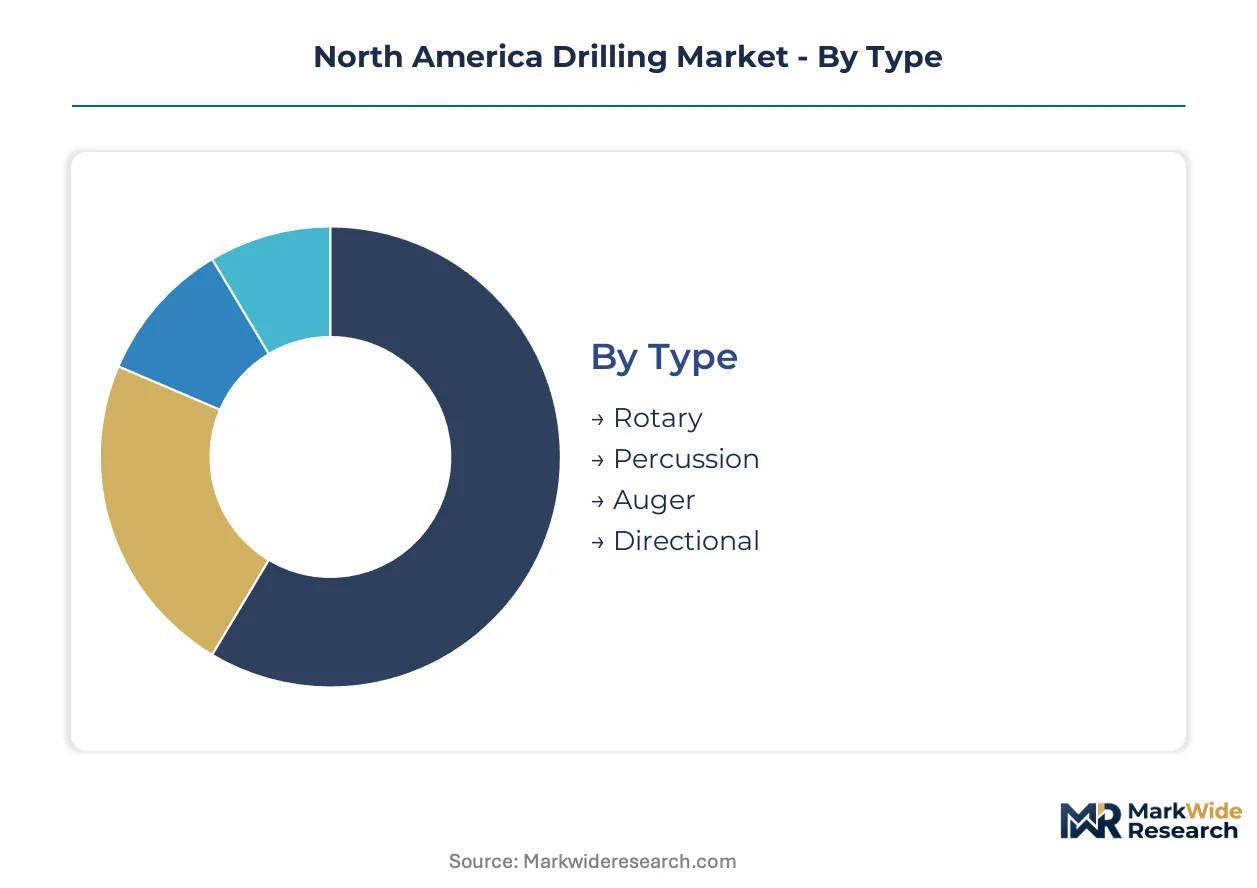
Segmentation in North America drilling reveals how capital allocation splits across extraction methods, resource targets, and operational sophistication. Understanding these divisions exposes where technology premiums command pricing power versus where commodity economics dominate procurement decisions.
Type:
Buyers in this category differentiate primarily by geological hardness and depth requirements, which dictate mechanical approach and capital intensity.
- Rotary:Rotary systems deploy rotating drill bits with circulating fluid to cut through sedimentary and hard rock formations. Demand concentrates across Texas Permian and Alberta oil sands where operators require reliable penetration through interbedded shale and sandstone sequences under high-temperature, high-pressure conditions.
- Directional:Directional drilling employs steerable bottom-hole assemblies and real-time telemetry to execute planned wellbore trajectories. Lateral length extension in Delaware and Midland sub-basins drives deployment, as precision trajectory control maximizes reservoir contact per surface location and satisfies lease configuration constraints.
- Percussion:Percussion methods utilize repeated impact force from pneumatic or hydraulic hammers to fracture rock. Hardrock mining operations in Nevada and Quebec employ these systems for blasthole drilling where rotary cutting proves inefficient.
- Auger:Auger drilling uses helical screw conveyors to remove cuttings in shallow, unconsolidated formations. Environmental monitoring wells and geotechnical site investigations across the US Gulf Coast represent primary demand pockets.
Rotary systems lead volumes today; directional is gaining share fastest.
Application:
Application segmentation tracks how resource economics and policy incentives redirect drilling capital across commodity cycles.
- Oil Extraction:Oil-directed drilling targets liquid hydrocarbon reservoirs through vertical, directional, and horizontal wellbores. Permian Basin operators in West Texas and Southeast New Mexico deploy extended-reach laterals to access stacked pay zones, with EPA methane compliance requirements shaping equipment specifications for new completions.
- Gas Extraction:Natural gas drilling accesses conventional and unconventional reservoirs including tight sands and shale formations. Appalachian Basin activity in Pennsylvania and West Virginia responds to LNG export capacity expansions and winter heating demand curves.
- Geothermal:Geothermal drilling penetrates hot dry rock and sedimentary formations to extract heat for electricity generation or direct use. Sedimentary heat extraction from depleted oil fields in Texas creates dual-use infrastructure opportunities as operators repurpose existing wellbores.
- Mining:Mining applications encompass exploration coring, blasthole drilling, and raise boring for mineral recovery. Nevada gold operations and Saskatchewan potash deposits sustain demand for specialized rig configurations.
Oil extraction dominates current deployment; geothermal is expanding most quickly.
Technology:
Technology tiers separate operators by automation readiness and digital integration depth, with premium pricing attached to closed-loop systems.
- Automation:Automated drilling platforms integrate real-time downhole measurement, adaptive control algorithms, and remote operation capabilities. Permian-focused independents adopt these systems to reduce crew exposure, improve rate of penetration, and satisfy insurer requirements for remote-operation readiness.
- Hydraulic:Hydraulic drilling leverages high-pressure fluid power for precise force transmission and vibration damping. Directional applications in the Bakken and Eagle Ford employ hydraulic top drives and mud motors for torque management in extended-reach configurations.
- Conventional:Conventional mechanical drilling relies on direct mechanical power transmission with manual parameter control. Mature onshore fields with capital-constrained operators retain substantial installed base where technology refresh cycles lag.
- Wireless:Wireless telemetry eliminates physical connections between surface and downhole instrumentation. Emerging deployments focus on managed pressure drilling applications where signal reliability through drilling fluid alternatives reduces non-productive time.
Conventional technology retains the largest installed base; automation is climbing the fastest.
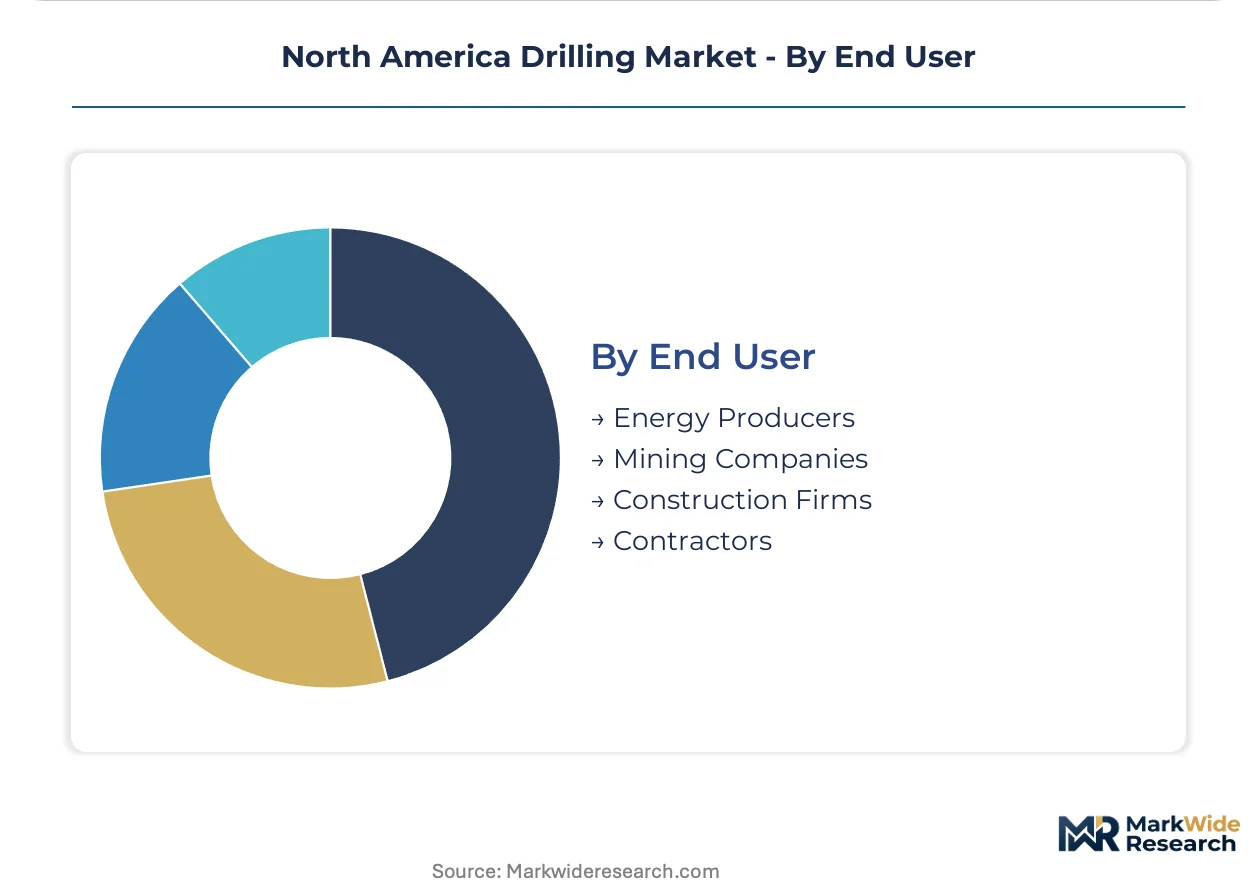
End User:
End user categories reflect procurement scale, technical sophistication, and service integration preferences across the value chain.
- Energy Producers:Integrated majors and large independents operate captive drilling programs or contract integrated services. These buyers prioritize bundled drilling, completions, and production packages to reduce transaction overhead and enforce standardized safety protocols across multi-basin portfolios.
- Contractors:Drilling contractors own and operate rig fleets under day-rate or footage-based arrangements. These service providers differentiate through equipment age, automation capability, and crew experience quality, with OSHA compliance and insurance costs driving consolidation.
- Mining Companies:Mining operators require specialized exploration and production drilling for mineral resource definition and extraction. Nevada gold producers and Quebec iron ore developers maintain dedicated drilling divisions or long-term contractor relationships.
- Construction Firms:Construction applications encompass foundation drilling, tunnel boring, and geotechnical investigation. Urban infrastructure projects in Toronto and Houston create intermittent demand for piling rigs and diaphragm wall equipment.
Energy producers represent the largest contract value; contractors show the steepest technology refresh activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American drilling industry traces its modern scale to the 1901 Spindletop discovery in Texas, which established the region as the cradle of rotary drilling technology and commercial petroleum extraction. This historical foundation shaped the Permian Basin, Gulf of Mexico, and Western Canadian Sedimentary Basin as the three dominant drilling corridors today.
United States
Permian Basin operators in West Texas and Southeast New Mexico deploy extended-reach horizontal laterals exceeding 15,000 feet to access stacked pay zones. EPA methane regulations under the Clean Air Act mandate green completions equipment and vapor recovery units for new well construction. The Midland-Odessa metropolitan cluster concentrates directional drilling automation deployment, with rig contractors retrofitting closed-loop systems to satisfy insurer remote-operation requirements.
Canada
Alberta's oil sands and Montney tight gas formations sustain demand for high-horsepower drilling rigs capable of winterized operation. The Alberta Energy Regulator enforces Directive 020 well integrity standards and Directive 006 abandonment bonding requirements that shape operator capital allocation timelines. Calgary anchors integrated service company headquarters, while Grande Prairie and Fort McMurray function as operational staging grounds for northern drilling campaigns.
Mexico
Reform-era energy liberalization opened deepwater blocks in the Gulf of Mexico to international operators, expanding demand for ultra-deepwater drilling units. The National Hydrocarbons Commission regulates exploration and production contracts under the Hydrocarbons Law framework. Ciudad del Carmen in Campeche serves as the primary logistics hub for offshore drilling support vessels and helicopter operations to Cantarell and Ku-Maloob-Zaap fields.
North America Drilling Market Competitive Landscape
Capital-heavy rig owners compete with asset-light technology licensors across tiered service arrangements. The vendor base concentrates among integrated oilfield service conglomerates, specialized drilling contractors, and equipment manufacturers. Three strategic archetypes dominate: full-service integrators bundling drilling through completions, pure-play rig operators competing on day-rate efficiency, and technology specialists licensing directional control systems. Consolidation through fleet acquisitions and strategic partnerships for automation deployment represent the primary competitive vectors reshaping market share.
Among Houston-headquartered service conglomerates, Schlumberger Limited and Halliburton Company exemplify the full-service integrator archetype, while Baker Hughes Company occupies a position spanning equipment manufacturing and digital automation platforms. These entities anchor the premium tier through bundled service contracts that reduce transaction overhead for Permian-focused independents.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| Chevron Corporation |
| ConocoPhillips |
| Nabors Industries Ltd. |
| Helmerich & Payne Inc. |
| National Oilwell Varco |
| Weatherford International |
| Others |
Value Network & Pricing Analysis
Captive integration of pressure pumping and directional services anchors Halliburton Company and Schlumberger Limited to premium day-rate pricing in the Permian Basin. This vertical control over critical path equipment insulates integrated service providers from spot-market volatility while compressing margins for pure-play rig contractors competing on mechanical drilling alone.
Pricing Analysis
Three-tier pricing structure across premium automation, standard hydraulic, and economy mechanical rig tiers separates operator procurement strategies in North America. Price differentiation rests on automation capability depth and EPA methane compliance certification status. Cost compression in economy mechanical tiers intensifies because steel input volatility and crew retention expenses squeeze legacy fleet operators. Private Permian independents exhibit highest price sensitivity, while integrated majors prioritize specification compliance over rate negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Chinese seamless steel pipe suppliers and South Korean specialized alloy producers for high-pressure drilling components. Raw material dependencies draw from scrap metal pricing cycles, chromium-molybdenum alloy availability, and advanced electronics for downhole telemetry systems. Tariff exposure on imported steel and alloy inputs threatens rig contractor margin stability. Distribution runs through Houston-based equipment staging yards and Calgary logistics hubs serving basin-specific operator demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America drilling has shifted toward a late-cycle quality story as EPA methane compliance deadlines force equipment refresh toward low-leakage, automated systems. Premium specification demand from Permian operators now rewards integrated service bundling over point-solution procurement.
For Market Incumbents: To counter automation technology commoditization from pure-play software vendors, Schlumberger Limited and Baker Hughes Company should deepen captive control over directional drilling telemetry manufacturing and secure exclusive equipment supply agreements with top-ten Permian independents. Backward integration into downhole sensor production reduces third-party dependency while locking in multi-year service contracts. For New Entrants and Emerging Players: A mid-tier pricing gap between premium closed-loop automation and legacy mechanical rigs creates white-space opportunity for regional contractors offering retrofit automation packages to capital-constrained operators in the Anadarko and DJ basins. Target orphaned well plugging and abandonment services in Texas and Louisiana where state bonding enforcement accelerates rig demand. Lead with regulatory compliance expertise as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap drilling contractors with established Permian basin positions because fragmented private operator procurement patterns favor consolidated vendor relationships over fragmented service sourcing. Five-to-ten year viability hinges on automation capex conversion rates and regulatory compliance cost pass-through success. Monitor EPA enforcement intensity on methane standards as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Deployment | Closed-loop rig systems reduce crew exposure and satisfy insurer remote-operation requirements across Permian operations. |
| Backward Integration into Telemetry Manufacturing | Captive sensor production insulates service margins from semiconductor supply chain volatility affecting downhole instrumentation. |
| Orphaned Well Plugging Specialization | State bonding enforcement in Texas and Louisiana creates dedicated rig demand for abandonment-focused contractors. |
| EPA Compliance Certification Investment | Green completions equipment certification opens retrofit opportunities among private operators facing regulatory deadlines. |
| Integrated Service Contracting Expansion | Bundled drilling-through-completions packages reduce transaction overhead for Permian-focused independents seeking operational simplicity. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each country's drilling corridor stakeholders. The analysis combines structured interviews with rig contractors, directional drilling specialists, E&P procurement executives, and regulatory compliance officers with secondary validation from EIA production data, Alberta Energy Regulator directives, SEC 10-K filings, and Bureau of Land Management permitting records. Bottom-up rig fleet counts and top-down basin-level expenditure estimates triangulate market sizing.
Rate-of-change decomposition across the analysis window separates volume effects from price-mix shifts in directional versus mechanical rig deployment. Segmentation dimensions modeled include drilling type, automation technology tier, application target, and end-user procurement scale. CAGRs derive from basin-specific activity forecasts incorporating EPA regulatory timelines and operator capital allocation surveys. Forecast inputs center on lateral length extension trajectories and electrification infrastructure buildout pace in West Texas.
Caveats apply where steel tariff policy shifts or accelerated EPA enforcement timelines could materially shift the outlook for equipment refresh cycles and rig retirement decisions. Forecasts reflect assumptions about methane regulation stability and operator consolidation patterns among Permian independents. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
Utility Locator Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Global Asphalt Crushers Market