
 North America MEMS and Sensors Market | 2026-2036
North America MEMS and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America MEMS and Sensors Market Analytics
The capital-intensity divergence between captive foundry operators and fabless design houses is collapsing as wafer costs escalate across all process nodes. Texas Instruments Incorporated sustains its competitive moat through backward integration into 300mm analog wafer fabrication. STMicroelectronics leverages its vertically integrated MEMS production lines to control yield and accelerate time-to-market for automotive-grade accelerometers. Robert Bosch GmbH anchors its North American position through dedicated cleanroom capacity serving Tier 1 suppliers in Detroit and Stuttgart-aligned operations.
Micro-Electro-Mechanical Systems and sensors integrate micromachined silicon structures with transduction mechanisms to measure physical, chemical, or biological parameters, typically fabricated through bulk micromachining or surface micromachining processes with feature resolutions below 100 micrometers. These devices convert mechanical displacement, pressure differentials, or inertial forces into electrical signals for closed-loop control in safety-critical and consumer systems. Pressure sensors and accelerometers occupy mature volume positions where automotive qualification cycles and consumer electronics procurement contracts compress margins. MEMS Technology and capacitive sensing architectures represent the fastest-expanding technology categories, driven by fingerprint recognition modules and microphone arrays in wearable devices and smart home ecosystems. Optical sensors command premium pricing in healthcare diagnostics and industrial metrology where precision requirements exceed standard CMOS capabilities.
The U.S. Food and Drug Administration and Health Canada enforce biocompatibility and electromagnetic compatibility standards that gate market entry for implantable and diagnostic sensor platforms. The U.S. Federal Communications Commission regulates radio-frequency emissions from wireless sensor nodes, directly shaping antenna integration and packaging decisions for IoT deployments. Stakeholders must monitor how NHTSA autonomous vehicle testing mandates and EPA emissions monitoring requirements redirect R&D spending toward multi-axis inertial units and high-temperature exhaust gas sensors.
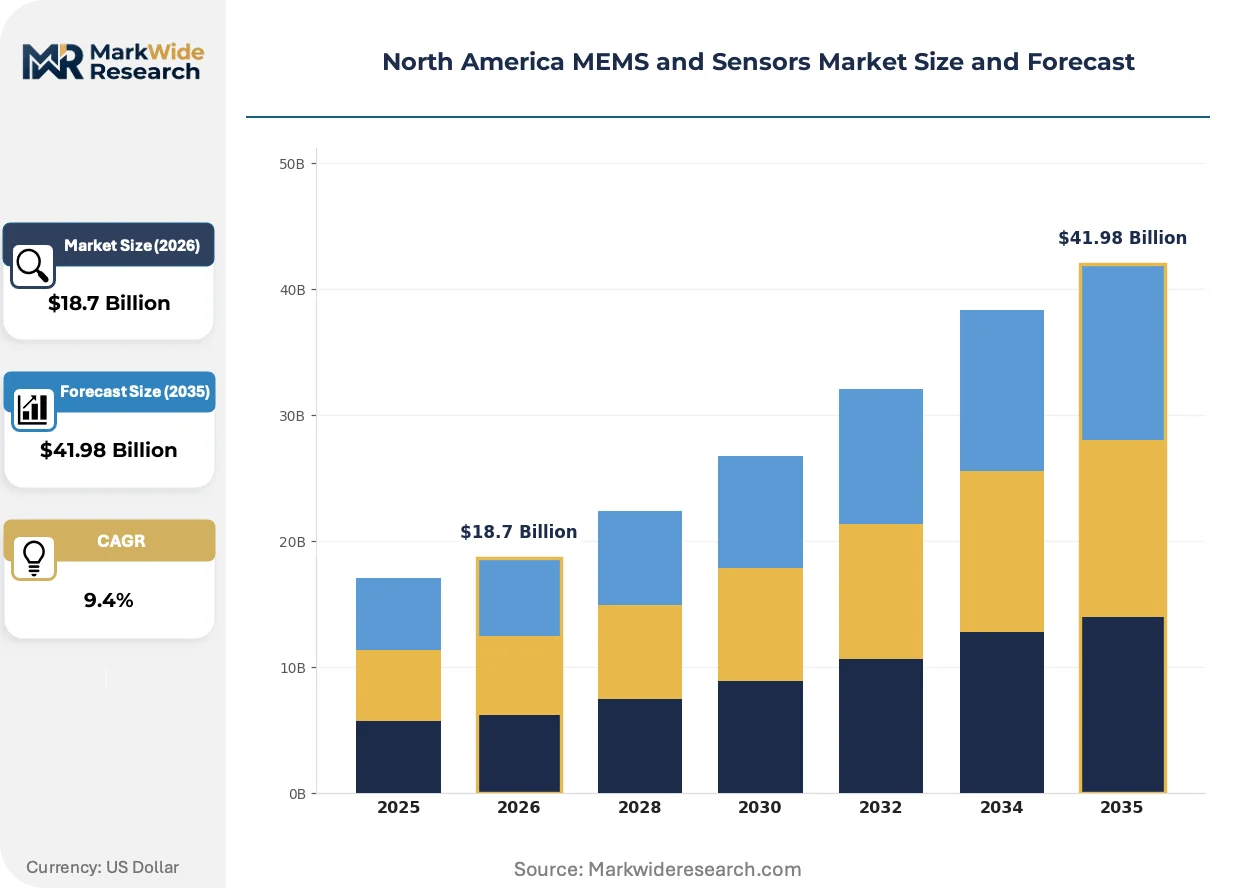
Market Dynamics
The U.S. CHIPS and Science Act has redirected semiconductor fabrication investment toward domestic MEMS foundries, collapsing the historical cost advantage of offshore analog wafer production and forcing fabless design houses to reassess captive versus outsourced manufacturing strategies.
Growth Catalysts
- Automotive safety mandates:NHTSA autonomous vehicle testing requirements are absorbing advanced inertial measurement units for collision avoidance and lane-keeping systems across Detroit and Stuttgart-aligned supply chains.
- EPA emissions monitoring:High-temperature exhaust gas sensors face expanded installation mandates in heavy-duty trucking and off-highway equipment, redirecting R&D spending toward ceramic packaging and signal conditioning.
- Silicon Valley design clusters:California's sensor design ecosystem is concentrating venture funding for fingerprint recognition modules and microphone arrays targeting wearable device OEMs.
Market Restraints
- 300mm analog wafer cost escalation:Backward integration into captive foundry capacity requires capital commitments exceeding fabless burn rates, compressing margin structures for mid-tier accelerometer suppliers.
- Automotive qualification cycles:AEC-Q100 stress testing and PPAP documentation timelines extend 18-24 months, gating revenue recognition for new pressure sensor platforms.
- Optical CMOS substitution:Standard CMOS image sensors are displacing MEMS-based microbolometers in low-resolution thermal imaging applications, constraining addressable market expansion.
Strategic Opportunities
- Underpenetrated Canadian medical devices:Health Canada biocompatibility pathways for implantable pressure monitors remain less contested than FDA 510(k) routes, offering faster regulatory arbitrage for cardiovascular sensor startups.
- Smart home ecosystem convergence:FCC Part 15 unlicensed spectrum rules are enabling integrated microphone-array and environmental-sensor nodes that combine voice recognition with air-quality monitoring.
- Michigan automotive electronics corridors:Tier 1 supplier co-location incentives around Detroit are creating captive demand for localized cleanroom capacity serving powertrain and chassis control modules.
Industry Challenges
- MEMS-specific process engineering talent:Bulk and surface micromachining expertise concentrates among aging specialists at legacy IDMs, constraining yield ramp timelines for new entrants.
- Multi-axis calibration complexity:Inertial measurement unit alignment across six degrees of freedom requires specialized test equipment and temperature compensation algorithms that extend factory cycle times.
- Wireless sensor node integration:Antenna-in-package design for FCC-compliant IoT deployments demands RF-MEMS co-design capabilities scarce among traditional mechanical sensor houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America MEMS and Sensors Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Accelerometers, Gyroscopes, Microphones End User: Consumer Electronics, Automotive, Healthcare, Industrial Equipment Technology: Optical Sensors, Thermal Sensors, MEMS Technology, Capacitive Sensors Application: Wearable Devices, Smart Homes, Automotive Safety, Industrial Automation |
| Companies Covered | Analog Devices, Inc., STMicroelectronics, Texas Instruments Incorporated, NXP Semiconductors, Robert Bosch GmbH, Panasonic Corporation of North America, Murata Manufacturing Co., Ltd, Honeywell International Inc., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America MEMS and Sensors Market Evolving Landscape
Capacitive sensing architectures are bifurcating the competitive landscape between precision-focused healthcare diagnostics and cost-optimized consumer electronics, while regulatory pressure on autonomous vehicle safety and emissions monitoring accelerates sensor fusion requirements.
MEMS Technology is bifurcating into two distinct commercialization tracks. Capacitive microstructures for fingerprint recognition modules deliver biometric security in smartphones and wearables. Automotive OEMs in Detroit and California are adopting these same architectures for human-machine interface controls at accelerated procurement cycles. The technology is bifurcating the supplier base between precision-focused foundries serving medical diagnostics and high-volume operators optimized for consumer price points.
NHTSA autonomous vehicle testing mandates are compressing development timelines for multi-axis inertial units. The regulations require redundant sensor configurations for lane-keeping and emergency braking validation. Tier 1 suppliers serving Detroit automakers are responding with dedicated cleanroom capacity for automotive-grade accelerometer production. Michigan's electronics corridors are absorbing the capital influx as Stuttgart-aligned operations localize North American supply.
Buyers in California's Silicon Valley clusters are consolidating procurement around sensor fusion platforms that combine accelerometer, gyroscope, and pressure data. Component distributors are losing share to direct OEM relationships as design houses seek tighter integration between MEMS design and system-level algorithm development. This pattern is most visible in wearable device supply chains where fingerprint recognition and environmental monitoring converge in single-package solutions.
North America MEMS and Sensors Market Segmentation
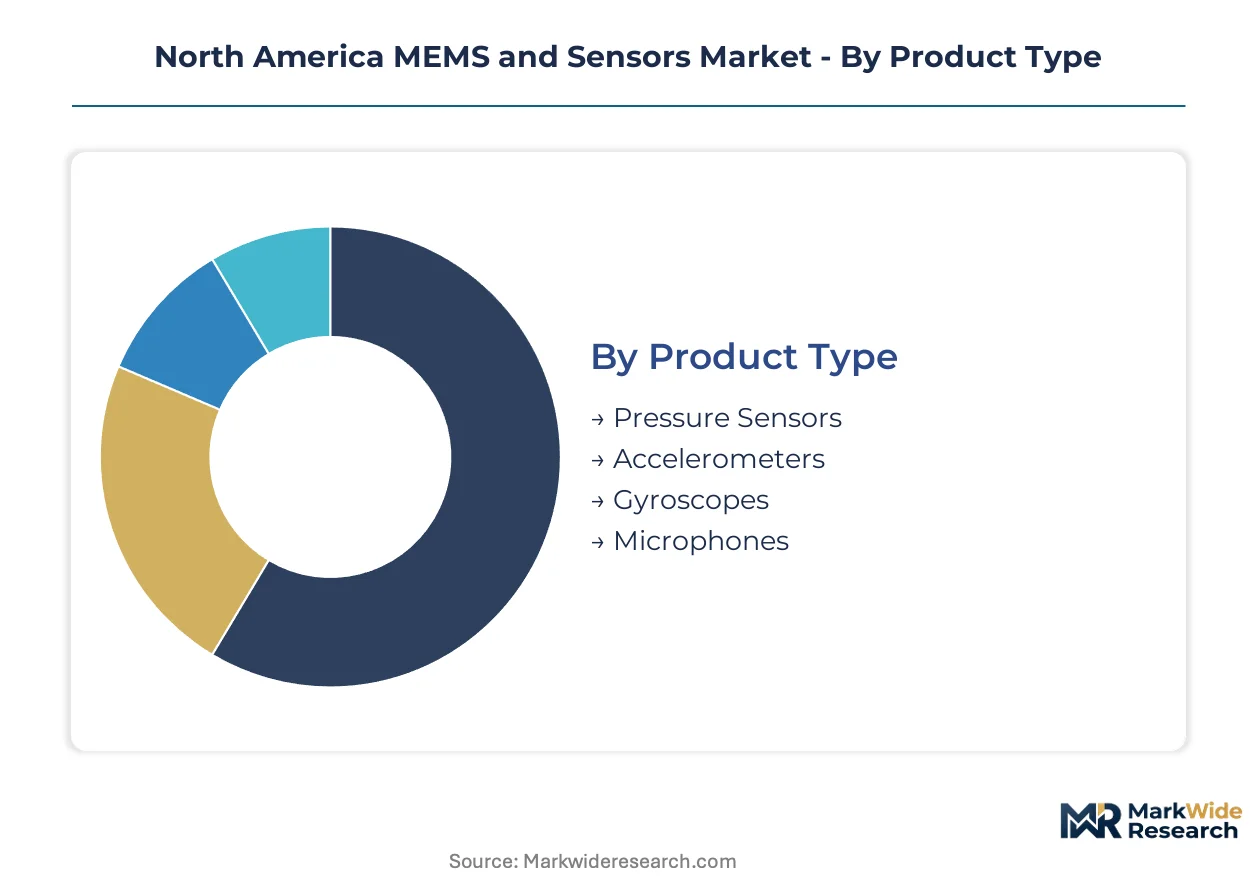
MEMS and sensors demand fragments across incompatible qualification regimes—automotive AEC-Q100 stress testing, FDA biocompatibility pathways, and FCC Part 15 emissions limits—forcing suppliers to specialize rather than span all verticals. Margin pools concentrate where certification complexity erects barriers: automotive safety systems and implantable healthcare devices command premium pricing against commoditized consumer electronics procurement.
Product Type:
Pressure sensors and accelerometers absorb the highest gross margins in automotive and industrial verticals, where temperature extremes and vibration immunity justify specialized packaging and signal conditioning.
- Pressure Sensors:Piezoresistive and capacitive transduction elements measure absolute, differential, or gauge pressure in engine management, HVAC controls, and medical infusion pumps. Automotive applications in Michigan's electronics corridors dominate procurement volume, with EPA emissions monitoring mandates driving ceramic-packaged exhaust gas variants.
- Accelerometers:Multi-axis inertial measurement units combine micromachined proof masses with capacitive sensing for collision detection, stability control, and consumer motion tracking. NHTSA autonomous vehicle testing requirements in the United States are absorbing six-degree-of-freedom units with redundant sensor configurations for lane-keeping validation.
- Gyroscopes:Coriolis-effect vibratory structures detect rotational rate for navigation stabilization and image stabilization in cameras.
- Microphones:Capacitive MEMS diaphragms convert acoustic pressure to electrical signals for voice recognition in smart home ecosystems and wearable devices.
The dominant share belongs to Pressure Sensors, while Accelerometers is closing the gap fastest.
End User:
Customer procurement patterns split between high-volume, low-margin consumer contracts and low-volume, high-margin safety-critical qualification cycles.
- Automotive:Tier 1 suppliers in Detroit and Stuttgart-aligned operations source accelerometers, pressure sensors, and gyroscopes for powertrain, chassis, and ADAS modules. AEC-Q100 qualification and PPAP documentation extend 18-24 month development timelines, gating revenue recognition but protecting margin structures.
- Healthcare:Implantable pressure monitors and diagnostic sensor platforms face FDA and Health Canada biocompatibility enforcement, with electromagnetic compatibility standards gating market entry. Cardiovascular sensor startups are exploiting faster Health Canada pathways versus FDA 510(k) routes.
- Consumer Electronics:California's Silicon Valley design clusters concentrate venture funding for fingerprint recognition modules and microphone arrays targeting smartphone and wearable OEMs.
- Industrial Equipment:High-temperature and corrosive environment sensors serve process automation, predictive maintenance, and emissions monitoring applications.
Automotive commands the largest revenue pool, with Healthcare expanding most quickly on regulatory arbitrage opportunities.
Technology:
Process maturity and fabrication cost structures determine competitive moat durability across sensing architectures.
- MEMS Technology:Bulk and surface micromachining of silicon substrates creates mechanical structures with feature resolutions below 100 micrometers for inertial, pressure, and acoustic sensing. The category bifurcates between precision-focused foundries serving medical diagnostics and high-volume operators optimized for consumer price points.
- Capacitive Sensors:Parallel-plate or interdigitated electrode configurations detect displacement, proximity, or force with low power consumption and high sensitivity. Fingerprint recognition modules and human-machine interface controls in automotive and consumer applications are climbing the fastest.
- Optical Sensors:Photodiode arrays and interferometric structures measure intensity, wavelength, or phase for healthcare diagnostics and industrial metrology where precision exceeds standard CMOS capabilities.
- Thermal Sensors:Thermopile and microbolometer architectures detect infrared radiation for temperature measurement and thermal imaging, facing displacement by standard CMOS image sensors in low-resolution applications.
MEMS Technology holds the installed base advantage, though Capacitive Sensors is gaining share fastest on biometric and HMI demand convergence.
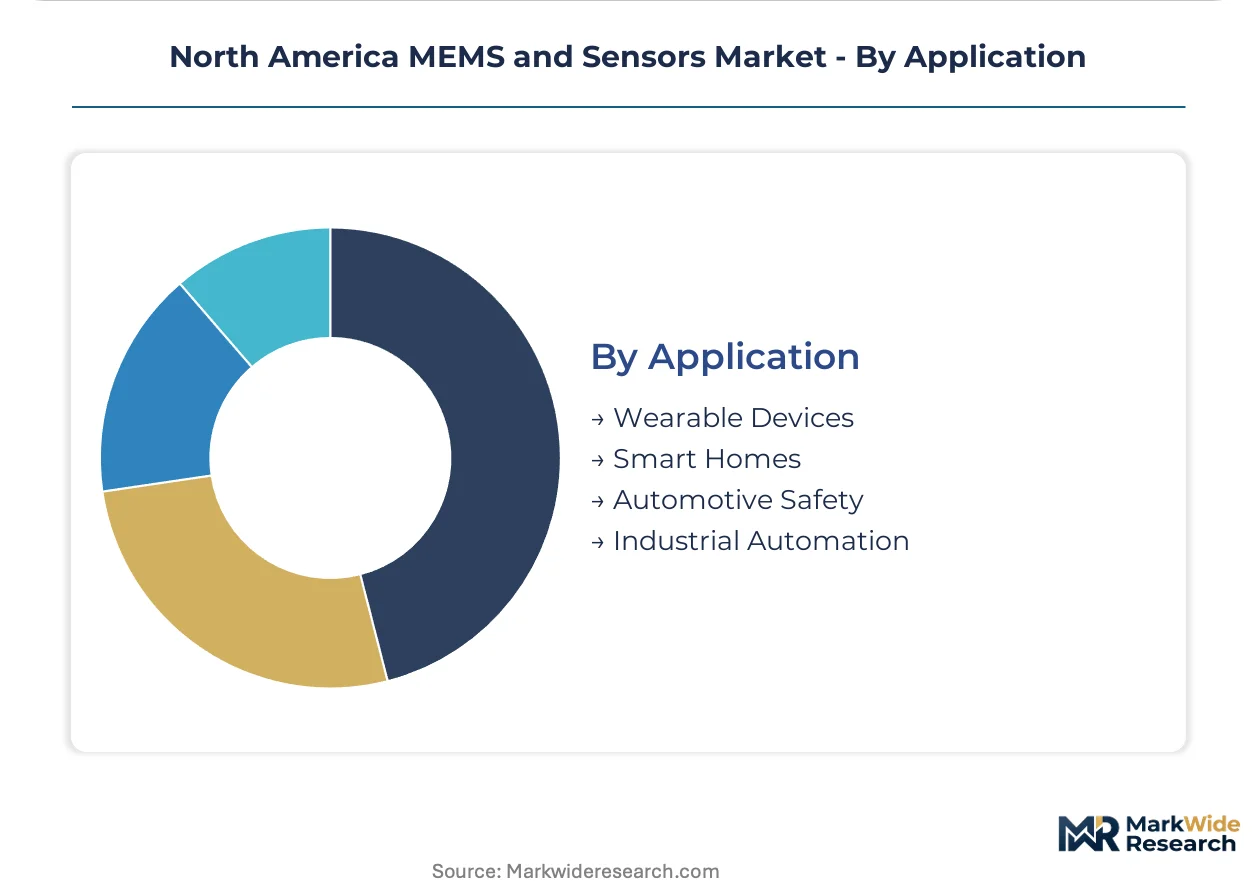
Application:
Use-case integration complexity determines whether suppliers sell discrete components or capture value through sensor fusion platforms.
- Automotive Safety:Redundant inertial measurement units, pressure sensors, and radar interfaces enable collision avoidance, emergency braking, and lane-keeping systems. NHTSA mandates are compressing development timelines and consolidating procurement around multi-axis units.
- Smart Homes:Environmental monitoring nodes combine voice recognition, air quality sensing, and occupancy detection. FCC Part 15 unlicensed spectrum rules are enabling integrated microphone-array and sensor convergence.
- Wearable Devices:Fingerprint recognition, motion tracking, and physiological monitoring integrate in single-package solutions. Design houses are bypassing distributors for direct OEM relationships to tighten algorithm-sensor integration.
- Industrial Automation:Predictive maintenance and process control applications demand ruggedized packaging and wireless sensor node integration with antenna-in-package RF-MEMS co-design.
Automotive Safety retains the dominant position, while Smart Homes is closing fastest on ecosystem convergence and unlicensed spectrum enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Michigan's automotive corridors exceeds that of Ontario's medical device clusters by roughly 15-20% on comparable pressure sensor platforms, reflecting divergent qualification regimes and captive demand concentration.
United States
Detroit's Tier 1 supplier ecosystem and California's Silicon Valley design houses absorb divergent MEMS categories—automotive safety modules versus biometric consumer platforms. NHTSA autonomous vehicle mandates and EPA emissions monitoring redirect R&D toward multi-axis inertial units and high-temperature exhaust sensors. Michigan's electronics corridors concentrate cleanroom capacity serving powertrain and chassis control modules.
Canada
Cardiovascular sensor startups exploit Health Canada's biocompatibility pathways, achieving faster regulatory clearance than FDA 510(k) routes for implantable pressure monitors. Ontario's medical device manufacturing base absorbs specialized packaging for diagnostic platforms. Toronto-Waterloo corridor clusters attract venture funding for physiological monitoring wearables.
Mexico
Bajío Region automotive assembly plants generate pull-through demand for pressure sensors and accelerometers in powertrain modules, though most value-add fabrication remains US-based. Nuevo León's electronics manufacturing services sector handles final test and calibration for Detroit-bound components. Maquiladora operations concentrate on labor-intensive packaging steps rather than front-end micromachining.
North America MEMS and Sensors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated structure where precision-focused foundries serving medical diagnostics coexist with high-volume operators optimized for consumer price points. The vendor base spans vertically integrated IDMs with captive 300mm analog wafer fabrication and fabless design houses reassessing outsourcing strategies under CHIPS Act incentives. Two archetypes dominate: backward-integrated specialists controlling yield through in-house production, and ecosystem-integrated players leveraging direct OEM relationships for sensor fusion platforms. Competitive moves concentrate on geographic expansion into Michigan's automotive corridors and portfolio diversification across biometric and environmental sensing.
Among European-anchored diversified industrials, Robert Bosch GmbH and STMicroelectronics exemplify the backward-integrated archetype, while Texas Instruments Incorporated occupies a position representing US-based analog semiconductor integration. These three anchors illustrate how competitive positioning depends on wafer fabrication control and automotive qualification depth rather than design-only agility.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| STMicroelectronics |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Robert Bosch GmbH |
| Panasonic Corporation of North America |
| Murata Manufacturing Co., Ltd |
| Honeywell International Inc. |
| Infineon Technologies AG |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month automotive qualification cycles compress working capital efficiency for MEMS suppliers, concentrating pricing power among backward-integrated IDMs with captive cleanroom capacity while fabless design houses absorb margin erosion from wafer cost escalation.
Pricing Analysis
The customization-premium spread widens to 40-60% between AEC-Q100 qualified automotive-grade units and standard consumer accelerometers. Pricing stratifies across premium, standard, and economy tiers driven by certification level and volume scale. Cost compression in consumer-grade fingerprint modules intensifies as smartphone OEMs consolidate procurement around sensor fusion platforms. Tier 1 automotive suppliers exhibit lowest price sensitivity due to liability exposure and safety-critical validation requirements.
Supply Chain Analysis
The United States anchors front-end MEMS fabrication through Michigan's automotive cleanroom corridors and California's design clusters, while Mexico's Bajío Region handles final test and calibration for Detroit-bound powertrain modules. Raw material dependencies center on silicon wafers, ceramic packaging substrates, and specialized etching gases. Single-source vulnerability concentrates in 300mm analog wafer supply where Texas Instruments and STMicroelectronics maintain captive capacity. Distribution runs through direct OEM relationships that bypass traditional component distributors for algorithm-integrated sensor platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America MEMS and Sensors Market represents a high-growth disruption as NHTSA autonomous vehicle mandates and EPA emissions monitoring redirect R&D spending toward multi-axis inertial units and high-temperature exhaust gas sensors.
For Market Incumbents: Shield automotive margin pools by deepening backward integration into 300mm analog wafer fabrication and accelerating AEC-Q100 qualification cycles for next-generation pressure sensors. Consolidate procurement relationships with Detroit Tier 1 suppliers before fabless entrants capture share through CHIPS Act subsidized foundry capacity. For New Entrants and Emerging Players: Lead with Health Canada biocompatibility arbitrage for implantable cardiovascular pressure monitors, exploiting faster regulatory pathways than FDA 510(k) routes. Target Ontario's medical device manufacturing base with specialized ceramic packaging capabilities. Pursue direct OEM relationships with wearable device houses in California's Silicon Valley clusters to bypass distributor margin extraction. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MEMS-specific process engineering talent concentrates among aging specialists at legacy IDMs, constraining yield ramp timelines for new entrants. Acquire precision-focused foundries serving medical diagnostics before automotive qualification depth becomes the sole competitive moat. Watch NHTSA autonomous vehicle testing mandate expansion as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 300mm Wafer Fabrication | Captive supply of analog wafers insulates Texas Instruments and STMicroelectronics from foundry cost escalation. |
| AEC-Q100 Accelerated Qualification Programs | Compressed 18-24 month validation timelines gate revenue recognition for automotive safety module suppliers. |
| Health Canada Regulatory Arbitrage | Faster biocompatibility pathways enable cardiovascular sensor startups to outpace FDA 510(k) competitors. |
| Direct OEM Relationship Development | Bypassing distributors allows design houses to tighten algorithm-sensor integration for wearable platforms. |
| Sensor Fusion Platform Convergence | Integrated microphone-array and environmental nodes combine voice recognition with air-quality monitoring under FCC Part 15 rules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, NHTSA autonomous vehicle testing documentation, EPA emissions monitoring standards, and semiconductor trade association data. The research program combined structured interviews with MEMS process engineers, Tier 1 automotive procurement directors, biomedical device regulatory affairs leads, and venture capital partners focused on sensor hardware. Bottom-up demand modeling triangulated against top-down wafer capacity analysis validated volume and value estimates.
Segmentation dimensions modeled span product type, end user vertical, micromachining technology, and application use case across the analysis window. Automotive content per vehicle, healthcare implantable unit volumes, and consumer electronics procurement contract structures fed the quantitative framework. CAGRs derived from regression analysis against historical qualification cycle timelines and foundry capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained CHIPS Act funding levels, NHTSA mandate enforcement intensity, or Health Canada regulatory pathway stability would require recalibration. Forecasts reflect assumptions about automotive electrification penetration and wearable device sensor integration trends. Recalibration cycles align with material shifts in foundry cost structures and autonomous vehicle safety regulation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market