
 Piezoelectric Actuators Market | 2026-2036
Piezoelectric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Actuators Market Analysis
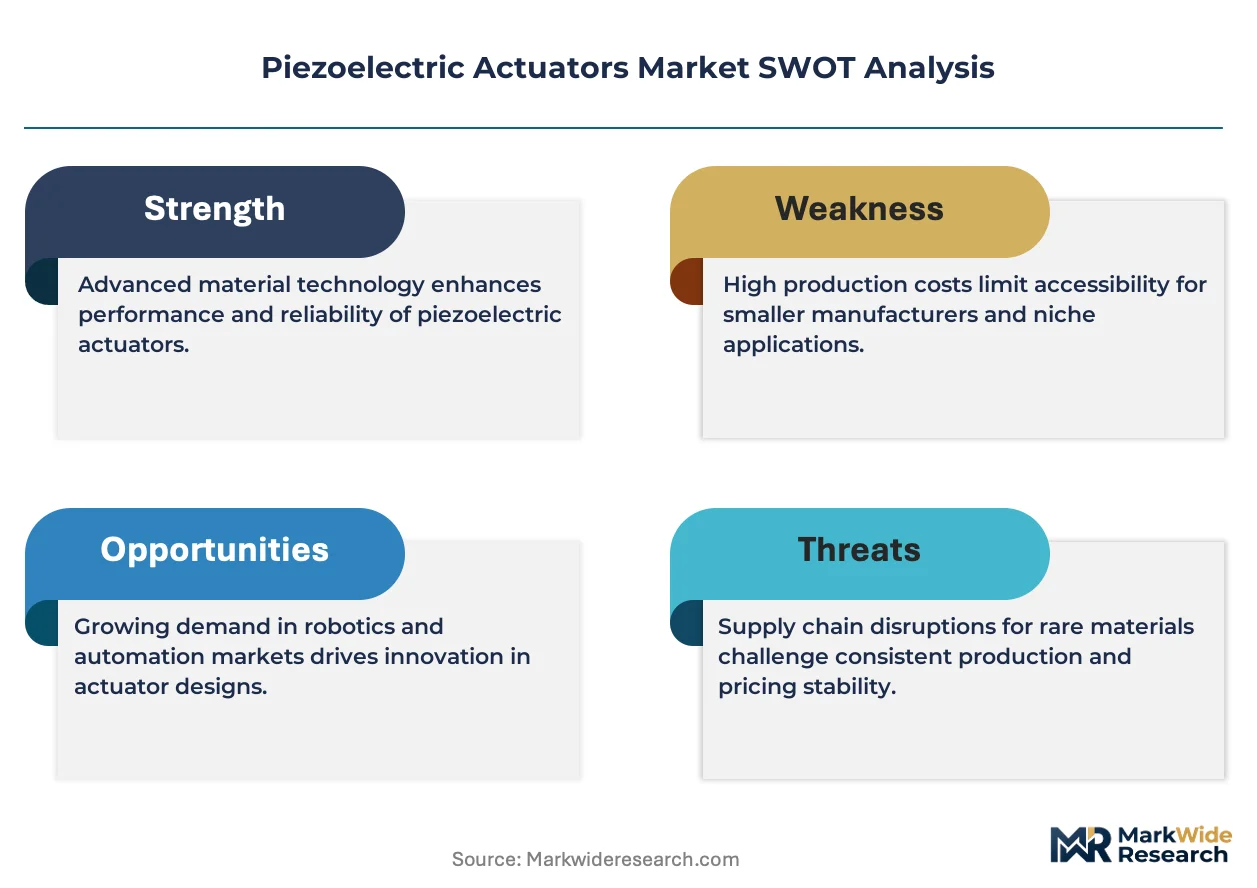
REACH is rebalancing material compliance costs for European manufacturers of lead-based piezoelectric ceramics. CTS Corporation leverages captive ceramic fabrication to absorb regulatory transition expenses without outsourcing. Kyocera Corporation anchors its actuator portfolio on vertically integrated piezoelectric material science spanning substrate growth through finished assembly.
Piezoelectric actuators convert electrical energy into precise mechanical displacement through crystalline lattice deformation, typically achieving sub-nanometer resolution with response times under microseconds for optical alignment and microfluidic control. Stack actuators dominate precision positioning revenue owing to their force density and mature supply chain, while polymer-based variants capture emerging robotics interest through conformable geometries that rigid ceramic stacks cannot match. Linear actuators sustain the largest installed base across semiconductor wafer stages, though ultrasonic actuators penetrate acoustic device applications where resonant frequency operation outweighs static positioning requirements.
FDA device clearance timelines shape healthcare actuator qualification cycles in the United States, while ECHA substance restrictions redirect European procurement toward compliant material certifications. ISO standardization for piezoelectric measurement protocols reduces cross-border qualification friction for Japanese and Korean suppliers. Stakeholders must calibrate R&D allocation between lead-free ceramic formulations and polymer alternatives before regulatory deadlines harden material specifications.
Market Dynamics
Semiconductor node shrinkage below 3nm is compressing positioning tolerances to sub-atomic scales, forcing actuator architectures toward multi-axis nanopositioning stacks with integrated strain feedback loops that legacy open-loop designs cannot satisfy.
Growth Catalysts
- Sub-3nm lithography nodes:Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying piezoelectric wafer stages for extreme ultraviolet patterning, absorbing multi-thousand-unit actuator volumes per fabrication facility.
- Japan METI manufacturing subsidies:The Ministry of Economy, Trade and Industry funds domestic robotics actuator procurement, reinforcing export-oriented medical device and precision automation supply chains.
- Lead-free ceramic formulations:ECHA REACH restrictions on lead-based PZT are accelerating qualified substitutions across European semiconductor equipment supply chains ahead of 2027 enforcement deadlines.
Market Restraints
- Raw material concentration:High-purity zirconium feedstock for PZT ceramics concentrates in Chinese and Russian mining operations, exposing processors to geopolitical supply interruptions.
- Technical displacement ceiling:Voice coil motors retain cost advantages in coarse positioning above 100 micrometers, capping piezoelectric penetration in lower-precision industrial automation.
- REACH compliance friction:European manufacturers face 18-24 month requalification cycles for lead-free actuator variants, freezing procurement decisions during transition periods.
Strategic Opportunities
- Conformable polymer actuators:Soft robotics and wearable haptic interfaces in South Korea and Japan are piloting PVDF-TrFE film actuators for applications where ceramic brittleness disqualifies traditional stacks.
- India PLI scheme alignment:Production-linked incentives for semiconductor packaging and medical device manufacturing are creating first-mover advantages for actuator suppliers establishing local calibration facilities.
- ISO 16063-41 vibration calibration:Standardized piezoelectric measurement protocols are reducing cross-border qualification friction for Japanese and Korean suppliers entering European metrology markets.
Industry Challenges
- Multi-physics simulation expertise:Coupled electromechanical-thermal modeling for stack actuator design requires rare combinations of materials science and finite element analysis capabilities that contract engineering pools cannot reliably supply.
- FDA 510(k) clearance timelines:Surgical robotics and drug delivery actuator modules face 12-18 month qualification cycles in the United States, compressing product refresh rates against semiconductor equipment cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Actuators Market |
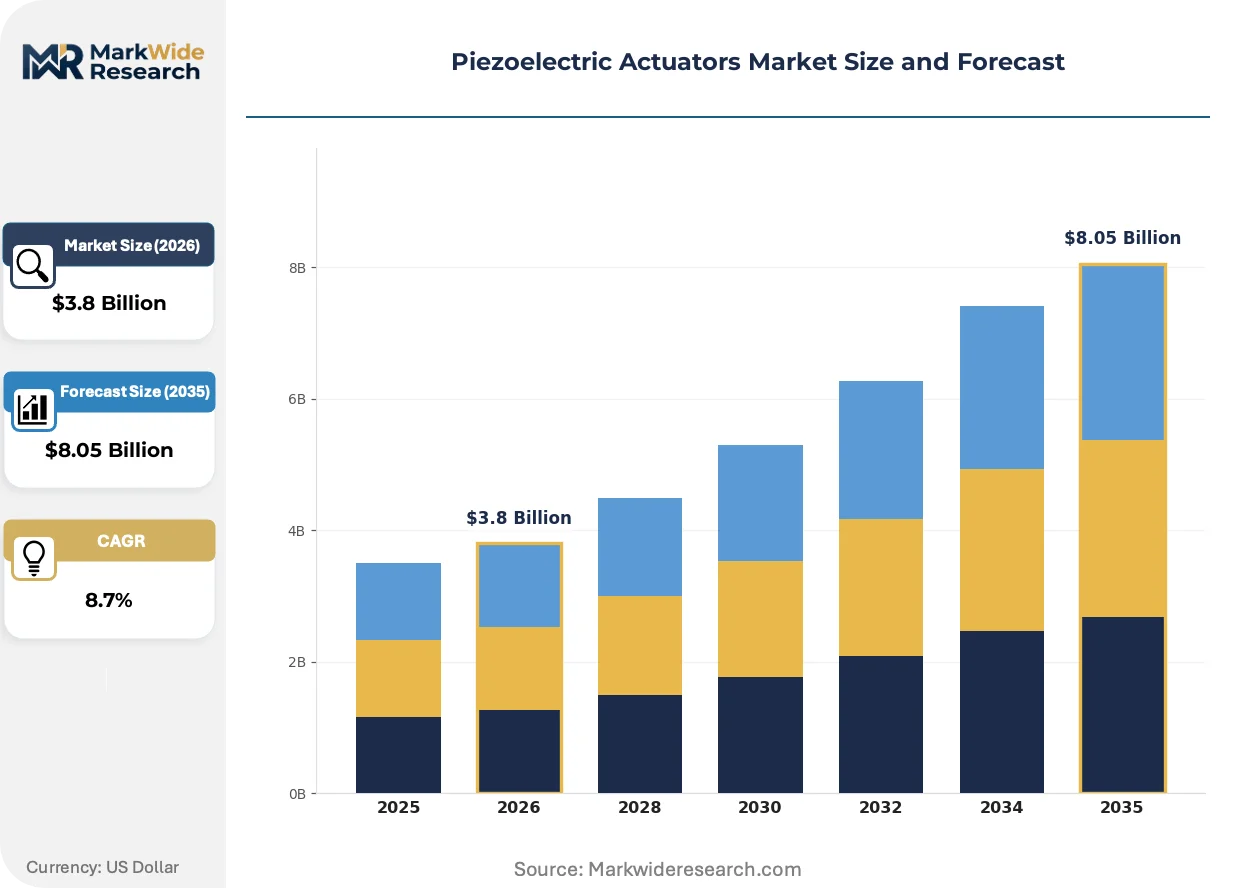
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotational Actuators, Ultrasonic Actuators, Stack Actuators Technology: PZT, PMN-PT, Polymer-based, Quartz End User: Automotive, Aerospace, Robotics, Healthcare Application: Precision Positioning, Vibration Control, Micro-manipulation, Acoustic Devices |
| Companies Covered | CTS Corporation, Kyocera Corporation, Physik Instrumente (PI), Cedrat Technologies, APC International, TDK Corporation, CeramTec GmbH, Piezosystem Jena, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Actuators Market Emerging Trajectories
Actuator architectures are bifurcating between ultra-precision ceramic stacks for established semiconductor applications and conformable polymer alternatives for emerging robotics and medical modalities, with hybrid designs bridging performance gaps in multi-domain systems.
Monolithic multi-layer ceramic stack technology is consolidating precision positioning market share through integrated strain-gauge feedback and temperature-compensated drive electronics. ASML and Nikon lithography divisions specify these architectures for immersion scanner wafer stages. The technology is consolidating supplier bases toward captive ceramic fabrication capabilities that external module assemblers cannot replicate without capital commitments exceeding $50 million.
REACH substance restrictions are forcing material transitions across European industrial automation supply chains. ECHA authorization requirements for lead compounds in PZT ceramics are redirecting procurement toward qualified lead-free formulations from Japanese and Korean material suppliers. German semiconductor equipment manufacturers are absorbing 15-20% material cost premiums during multi-year qualification transitions.
After-sales service unbundling is disrupting traditional actuator procurement in North American medical device manufacturing. Original equipment manufacturers are separating hardware supply from calibration and recertification contracts, enabling third-party metrology laboratories to capture recurring revenue streams. This pattern concentrates in FDA-regulated surgical robotics clusters around Boston and Minneapolis.
Piezoelectric Actuators Market Segmentation
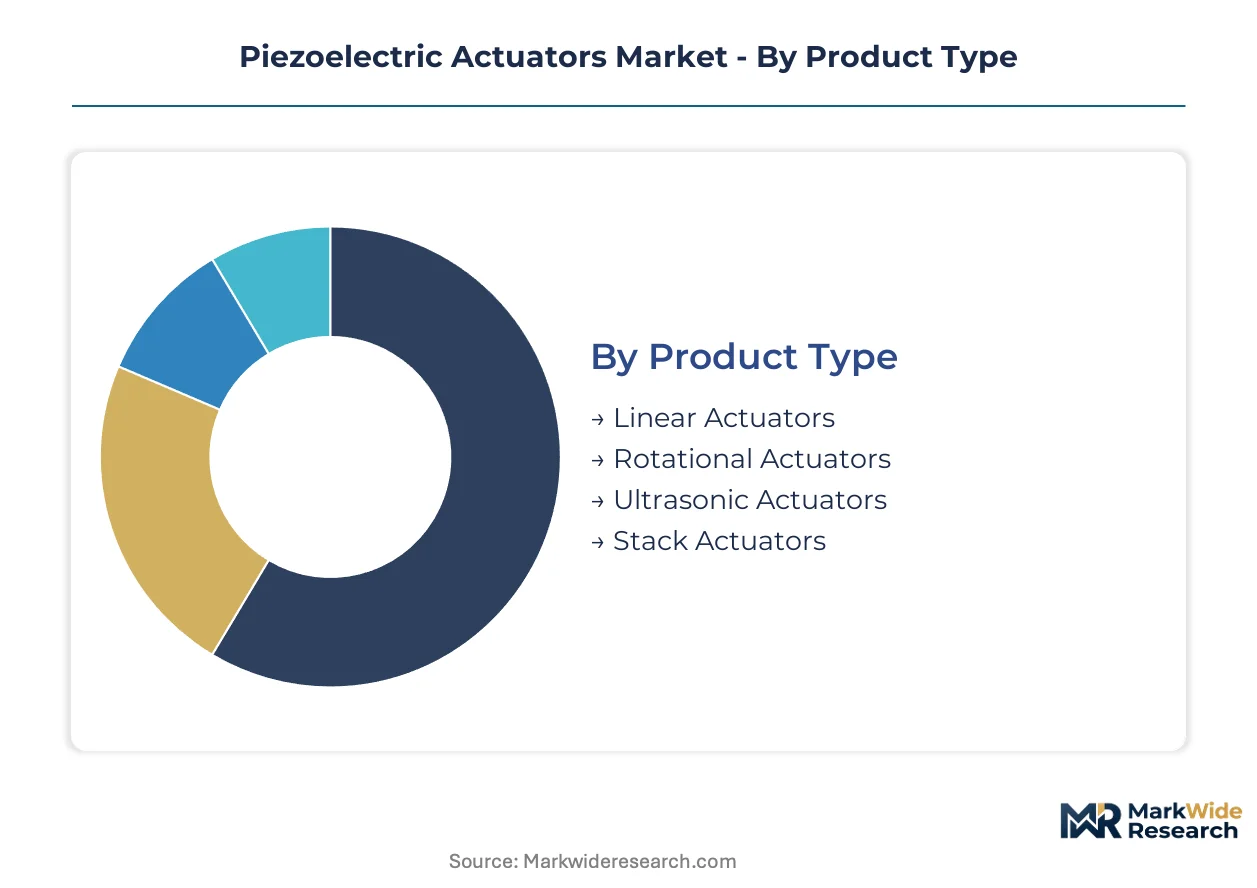
Piezoelectric actuator procurement patterns diverge sharply across certification regimes. Semiconductor equipment demands ISO-calibrated traceability, while medical robotics triggers FDA or PMDA clearance cycles that stretch supplier qualification timelines.
Product Type:
FDA 510(k) pathways govern surgical robotics actuators in the United States, while semiconductor wafer stages require ISO 16063-41 vibration calibration certificates for cross-border acceptance.
- Stack Actuators:Monolithic multi-layer ceramic architectures achieve sub-nanometer resolution through integrated strain-gauge feedback. Taiwan Semiconductor Manufacturing and Samsung Foundry absorb multi-thousand-unit volumes per EUV lithography facility as node shrinkage compresses positioning tolerances.
- Linear Actuators:Sustaining the largest installed base across semiconductor wafer stages, these architectures deliver precise linear displacement through crystalline lattice deformation. Nikon and ASML lithography divisions specify linear configurations for immersion scanner stages, though voice coil motors retain cost advantages above 100 micrometers.
- Rotational Actuators:Precision angular positioning for optical alignment systems in Japanese and Korean metrology equipment.
- Ultrasonic Actuators:Resonant frequency operation for acoustic device applications where static positioning requirements yield to vibrational energy transfer.
Stack Actuators sits at the top of the volume ranking, with Linear Actuators climbing the fastest.
Technology:
Material selection directly determines REACH compliance burden for European manufacturers, with lead-free formulations commanding 15-20% cost premiums during multi-year qualification transitions.
- PZT:Lead zirconate titanate ceramics dominate precision positioning through mature supply chains and established electromechanical coupling coefficients. ECHA authorization requirements are redirecting European procurement toward qualified lead-free substitutions ahead of enforcement deadlines.
- PMN-PT:Single-crystal relaxor ferroelectrics deliver superior strain response for medical ultrasound transducers and high-force precision stages. Japanese material suppliers anchor supply through vertically integrated substrate growth capabilities.
- Polymer-based:PVDF-TrFE film actuators enable conformable geometries for soft robotics and wearable haptic interfaces in South Korean pilot programs.
- Quartz:Piezoelectric stability for frequency control applications in telecommunications and timing devices.
PZT holds the dominant revenue position, though PMN-PT gains share fastest in medical imaging modalities.
End User:
Customer type shapes service unbundling patterns, with North American medical device manufacturers separating hardware supply from third-party calibration contracts.
- Healthcare:Surgical robotics and drug delivery modules face 12-18 month FDA clearance timelines in the United States, compressing product refresh rates. Boston and Minneapolis clusters concentrate after-sales service unbundling toward third-party metrology laboratories.
- Robotics:METI-funded advanced manufacturing programs in Japan reinforce domestic actuator consumption for export-oriented medical device and precision automation supply chains.
- Automotive:Precision fuel injection and active suspension systems with escalating electrification content.
- Aerospace:Vibration suppression and adaptive wing surfaces under FAA airworthiness certification protocols.
Healthcare commands the highest unit margins, with Robotics expanding most quickly through government-funded procurement.
Application:
Functional use case determines feedback architecture requirements, with closed-loop strain compensation becoming mandatory below 3nm lithography nodes.
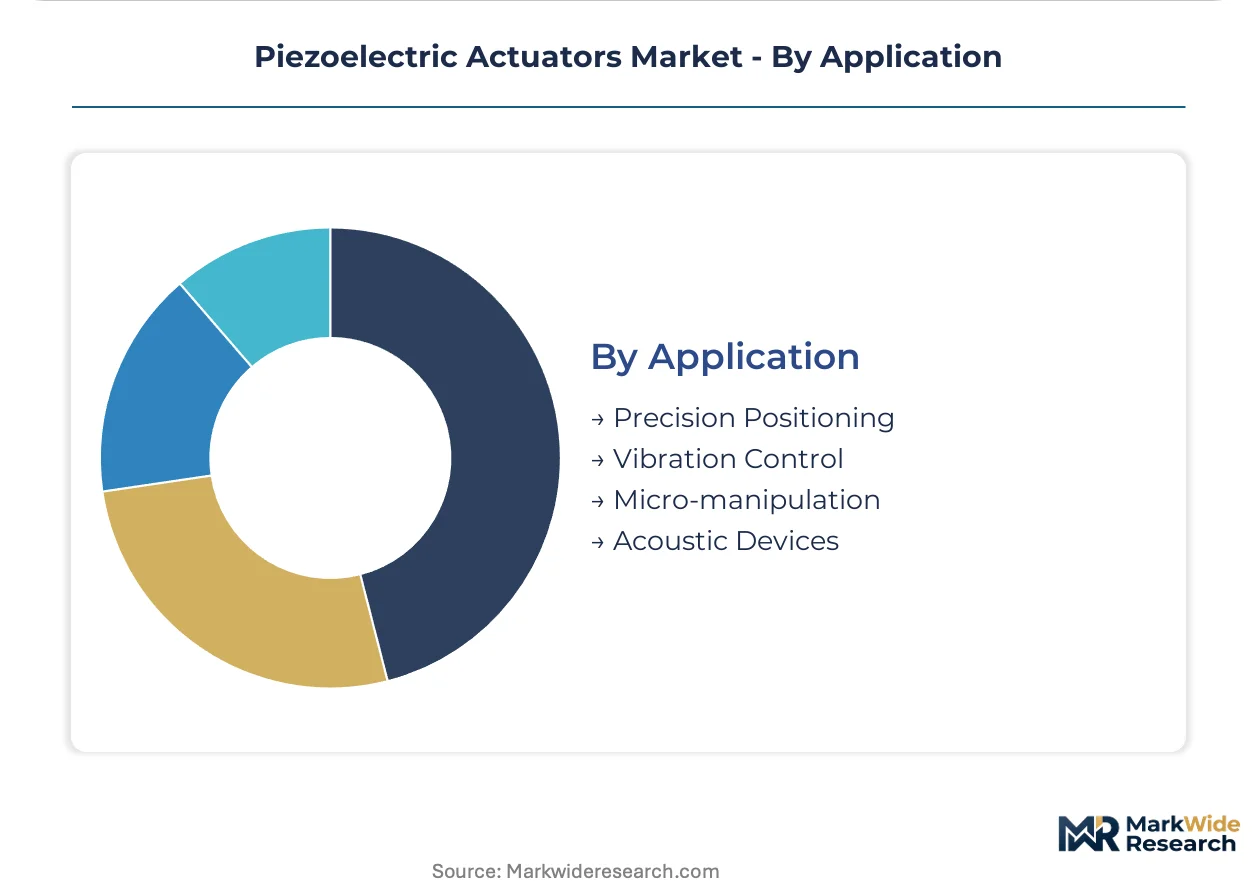
- Precision Positioning:Multi-axis nanopositioning stacks with integrated strain feedback loops satisfy sub-atomic tolerance requirements for EUV patterning. Open-loop designs face technical displacement as Taiwan Semiconductor Manufacturing and Samsung Foundry qualify next-generation wafer stages.
- Vibration Control:Active damping systems for semiconductor manufacturing equipment and precision metrology platforms requiring ISO-standardized calibration protocols.
- Micro-manipulation:Cell surgery and material science research platforms with sub-micron resolution requirements.
- Acoustic Devices:Resonant frequency operation for ultrasound imaging and industrial cleaning systems where static positioning yields to vibrational energy transfer.
Precision Positioning generates the largest revenue pool, with Vibration Control gaining traction fastest through metrology standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and precision engineers concentrate in Japanese and German industrial clusters, anchoring piezoelectric actuator fabrication expertise. Taiwan and South Korean semiconductor ecosystems absorb the highest actuator volumes per capita. North American medical device corridors sustain specialized qualification capabilities.
Japan
Domestic robotics and precision automation manufacturers absorb substantial actuator volumes through METI-funded procurement programs. PMDA medical device clearance protocols shape qualification timelines for surgical robotics exports. The Kanto region around Tokyo hosts vertically integrated ceramic fabrication facilities serving lithography equipment makers.
Germany
ECHA REACH restrictions on lead-based PZT ceramics are redirecting procurement toward qualified lead-free formulations from Japanese material suppliers. German semiconductor equipment manufacturers absorb 15-20% material cost premiums during multi-year qualification transitions. The Baden-Württemberg precision engineering corridor anchors metrology equipment production requiring ISO-standardized vibration calibration.
United States
FDA 510(k) clearance timelines stretch 12-18 months for surgical robotics and drug delivery actuator modules. Boston and Minneapolis medical device clusters concentrate after-sales service unbundling toward third-party metrology laboratories. Domestic semiconductor packaging facilities are qualifying piezoelectric stages for advanced node production.
Taiwan
TSMC and foundry competitors are qualifying piezoelectric wafer stages for extreme ultraviolet patterning below 3nm nodes. Each fabrication facility absorbs multi-thousand-unit actuator volumes. The Hsinchu Science Park anchors precision equipment supply chains with captive calibration capabilities.
South Korea
Samsung Foundry and domestic memory manufacturers drive precision positioning demand for sub-atomic tolerance requirements. Government-funded pilot programs are testing PVDF-TrFE film actuators for soft robotics and wearable haptic interfaces. The Seoul Capital Area concentrates materials research institutions advancing polymer-based formulations.
Piezoelectric Actuators Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material science and precision assembly capabilities. The vendor base stratifies between captive ceramic fabricators and external module assemblers lacking upstream material control. Three archetypes dominate: vertically integrated Japanese conglomerates, German precision engineering specialists, and North American diversified electronics suppliers. Competitive moves concentrate on backward integration into ceramic feedstock and geographic expansion through local calibration facilities.
Among Japanese conglomerates with captive material science capabilities, Kyocera Corporation and TDK Corporation exemplify the vertically integrated archetype spanning substrate growth through finished assembly. German precision specialists CeramTec GmbH and Piezosystem Jena occupy positions requiring ISO-standardized measurement protocols for European metrology market entry. CTS Corporation represents the North American diversified electronics supplier model leveraging in-house ceramic fabrication to absorb regulatory transition expenses.
| Leading Market Players |
|---|
| CTS Corporation |
| Kyocera Corporation |
| Physik Instrumente (PI) |
| Cedrat Technologies |
| APC International |
| TDK Corporation |
| CeramTec GmbH |
| Piezosystem Jena |
| Murata Manufacturing |
| Others |
Supply Flow & Price Mechanics
ECHA REACH authorization deadlines for lead-based PZT ceramics gate both qualified supply access and premium-tier pricing power, forcing European semiconductor equipment manufacturers to absorb material cost premiums while Japanese and Korean suppliers capture margin expansion through compliant formulation dominance.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across end-use segments. Medical device manufacturers in Boston and Minneapolis clusters increasingly separate hardware procurement from third-party calibration contracts, while semiconductor wafer stages retain integrated service bundles. Price differentiation hinges on ISO 16063-41 certification grade and captive ceramic fabrication capability. Cost compression in standard-tier stack actuators intensifies as voice coil motors press from above 100 micrometers. Robotics OEMs exhibit highest price sensitivity; lithography equipment makers show lowest.
Supply Chain Analysis
Reverse-logistics flows for strain-gauge recalibration and ceramic stack refurbishment concentrate service revenue in Japanese and German precision engineering corridors. High-purity zirconium feedstock draws from Chinese and Russian mining operations, tethering PZT ceramic production to geopolitical supply interruptions. Lead-free piezoelectric formulations rest on Japanese and Korean material science capabilities. Single-source vulnerability pervades relaxor ferroelectric substrate growth. Distribution runs through captive fabrication facilities for tier-one lithography suppliers and modular assemblers for secondary automation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piezoelectric actuators market compounds steadily as sub-3nm lithography nodes force positioning tolerance compression that legacy electromagnetic technologies cannot satisfy.
For Market Incumbents: Lock in captive ceramic fabrication capacity before ECHA REACH enforcement hardens material specifications. Kyocera Corporation and TDK Corporation demonstrate how substrate-to-assembly vertical integration absorbs regulatory transition costs that external module assemblers cannot replicate. Prioritize lead-free formulation R&D to defend margin position against qualified Japanese and Korean material suppliers. Expand local calibration facilities in Taiwan and South Korea to match TSMC and Samsung Foundry procurement localization requirements. For New Entrants and Emerging Players: The premium-to-economy price-point gap in surgical robotics actuators offers white-space entry below FDA-cleared incumbent pricing. Target South Korean government-funded PVDF-TrFE pilot programs for soft robotics and wearable haptic interfaces where ceramic brittleness disqualifies traditional stacks. Establish ISO 16063-41 vibration calibration capabilities as the primary go-to-market credential for European metrology equipment penetration. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap precision assembly specialists because customer qualification timelines and regulatory certification burdens create sticky incumbent relationships that resist displacement. Five-to-ten-year viability favors targets with backward integration into piezoelectric material science or established FDA 510(k) clearance track records. Monitor ECHA substance restriction enforcement intensity as the inflection signal for lead-free formulation market share capture rates.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Ceramic Formulation Certification | ECHA REACH compliance unlocks European semiconductor equipment procurement before enforcement deadlines. |
| Captive Piezoelectric Material Fabrication | Substrate-to-assembly integration absorbs regulatory cost premiums that modular assemblers cannot match. |
| ISO 16063-41 Calibration Facility Expansion | Standardized vibration measurement protocols reduce cross-border qualification friction for Japanese and Korean suppliers. |
| PVDF-TrFE Polymer Actuator Pilot Programs | South Korean government funding tests conformable geometries for soft robotics applications ceramic stacks cannot serve. |
| Third-Party Metrology Service Unbundling | Separate hardware supply from recalibration contracts captures recurring revenue in FDA-regulated medical device clusters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with semiconductor equipment procurement directors, lithography stage engineers, medical device regulatory affairs leads, and precision automation R&D heads informed demand-side dynamics. Secondary validation drew from ECHA substance restriction filings, FDA 510(k) clearance databases, METI program disclosures, and ISO standardization committee records. Bottom-up actuator volume modeling and top-down equipment capex allocation analysis triangulated market sizing.
Comparable historical periods anchored the projection horizon against prior node-shrinkage cycles and regulatory transition timelines. Segmentation modeling spanned product architecture, material technology, end-use certification regime, and regional procurement pattern dimensions. CAGRs derived from equipment installation forecasts and content-per-system assumptions. Forecast inputs incorporated EUV lithography adoption curves and lead-free ceramic qualification progress.
Caveats apply where ECHA enforcement intensity, zirconium supply disruptions, or voice coil motor cost compression could materially shift the outlook. Practitioners should monitor sub-3nm lithography yield rates and lead-free formulation qualification completion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Automotive Steering Sensors Market