
 Electronic Differential Control Module Market | 2026-2036
Electronic Differential Control Module Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Differential Control Module Market Insights
The price-performance gap between premium torque-vectoring modules and commodity traction-control units is hardening. Continental AG leverages its integrated sensor-to-actuator pipeline to dominate electromechanical architectures, while Robert Bosch GmbH sustains R&D intensity across software-driven algorithm stacks. ZF Friedrichshafen AG anchors its position through captive manufacturing scale in precision geartrain integration.
An electronic differential control module is an embedded mechatronic system that modulates torque distribution across driven axles or wheels through clutch packs, electric motors, or hydraulic actuators governed by real-time sensor feedback and vehicle dynamics algorithms. Its primary purpose is to optimize traction, stability, and cornering performance without driver intervention. Active differential control and software-driven algorithms are capturing margin pools as automakers prioritize predictive torque management over reactive slip mitigation. Electromechanical control is displacing hydraulic systems in passenger vehicle applications, while hybrid differential systems retain share in commercial trucks where cost sensitivity and durability requirements constrain full electrification.
NHTSA crashworthiness standards and EPA fuel-efficiency mandates in the United States shape product validation cycles and lightweighting priorities for module suppliers. The EU Green Deal and F-Gas Regulation in Europe are accelerating the phase-out of hydraulic fluids with high global-warming potential, pushing electromechanical alternatives. Stakeholders must monitor how OEM platform consolidation and software-defined vehicle architectures reshape procurement patterns for differential control hardware.
Market Dynamics
Software-defined vehicle architectures are forcing a fundamental renegotiation between automakers and differential control module suppliers, as hardware procurement decouples from embedded software ownership and predictive torque algorithms become the primary value differentiator.
Growth Catalysts
- EU F-Gas Regulation:The mandated phase-out of hydraulic fluids with high global-warming potential accelerates electromechanical platform conversions across European passenger vehicle lines.
- Torque-vectoring penetration:Premium passenger vehicle segments are pulling demand for active differential control ahead of basic traction modules, concentrating margin pools in high-performance architectures.
- Germany supplier ecosystem concentration:Stuttgart and Munich anchor integrated sensor-to-actuator development pipelines that compress validation cycles for new platform designs.
Market Restraints
- Precision geartrain input volatility:Specialized alloy and bearing supply constraints elevate bill-of-materials exposure for electromechanical architectures relative to legacy hydraulic systems.
- Commercial truck cost sensitivity:Durability requirements and total-cost-of-ownership thresholds in heavy-duty segments constrain full electrification of differential control, preserving hybrid hydraulic-electric systems.
- NHTSA validation friction:Extended crashworthiness certification timelines for new electromechanical actuation designs compress product launch windows relative to established hydraulic platforms.
Strategic Opportunities
- Software algorithm licensing:Decoupled procurement models create white space for suppliers to monetize predictive vehicle dynamics code independently of hardware sales.
- India automotive electrification:PLI scheme incentives for advanced automotive electronics attract module localization investments as domestic OEMs expand all-wheel-drive portfolios.
- ISO 26262 functional safety convergence:Unified ASIL-D certification standards reduce regional validation fragmentation and enable single-SKU global platform strategies.
Industry Challenges
- Embedded systems talent scarcity:Competition for automotive software engineers with real-time control and safety-critical firmware expertise compresses R&D team buildout timelines.
- Legacy platform integration complexity:Retrofitting electromechanical architectures onto existing vehicle electrical domains requires custom harness and gateway redesigns that strain program budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Differential Control Module Market |
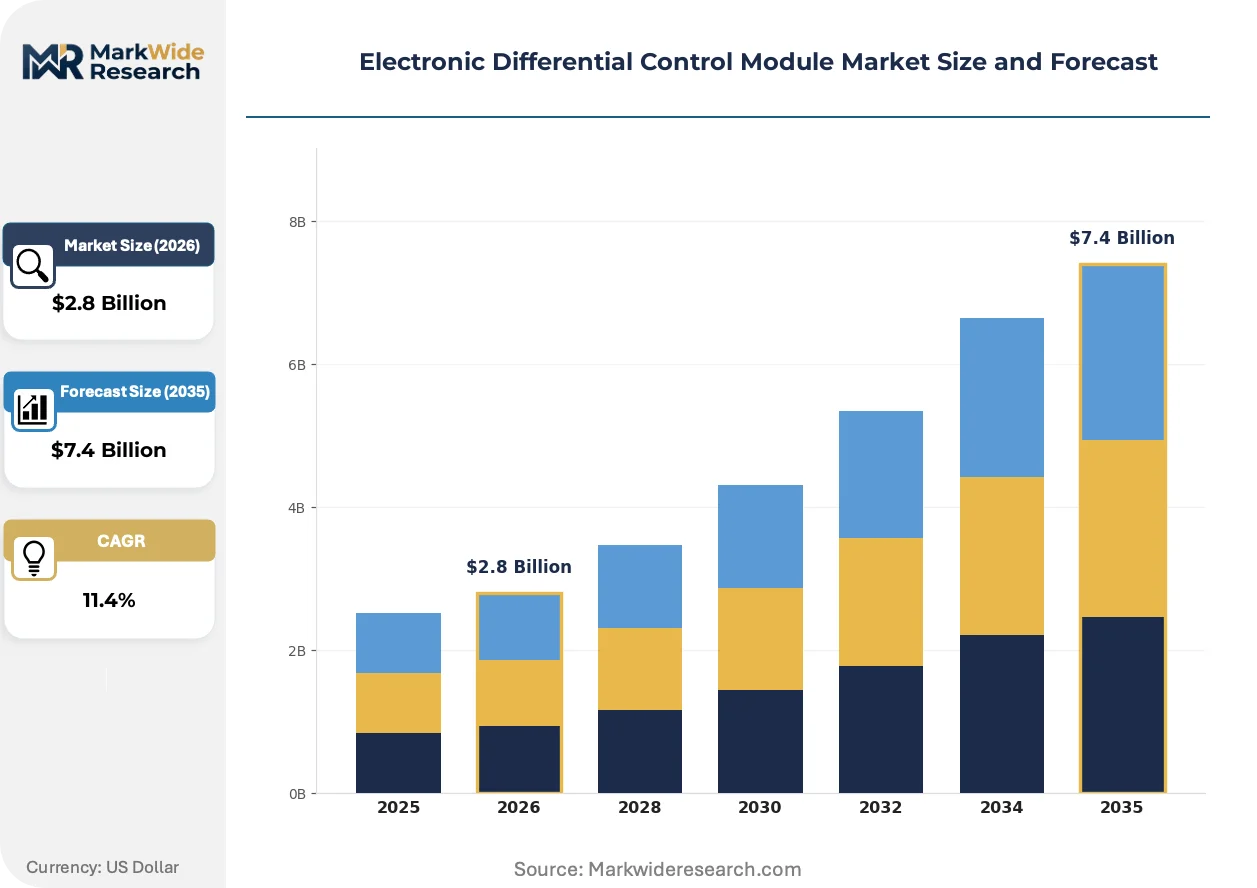
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Differential Control, Passive Differential Control, Hybrid Differential Systems, Electronic Control Units Technology: Sensor-Based Control, Hydraulic Control, Electromechanical Control, Software-Driven Algorithms Application: Passenger Vehicles, Commercial Trucks, Motorsport Vehicles, Off-Road Vehicles End User: OEMs, Vehicle Integrators, Aftermarket Suppliers, Tier-1 Component Manufacturers |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Aptiv PLC, Denso Corporation, Hitachi Astemo Ltd., Magna International, BorgWarner, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Differential Control Module Market Trends and Innovations
Real-time sensor fusion and edge computing capabilities are redefining how torque distribution decisions are executed, shifting competitive advantage from mechanical precision to algorithmic responsiveness and predictive modeling.
Model-predictive control algorithms are automating torque vectoring decisions across multiple axles simultaneously. Premium electric vehicle platforms are adopting these systems at accelerated refresh cycles. This capability is automating the transition from reactive slip mitigation to anticipatory traction management based on road surface prediction and driver intent inference.
The EU Green Deal's carbon-border adjustment mechanisms are tightening lifecycle accountability for automotive component manufacturing. Module suppliers face expanded disclosure requirements for embedded emissions in precision-machined geartrains and rare-earth motor materials. Electromechanical architectures with reduced fluid maintenance burdens are capturing preference in German and French OEM sourcing committees.
Direct sourcing contracts between semiconductor foundries and tier-one module suppliers are displacing traditional multi-tier distribution channels for high-voltage gate drivers and magnetic position sensors. Aftermarket service networks are unbundling from original equipment distribution, with independent diagnostic tool providers capturing calibration and software update revenue streams. This restructuring is most visible in North American and German markets where right-to-repair legislation accelerates channel fragmentation.
Electronic Differential Control Module Market Segmentation
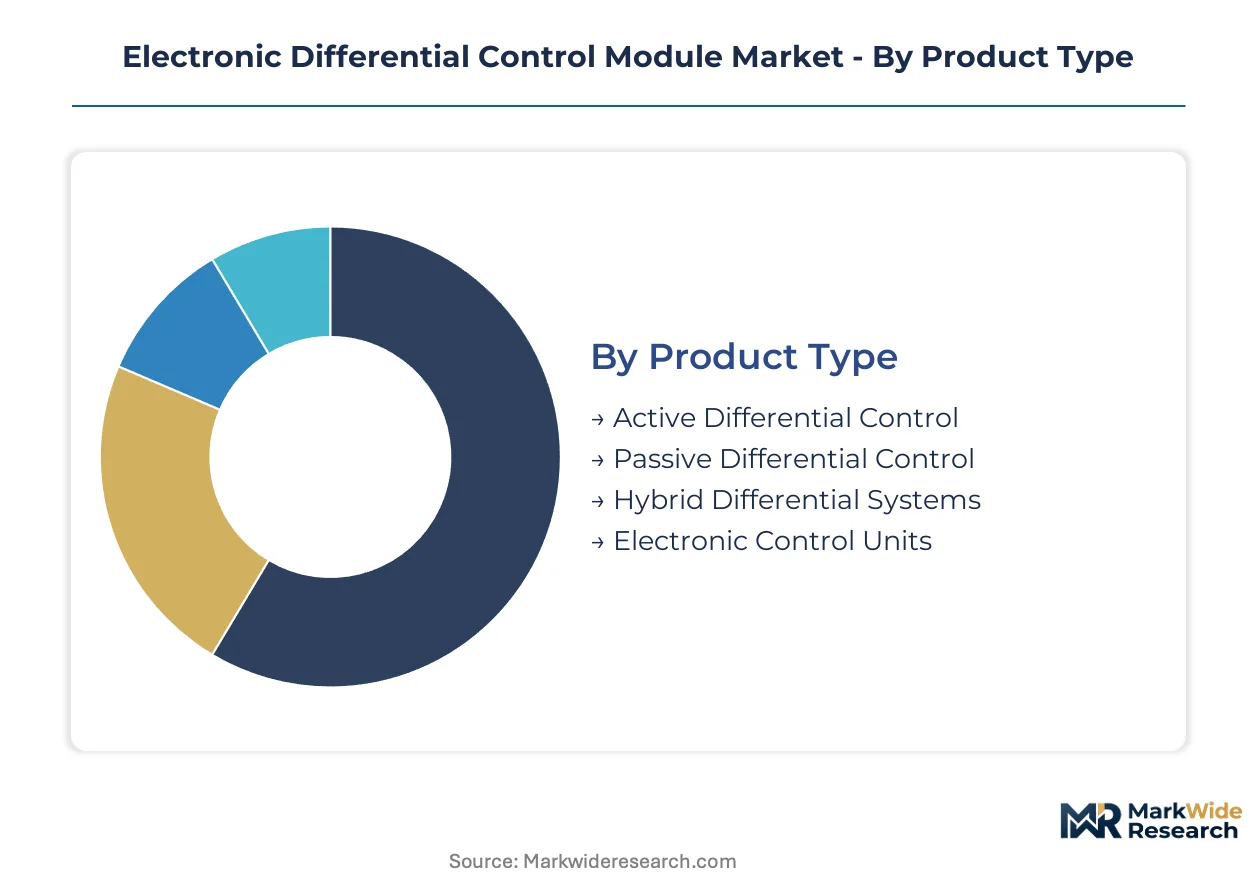
Segmentation in the electronic differential control module market exposes where capital deployment and margin capture diverge. Product architecture choices determine R&D intensity, while technology selections lock in supply chain partnerships and regulatory compliance pathways.
Product Type:
Capital intensity varies sharply across product architectures, with electromechanical systems demanding precision manufacturing investments that dwarf hydraulic legacy platforms.
- Active Differential Control:Torque-vectoring systems deploy multi-plate clutch packs or dual-motor architectures to distribute power across individual wheels in real time. Premium passenger vehicles in Germany and California concentrate demand as automakers chase predictive handling capabilities over reactive traction aids.
- Passive Differential Control:Limited-slip differentials rely on mechanical bias ratios or viscous couplings without electronic intervention. Cost-sensitive commercial truck fleets in India and Brazil sustain volume here, where durability thresholds override dynamic performance requirements.
- Hybrid Differential Systems:Hydraulic-electric architectures bridge legacy infrastructure and electrification roadmaps.
- Electronic Control Units:Embedded computing modules govern actuator commands and sensor fusion processing.
Most installed capacity flows through Passive Differential Control. Expansion is steepest in Active Differential Control.
Technology:
Technology selection determines supply chain concentration and regulatory exposure, with fluid-based systems facing phase-out pressure under EU environmental mandates.
- Electromechanical Control:Electric motors and precision geartrains replace hydraulic circuits, eliminating fluid maintenance and enabling software-defined torque mapping. Stuttgart supplier clusters anchor development pipelines for German OEM platform integrations.
- Software-Driven Algorithms:Model-predictive control stacks process vehicle dynamics data to anticipate traction needs before wheel slip occurs. Silicon Valley and Munich engineering centers compete for embedded systems talent developing these predictive stacks.
- Sensor-Based Control:Wheel-speed, yaw-rate, and accelerometer fusion enables real-time state estimation.
- Hydraulic Control:Legacy pressure-modulated architectures retain commercial truck share.
Sensor-Based Control carries the largest cumulative installation base. Software-Driven Algorithms are climbing the fastest as automakers decouple hardware procurement from algorithm ownership.
Application:
Application segmentation reveals diverging performance requirements and procurement power, with motorsport budgets per vehicle exceeding commercial truck volumes by orders of magnitude.
- Passenger Vehicles:All-wheel-drive crossovers and performance sedans integrate torque-vectoring modules as standard or optional equipment. EPA fuel-efficiency mandates and NHTSA stability requirements in the United States shape validation priorities for electromechanical architectures.
- Commercial Trucks:Heavy-duty segments prioritize total-cost-of-ownership and field-serviceability over dynamic performance. Indian and Brazilian fleet operators constrain supplier pricing power through volume aggregation and extended service-interval requirements.
- Motorsport Vehicles:Formula and GT racing categories drive algorithm development that cascades into road car programs.
- Off-Road Vehicles:Agricultural and construction equipment demands sealed-environment durability.
Passenger Vehicles absorb the majority of production volume. Motorsport Vehicles generate the steepest per-unit technology transfer value despite minimal absolute units.
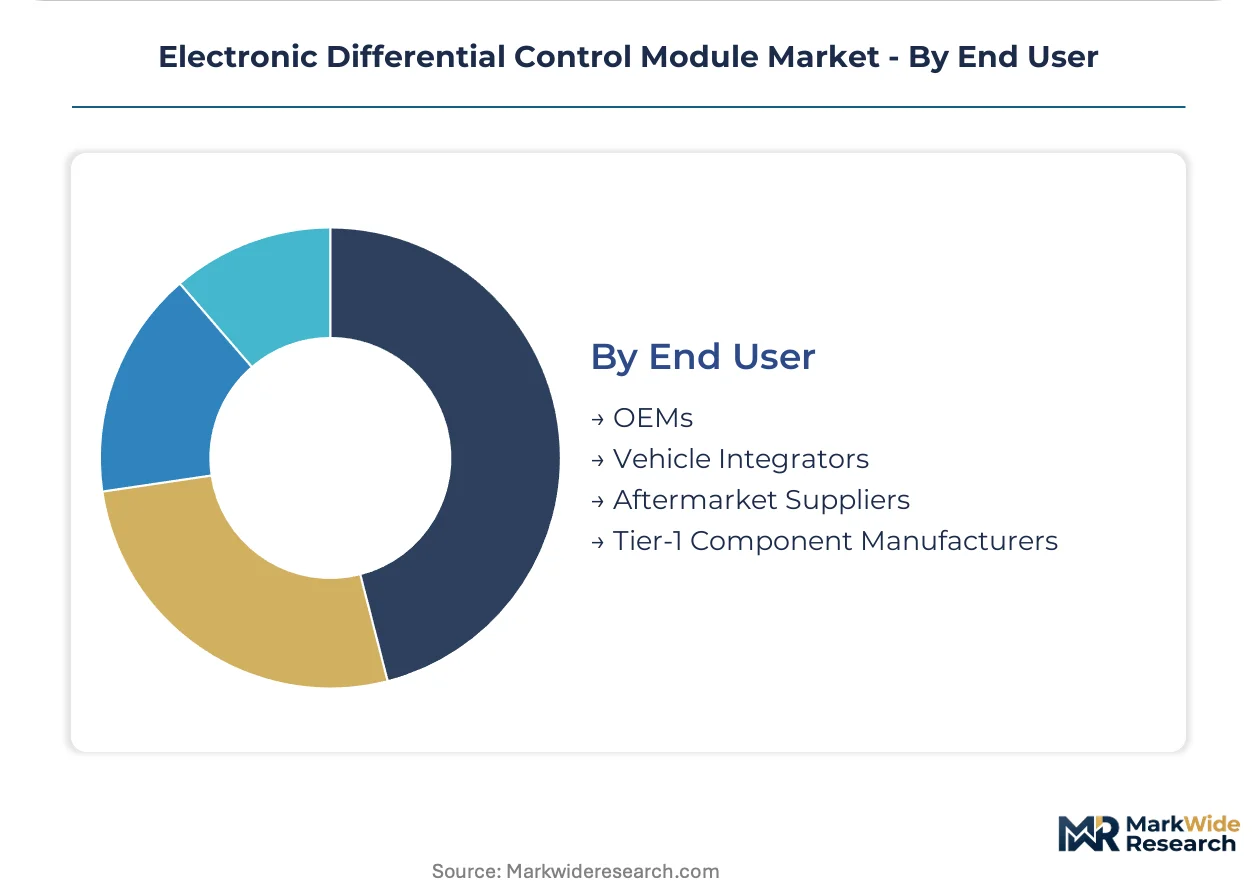
End User:
End-user structure determines contract terms and software ownership models, with OEM direct sourcing displacing traditional tiered distribution for electromechanical platforms.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz parent companies specify module architectures and increasingly retain algorithm IP through in-house software divisions. Direct semiconductor foundry contracts bypass traditional tier-one distribution for gate-driver and position-sensor procurement.
- Tier-1 Component Manufacturers:Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG integrate sensor, actuator, and control electronics into module assemblies. German supplier ecosystems around Munich and Stuttgart compress validation cycles through co-located R&D and manufacturing.
- Vehicle Integrators:Specialty upfitters and low-volume manufacturers source calibrated modules for niche applications.
- Aftermarket Suppliers:Independent diagnostic tool providers capture calibration and software update revenue as right-to-repair legislation fragments North American and European distribution channels.
Tier-1 Component Manufacturers channel the largest hardware shipment volumes. OEMs are gaining share fastest in algorithm licensing and direct semiconductor procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers concentrate around Stuttgart and Munich, where Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG operate integrated sensor-to-actuator development pipelines. This talent density compresses validation cycles for electromechanical architectures and anchors supplier ecosystems serving premium passenger vehicle platforms.
Germany
Stuttgart and Munich clusters drive torque-vectoring module development for BMW, Mercedes-Benz, and Volkswagen Group platforms. EU F-Gas Regulation accelerates hydraulic fluid phase-out, pushing electromechanical conversions. Baden-Württemberg's precision manufacturing corridor supplies precision geartrains and magnetic position sensors for next-generation architectures.
United States
Silicon Valley engineering centers compete for predictive algorithm talent developing model-predictive control stacks. NHTSA crashworthiness standards and EPA fuel-efficiency mandates shape electromechanical validation priorities. Michigan's automotive corridor integrates these modules into domestic OEM all-wheel-drive platforms.
Japan
Denso Corporation and Hitachi Astemo anchor development of sensor fusion and edge computing capabilities for real-time torque distribution. METI industrial policy supports automotive electronics R&D through targeted funding mechanisms. Nagoya's Chubu region concentrates precision manufacturing for hybrid differential systems.
China
Domestic OEM expansion into all-wheel-drive crossovers pulls module localization investments. MIIT new energy vehicle mandates and GB standards for vehicle stability control shape product specifications. Yangtze River Delta manufacturing hubs scale electromechanical production for both domestic brands and joint ventures.
India
PLI scheme incentives for advanced automotive electronics attract tier-one suppliers establishing module assembly operations. Domestic OEMs expanding all-wheel-drive portfolios create pull for localized differential control procurement. Tamil Nadu and Gujarat automotive corridors concentrate these investments near Chennai and Ahmedabad manufacturing zones.
Electronic Differential Control Module Market Competitive Landscape
Top-tier vendors anchor integrated module supply, while mid-tier specialists concentrate on component subsystems and regional assembly. The vendor base stratifies across three tiers: full-system integrators owning sensor-to-actuator pipelines, algorithm licensors monetizing software independently of hardware, and component specialists supplying precision geartrains or magnetic sensors. Competitive moves center on direct semiconductor foundry contracting to bypass distribution channels, and strategic algorithm licensing to capture recurring revenue from decoupled procurement models.
Within the full-system integrator tier, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG exemplify the German supplier archetype that dominates electromechanical architecture development. These Stuttgart and Munich-based entities occupy positions where co-located R&D and manufacturing compress platform validation timelines. Their concentration reflects the broader industry pattern where geographic proximity to OEM engineering centers determines differential control procurement relationships.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Denso Corporation |
| Hitachi Astemo Ltd. |
| Magna International |
| BorgWarner |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
German premium OEM procurement committees concentrate purchasing power for torque-vectoring modules, enforcing contract-based long-term offtake agreements that lock in electromechanical architecture pricing while squeezing hydraulic system margins through EU F-Gas compliance penalties.
Pricing Analysis
Bundled hardware-software procurement dominates active differential control, while unbundled algorithm licensing is capturing aftermarket calibration revenue. Three-tier pricing structure across premium torque-vectoring, standard all-wheel-drive, and economy traction-control tiers reflects ASIL-D certification grade and volume scale differentials. Cost compression in commercial truck segments is intensifying because Indian and Brazilian fleet operators aggregate procurement through extended service-interval contracts. Tier-1 component manufacturers exhibit the lowest price sensitivity; aftermarket diagnostic tool providers face the highest.
Supply Chain Analysis
Workforce availability for embedded systems engineers concentrates in Stuttgart, Munich, and Silicon Valley, compressing R&D timelines for German and California-based module developers. Manufacturing feeds from China, Germany, and Japan for precision geartrains, rare-earth motor materials, and magnetic position sensors. Single-source vulnerability runs through Taiwan semiconductor foundries supplying high-voltage gate drivers. Distribution runs through direct OEM contracts displacing traditional tier-one distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Europe exceed India's PLI scheme incentive value, creating margin expansion for suppliers relocating module assembly to Tamil Nadu and Gujarat corridors.
For Market Incumbents: Cement dominance in electromechanical architectures through captive manufacturing scale for precision geartrains, countering emerging algorithm licensors threatening hardware commoditization. Prioritize ASIL-D certification investment to maintain OEM platform engineering relationships against software-first entrants. For New Entrants and Emerging Players: Model-predictive control algorithm stacks offer a technology-first wedge into the decoupled procurement white space opening between OEM software divisions and tier-one hardware suppliers. Target India's domestic OEM all-wheel-drive expansion as the most penetrable geography, leveraging PLI scheme localization requirements as the go-to-market anchor. For Investors and Strategic Acquirers: Tier-one automotive electronics conglomerates are the most active acquirer in this space, consolidating sensor-to-actuator pipeline capabilities. The five-to-ten-year viability window favors algorithm licensors with recurring revenue models over pure hardware assemblers. Monitor NHTSA electromechanical crashworthiness certification timeline compression as the inflection signal for platform validation cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Decouples algorithm ownership from hardware procurement for Continental AG and Robert Bosch GmbH. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat corridors capture PLI scheme incentives for module localization. |
| Platform Standardization | Single-SKU global strategies reduce validation fragmentation under ISO 26262 ASIL-D convergence. |
| Battery Supply Agreement | Electric motor architectures for torque-vectoring depend on rare-earth magnet supply contracts. |
| Charging Infrastructure Partnership | Edge computing integration for predictive torque management requires vehicle-to-grid data pipelines. |
Research Methodology
Multiple input streams — OEM platform engineering specifications, tier-one supplier production schedules, and regulatory filing databases — were reconciled through primary interviews with automotive electronics procurement leads, embedded systems R&D directors, aftermarket diagnostic tool providers, and vehicle dynamics algorithm engineers, cross-referenced against NHTSA crashworthiness standards, EPA fuel-efficiency mandates, EU F-Gas Regulation disclosures, and MIIT new energy vehicle policy documents, with bottom-up module shipment aggregation triangulated against top-down OEM platform production forecasts.
Historical electromechanical architecture adoption curves were cross-referenced against Delphi panel inputs from Stuttgart and Munich supplier clusters to project penetration rates across the analysis window, modeling vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions, with CAGRs derived from slope-consistent trajectory fitting anchored to known platform refresh cycles and validated against semiconductor foundry capacity expansion announcements for high-voltage gate drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal carbon-border adjustment mechanism stringency and embedded systems talent scarcity compression. Forecasts reflect documented assumptions regarding OEM platform consolidation timelines and software-defined vehicle architecture rollout pace. Practitioners should monitor NHTSA electromechanical validation timeline rulings and right-to-repair legislative progression in North American and European markets for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
MEMS Gyroscope Market