
 North America Fingerprint Sensor Market | 2026-2036
North America Fingerprint Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fingerprint Sensor Market Analytics
Enterprise security buyers is rotating toward multimodal biometric systems that integrate fingerprint with facial recognition for zero-trust architectures. Synaptics Incorporated leverages its capacitive sensor portfolio to dominate laptop integration programs across major OEMs. Qualcomm Incorporated anchors the mobile segment through ultrasonic under-display modules that sustain premium smartphone ASPs. Apple Inc. competes through proprietary embedded technology that controls the full hardware-software authentication stack.
A fingerprint sensor is a solid-state or optical transducer that captures ridge and valley patterns from a human fingertip, converting analog biometric data into digital templates through capacitive, optical, or ultrasonic detection methods with resolution typically exceeding 500 dots per inch for forensic-grade matching. The device serves as an identity verification endpoint in consumer electronics, physical access systems, and financial transaction terminals. Capacitive sensors still occupy the largest revenue pool in smartphones though ultrasonic modules are capturing premium tier share. Optical sensors dominate access control installations where multispectral imaging differentiates live tissue from spoof artifacts. Embedded technology leads in payment systems where 3D sensing creates the fastest-growing margin pool.
FCC equipment authorization rules govern radio-emitting biometric devices while NIST testing protocols set accuracy benchmarks for federal procurement eligibility. The FDA regulates fingerprint sensors integrated into medical device access controls under 21 CFR Part 820 quality system requirements. FIDO Alliance standards are reshaping BFSI procurement specifications by mandating anti-spoofing liveness detection. Stakeholders must monitor how state-level biometric privacy statutes in Illinois, Texas, and Washington alter consent frameworks and data retention obligations.
Market Dynamics
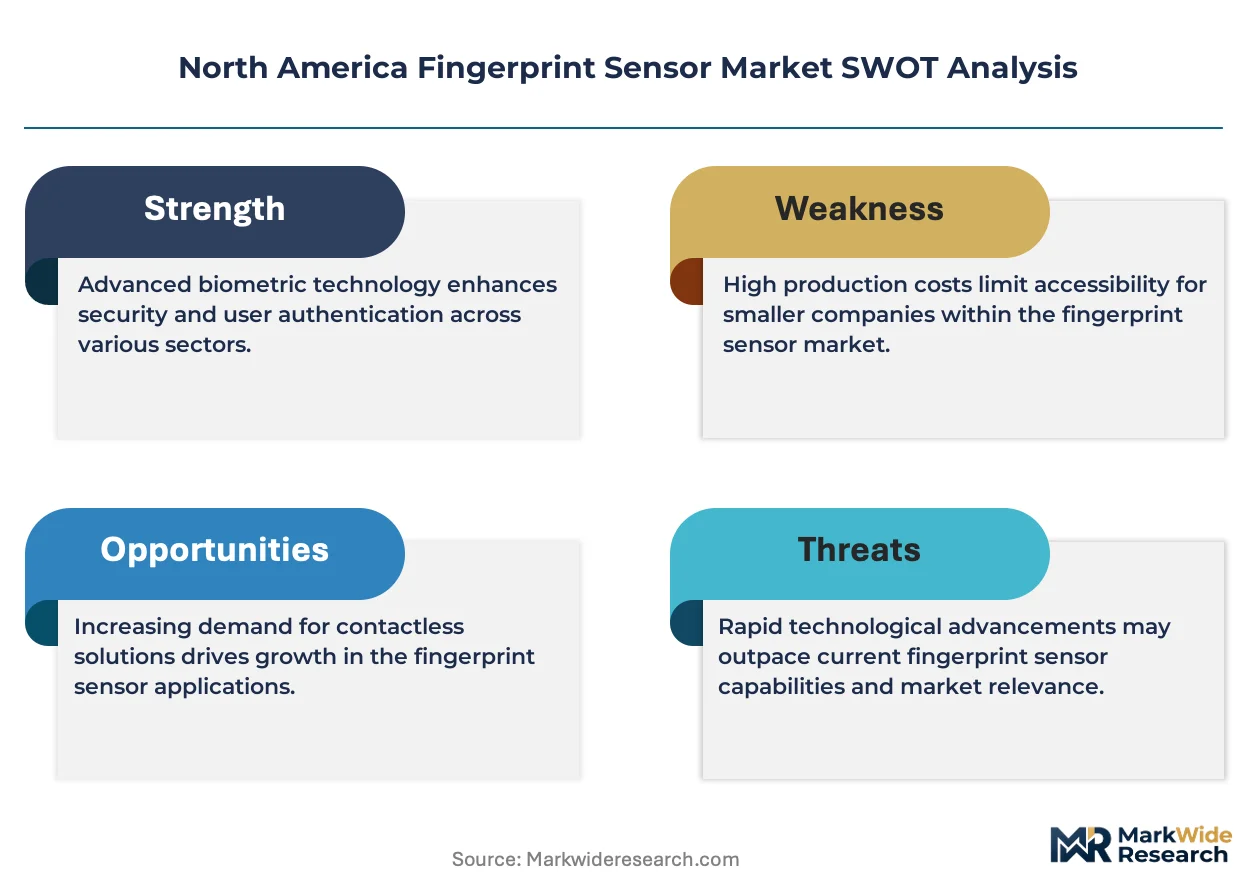
Enterprise migration toward zero-trust security architectures is compressing replacement cycles for legacy card-based access systems across corporate campuses and government facilities. This structural shift favors biometric endpoints that integrate with cloud identity platforms rather than standalone hardware.
Growth Catalysts
- FIDO Alliance protocols:Anti-spoofing liveness detection mandates in BFSI procurement specifications are accelerating sensor upgrades across Texas and California financial services hubs.
- Ultrasonic under-display modules:Premium smartphone OEMs are embedding these sensors deeper beneath glass panels, expanding addressable surface area for authentication.
- California technology corridor:Data center and cloud infrastructure buildouts are driving multimodal biometric deployments for physical access control at hyperscale facilities.
Market Restraints
- Silicon wafer supply concentration:Capacitive sensor foundry capacity concentrates in East Asian contract manufacturers, exposing North American module assemblers to geopolitical logistics friction.
- Illinois Biometric Information Privacy Act:Stringent consent and retention requirements create compliance overhead that slows enterprise deployment timelines in the Midwest.
- Optical sensor spoof vulnerability:Multispectral imaging adds cost but remains technically penetrable by advanced presentation attacks, limiting adoption in high-security federal applications.
Strategic Opportunities
- Canada healthcare digitization:Provincial hospital systems are piloting fingerprint-secured medication dispensing cabinets, creating a new vertical for embedded sensor vendors.
- Texas financial services:Regional banks are consolidating branch networks into flagship locations with biometric-enabled self-service kiosks, expanding unit volume per site.
- Ultrasonic-capacitive convergence:Hybrid modules combining both detection methods are opening design wins in ruggedized industrial tablets and field service equipment.
Industry Challenges
- Embedded systems firmware integration:Sensor OEMs must maintain separate software stacks for Android, Windows Hello, and proprietary RTOS environments, fragmenting engineering resources.
- NIST MINEX III certification timelines:Federal procurement eligibility requires passing updated interoperability benchmarks that extend product validation cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fingerprint Sensor Market |
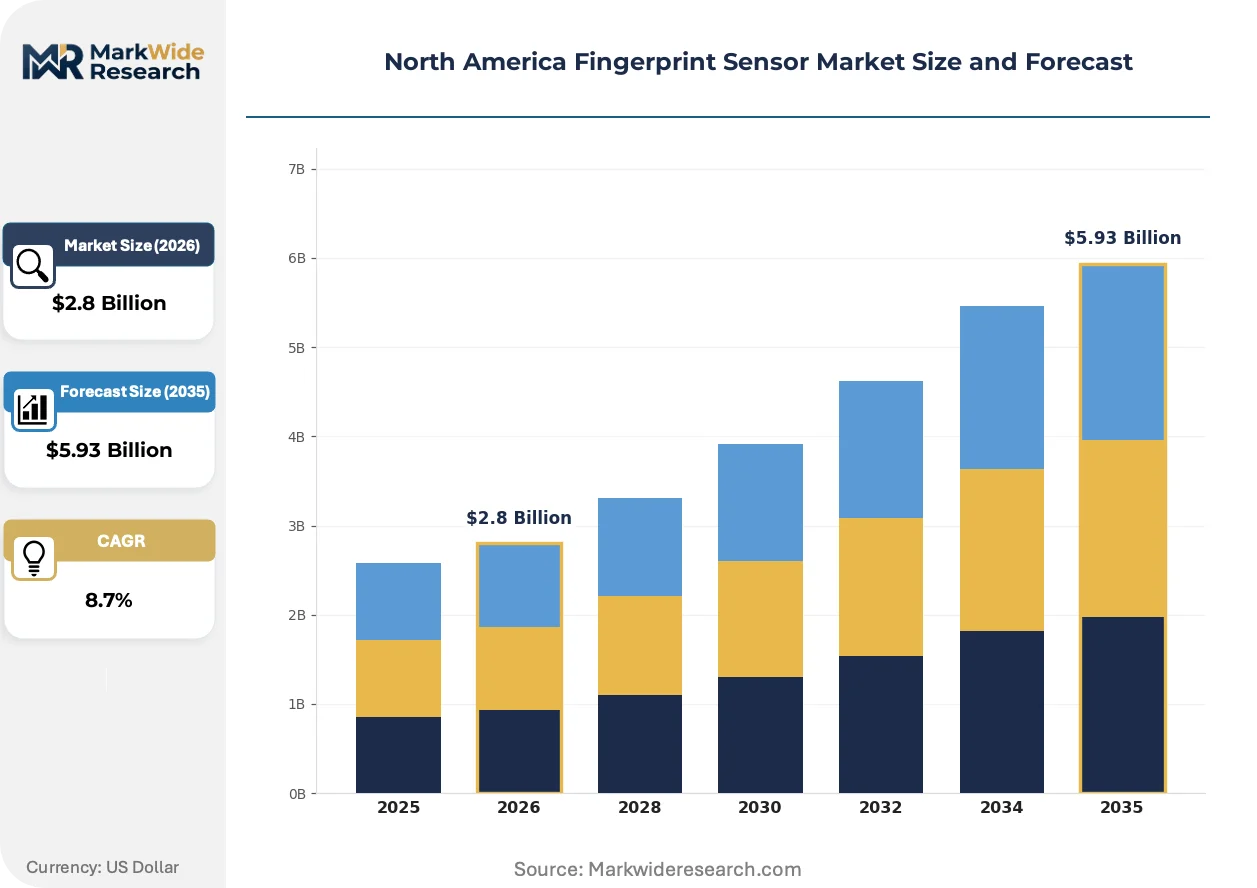
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Optical, Ultrasonic, Thermal Application: Smartphones, Laptops, Access Control, Payment Systems End User: Government, BFSI, Healthcare, Retail Technology: 2D, 3D, Multispectral, Embedded |
| Companies Covered | Synaptics Incorporated, Qualcomm Incorporated, Apple Inc., TDK Corporation, NEC Corporation, Gemalto NV, IDEX, 3M Cogent Inc., Crossmatch, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fingerprint Sensor Market Evolving Landscape
Sensor technology is splitting into two performance tiers as enterprise buyers demand forensic-grade accuracy while consumer OEMs prioritize cost-optimized miniaturization. This divergence is reshaping R&D allocation and foundry partnerships across the value chain.
Ultrasonic sensing is bifurcating the premium smartphone segment. Qualcomm's under-display modules penetrate glass and metal substrates to capture 3D ridge detail. Flagship OEMs in California and South Korea are adopting this technology for full-screen designs without physical buttons. The capability gap between ultrasonic and capacitive alternatives is widening average selling price dispersion in the mobile category.
Washington state's biometric privacy statute is tightening consent frameworks for commercial fingerprint collection. Retail and hospitality deployers must now provide explicit opt-out mechanisms and data retention disclosures. Franchise operators in Seattle and Portland are delaying kiosk rollouts to reconfigure backend data architectures, compressing near-term hardware shipments while expanding compliance service opportunities.
Enterprise security procurement is consolidating around cloud-managed biometric platforms. Fortune 500 facilities teams are replacing on-premise access control servers with Azure AD and Okta-integrated endpoints. This shift favors sensor vendors with pre-certified API integrations over hardware-only suppliers. The pattern is most pronounced in Texas energy sector campuses and Illinois manufacturing headquarters where IT-physical security convergence is accelerating.
North America Fingerprint Sensor Market Segmentation
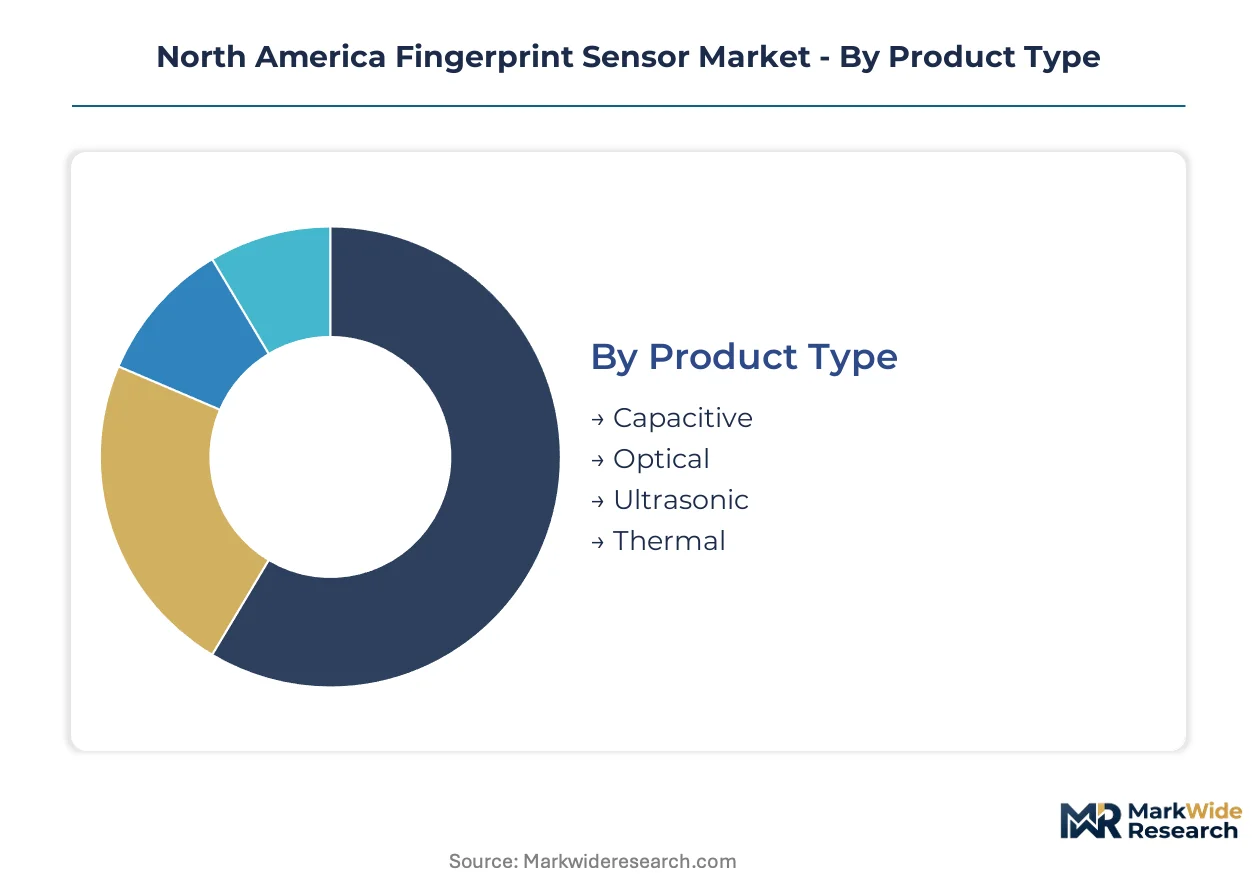
Technology heterogeneity across the North America Fingerprint Sensor Market creates distinct margin architectures that reward vendors with application-specific certification depth. Segmentation reveals how capacitive dominance in consumer electronics coexists with optical and multispectral premiums in enterprise security deployments.
Product Type:
Margin pools concentrate in ultrasonic modules for premium mobile devices and multispectral optical sensors for high-assurance access control installations.
- Capacitive:Solid-state sensors detect ridge patterns through electrical field distortion across silicon substrates, achieving sub-100ms authentication latency. Texas and California smartphone assembly plants drive volume procurement for mid-tier handset programs, though ASP compression from Asian foundry competition constrains vendor profitability.
- Optical:Image-based capture using CMOS or CCD arrays dominates corporate campus deployments across Illinois and Washington state manufacturing headquarters, where multispectral variants command 40-60% price premiums for liveness detection compliance with BIPA and state privacy statutes.
- Ultrasonic:Qualcomm's under-display modules penetrate glass substrates to capture 3D ridge topology, sustaining premium tier ASPs in flagship smartphone designs from California and South Korea OEMs.
- Thermal:Pyroelectric arrays detect temperature differentials between ridges and valleys, finding niche deployment in outdoor access control installations across Canadian oil sands facilities where environmental hardening requirements exceed capacitive durability limits.
The dominant share belongs to Capacitive, while Ultrasonic is closing the gap fastest through premium smartphone design wins.
Application:
Volume distribution tracks OEM procurement cycles, with mobile device integration programs commanding the largest unit shipments and enterprise access control delivering superior margin per unit.
- Smartphones:Under-display ultrasonic and capacitive modules embed beneath Gorilla Glass panels, with California-based OEMs and Korean flagship manufacturers driving technology roadmaps that prioritize full-screen aesthetics over physical button retention.
- Access Control:Wall-mounted and turnstile-integrated optical sensors dominate Fortune 500 campus security upgrades across Texas energy corridors and Illinois logistics hubs, where FIDO Alliance certification requirements filter vendor eligibility.
- Laptops:Windows Hello-compatible capacitive modules integrate into power buttons and palm rests, with Synaptics securing design wins across major OEM programs targeting enterprise fleet refreshes.
- Payment Systems:PCI PTS-certified embedded sensors enable biometric card and POS terminal authentication, with pilot deployments accelerating in Toronto and Vancouver financial services corridors ahead of broader Canadian rollout.
Smartphones maintain volume leadership, though Access Control is expanding most quickly as zero-trust security architectures compress replacement cycles.
End User:
Procurement sophistication varies sharply across verticals, with federal security mandates creating the highest certification barriers and retail applications facing the most stringent state-level privacy compliance overhead.
- Government:NIST MINEX III certification and FIPS 140-2 compliance requirements govern federal facility deployments, extending vendor validation timelines and favoring established suppliers with dedicated certification engineering teams.
- BFSI:Texas regional banks and California credit unions are consolidating branch networks into flagship locations with biometric-enabled self-service kiosks, expanding sensor volume per site while mandating anti-spoofing liveness detection under FIDO Alliance procurement specifications.
- Healthcare:Provincial Canadian hospital systems pilot fingerprint-secured medication dispensing cabinets, creating a new embedded sensor vertical where FDA 21 CFR Part 820 quality system requirements apply to US medical device access integrations.
- Retail:Illinois BIPA and Washington state biometric privacy statutes impose explicit consent and data retention obligations that compress near-term kiosk rollout timelines in Seattle and Portland franchise networks.
BFSI captures the largest revenue pool, while Healthcare is gaining share fastest through Canadian digitization initiatives and US medical device integration mandates.
Technology:
Dimensional sensing capability separates premium tiers, with 3D and embedded architectures commanding substantial price premiums over planar alternatives in payment and high-assurance applications.
- 2D:Planar image capture dominates legacy access control installations and cost-optimized smartphone modules, though spoof vulnerability limits adoption in federal and financial services applications requiring presentation attack resistance.
- 3D:Ultrasonic and structured light methods capture sub-surface ridge detail, with Qualcomm's under-display modules anchoring premium smartphone authentication and expanding into ruggedized industrial tablets for Texas field service deployments.
- Multispectral:Multi-wavelength imaging differentiates live tissue from spoof artifacts using near-infrared and visible light arrays, commanding enterprise security premiums across California data center campuses and Illinois government facilities.
- Embedded:System-in-package integration combines sensing, processing, and secure element functions for payment card and POS terminal applications, creating the steepest expansion trajectory as PCI PTS certification requirements harden.
2D retains installed base dominance, though Embedded is climbing the fastest as payment system security specifications tighten across North American financial networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-5 technology corridor spanning California to Washington anchors North American semiconductor and sensor module distribution, while the CANAMEX trade corridor funnels precision components from Mexican assembly plants to US integration facilities.
United States
California's hyperscale data centers and Texas financial services hubs drive multimodal biometric deployments for physical access control. NIST MINEX III certification requirements govern federal procurement eligibility, extending vendor validation timelines by six to nine months. Illinois manufacturing headquarters face BIPA compliance overhead that compresses enterprise rollout schedules in the Midwest.
Canada
Provincial hospital systems in Ontario and British Columbia pilot fingerprint-secured medication dispensing cabinets, creating embedded sensor demand in healthcare digitization initiatives. Health Canada regulates medical device access integrations under quality system requirements aligned with FDA 21 CFR Part 820. Toronto and Vancouver financial services corridors accelerate PCI PTS-certified payment terminal pilots ahead of broader national rollout.
Mexico
Nuevo León's electronics manufacturing clusters assemble capacitive sensor modules for re-export to US smartphone OEMs, leveraging proximity to Texas distribution hubs. The country's national standards body certifies biometric equipment under NOM-024-SCFI standards for consumer protection. Guadalajara's technology park hosts module testing facilities serving North American certification requirements.
North America Fingerprint Sensor Market Competitive Landscape
Concentration sits with diversified semiconductor houses that leverage captive foundry relationships and pre-certified API integrations. The vendor base splits between mobile-focused module suppliers and enterprise security specialists, with tiered pricing separating forensic-grade from cost-optimized tiers. Two strategic archetypes dominate: platform-integrated sensor vendors and standalone biometric hardware specialists. Competitive moves center on cloud identity platform pre-certifications and ultrasonic-capacitive hybrid module development.
Among diversified semiconductor houses, Synaptics Incorporated and Qualcomm Incorporated exemplify platform-integrated positioning through Windows Hello and under-display ultrasonic architectures respectively. Apple Inc. occupies a proprietary ecosystem anchor role controlling full hardware-software authentication stacks. These three entities represent distinct competitive vectors: laptop integration programs, premium mobile modules, and closed-system embedded technology.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Qualcomm Incorporated |
| Apple Inc. |
| TDK Corporation |
| NEC Corporation |
| Gemalto NV |
| IDEX |
| 3M Cogent Inc. |
| Crossmatch |
| Others |
Value Network & Pricing Analysis
Ultrasonic module displacement of capacitive alternatives in premium smartphone slots simultaneously redraws procurement geography toward South Korean and Taiwanese foundries while compressing margin structures for legacy silicon suppliers serving mid-tier handset programs. This substitution dynamic concentrates pricing power with Qualcomm's captive supply chain while forcing capacitive vendors toward volume-discount negotiations with Texas and California OEM assembly plants.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with three-tier pricing separating NIST-certified forensic-grade modules from FIDO-compliant enterprise tiers and cost-optimized consumer electronics variants. Price differentiation hinges on certification level and volume scale, with MINEX III validation adding substantial premiums. Pricing pressure stems from Asian foundry overcapacity in capacitive sensor wafers. Enterprise security buyers show lowest price sensitivity due to compliance mandates, while retail kiosk deployers face acute budget constraints under Illinois BIPA implementation costs.
Supply Chain Analysis
Port congestion across the Trans-Pacific trade lane elevates inbound logistics costs for East Asian silicon wafer shipments to Mexican module assembly plants in Nuevo León. Supply concentrates in Taiwan, South Korea, and China for CMOS image sensors and ASIC controllers. Raw material dependencies include silicon wafers, glass substrates, and rare-earth dopants for pyroelectric thermal arrays. Single-source vulnerability sits with TSMC advanced-node capacity for ultrasonic processing chips. Distribution runs through Texas distribution hubs serving California and Illinois end-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified firmware engineering talent scarcity defines competitive moats in this market, as NIST validation timelines stretch eighteen months and FIDO Alliance pre-certification requirements filter vendor eligibility for financial services procurement.
For Market Incumbents: Shield market position by deepening captive foundry relationships in Taiwan and South Korea to secure ultrasonic sensor wafer allocation ahead of premium smartphone design wins. Accelerate NIST MINEX III pre-certification pipelines to compress federal procurement eligibility timelines. Vertical integration into secure element packaging protects margin pools in payment system applications. For New Entrants and Emerging Players: Differentiate on Canadian healthcare digitization pilots, where provincial hospital medication dispensing cabinet deployments lack established sensor vendor relationships. Target Ontario and British Columbia procurement corridors where FDA 21 CFR Part 820 alignment creates certification barriers for hardware-only suppliers. Pursue strategic partnerships with medical device OEMs seeking embedded biometric modules. For Investors and Strategic Acquirers: Illinois BIPA enforcement reshapes the acquisition landscape by elevating compliance-engineering capabilities above pure hardware scale in valuation frameworks. Long-term viability favors vendors with pre-certified cloud identity platform integrations over standalone hardware specialists. Watch Texas regional bank branch consolidation velocity as an inflection indicator for biometric kiosk demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic-Capacitive Hybrid Module Development | Combines detection methods for ruggedized industrial tablets serving Texas field service deployments. |
| NIST MINEX III Pre-Certification Investment | Compresses federal procurement eligibility timelines by six to nine months. |
| Cloud Identity Platform API Integration | Enables Azure AD and Okta compatibility for Fortune 500 access control upgrades. |
| Canadian Healthcare Pilot Partnership | Opens embedded sensor vertical in Ontario and British Columbia hospital digitization. |
| FIDO Alliance Anti-Spoofing Certification | Mandates liveness detection for Texas and California BFSI procurement specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing sensor OEM product managers, enterprise security procurement directors at Fortune 500 facilities, biometric system integrators, and foundry supply chain specialists. Secondary validation drew from FCC equipment authorization databases, NIST biometric test results, FIDO Alliance certification registries, and SEC filings of diversified semiconductor houses. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
The projection horizon spans the full analysis window with annual interval modeling. Segmentation dimensions include technology tier, application vertical, end-user industry, and geographic regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and technology substitution patterns. Forecast inputs incorporated smartphone OEM design win pipelines, enterprise access control refresh schedules, and state-level biometric privacy statute implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained premium smartphone ultrasonic adoption or accelerated Illinois BIPA enforcement would require recalibration. Forecasts reflect assumptions around foundry capacity allocation, NIST certification throughput, and cloud identity platform migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Refrigeration Gauge Market