
 Potentiometer Market | 2026-2036
Potentiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Potentiometer Market Outlook
Asset-light manufacturing partnerships is narrowing the capital barrier for mid-tier competitors entering precision potentiometer production. TE Connectivity leverages its vertical integration across conductive plastic formulation and contact assembly to sustain margin control in automotive sensor modules. Bourns anchors its position in high-temperature wirewound designs for aerospace and defense applications. Vishay Intertechnology competes through broad catalog breadth across linear and rotary configurations.
A potentiometer is a three-terminal resistor with a sliding or rotating contact that forms an adjustable voltage divider, typically manufactured with resistive elements of conductive plastic, carbon composition, or precision wirewound wire on ceramic or molded substrates. The device converts mechanical position into electrical resistance, serving as a fundamental interface for volume controls, position sensing, calibration trimming, and feedback loops in analog and mixed-signal systems. Rotary potentiometers occupy the largest volume share in consumer electronics and automotive instrument clusters, while digital potentiometers command premium positioning in programmable gain stages and automated test equipment where software-configurable resistance eliminates mechanical wear. Wirewound technology dominates industrial and military applications requiring stability under thermal stress, whereas conductive plastic formulations are displacing carbon composition in audio and instrumentation markets due to superior resolution and noise characteristics.
US manufacturers navigate FCC emissions rules for potentiometer-integrated controls in telecommunications gear and NHTSA reliability standards for automotive human-machine interfaces. European suppliers face REACH substance restrictions on legacy resistive materials and RoHS compliance mandates that have accelerated halogen-free conductive plastic development. Japan's METI energy-efficiency guidelines influence potentiometer specification in appliance motor controls. Stakeholders must monitor how automotive electrification architectures relegate mechanical trimmers to redundant backup roles while expanding digital potentiometer deployment in battery management and inverter calibration circuits.
Market Dynamics
Automotive electrification architectures are systematically relegating mechanical trimmers to redundant backup roles while expanding digital potentiometer deployment in battery management and inverter calibration circuits, fundamentally restructuring component specification across tier-one supply chains.
Growth Catalysts
- China's dual carbon goals:GB standards on energy efficiency are pushing manufacturers toward conductive plastic formulations with lower lifecycle emissions, opening substitution windows in industrial controls.
- Medical device precision requirements:Surgical robotics and diagnostic imaging OEMs specify sub-1% linearity potentiometers for haptic feedback and position sensing, tightening qualification standards.
- Germany's industrial automation corridor:Motion control system builders in Baden-Württemberg and Bavaria source high-reliability wirewound units for servo motor feedback loops.
Market Restraints
- Palladium and ruthenium price volatility:Precious metal contact plating in precision wirewound units faces input cost swings that compress margin predictability for mid-tier manufacturers.
- REACH substance restrictions:Legacy carbon composition formulations containing restricted phthalates face compliance-driven phase-outs across European supply chains.
- Digital potentiometer substitution:Software-configurable resistance arrays eliminate mechanical wear in programmable gain stages and automated test equipment.
Strategic Opportunities
- India's PLI scheme for electronics:Contract manufacturers establishing assembly capacity under production-linked incentives create localized demand for trimmer potentiometers in consumer appliance motor controls.
- Battery management system calibration:Electric vehicle inverter architectures require non-volatile digital potentiometers for voltage reference trimming across cell monitoring circuits.
- Halogen-free conductive plastics:RoHS compliance mandates are accelerating development of bromine-free formulations that command premium positioning in audio and instrumentation markets.
Industry Challenges
- Thin-film deposition expertise:Conductive plastic formulation requires polymer chemistry and precision coating capabilities that concentrate among a narrow supplier base.
- IEC 60393 qualification timelines:Extended certification cycles for precision rotary units delay new product introductions in aerospace and defense procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potentiometer Market |
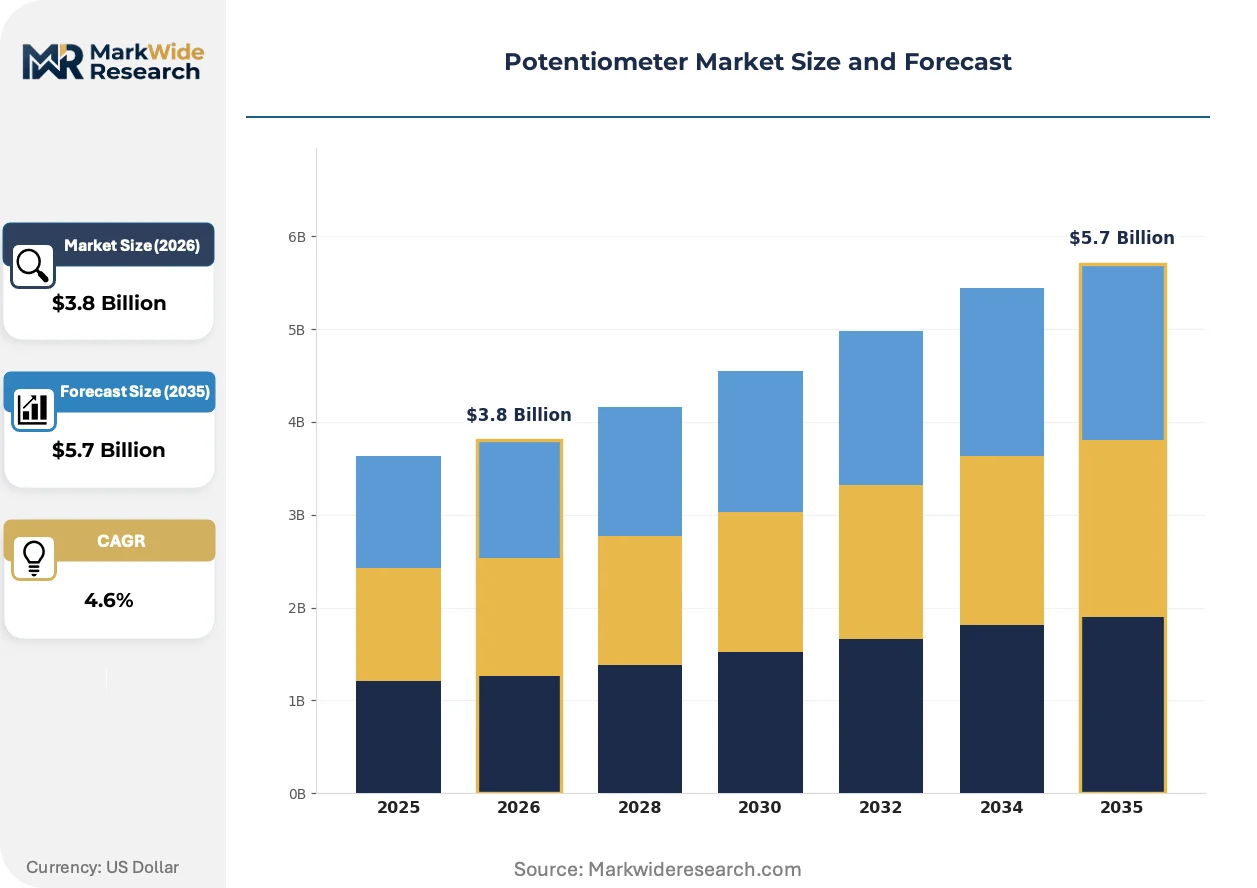
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Linear, Digital, Tapered Application: Consumer Electronics, Automotive Controls, Industrial Equipment, Medical Devices Technology: Conductive Plastic, Carbon Composition, Wirewound, Optical End User: Manufacturers, Repair Services, DIY Enthusiasts, Educational Institutions |
| Companies Covered | TE Connectivity, BEI Sensors, Texas Instruments, Honeywell, Bourns, Vishay Intertechnology, Microchip Technology, Renesas Electronics Corporation, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potentiometer Market Strategic Shifts
Component miniaturization and contact reliability engineering are converging to reshape potentiometer architectures across consumer, industrial, and automotive tiers, with material science advances enabling performance thresholds previously unattainable in compact form factors.
Non-contact magnetic and optical position sensors is collapsing the addressable market for traditional mechanical potentiometers in high-cycle industrial applications. Automotive steering angle and throttle position sensing modules now specify Hall-effect and inductive alternatives that eliminate wear-induced drift. This substitution is compressing wirewound unit volumes in under-hood environments while forcing incumbent suppliers to defend remaining sockets through extreme temperature resilience claims.
REACH substance restrictions on legacy resistive materials have accelerated halogen-free conductive plastic development across European formulation houses. ECHA candidate list updates are disqualifying brominated flame retardants and certain phthalate plasticizers from new designs. Medical device and professional audio OEMs in Germany and Switzerland now specify full material disclosure as a procurement gate, privileging suppliers with certified green chemistry pipelines.
Consolidation among contract electronics manufacturers is concentrating purchasing power for standard trimmer volumes. Foxconn, Jabil, and Flex now negotiate global frame agreements that compress unit pricing and demand vendor-managed inventory programs. This buyer concentration is most visible in China's Pearl River Delta, where appliance and consumer electronics assembly clusters have reduced qualified supplier lists by half over the past qualification cycle.
Potentiometer Market Segmentation
Precision potentiometer specification diverges sharply across end-use environments, with automotive electrification and surgical robotics imposing fundamentally different reliability and resolution requirements. Component suppliers must align formulation chemistry and contact architecture to distinct qualification regimes rather than pursuing universal platform designs.
Product Type:
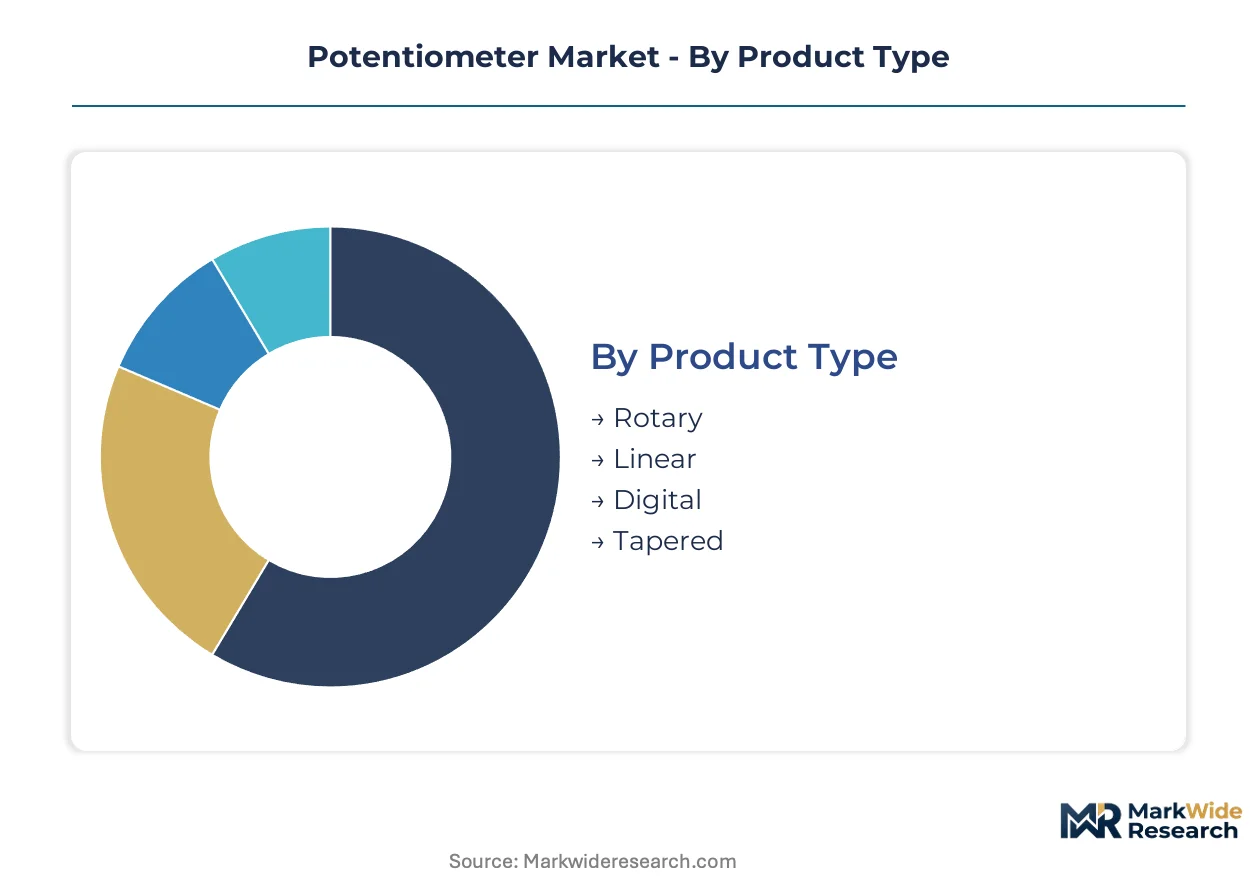
Rotary mechanisms dominate volume-intensive applications where angular position sensing interfaces with human operators, while linear and digital variants address specialized motion control and software-configurable calibration needs.
- Rotary:Circular resistive tracks with wiper contacts convert shaft rotation into proportional voltage division. Automotive instrument clusters in Germany and consumer audio equipment in Japan specify these units for volume and tuning controls where tactile feedback matters.
- Linear:Straight-line resistive elements suit slide controls and position feedback in industrial automation. Motion control OEMs in Baden-Württemberg source precision linear units for servo motor positioning where straight-line displacement must map to electrical output with sub-1% accuracy.
- Digital:Solid-state resistor arrays eliminate mechanical wear through software-controlled switching. Battery management systems in electric vehicle architectures deploy non-volatile digital potentiometers for voltage reference trimming across cell monitoring circuits.
- Tapered:Non-linear resistance curves match human perceptual response in audio attenuation applications. Professional mixing consoles and hearing aid manufacturers specify audio-taper and reverse-audio-taper laws for natural loudness progression.
The dominant share belongs to Rotary, while Digital is closing the gap fastest as automotive electrification architectures displace mechanical trimmers with software-configurable alternatives.
Application:
Cost tiers stratify sharply across these verticals, with medical and industrial buyers absorbing premium pricing for qualification documentation while consumer electronics procurement drives aggressive unit cost compression.
- Consumer Electronics:High-volume trimmers and rotary controls in smartphones, laptops, and home appliances face extreme price pressure. Contract manufacturers in China's Pearl River Delta negotiate global frame agreements that compress margins and demand vendor-managed inventory programs.
- Automotive Controls:Steering angle sensors, throttle position modules, and climate control interfaces must survive temperature cycling and vibration profiles specified by NHTSA and ECE regulations. Tier-one suppliers specify wirewound units for under-hood environments where conductive plastic would degrade.
- Industrial Equipment:Factory automation and process control systems require million-cycle durability and IP-rated sealing. Motion control builders in Bavaria source high-reliability units for servo feedback loops where position drift would cascade into production defects.
- Medical Devices:Surgical robotics and diagnostic imaging OEMs impose sub-1% linearity requirements and full material disclosure for biocompatibility. FDA and MDR qualification timelines extend procurement cycles but lock in supplier relationships for product generations.
Consumer Electronics captures the highest unit volumes, though Medical Devices exhibits the steepest expansion trajectory as robotic surgery platforms proliferate in Germany, Switzerland, and the United States.
Technology:
Supply concentration in conductive plastic formulation and precision wirewound winding creates capability scarcity that shapes competitive positioning among mid-tier manufacturers.
- Conductive Plastic:Polymer matrices loaded with carbon or metal particles deliver smooth rotation feel and low noise in audio applications. REACH-compliant halogen-free formulations now command premium positioning in European professional audio and instrumentation markets as ECHA restrictions disqualify legacy materials.
- Carbon Composition:Molded carbon-phenolic elements offer lowest cost but suffer from moisture absorption and wear debris. Phthalate-containing formulations face compliance-driven phase-outs across European supply chains, accelerating substitution toward conductive plastic alternatives.
- Wirewound:Precision resistance wire wound on ceramic substrates achieves temperature coefficients below 50 ppm/°C and power dissipation ratings exceeding 5 watts. Aerospace and defense procurement channels in the United States specify these units for flight control surface position feedback where thermal stability is non-negotiable.
- Optical:Non-contact position encoding through LED-photodiode pairs eliminates mechanical wear entirely. Industrial automation OEMs in Japan specify optical alternatives for high-cycle packaging machinery where traditional wipers would fail within months.
Conductive Plastic holds the installed base advantage, yet Optical encoding is gaining share fastest in high-reliability industrial sockets where maintenance access is costly.
End User:
Customer type determines channel structure and service intensity, with OEM manufacturers demanding application engineering support while repair and DIY segments prioritize availability and price transparency.
- Manufacturers:OEM procurement teams specify potentiometers during original product design, locking in volumes through approved vendor lists. Automotive tier-ones and medical device builders conduct multi-year qualification cycles that concentrate purchasing among pre-certified suppliers.
- Repair Services:Independent electronics repair shops and authorized service centers require cross-referenced part numbers and rapid availability. Distributors such as Digi-Key and Mouser stock broad parametric ranges to serve this fragmented demand base.
- DIY Enthusiasts:Hobbyist electronics builders purchase through retail channels and online marketplaces for audio projects, guitar effects, and prototyping. This segment exhibits high price sensitivity and preference for established component brands with documented datasheets.
- Educational Institutions:University engineering laboratories and technical training centers consume trimmer potentiometers for circuit instruction and student projects. Procurement flows through academic supply contracts with emphasis on lead time reliability over technical sophistication.
Manufacturers represent the dominant revenue concentration, though Repair Services is expanding most quickly as right-to-repair legislation in the United States and European Union extends equipment service lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement from medical device OEMs concentrates demand in Germany, Switzerland, and the United States, while automotive tier-ones in China and Japan drive volume specifications for electrification architectures.
United States
Aerospace and defense contractors specify precision wirewound units for flight control surface feedback. FAA certification requirements and NHTSA reliability standards govern qualification timelines for automotive human-machine interfaces. Boston-area surgical robotics developers source sub-1% linearity potentiometers for haptic feedback systems.
Germany
Motion control OEMs in Baden-Württemberg and Bavaria consume high-reliability wirewound units for servo motor positioning loops. REACH substance restrictions and RoHS compliance mandates accelerate halogen-free conductive plastic development. Stuttgart's industrial automation corridor anchors procurement for factory automation feedback systems.
China
Contract manufacturers in the Pearl River Delta negotiate global frame agreements for consumer electronics trimmers. GB standards on energy efficiency and the dual carbon goals push conductive plastic formulation toward lower lifecycle emissions. Shenzhen appliance clusters reduce qualified supplier lists through consolidated purchasing power.
Japan
Industrial automation OEMs specify optical position sensors for high-cycle packaging machinery where mechanical wipers would fail. METI energy-efficiency guidelines influence potentiometer specification in appliance motor controls. Nagoya's automotive component suppliers deploy non-volatile digital potentiometers for inverter calibration circuits.
Switzerland
Professional audio and medical device manufacturers impose full material disclosure requirements as procurement gates. Swissmedic and MDR alignment drives qualification documentation intensity for surgical equipment builders. Zurich-area precision instrument clusters privilege suppliers with certified green chemistry pipelines.
Potentiometer Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation among contract electronics manufacturers concentrates purchasing power for standard trimmer volumes, compressing margins for undifferentiated suppliers. The competitive terrain separates vertical integrators with captive material capabilities, precision specialists serving aerospace and medical qualification regimes, and broad-catalog distributors competing on availability. Dominant moves include backward integration into conductive plastic formulation and strategic partnerships with automotive tier-ones for battery management system calibration sockets.
Within the precision-specialist tier, Bourns and BEI Sensors exemplify qualification-intensive positioning for high-temperature and high-reliability applications. TE Connectivity anchors the vertical-integration archetype through upstream control over contact assembly and material formulation. Among semiconductor-based digital potentiometer suppliers, Texas Instruments occupies a position exemplifying the transition from mechanical to software-configurable resistance arrays in automotive electrification architectures.
| Leading Market Players |
|---|
| TE Connectivity |
| BEI Sensors |
| Texas Instruments |
| Honeywell |
| Bourns |
| Vishay Intertechnology |
| Microchip Technology |
| Renesas Electronics Corporation |
| Analog Devices |
| Others |
Value Chain & Pricing Dynamics
Conductive plastic formulation expertise concentrates among Japanese and German specialty chemical houses, anchoring margin capture upstream while contract manufacturers in China's Pearl River Delta compress unit economics through consolidated purchasing power.
Pricing Analysis
Certification level (IEC 60393-grade, RoHS-compliant, halogen-free) creates the primary spread between aerospace wirewound units and consumer trimmers. Three-tier pricing structure across precision industrial, standard commercial, and economy appliance grades reflects qualification documentation intensity. Cost compression in consumer electronics trimmers intensifies because Foxconn and Jabil negotiate global frame agreements. Appliance OEMs exhibit highest price sensitivity; medical device builders absorb premiums for sub-1% linearity guarantees.
Supply Chain Analysis
Export controls on precision resistance wire alloys and palladium plating chemistries limit technology flows to certain defense-aerospace procurement channels. Manufacturing concentrates in China, Germany, and Japan. Supply chains draw from ceramic substrate foundries, precious metal refiners, and polymer formulation specialists. Single-source vulnerability concentrates in halogen-free conductive plastic resin supply. Distribution runs through authorized distributors Digi-Key and Mouser serving fragmented repair demand alongside direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital potentiometer interoperability with automotive battery management architectures is restructuring platform economics, rewarding suppliers who bridge mechanical legacy and solid-state calibration ecosystems.
For Market Incumbents: Harden qualification moats around IEC 60393-certified rotary units for aerospace and surgical robotics sockets. Deepen backward integration into conductive plastic formulation to defend margin pools against REACH-driven material substitution. Priority investment targets halogen-free polymer chemistry pipelines serving European medical audio OEMs. For New Entrants and Emerging Players: Build out India-based trimmer assembly capacity under PLI scheme incentives for appliance motor control demand. White-space concentrates in halogen-free conductive plastic supply to Swiss and German professional audio manufacturers. Go-to-market leverage: certified green chemistry disclosure as procurement gate pass. For Investors and Strategic Acquirers: Capital is best deployed toward precision-specialist manufacturers with captive IEC 60393 qualification records and medical device approved vendor list status. Long-term viability favors suppliers bridging mechanical and digital architectures for automotive electrification. Signal to watch: battery management system calibration socket awards at Nagoya-area tier-ones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Plastic Formulation | REACH-compliant halogen-free resin supply locks in European medical and audio OEM procurement. |
| IEC 60393 Qualification Investment | Aerospace and defense channel access requires extended certification cycles that filter competitor entry. |
| Digital Potentiometer Platform Development | Automotive battery management architectures displace mechanical trimmers with software-configurable alternatives. |
| India PLI Scheme Manufacturing Footprint | Localized assembly capacity captures appliance motor control demand from contract manufacturers. |
| Halogen-Free Material Certification Pipeline | Full material disclosure compliance opens Swiss and German professional audio procurement gates. |
Study Parameters
Initial hypotheses were tested against primary input from potentiometer procurement managers at automotive tier-ones, biomedical engineers at surgical robotics OEMs, plant managers at conductive plastic formulation houses, and distribution channel partners at Digi-Key and Mouser, then refined against secondary validation from SEC filings, customs trade records, IEC certification databases, and ECHA substance restriction updates. Bottom-up segment sizing triangulated with top-down industry value chain analysis.
Demand-supply balance modeling across the projection horizon incorporated product type (rotary, linear, digital, tapered), application vertical (consumer electronics, automotive, industrial, medical), technology (conductive plastic, carbon composition, wirewound, optical), and end user channel (manufacturers, repair services, DIY, educational). CAGRs derived from regression against historical qualification cycle timelines and substitution elasticity parameters. Industry-specific inputs included automotive electrification architecture roadmaps and medical device FDA/MDR approval trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese contract manufacturers or accelerated optical sensor substitution in industrial automation would shift outcomes. Material shifts in REACH substance restrictions, palladium price volatility, or battery management system calibration standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Global PH Sensor Market