
 Digital Humidity Sensor Market | 2026-2036
Digital Humidity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Humidity Sensor Market Outlook
The capability gap between MEMS-integrated humidity sensor producers and discrete component suppliers is collapsing as wafer-level packaging costs fall. Texas Instruments leverages its analog front-end expertise to bundle humidity sensing with signal conditioning on single dies. Sensirion AG sustains Swiss precision manufacturing for medical and laboratory-grade calibration standards. Bosch Sensortec GmbH dominates automotive cabin-climate applications through backward integration into its broader environmental sensor portfolio.
A digital humidity sensor measures water vapor concentration in air or gas streams, typically employing capacitive polymer films that shift dielectric properties across zero to one-hundred percent relative humidity ranges; these devices output calibrated digital signals through I2C or SPI interfaces for direct microcontroller integration. Capacitive sensors occupy the largest value share due to their stability in industrial process control and HVAC systems, while wireless technology variants are recording the fastest expansion as IoT retrofit installations multiply across agricultural monitoring networks. Resistive sensors retain niche positions in cost-constrained consumer electronics, though margin pools concentrate in integrated modules serving pharmaceutical cold-chain validation.
The EPA enforces indoor air quality standards that mandate humidity monitoring in commercial buildings, while FDA 21 CFR Part 11 guidelines shape validation protocols for sensors deployed in pharmaceutical manufacturing environments. The EU Green Deal's building renovation targets are tightening HVAC efficiency requirements across member states, directly expanding addressable demand for precision humidity control. Stakeholders must monitor how emerging battery-humidity safety standards for electric vehicles create new qualification barriers for sensor suppliers seeking automotive qualification.
Market Dynamics
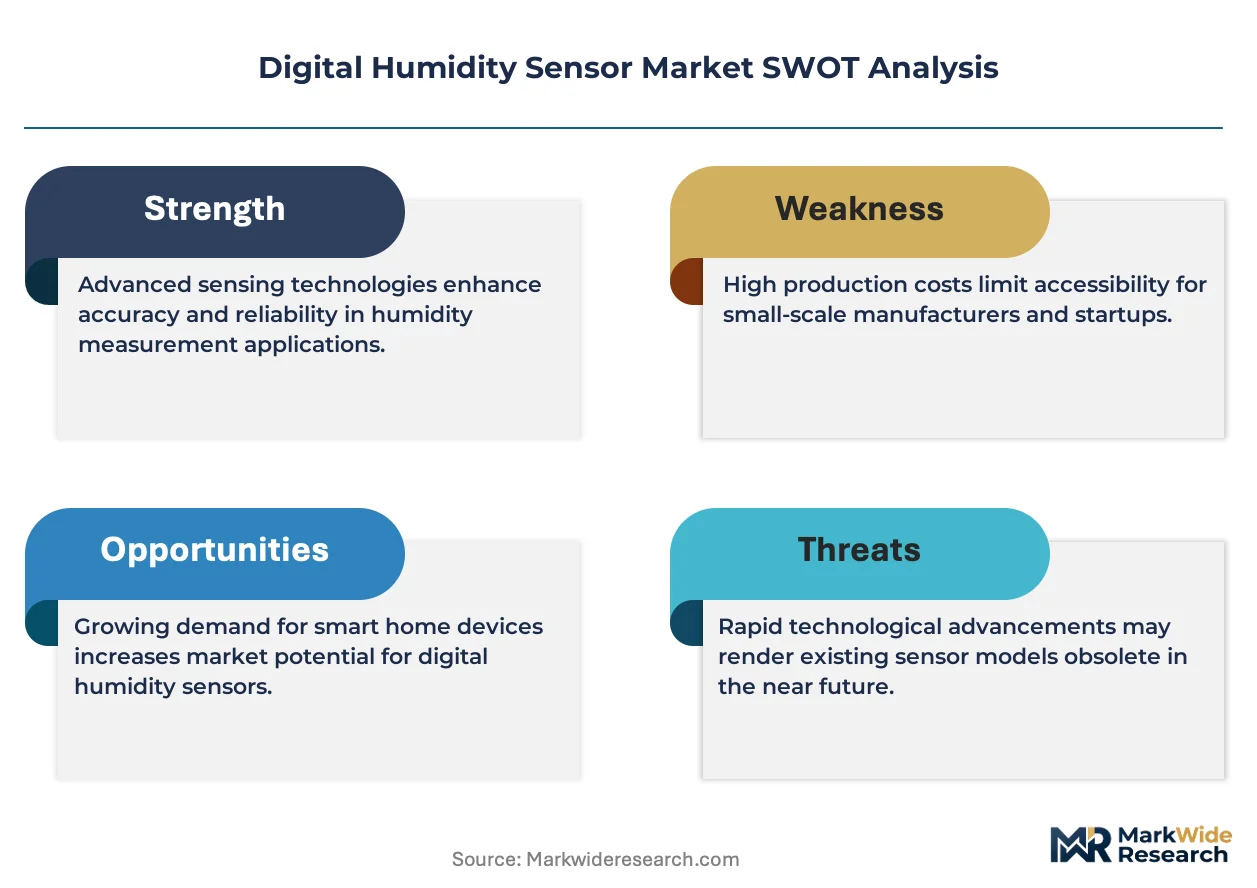
Wafer-level packaging cost compression is collapsing the traditional boundary between MEMS-integrated and discrete humidity sensor architectures, forcing suppliers to consolidate analog front-end and sensing functions on single dies or surrender margin to module integrators.
Growth Catalysts
- EPA Indoor Air Quality Mandates:Commercial building operators across the United States must deploy continuous humidity monitoring to comply with ventilation standards, expanding retrofit demand for digital sensors with I2C outputs.
- EU F-Gas Regulation:Refrigeration and HVAC leak-detection systems throughout Germany, France, and Italy now require precision humidity tracking to identify refrigerant loss events, accelerating sensor replacement cycles.
- Precision Agriculture Sensor Networks:California's Central Valley and the Netherlands' greenhouse clusters are installing wireless humidity nodes for irrigation control, creating volume pull for low-power digital variants.
Market Restraints
- Polymer Film Input Volatility:Capacitive sensing elements depend on specialized dielectric polymers whose prices fluctuate with petrochemical feedstock costs, squeezing gross margins for mid-tier suppliers.
- Foundry Concentration Risk:Advanced MEMS fabrication for automotive-grade sensors concentrates at TSMC and GlobalFoundries facilities in Taiwan and Singapore, exposing supply chains to geographic concentration vulnerability.
- Resistive Sensor Substitution:Cost-constrained consumer electronics manufacturers in Shenzhen and Dongguan continue specifying resistive humidity elements for white goods, capping pricing power for digital alternatives.
Strategic Opportunities
- Battery Safety Standards:Emerging qualification protocols for electric vehicle battery packs require humidity monitoring to detect thermal runaway precursors, creating new automotive certification pathways.
- India PLI Scheme Incentives:Production-linked incentives for electronic components manufacturing are attracting humidity sensor assembly operations to Gujarat and Tamil Nadu industrial corridors.
- LoRaWAN Agricultural Networks:Brazilian soybean operations and Australian wheat belt farmers are deploying long-range wireless humidity sensors for soil moisture correlation, opening greenfield IoT retrofit demand.
Industry Challenges
- Medical Calibration Expertise Gap:Pharmaceutical cold-chain validation requires Swiss-grade calibration protocols that few Asian contract manufacturers can replicate, constraining supply expansion.
- Automotive Qualification Timelines:AEC-Q100 certification cycles extend 18-24 months, locking working capital and delaying revenue recognition for new sensor designs targeting cabin climate systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Humidity Sensor Market |
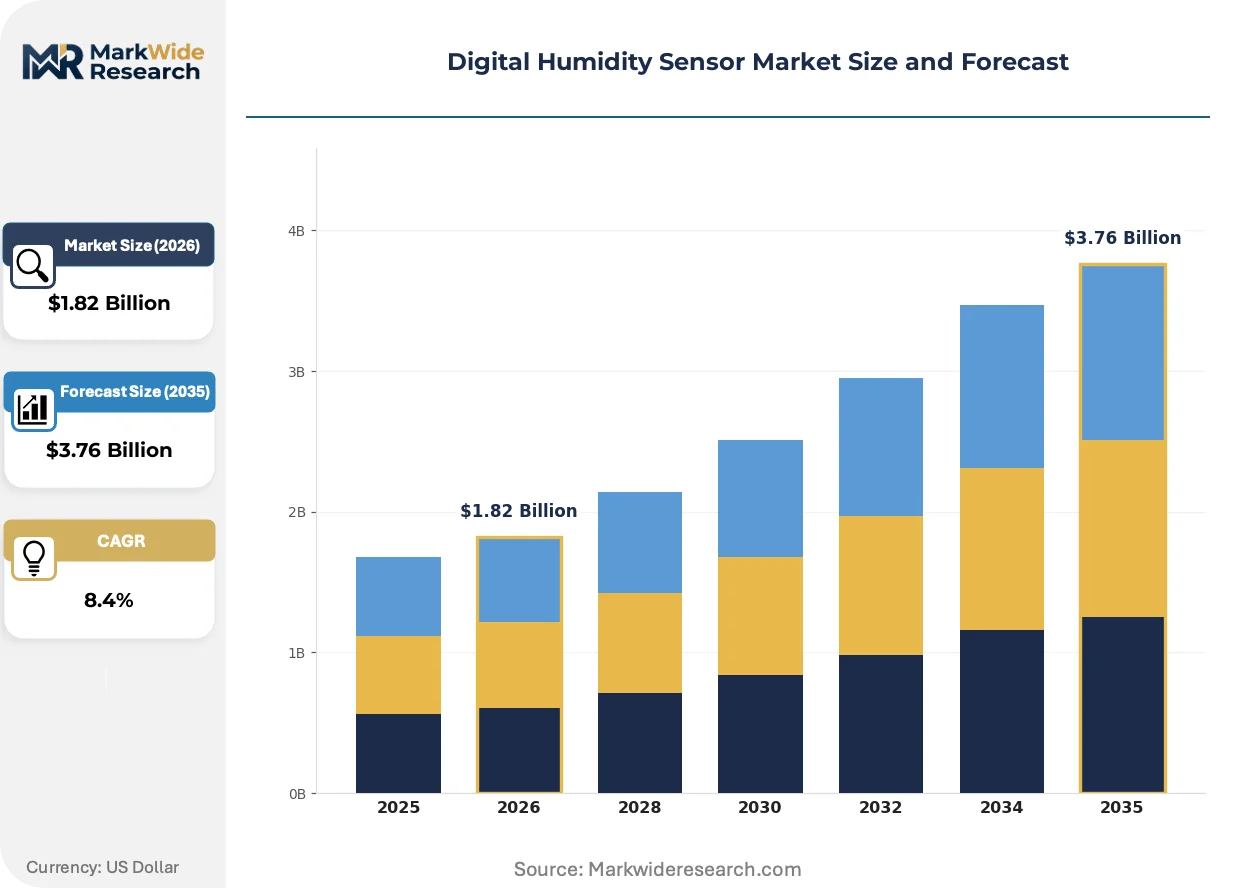
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Resistive Sensors, Thermal Sensors, Hygrometers Technology: Analog, Digital, Wireless, Infrared End User: Agriculture, HVAC, Consumer Electronics, Industrial Automation Installation: Fixed, Portable, Integrated, Remote |
| Companies Covered | Honeywell International, Sensirion AG, Texas Instruments, TE Connectivity, Bosch Sensortec GmbH, STMicroelectronics, Amphenol Advanced Sensors, Analog Devices, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Humidity Sensor Market Strategic Shifts
Multi-sensor fusion architectures are redefining competitive boundaries as environmental monitoring demands converge temperature, pressure, and humidity data streams into unified digital outputs for edge computing applications.
Silicon CMOS-MEMS co-integration is fragmenting the traditional sensor module supply chain. Bosch Sensortec and Texas Instruments now embed humidity sensing directly alongside temperature and pressure elements on single die substrates. Automotive tier-1 suppliers in Stuttgart and Detroit are adopting these consolidated modules to reduce BOM line items and assembly labor. The shift is fragmenting revenue pools previously captured by discrete component distributors.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of capacitive polymer sensing films used in industrial process control equipment. German chemical suppliers at BASF and Evonik are accelerating development of fluorine-free dielectric alternatives. Medical device manufacturers in Switzerland and laboratory equipment builders in Massachusetts face the tightest compliance deadlines and are pre-qualifying next-generation sensor variants.
Subscription-based sensor calibration services are displacing traditional hardware-only procurement in pharmaceutical manufacturing. Merck KGaA and Lonza are contracting Sensirion for continuous recertification of cleanroom monitoring networks. The model concentrates recurring revenue with precision-calibration specialists while commoditizing raw hardware supply. FDA 21 CFR Part 11 validation requirements in Maryland and New Jersey facilities are accelerating this behavioral shift.
Digital Humidity Sensor Market Segmentation
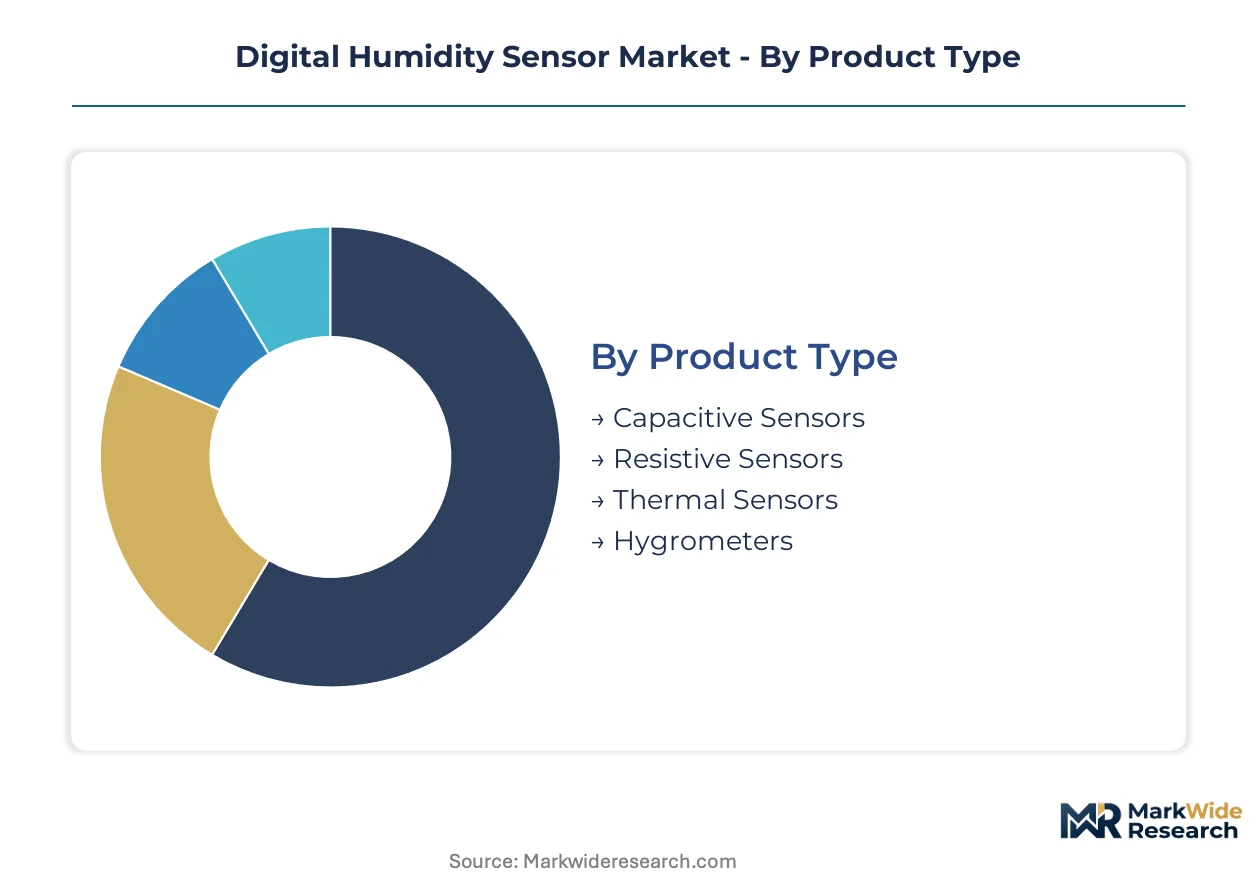
Segmentation in the Digital Humidity Sensor Market reveals how technical specifications, connectivity protocols, and deployment contexts fragment procurement patterns across precision agriculture, pharmaceutical manufacturing, and automotive cabin systems. Buyers select sensor architectures based on calibration requirements, power budgets, and integration complexity rather than unit cost alone.
Product Type:
Capacitive and resistive variants dominate domestic manufacturing footprints in Germany and Switzerland, while thermal sensors and hygrometers concentrate in export-oriented supply chains serving Asian industrial automation corridors.
- Capacitive Sensors:Polymer dielectric films shift electrical properties across relative humidity ranges, enabling stability in HVAC and process control installations. Demand clusters in Germany's industrial automation corridor and California's Central Valley precision agriculture networks, where EPA indoor air quality mandates and irrigation efficiency targets drive replacement cycles.
- Resistive Sensors:Ceramic or polymer elements alter conductivity with moisture absorption, sacrificing precision for cost advantages in high-volume applications. Shenzhen and Dongguan consumer electronics manufacturers specify these for white goods and appliances, though margin compression limits supplier pricing power.
- Thermal Sensors:Psychrometric principles measure humidity through wet-bulb/dry-bulb differential temperature readings.
- Hygrometers:Mechanical or electronic instruments provide standalone humidity measurement for laboratory and meteorological validation.
Capacitive sensors command the established base. The steepest expansion runs through thermal sensors serving pharmaceutical cold-chain applications.
Technology:
Cost tier differentiation separates analog architectures in legacy industrial equipment from digital and wireless variants capturing IoT retrofit budgets across agricultural monitoring networks.
- Analog:Continuous voltage or current outputs require external ADC conversion, retaining position in legacy process control infrastructure where microcontroller integration costs exceed replacement economics.
- Digital:I2C and SPI interfaces deliver calibrated outputs direct to microcontrollers, dominating new HVAC and automotive cabin climate designs where BOM simplification drives selection. Texas Instruments and Bosch Sensortec bundle these with temperature and pressure sensing on single dies.
- Wireless:LoRaWAN and Bluetooth Low Energy protocols eliminate wiring in distributed agricultural sensor networks.
- Infrared:Spectroscopic absorption techniques enable non-contact measurement in harsh chemical process environments.
Digital technology anchors current revenue pools. Wireless variants are climbing the fastest as Brazilian soybean operations and Australian wheat belt farmers deploy long-range humidity nodes.
End User:
Application maturity determines margin structures, with pharmaceutical and automotive qualification requirements sustaining premium pricing against commoditized consumer electronics procurement.
- Agriculture:Soil moisture correlation and greenhouse climate control drive wireless sensor deployment in the Netherlands' glasshouse clusters and California's Central Valley, where water stress regulations intensify monitoring requirements.
- HVAC:Building automation systems across Germany, France, and Italy incorporate precision humidity tracking to satisfy EU F-Gas Regulation leak-detection mandates and Green Deal renovation efficiency targets.
- Consumer Electronics:Smart home devices and wearables specify compact, low-cost elements with reduced calibration requirements.
- Industrial Automation:Factory-floor environmental monitoring and process control demand Swiss-grade calibration protocols that few Asian contract manufacturers replicate.
HVAC applications concentrate the largest installed base. Agriculture is expanding most quickly through IoT retrofit installations.
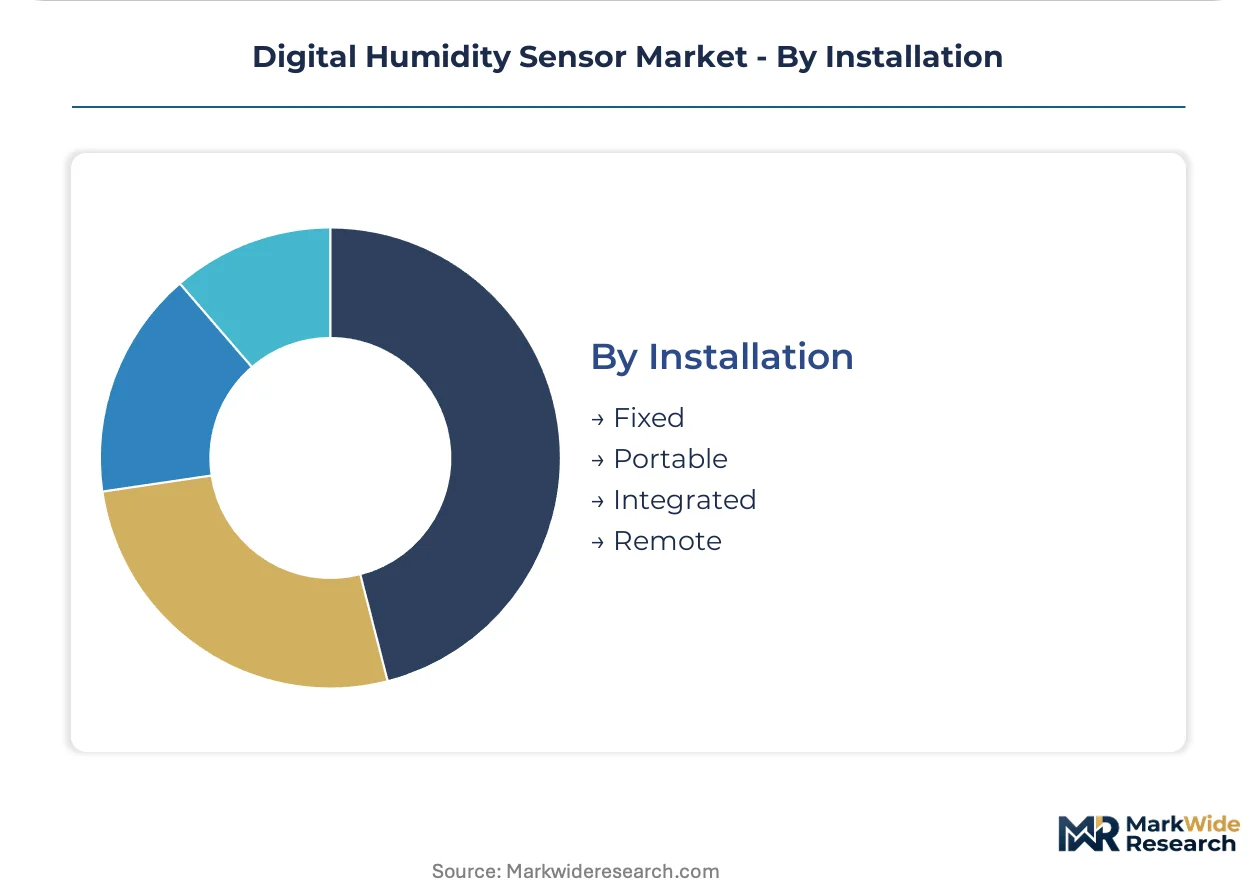
Installation:
Volume scale separates fixed infrastructure deployments from portable and remote configurations serving distributed monitoring requirements.
- Fixed:Permanent mounting in building automation and process equipment dominates unit economics, with German automotive tier-1 suppliers in Stuttgart consolidating multi-sensor modules to reduce assembly labor.
- Portable:Handheld validation instruments serve pharmaceutical cleanroom certification and field calibration services.
- Integrated:Multi-sensor fusion architectures embed humidity alongside temperature, pressure, and gas sensing in unified environmental monitoring nodes.
- Remote:Battery-powered wireless nodes eliminate cabling in agricultural and warehouse applications.
Fixed installations retain the dominant revenue share. Remote configurations are gaining share fastest through precision agriculture network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German precision manufacturing corridors, while volume manufacturing gravitates toward cost-optimized Asian assembly hubs. This asymmetry shapes procurement patterns across automotive qualification tiers and pharmaceutical calibration standards.
United States
Precision agriculture networks in California's Central Valley and EPA indoor air quality mandates for commercial buildings drive sensor deployment. The EPA enforces continuous humidity monitoring in ventilation systems. Boston-area pharmaceutical manufacturers maintain Swiss-grade calibration requirements for cold-chain validation.
Germany
Industrial automation corridors around Stuttgart and Munich anchor demand for automotive cabin-climate and factory-floor environmental monitoring. The EU F-Gas Regulation accelerates replacement cycles for refrigeration leak-detection systems. Bosch Sensortec's backward integration into environmental sensor portfolios dominates supply chains serving tier-1 automotive suppliers.
Switzerland
Medical device manufacturers and laboratory equipment builders sustain premium pricing for precision-calibrated humidity sensors. Swissmedic compliance deadlines tighten for cleanroom monitoring networks. Sensirion AG maintains manufacturing protocols that Asian contract manufacturers struggle to replicate.
China
Shenzhen and Dongguan consumer electronics manufacturers specify resistive humidity elements for cost-constrained white goods production. NMPA guidelines shape medical device sensor requirements. Yangtze River Delta industrial clusters absorb volume production for domestic HVAC retrofit programs.
India
Gujarat and Tamil Nadu industrial corridors attract humidity sensor assembly operations through Production-Linked Incentive schemes. BIS certification requirements for electronic components tighten import substitution timelines. Maharashtra pharmaceutical manufacturers import Swiss-calibrated sensors for API manufacturing environments.
Digital Humidity Sensor Market Competitive Environment
Concentration sits with diversified semiconductor conglomerates and precision MEMS specialists. The vendor base separates into three tiers: integrated environmental sensor platforms, discrete component specialists, and contract manufacturing assemblers. Strategic moves center on wafer-level packaging consolidation and multi-sensor fusion architectures that collapse analog front-end boundaries.
Among diversified semiconductor conglomerates, Texas Instruments and STMicroelectronics exemplify platform consolidation through analog front-end bundling. Sensirion AG occupies a position within the precision-calibration specialist tier, anchoring medical and laboratory-grade standards. Bosch Sensortec GmbH represents automotive integration archetypes through captive supply of environmental sensor portfolios. These three anchors illustrate how capability gaps between MEMS-integrated and discrete architectures are collapsing as packaging costs compress.
| Leading Market Players |
|---|
| Honeywell International |
| Sensirion AG |
| Texas Instruments |
| TE Connectivity |
| Bosch Sensortec GmbH |
| STMicroelectronics |
| Amphenol Advanced Sensors |
| Analog Devices |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Wafer-level packaging scale economies at TSMC and GlobalFoundries facilities compress unit costs for MEMS-integrated humidity sensors, concentrating pricing power with suppliers who control analog front-end bundling while marginalizing discrete component vendors. This cost structure elevates price floors for automotive-grade AEC-Q100 qualified sensors above consumer electronics tiers, where Shenzhen contract manufacturers extract concessions through volume consolidation.
Pricing Analysis
The customization-premium spread between Swiss-grade calibrated sensors and standard I2C-output variants reaches three-to-one multiples, with Sensirion AG commanding configured-to-order pricing for pharmaceutical clean-chain validation against commoditized Asian assembly. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive modules from HVAC retrofit components and resistive white-goods elements. Pricing pressure stems from polymer film input volatility tied to petrochemical feedstock costs, squeezing mid-tier suppliers without backward integration into polymer dielectric production. Consumer electronics manufacturers in Dongguan exhibit highest price sensitivity, while Boston-area pharmaceutical manufacturers accept premium positioning for FDA 21 CFR Part 11 compliance.
Supply Chain Analysis
Container availability constraints on transpacific lanes from Taiwan and Singapore elevate inbound logistics costs for MEMS wafer shipments, forcing inventory pre-positioning at German automotive tier-1 hubs. Advanced fabrication concentrates in Taiwan, Singapore, and South Korea, drawing from specialized dielectric polymers, ceramic substrates, and precision calibration equipment. Single-source vulnerability at TSMC automotive MEMS lines exposes supply chains to geographic concentration risk. Distribution runs through Stuttgart and Detroit automotive corridors for cabin climate modules, with Swiss direct-ship protocols serving pharmaceutical validation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Humidity Sensor Market enters a cyclical recovery phase as precision agriculture capital expenditure rebounds from drought-driven deferrals and EU Green Deal renovation targets reactivate HVAC retrofit demand.
For Market Incumbents: Compound defensive positioning through captive supply of polymer dielectric films, insulating margin structures from petrochemical volatility that threatens mid-tier competitors. Deepen AEC-Q100 certification pipelines to lock automotive tier-1 relationships before emerging battery-safety standards create new qualification barriers. Prioritize backward integration into wafer-level packaging to collapse cost gaps with module integrators. For New Entrants and Emerging Players: Differentiate on LoRaWAN wireless protocol specialization for Brazilian soybean and Australian wheat belt agricultural networks, where incumbent environmental sensor platforms lack low-power long-range optimization. Target Gujarat and Tamil Nadu assembly corridors under India's PLI scheme, exploiting tariff advantages for domestic HVAC retrofit programs. Pursue hospital procurement channel partnerships for cleanroom monitoring calibration services, displacing hardware-only procurement with subscription-based recertification models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Swiss-grade calibration specialists serving pharmaceutical manufacturing, where FDA validation requirements lock multi-year service contracts and concentrate lifetime value beyond initial hardware shipment. Long-term viability favors precision-MEMS specialists with medical-grade manufacturing protocols that Asian contract manufacturers cannot replicate. Watch battery-humidity safety standard finalization as inflection indicator for automotive certification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Development | Bosch Sensortec and Texas Instruments consolidate temperature, pressure, and humidity on single dies, reducing automotive BOM line items. |
| Fluorine-Free Polymer Reformulation | BASF and Evonik accelerate REACH-compliant dielectric alternatives, forcing sensor suppliers to pre-qualify next-generation variants. |
| Subscription Calibration Service Launch | Sensirion contracts with Merck KGaA and Lonza for continuous pharmaceutical cleanroom recertification, concentrating recurring revenue. |
| PLI-Aligned Assembly Expansion | Gujarat and Tamil Nadu industrial corridors attract sensor manufacturing through Indian government production-linked incentives. |
| LoRaWAN Agricultural Network Deployment | Brazilian soybean operations and Australian wheat belt farmers adopt long-range wireless humidity nodes for soil moisture correlation. |
Study Parameters
A spread of perspectives from MEMS fabrication engineers, automotive tier-1 procurement managers, pharmaceutical cleanroom validation specialists, and precision agriculture network operators converged on the working assumptions for sensor deployment trajectories across HVAC, automotive, and agricultural end uses. Primary interview insights were cross-referenced against secondary validation from EPA indoor air quality enforcement records, EU F-Gas Regulation implementation reports, FDA 21 CFR Part 11 guidance documents, and Indian BIS certification databases. Bottom-up unit economics for capacitive and resistive sensor variants were triangulated against top-down market sizing derived from wafer-level packaging capacity disclosures.
Segmentation dimensions modeled include sensor technology type, connectivity protocol architecture, end-use industry vertical, and geographic regulatory cluster across the analysis window. CAGRs were derived from installed base replacement cycles, new-build penetration assumptions, and technology substitution elasticities. Industry-specific forecast inputs incorporated AEC-Q100 certification timeline delays, REACH substance restriction compliance deadlines, and precision agriculture water stress regulation intensity indices.
Material uncertainties — polymer feedstock cost volatility, foundry concentration disruptions, and battery safety standard finalization timelines — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and agricultural capital expenditure recovery patterns. Recalibration cycles align with material shifts in EU Green Deal renovation targets and emerging electric vehicle qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Potentiometer Market