
 Current Calibrator Market | 2026-2036
Current Calibrator Market Size, Share, and Industry Trends Forecast 2026-2036
Current Calibrator Market Outlook
Chinese bench-mounted instrument manufacturers is rebalancing capacity toward precision calibration modules for export markets. Fluke Corporation leverages its North American service network to sustain aftermarket calibration contracts across utility fleets. Keysight Technologies anchors its position through R&D intensity in RF and microwave calibration standards for telecommunications labs. Yokogawa Electric competes in process industry segments where integrated distributed control systems require continuous loop calibration.
A current calibrator is a precision electronic instrument that generates stable, known electrical signals—typically DC voltage, current, resistance, or frequency—with specified accuracy and stability parameters for verifying and adjusting measurement devices. Manufacturing plants deploy these instruments to maintain traceability chains for production-line sensors, while laboratories rely on them for ISO 17025-accredited calibration procedures. Multifunctional calibrators dominate the product mix by unit volume due to their versatility across electrical disciplines, though pressure calibrators command premium positioning in oil and gas process streams. Digital calibration technology leads the technology dimension as facilities replace analog units, yet smart calibration systems with embedded diagnostics represent the fastest-expanding margin pool.
IEC 17025 accreditation requirements and NIST-traceable standards shape procurement criteria for end users in regulated industries, while FDA 21 CFR Part 11 compliance drives validation protocols in pharmaceutical manufacturing environments. EPA emissions monitoring rules mandate periodic calibration of continuous emissions monitoring systems, sustaining replacement demand for electrical calibrators in utility stacks. Stakeholders must monitor how wireless calibration architectures disrupt traditional bench-mounted installation patterns without sacrificing traceability documentation.
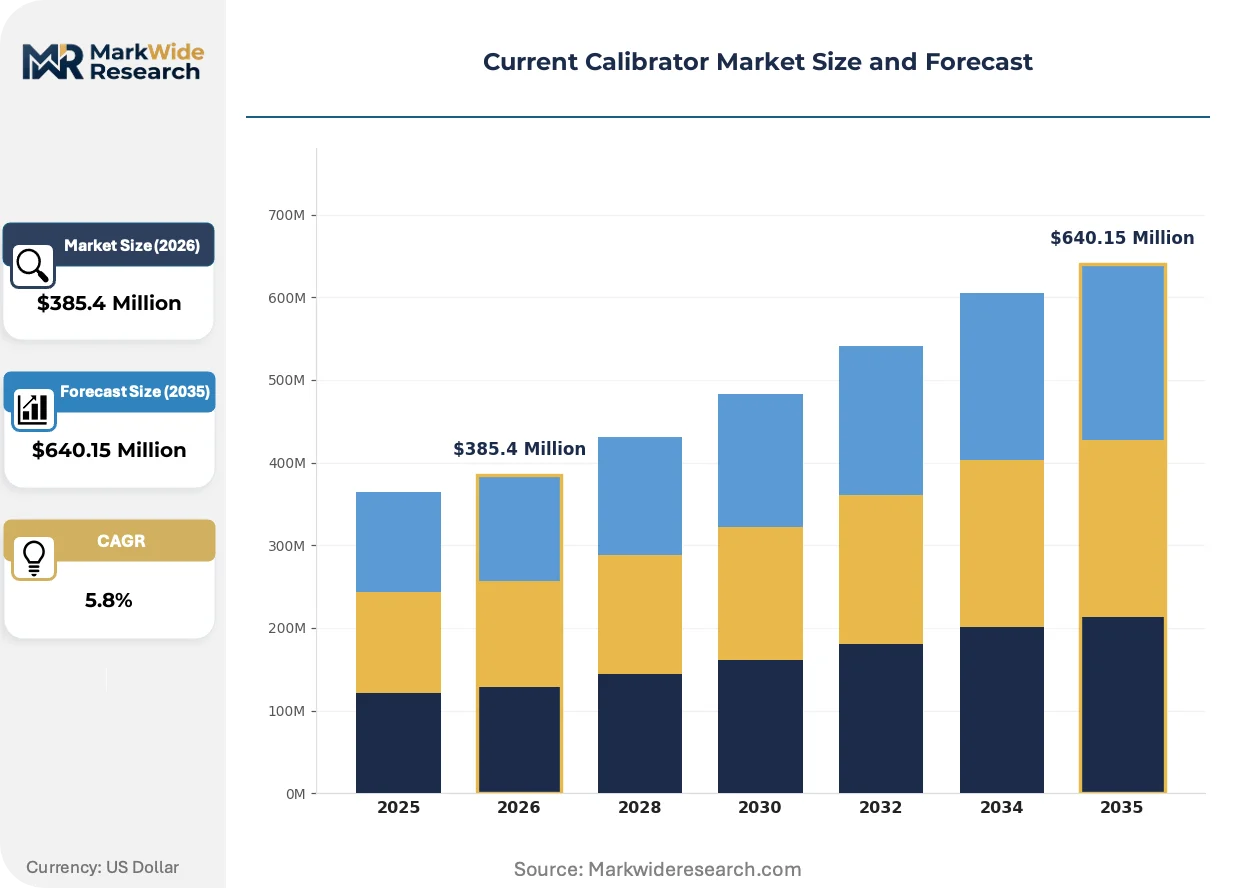
Market Dynamics
Digital calibration protocols under IEC standards are systematically displacing legacy analog workflows across industrial facilities, compressing replacement cycles and reshaping vendor competitive positioning around software-enabled traceability architectures.
Growth Catalysts
- Grid Stability Mandates:Power generation utilities in Germany are expanding calibration protocols for instrumentation tied to frequency regulation and voltage control, sustaining replacement demand for precision current sources.
- IEC 17025 Accreditation Pressure:ISO 17025 requirements for laboratory competence are forcing manufacturing plants to upgrade calibration equipment to maintain traceability chains for production-line sensors.
- Automotive Electrification:Precision engineering clusters supporting German automotive OEM supplier networks require dense calibration service ecosystems for battery management system validation.
Market Restraints
- Reference Standard Volatility:High-precision voltage references and temperature-stabilized resistors face input cost volatility due to concentrated specialty component supply from Japanese and German precision component manufacturers.
- Technical Obsolescence Risk:Analog calibration units retain residual utility in legacy process loops, creating technical friction against full digital migration in brownfield industrial facilities.
- Regulatory Fragmentation:Divergent FDA 21 CFR Part 11 validation protocols versus EPA emissions monitoring calibration intervals create compliance complexity for multi-site pharmaceutical and utility operators.
Strategic Opportunities
- Wireless Calibration Architectures:Embedded diagnostics in smart calibration systems enable remote verification without bench-mounted installation, opening service model innovation for distributed utility fleets.
- Pharmaceutical Manufacturing Expansion:FDA 21 CFR Part 11 compliance mandates in North American and European drug production facilities are accelerating validation protocol automation.
- Process Industry Integration:Continuous loop calibration requirements in oil and gas distributed control systems create attach opportunities for multifunctional calibrator vendors alongside Yokogawa and similar automation suppliers.
Industry Challenges
- Metrology Talent Scarcity:ISO 17025-accredited calibration procedures require specialized metrology expertise that manufacturing plants struggle to recruit and retain at competitive compensation levels.
- Legacy System Integration:Brownfield facilities face execution complexity when interfacing digital calibration protocols with analog-era distributed control systems and proprietary fieldbus architectures.
- Certification Timeline Compression:NIST-traceable standards verification and IEC accreditation renewal cycles consume operational bandwidth, delaying equipment deployment in regulated industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Current Calibrator Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multifunctional Calibrators, Pressure Calibrators, Temperature Calibrators, Electrical Calibrators Technology: Analog Calibration, Digital Calibration, Smart Calibration, Wireless Calibration End User: Manufacturing Plants, Laboratories, Aerospace, Telecommunications Installation: Bench-Mounted, Portable, Fixed, Integrated Systems |
| Companies Covered | Fluke Corporation, Keysight Technologies, Inc., Yokogawa Electric Corporation, WIKA Alexander Wiegand SE & Co. KG, Beamex Oy Ab, Time Electronics Ltd., Tektronix, Inc., Transmille Ltd., AMETEK Calibration Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Current Calibrator Market Strategic Shifts
Smart calibration systems with embedded diagnostics are capturing margin expansion as facilities prioritize predictive maintenance over reactive calibration scheduling, while wireless architectures disrupt traditional installation patterns without sacrificing traceability documentation.
Multifunctional calibrators are absorbing software-defined functionality that previously required discrete instrument categories, compressing vendor product line breadth requirements. Automotive tier-one suppliers in Germany are adopting these platforms at accelerated replacement cycles to support electric powertrain validation labs. This technology convergence is absorbing service revenue from standalone pressure and temperature calibrator categories into unified electrical platforms.
EPA emissions monitoring rules mandating periodic calibration of continuous emissions monitoring systems are forcing utility stack operators into tighter compliance documentation cycles. Industrial consequence includes sustained replacement demand for electrical calibrators capable of automated logging and tamper-evident data integrity. US utility fleets are responding by consolidating vendor relationships around service providers with embedded EPA compliance expertise.
After-sales service unbundling is fragmenting traditional calibration equipment purchasing patterns as end-users separate hardware acquisition from ongoing traceability maintenance contracts. Industrial distributors in North America are losing attach revenue to specialized metrology service firms offering subscription-based accreditation management. This behavioral shift is most visible in pharmaceutical manufacturing environments where FDA validation protocols favor third-party calibration independence over in-house capability.
Current Calibrator Market Segmentation
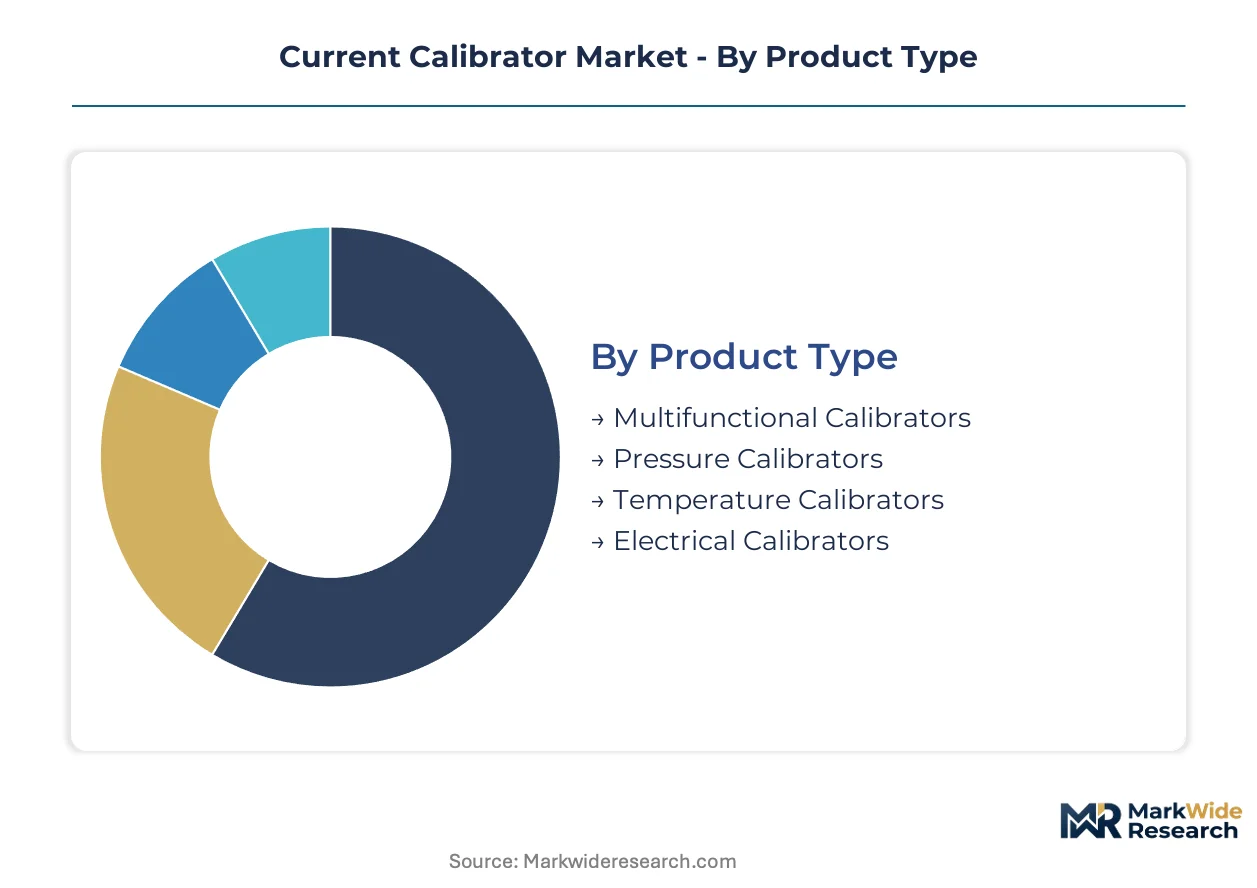
Current calibrator procurement patterns diverge sharply across product architectures and deployment contexts. Manufacturing plants prioritize traceability chains for production-line sensors, while laboratories demand ISO 17025-accredited platforms for metrology-grade verification.
Product Type:
Customization intensity varies from configurable multifunction platforms to single-parameter dedicated units engineered for extreme precision.
- Multifunctional Calibrators:These platforms generate DC voltage, current, resistance, and frequency signals through unified architectures. German automotive OEM supplier networks sustain dense calibration service ecosystems for these versatile units. IEC 17025 accreditation requirements force manufacturing plants to upgrade these systems to maintain production-line sensor traceability.
- Pressure Calibrators:Specialized instruments for pneumatic and hydraulic measurement verification feature precision pressure generation modules. Oil and gas process streams command premium positioning for these units due to continuous loop calibration requirements in distributed control systems. EPA emissions monitoring rules sustain replacement demand for electrical calibrators capable of automated logging in utility stack applications.
- Temperature Calibrators:Dry-block and liquid bath configurations provide stable thermal references for sensor verification.
- Electrical Calibrators:Dedicated current and voltage source instruments serve power generation utilities expanding calibration protocols for grid stability instrumentation.
Most installed capacity flows through Multifunctional Calibrators. Expansion is steepest in Pressure Calibrators.
Technology:
Cost tier stratification separates legacy analog investments from premium smart systems with embedded diagnostics.
- Digital Calibration:IEC-standard protocols systematically displace legacy analog workflows across industrial facilities. Brownfield sites in Germany face execution complexity when interfacing these systems with analog-era distributed control systems. Digital units compress replacement cycles through software-enabled traceability architectures.
- Smart Calibration:Embedded diagnostics enable predictive maintenance scheduling and remote verification capabilities. Wireless architectures disrupt traditional bench-mounted installation patterns without sacrificing traceability documentation. Pharmaceutical manufacturing environments favor these systems for FDA 21 CFR Part 11 compliance automation.
- Analog Calibration:Legacy units retain residual utility in brownfield process loops despite technical obsolescence risk.
- Wireless Calibration:Emerging architectures enable distributed utility fleet service model innovation.
Digital Calibration commands the largest installed base. Smart Calibration is gaining share fastest among regulated industries.
End User:
Application-specific requirements drive divergent specification priorities across laboratory precision and industrial durability contexts.
- Manufacturing Plants:Production-line sensor traceability chains require robust calibration protocols. ISO 17025-accredited procedures force these facilities to recruit scarce metrology talent at competitive compensation levels. NIST-traceable standards verification consumes operational bandwidth during equipment deployment.
- Laboratories:Metrology-grade facilities demand highest accuracy and stability parameters for measurement device verification. Certification timeline compression from IEC accreditation renewal cycles delays equipment deployment. Third-party calibration independence is favored over in-house capability in pharmaceutical validation protocols.
- Aerospace:Stringent documentation requirements for flight-critical measurement systems.
- Telecommunications:RF and microwave calibration standards for telecommunications labs anchor Keysight Technologies positioning.
Manufacturing Plants represent the dominant volume segment. Laboratories show the steepest margin expansion trajectory.
Installation:
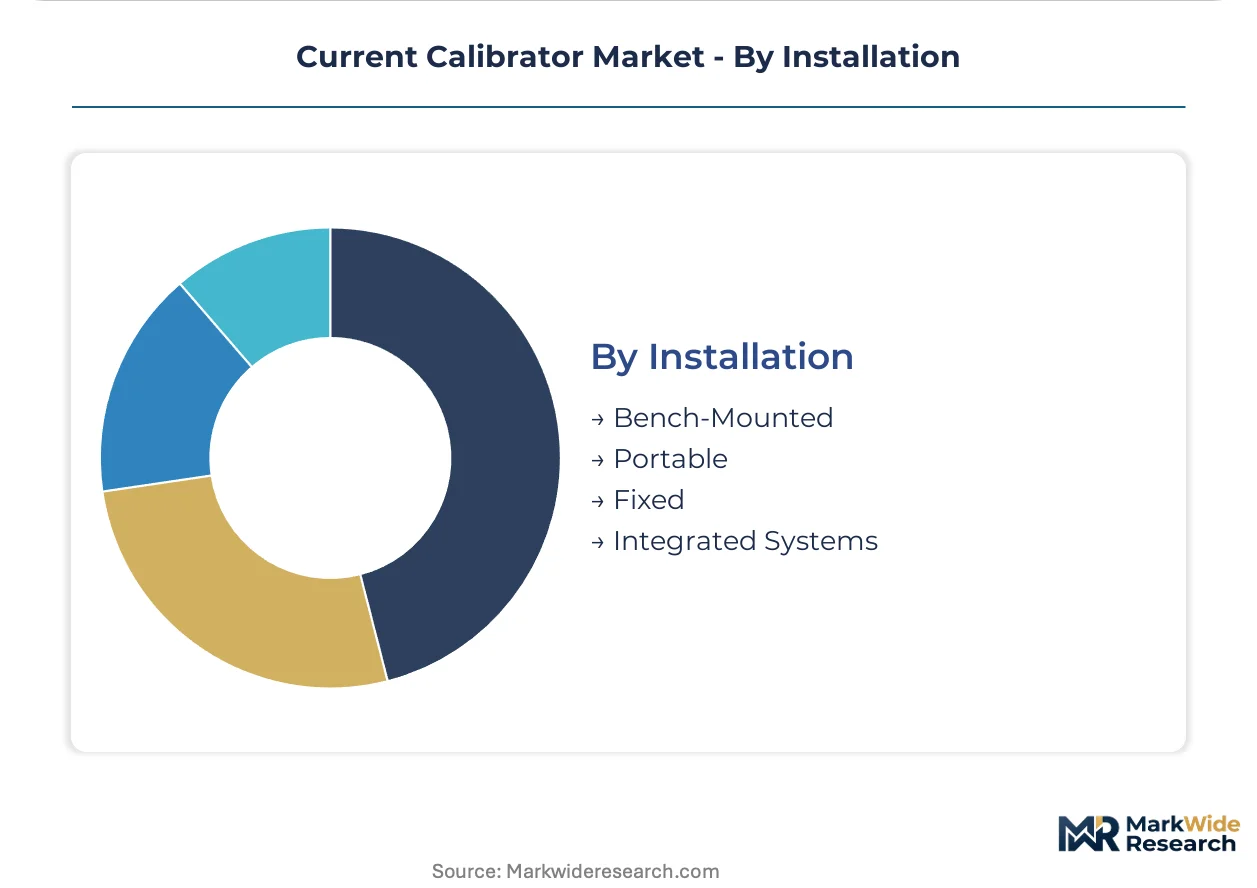
Volume concentration favors portable and bench-mounted formats, while margin pools concentrate in integrated system architectures.
- Bench-Mounted:Traditional laboratory and shop-floor configurations dominate unit volume. Chinese manufacturers are rebalancing capacity toward precision calibration modules for export markets in this category. After-sales service unbundling fragments traditional purchasing patterns as end-users separate hardware acquisition from traceability maintenance.
- Portable:Field-service configurations enable distributed calibration workflows across utility fleets. North American industrial distributors are losing attach revenue to specialized metrology service firms offering subscription-based accreditation management.
- Fixed:Permanent installations in process control environments.
- Integrated Systems:Continuous loop calibration requirements in oil and gas distributed control systems create attach opportunities alongside automation suppliers.
Bench-Mounted systems carry the largest installed base. Integrated Systems are climbing the fastest in process industry deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
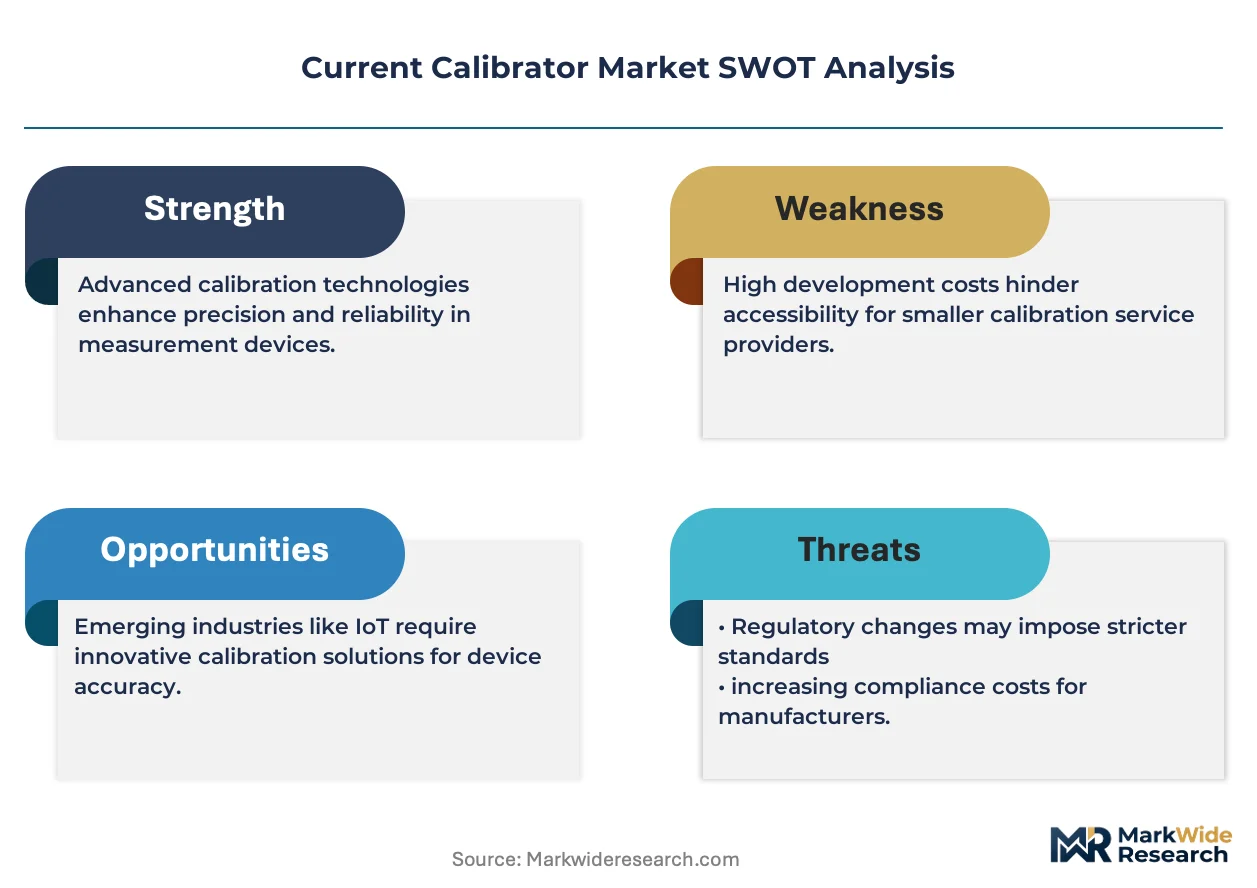
Calibration equipment production migrates toward jurisdictions with streamlined metrology accreditation frameworks, creating cost-of-compliance arbitrage between established precision engineering clusters and emerging manufacturing hubs.
Germany
Automotive electrification and grid stability mandates drive calibration protocol expansion across precision engineering clusters. KBA vehicle certification requirements and IEC 17025 laboratory accreditation standards shape procurement criteria for OEM supplier networks. Stuttgart and Munich manufacturing corridors sustain dense calibration service ecosystems for battery management system validation.
United States
Pharmaceutical manufacturing expansion and utility fleet consolidation sustain replacement demand for automated calibration systems. FDA 21 CFR Part 11 validation protocols and EPA emissions monitoring rules mandate periodic calibration documentation in drug production and power generation facilities. Houston energy corridor and Boston biotech cluster concentrate demand for NIST-traceable electrical calibrators.
China
Bench-mounted instrument manufacturers rebalance capacity toward precision calibration modules targeting export markets. MIIT industrial standardization directives and GB national standards accelerate digital calibration adoption in process industries. Yangtze River Delta electronics manufacturing belt generates demand for multifunctional calibrator platforms serving semiconductor fabrication lines.
Japan
Specialty component supply concentration in precision voltage references and temperature-stabilized resistors sustains upstream calibration equipment demand. METI industrial technology roadmaps and JIS standards guide metrology infrastructure investment in automotive and electronics sectors. Nagoya automotive manufacturing zone and Osaka precision instrument district anchor domestic calibration service networks.
India
Process industry automation and pharmaceutical export manufacturing create calibration equipment procurement growth. CDSCO pharmaceutical manufacturing regulations and BIS national standards drive laboratory accreditation upgrades in contract research organizations. Gujarat chemical manufacturing corridor and Maharashtra pharmaceutical clusters expand ISO 17025-compliant calibration capacity.
Current Calibrator Market Competitive Environment
German precision engineering specialists anchor one tier; Japanese and North American electronics conglomerates hold adjacent positions through diversified instrumentation portfolios. Market structure concentrates around integrated automation suppliers with captive calibration offerings and standalone metrology specialists with service-dependent revenue models. Three archetypes dominate: multifunction platform vendors absorbing discrete instrument categories, process industry integration specialists, and subscription-based traceability service providers. Competitive moves center on wireless architecture development and after-sales service unbundling to capture recurring accreditation management contracts.
Within the integrated automation tier, Yokogawa Electric Corporation exemplifies process industry positioning alongside distributed control system offerings. Fluke Corporation and Keysight Technologies, Inc. occupy distinct specialization vectors—field-service network density versus telecommunications laboratory standards development. These three entities represent contrasting strategic postures: utility fleet aftermarket consolidation, RF and microwave calibration R&D intensity, and continuous loop calibration integration in oil and gas environments.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies, Inc. |
| Yokogawa Electric Corporation |
| WIKA Alexander Wiegand SE & Co. KG |
| Beamex Oy Ab |
| Time Electronics Ltd. |
| Tektronix, Inc. |
| Transmille Ltd. |
| AMETEK Calibration Instruments |
| Others |
Value Chain & Pricing Dynamics
Captive backward integration into precision voltage reference manufacturing anchors both supply security and pricing power for Japanese and German component specialists serving IEC 17025-accredited calibration equipment producers. This integration choice insulates tier-one vendors from input cost volatility while compressing margins for distributors dependent on merchant component sourcing.
Pricing Analysis
Distributor margins of 15-25% separate OEM-direct contract pricing from end-user list prices in the bench-mounted instrument channel. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 certification grade and NIST-traceable documentation depth. Pricing pressure stems from Chinese manufacturers rebalancing capacity toward export markets with aggressive landed-cost positioning. Pharmaceutical laboratories exhibit lowest price sensitivity due to FDA 21 CFR Part 11 validation protocol requirements, while brownfield manufacturing plants in process industries drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive OEM supplier networks and US utility fleet consolidators, bypassing traditional industrial distribution. Geographic concentration centers on Japan for precision voltage references and temperature-stabilized resistors, Germany for precision engineering clusters, and China for bench-mounted module assembly. Raw material dependencies include specialty metal foil resistors, hermetic sealing ceramics, and low-noise semiconductor substrates. Single-source vulnerability in Japanese precision component supply creates structural risk for calibration equipment lead times. Distribution runs through specialized metrology service firms offering subscription-based accreditation management alongside traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Current Calibrator Market represents a late-cycle quality story as automotive electrification and pharmaceutical manufacturing expansion shift procurement toward premium smart calibration systems with embedded diagnostics and automated compliance documentation.
For Market Incumbents: To counter wireless calibration architecture disruption from emerging platform vendors, Fluke Corporation and Keysight Technologies must deepen captive supply control over precision voltage reference production and accelerate R&D intensity in RF and microwave standards. Channel control through direct utility fleet aftermarket contracts offers defensive positioning against service unbundling trends fragmenting traditional purchasing patterns. For New Entrants and Emerging Players: FDA 21 CFR Part 11 compliance mandates in North American pharmaceutical manufacturing open a window for specialized validation protocol automation vendors to capture white-space in smart calibration systems. Wireless calibration architectures for distributed utility fleets represent the most penetrable segment given incumbent bench-mounted installation legacy. A subscription-based traceability service model targeting third-party calibration independence offers the clearest go-to-market angle against hardware-centric incumbents. For Investors and Strategic Acquirers: Roll-up economics work for specialized metrology service firms because after-sales service unbundling fragments traditional purchasing patterns and creates recurring accreditation management revenue pools. The five-to-ten year viability window favors platform-rollup strategies targeting regional calibration service providers with ISO 17025 laboratory infrastructure. Acquisition target archetype: mid-cap specialists with captive EPA compliance expertise in utility stack applications. The signal to watch is consolidation velocity among North American industrial distributors losing attach revenue to subscription-based service models.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Calibration Architecture Development | Enables remote verification for distributed German utility fleets without bench-mounted installation constraints. |
| Backward Integration into Precision Components | Secures captive supply of Japanese-sourced voltage references against input cost volatility. |
| Subscription-Based Accreditation Management | Captures recurring revenue from pharmaceutical laboratories seeking FDA 21 CFR Part 11 compliance automation. |
| Smart Calibration System Launch | Absorbs predictive maintenance demand from automotive electrification validation labs in Stuttgart manufacturing corridor. |
| Geographic Expansion into Process Industry Clusters | Attaches multifunctional calibrator sales to Yokogawa-class distributed control system deployments in oil and gas. |
Study Parameters
Multiple input streams — structured interviews with calibration laboratory managers and metrology service firm executives, trade data reconciliation, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork engaged plant engineers at German automotive OEM supplier networks, utility fleet maintenance directors in the United States, and pharmaceutical manufacturing quality leads. Secondary validation drew from IEC standards documentation, EPA emissions monitoring rulemakings, FDA 21 CFR Part 11 guidance publications, and customs records for precision instrument trade flows. Bottom-up equipment unit analysis and top-down industry spend estimates were cross-referenced for triangulation.
Data-stream reconciliation across product type, technology tier, end-user vertical, and installation format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle compression analysis in digital calibration protocols and expansion rate modeling for smart calibration system adoption. Industry-specific forecast inputs included German KBA vehicle certification timeline acceleration and US pharmaceutical manufacturing capacity buildout trajectories.
Revisions become necessary when IEC 17025 accreditation timeline shifts, precision component supply disruptions, or wireless calibration standardization breakthroughs materialize. Forecasts reflect documented assumptions about replacement cycle velocity and regulatory compliance automation adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Barometer Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
DCT Mechatronic Control Unit Market