
 North America Membrane Water Treatment Chemicals Market | 2026-2036
North America Membrane Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Membrane Water Treatment Chemicals Market Analytics
Buyer concentration among municipal water utilities and large industrial operators is hardening across the United States and Canada. Solenis leverages its specialty chemical portfolio to serve power generation and pulp-and-paper membrane systems. Ecolab sustains broad geographic coverage through integrated water management services and on-site technical support.
Membrane water treatment chemicals encompass antiscalants, biocides, cleaners, and pH adjusters formulated to protect polyamide and cellulose acetate membranes from fouling, scaling, and oxidative degradation while maintaining flux rates and salt rejection. These formulations prevent irreversible membrane damage in reverse osmosis, nanofiltration, and ultrafiltration systems used for producing potable water and process-grade effluent. Antiscalants command the largest share of product-type value pools due to the prevalence of calcium carbonate and sulfate scaling in high-recovery RO plants. Industrial water treatment generates the fastest application growth as semiconductor fabrication, data center cooling, and chemical manufacturing expand zero-liquid-discharge requirements.
EPA Safe Drinking Water Act amendments and state-level recycled water regulations in California and Texas mandate membrane integrity and compatible chemical formulations. OSHA process safety standards and NSF/ANSI 60 certification requirements shape product development timelines and market access barriers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions and their interaction with fluorinated membrane chemistries.
Market Dynamics
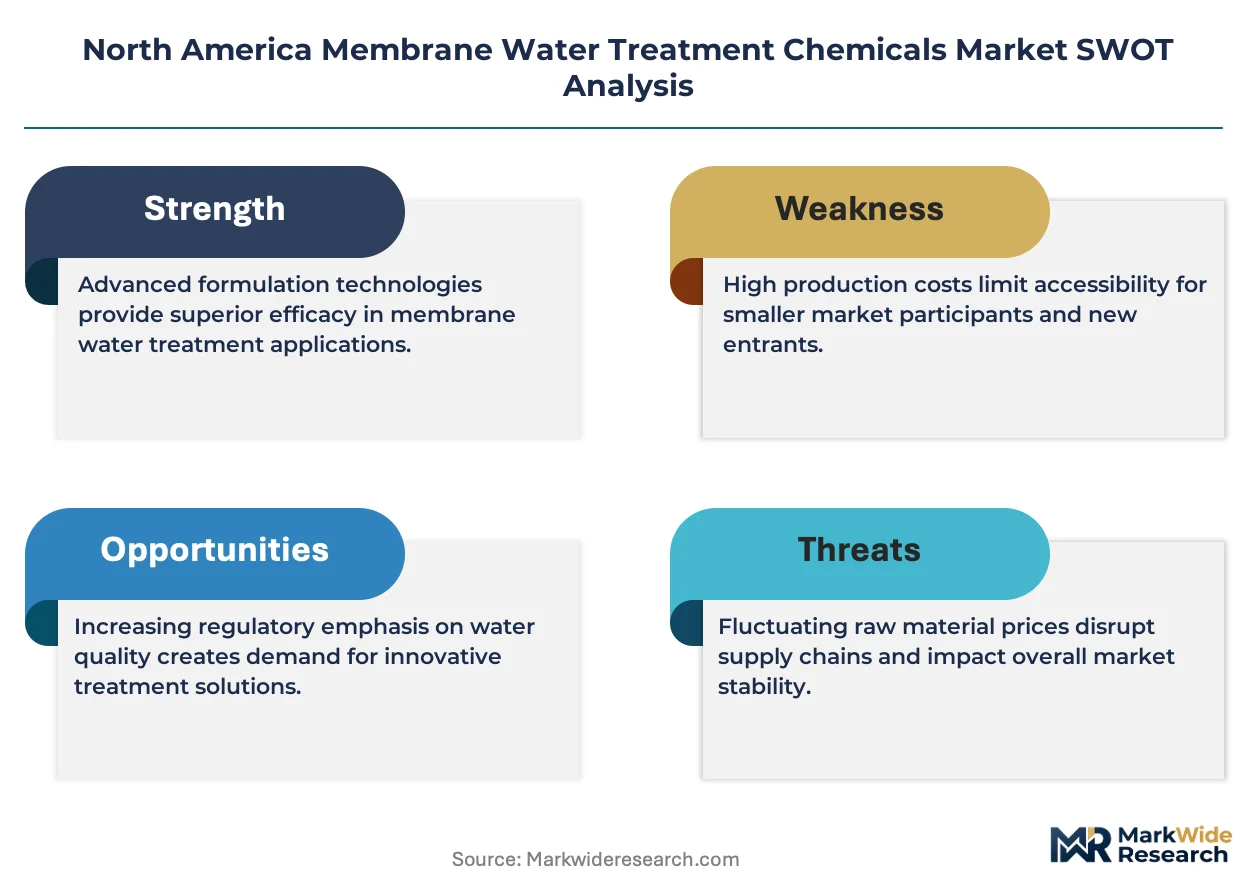
Membrane water treatment chemical suppliers face intensifying pressure from EPA discharge standards and state-level water reuse mandates that tighten formulation compatibility requirements while utilities consolidate procurement around fewer integrated service providers.
Growth Catalysts
- Texas Senate Bill 3:State-level water reuse mandates in drought-prone regions are accelerating membrane-based filtration retrofits across municipal utilities.
- Semiconductor fabrication:Zero-liquid-discharge requirements from fabs in Arizona and New York are expanding demand for high-performance antiscalant chemistries.
- Polyamide membrane degradation:Chloramine tolerance improvements in new membrane chemistries are extending replacement cycles and driving compatible cleaner formulations.
Market Restraints
- Phosphonate supply concentration:Antiscalant raw material production clusters in the US Gulf Coast, exposing formulators to hurricane-related disruption risk.
- PFAS regulatory friction:EPA restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fluorinated membrane maintenance chemistries.
- Caustic soda price volatility:pH adjuster input costs swing with energy-intensive chlor-alkali plant economics.
Strategic Opportunities
- Great Lakes corridor industrial clustering:Chemical manufacturing and automotive paint pretreatment operations in Michigan and Ohio present underpenetrated membrane chemical demand.
- Data center cooling expansion:Hyperscale facility construction in Virginia and Illinois is creating new ultrapure water treatment chemical requirements.
- California Title 22 compliance:Recycled water regulations are mandating membrane integrity monitoring systems that bundle chemical supply with sensor maintenance contracts.
Industry Challenges
- NSF/ANSI 60 certification timelines:Potable water chemical approvals stretch 18-24 months, compressing product launch windows.
- Membrane autopsy technician scarcity:Fouling diagnosis expertise concentrates among veteran specialists at OEM service divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Membrane Water Treatment Chemicals Market |
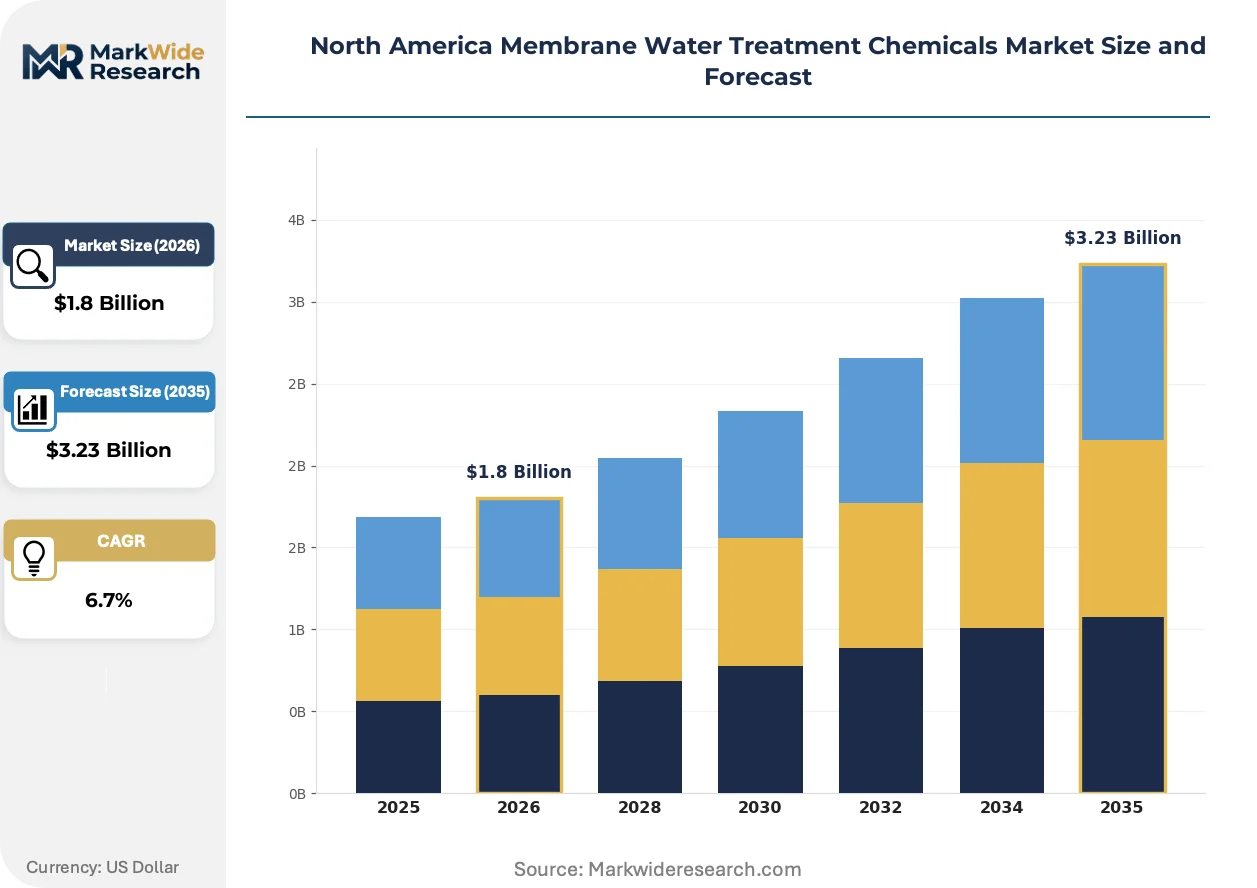
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Antiscalants, pH Adjusters Application: Industrial Water Treatment, Municipal Water Treatment, Desalination, Recycling End User: Power Generation, Oil & Gas, Chemical Manufacturing, Food & Beverage Delivery Mode: Liquid Form, Powder Form, Granular Form, Concentrated Solutions |
| Companies Covered | Solenis, Ecolab, Kemira, Suez, Veolia, American Water Chemicals, Inc., Danaher (ChemTreat Inc.), Dow, Kurita Water Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Membrane Water Treatment Chemicals Market Evolving Landscape
Chemical formulation strategies are pivoting toward membrane-specific compatibility testing as polyamide chemistries diversify and utilities demand longer warranty protection from suppliers.
Biodegradable antiscalant polymers are absorbing market share from traditional phosphonate chemistries as municipal utilities face nutrient discharge limits. Data center operators in Texas and Arizona are adopting these formulations fastest to align with corporate sustainability commitments. The shift is compressing pricing premiums for conventional high-performance antiscalants.
EPA's proposed PFAS drinking water standards are forcing membrane chemical suppliers to eliminate fluorinated surfactants from cleaner formulations. Industrial RO operators in California and Texas are pre-emptively switching to compliant alternatives ahead of enforcement deadlines. The transition is lengthening qualification cycles for new chemical suppliers.
Integrated chemical-feed automation is displacing manual dosing regimes across large municipal utilities. Solenoid-driven precision injection systems bundled with cloud-based performance monitoring are replacing periodic technician visits. The model is concentrating fastest in Florida and Arizona where labor costs and membrane replacement penalties are highest.
North America Membrane Water Treatment Chemicals Market Segmentation
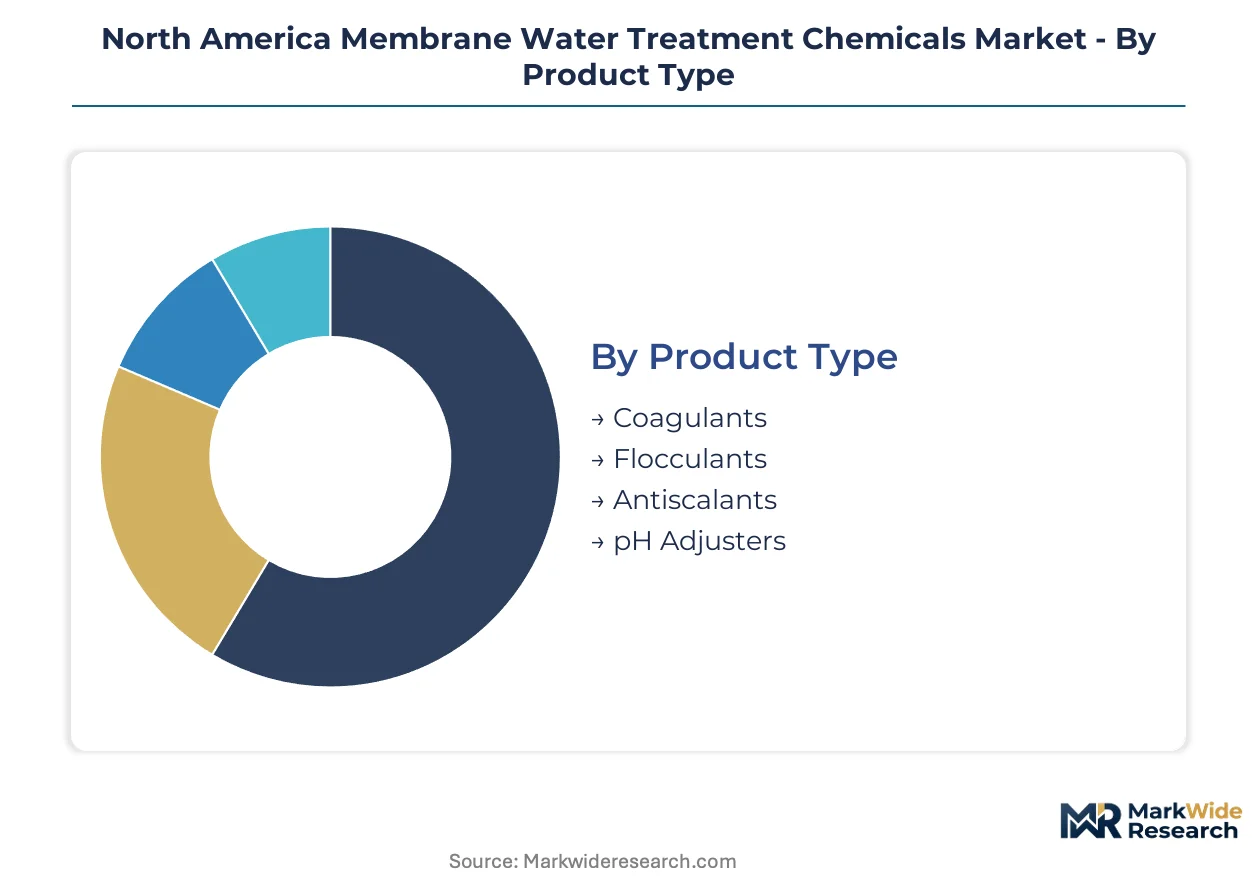
Membrane water treatment chemical purchasing decisions pivot on membrane compatibility, fouling chemistry, and regulatory compliance requirements that vary sharply across end-use environments. Suppliers configure formulation portfolios around replacement-cycle economics and feed-system integration rather than standalone product specifications.
Product Type:
Upgrade cycles for antiscalant chemistries are shortening as high-recovery RO plants push recovery rates past 85%, accelerating demand for next-generation polymer formulations.
- Antiscalants:Phosphonate and polymer-based formulations inhibit calcium carbonate, sulfate, and silica precipitation on polyamide membrane surfaces. Demand concentrates in Texas municipal utilities operating high-recovery brackish water RO, where scaling risk intensifies with drought-driven concentration factors.
- pH Adjusters:Sulfuric acid, caustic soda, and bicarbonate solutions maintain optimal membrane surface charge and solubility indices. Semiconductor fabs in Arizona and New York deploy precision pH control to protect ultrapure water membranes from hydrolytic degradation during extended production runs.
- Coagulants:Aluminum and iron-based pretreatment chemicals reduce colloidal fouling upstream of membrane arrays.
- Flocculants:Polyacrylamide polymers enhance solids removal in clarification stages preceding ultrafiltration.
Antiscalants sits at the top of the volume ranking, with pH adjusters climbing the fastest.
Application:
Cost tier differentiation separates commodity municipal specifications from premium industrial formulations commanding technical service bundling.
- Industrial Water Treatment:Zero-liquid-discharge systems in chemical manufacturing and data centers require customized antiscalant blends compatible with complex wastewater chemistries. Semiconductor fabrication in Arizona and New York drives the steepest expansion trajectory as fabs pursue closed-loop water recovery targets.
- Municipal Water Treatment:Brackish and surface water RO plants serving Texas and California communities prioritize NSF/ANSI 60 certified formulations with documented membrane warranty protection. Consolidated procurement by regional water authorities is compressing supplier margins while extending contract durations.
- Desalination:Seawater RO facilities on the California coast and Florida Gulf Coast demand high-performance antiscalants formulated for extreme salinity and boron rejection requirements.
- Recycling:Title 22 compliant indirect potable reuse plants in California mandate membrane integrity monitoring bundled with chemical supply agreements.
Industrial water treatment captures the premium pricing tier, while municipal contracts anchor baseline volume commitments.
End User:
Customer-type concentration patterns reflect water intensity, discharge permit stringency, and membrane asset criticality to core operations.
- Chemical Manufacturing:Petrochemical complexes along the Texas Gulf Coast and Great Lakes corridor operate extensive RO and nanofiltration trains for process water and wastewater polishing. These facilities generate recurring demand for high-dose antiscalant programs and automated chemical-feed systems.
- Power Generation:Combined-cycle gas turbine plants in Texas and Pennsylvania rely on membrane pretreatment for boiler feedwater makeup, driving seasonal demand spikes during summer peak generation periods.
- Oil & Gas:Produced water treatment for hydraulic fracturing reuse and disposal applications in the Permian Basin employs mobile RO units with rapid-deployment chemical dosing skids.
- Food & Beverage:Dairy processing and beverage bottling operations in Wisconsin and California deploy membrane filtration for product concentration and ingredient water purification.
Chemical manufacturing leads absolute consumption, with power generation expanding most quickly as merchant plants add membrane pretreatment capacity.
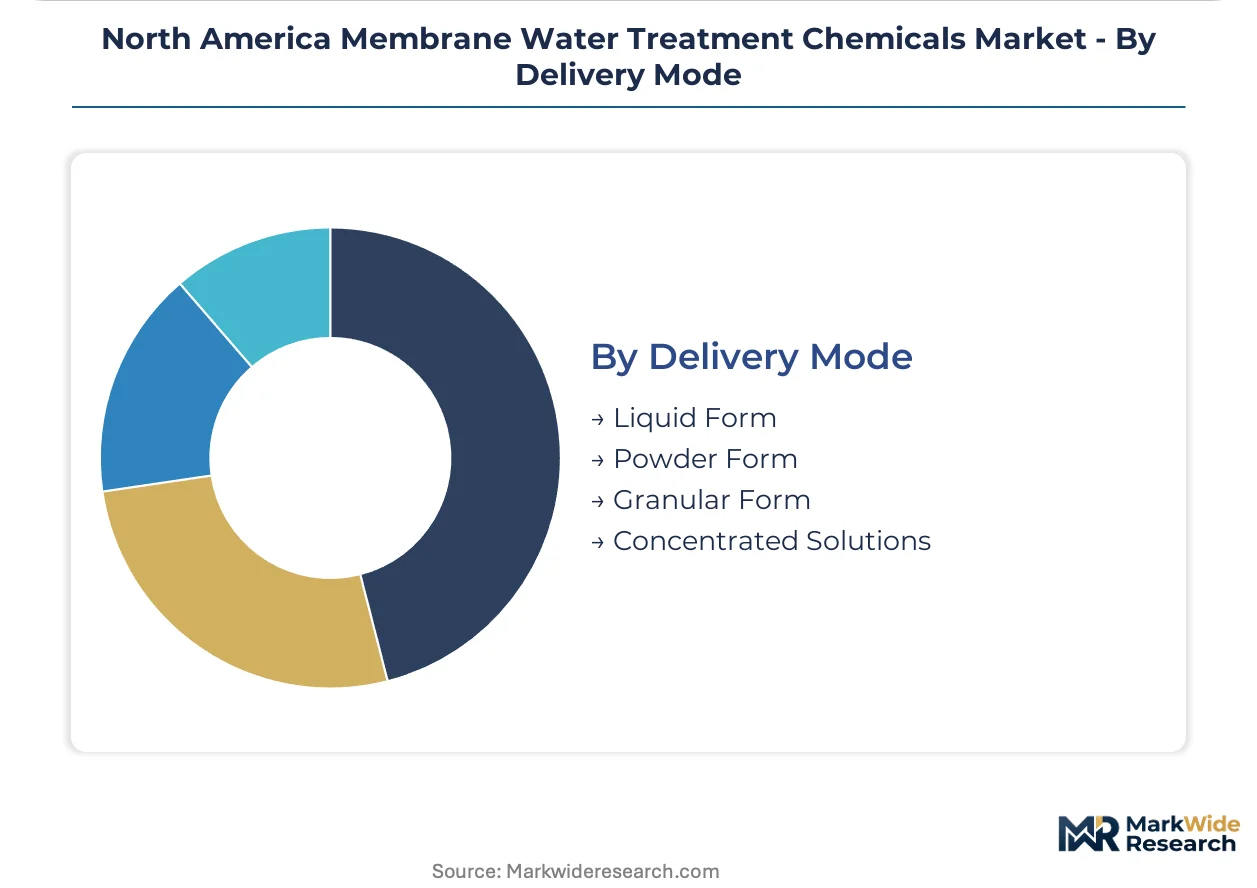
Delivery Mode:
Supply concentration in liquid bulk distribution networks shapes regional availability and logistics cost structures for formulators.
- Liquid Form:Ready-to-feed solutions dominate large municipal and industrial installations with automated dosing infrastructure. Tanker truck delivery from Gulf Coast blending plants minimizes handling costs for high-volume antiscalant and pH adjuster programs across Texas and Louisiana.
- Concentrated Solutions:Reduced-volume formulations lower freight costs for remote desalination sites and mobile treatment units. Mining operations in Nevada and Arizona favor concentrated antiscalants for on-site dilution at well-field RO installations.
- Powder Form:Dry polymer flocculants serve small municipal systems and temporary construction dewatering applications.
- Granular Form:Solid caustic and bicarbonate products target facilities lacking liquid chemical handling infrastructure.
Liquid form holds the volume leadership position, with concentrated solutions gaining share fastest in remote and decentralized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane water treatment chemical demand concentrates where water stress intersects with industrial clustering and specialized workforce pools. The North American market spans three national jurisdictions with distinct regulatory frameworks and infrastructure investment cycles.
United States
Texas Senate Bill 3 and California Title 22 regulations are accelerating membrane retrofits across municipal utilities. EPA Safe Drinking Water Act amendments mandate compatible chemical formulations for membrane integrity protection. Semiconductor fabrication clusters in Arizona and New York deploy zero-liquid-discharge systems requiring customized antiscalant programs.
Canada
Great Lakes corridor chemical manufacturing and automotive operations generate membrane chemical demand for process water recycling. Health Canada and PMRA standards govern potable water chemical approvals with NSF/ANSI 60 certification requirements. Ontario petrochemical complexes and Alberta oil sands operations anchor industrial consumption volumes.
Mexico
Northern border states house maquiladora manufacturing with membrane pretreatment for high-purity process water. CONAGUA water reuse mandates and NOM-001 discharge standards tighten chemical performance specifications. Monterrey and Tijuana industrial parks are expanding reverse osmosis capacity for electronics assembly and automotive painting operations.
North America Membrane Water Treatment Chemicals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation development and service bundling. The vendor base organizes around three tiers: integrated water management providers, specialty chemical formulators, and regional distribution-focused suppliers. Consolidation pressures intensify as municipal procurement centralizes around fewer service providers with automated dosing capabilities. Dominant competitive moves include geographic expansion through distribution partnerships and backward integration into phosphonate polymer production.
Among integrated service providers, Solenis and Ecolab occupy positions exemplifying the bundled chemical-feed automation model. Kemira represents the specialty chemical formulator archetype with concentrated expertise in antiscalant polymer development. These three companies anchor the competitive structure through differentiated approaches to membrane compatibility testing and technical service deployment.
| Leading Market Players |
|---|
| Solenis |
| Ecolab |
| Kemira |
| Suez |
| Veolia |
| American Water Chemicals, Inc. |
| Danaher (ChemTreat Inc.) |
| Dow |
| Kurita Water Industries Ltd |
| Others |
Value Network & Pricing Analysis
California Title 22 recycled water mandates gate qualified supply access and premium-tier pricing power by requiring NSF/ANSI 60 certification bundles that only established formulators can deliver. Municipal utilities in Texas and California now consolidate procurement around fewer suppliers with automated dosing capabilities, compressing margins for unbundled commodity offerings while elevating integrated service premiums.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning across the North American membrane chemicals landscape. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 60 certified formulations with warranty protection from commodity antiscalants and basic pH adjusters. Cost compression in the standard tier is intensifying because biodegradable polymer antiscalants are absorbing share from phosphonate chemistries. Municipal water authorities exhibit the highest price sensitivity due to consolidated procurement and public budget constraints, while semiconductor fabs accept premium pricing for customized zero-liquid-discharge programs.
Supply Chain Analysis
NSF/ANSI 60 certification timelines stretching 18-24 months gate market entry and concentrate qualified supply among incumbent formulators with established regulatory dossiers. Phosphonate polymer production clusters in the United States Gulf Coast, with caustic soda sourcing tethered to energy-intensive chlor-alkali plant economics along the same corridor. Hurricane exposure along the Gulf Coast presents the dominant structural risk to antiscalant raw material availability. Distribution runs through liquid bulk tanker networks serving large municipal utilities, with concentrated solutions gaining share in remote mining and mobile treatment applications across Nevada and Arizona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Texas and California, where divergent drought severity and state-level reuse mandates create asymmetric chemical specification premiums and procurement consolidation rhythms.
For Market Incumbents: To counter phosphonate supply concentration risk, Solenis and Ecolab should secure captive supply of biodegradable antiscalant polymers through backward integration into Gulf Coast polymer production or long-term offtake agreements with specialty chemical manufacturers. Certification investment in NSF/ANSI 60 compliant fluorine-free cleaner formulations will preempt PFAS regulatory enforcement and extend warranty protection offerings. For New Entrants and Emerging Players: Cloud-based chemical-feed automation platforms offer the most penetrable wedge for displacing incumbent service contracts among midsize municipal utilities in Florida and Arizona where labor costs and membrane replacement penalties concentrate. Target the Great Lakes corridor chemical manufacturing sector with automated dosing skids bundled with remote monitoring subscriptions, leveraging underpenetrated membrane chemical demand in Michigan and Ohio automotive paint pretreatment operations. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution-focused suppliers lacking automated dosing capabilities and NSF/ANSI 60 certification breadth. The long-term viability framing favors acquisition of specialty antiscalant formulators with established membrane compatibility testing protocols and existing EPA regulatory dossiers. Watch for PFAS enforcement deadline acceleration as the signal indicating qualification cycle lengthening and incumbent pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphonate Polymers | Secures raw material supply against Gulf Coast hurricane disruption risk for antiscalant formulators. |
| NSF/ANSI 60 Certification Expansion | Opens California Title 22 compliance bundling opportunities with membrane integrity monitoring contracts. |
| Automated Chemical-Feed System Deployment | Replaces periodic technician visits with solenoid-driven precision injection across Florida municipal utilities. |
| Fluorine-Free Cleaner Formulation Launch | Preempts EPA PFAS drinking water standard enforcement in Texas and California industrial RO operations. |
| Great Lakes Distribution Partnership | Captures underpenetrated chemical manufacturing and automotive membrane chemical demand in Michigan and Ohio. |
Research Methodology
Bottom-up municipal and industrial consumption modeling reconciled against top-down phosphonate polymer production tracking forms the analytical core of this study. Primary interviews with membrane system OEM service directors, municipal water utility procurement managers, semiconductor fab facilities engineers, and specialty chemical plant managers were combined with secondary validation from EPA Safe Drinking Water Act filings, state-level water reuse mandate databases, SEC 10-K disclosures from diversified water treatment conglomerates, and customs trade data on phosphonate polymer imports. Triangulation between end-use demand signals and supply-side capacity announcements ensures cross-verified volume and value estimates.
The input-output matrix framing maps antiscalant, biocide, cleaner, and pH adjuster consumption against installed reverse osmosis, nanofiltration, and ultrafiltration capacity across municipal, industrial, desalination, and recycling applications. Segmentation dimensions include product chemistry type, membrane material compatibility, end-use water stress severity, and regional regulatory stringency tier. CAGRs were derived from regression analysis of historical membrane installation rates against chemical dose intensity coefficients, with forecast inputs incorporating Texas Senate Bill 3 implementation timelines and semiconductor fab zero-liquid-discharge target announcements across the analysis window.
The model holds under stable EPA enforcement timelines and phosphonate supply continuity; deviation in PFAS regulatory acceleration or Gulf Coast hurricane frequency would shift volume trajectories. A model refresh is warranted upon material change in California Title 22 compliance deadline adjustments or major phosphonate polymer production facility announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market