

Enzymes for Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Enzymes for Water Treatment Market Insights
Municipal wastewater operators are bifurcating from chemical-dependent utilities toward biologically integrated treatment plants. Novonesis leverages its fermentation scale to supply laccase blends for Nordic pulp mills. BASF anchors European industrial effluent contracts through captive enzyme supply chains. International Flavors & Fragrances competes in food & beverage pre-treatment with specialized amylase portfolios.
Enzymes for water treatment comprise protein-based biocatalysts—typically operating at 20–50°C and pH 6–9—that accelerate hydrolysis, oxidation, or polymerization of organic contaminants in aqueous systems. Their primary purpose is to degrade fats, starches, lignins, and phenolic compounds without generating chlorinated byproducts. Protease and cellulase formulations dominate municipal and paper & pulp effluent segments due to broad substrate compatibility and lower dosing costs. Laccase and xylanase represent faster-growing niches in textile dye degradation and lignin-heavy pulp streams where oxidative chemistry commands premium pricing.
EPA effluent limitation guidelines and EU Urban Wastewater Treatment Directive revisions are forcing U.S. and European facilities to reduce nitrogen and phosphorus discharge loads, directly expanding enzymatic denitrification deployments. REACH registration requirements for biocidal products constrain market entry for non-compliant enzyme suppliers in Europe. Stakeholders must monitor how China's MEE wastewater discharge standards and India's CPCB mandates reshape import demand for thermostable enzyme formulations.
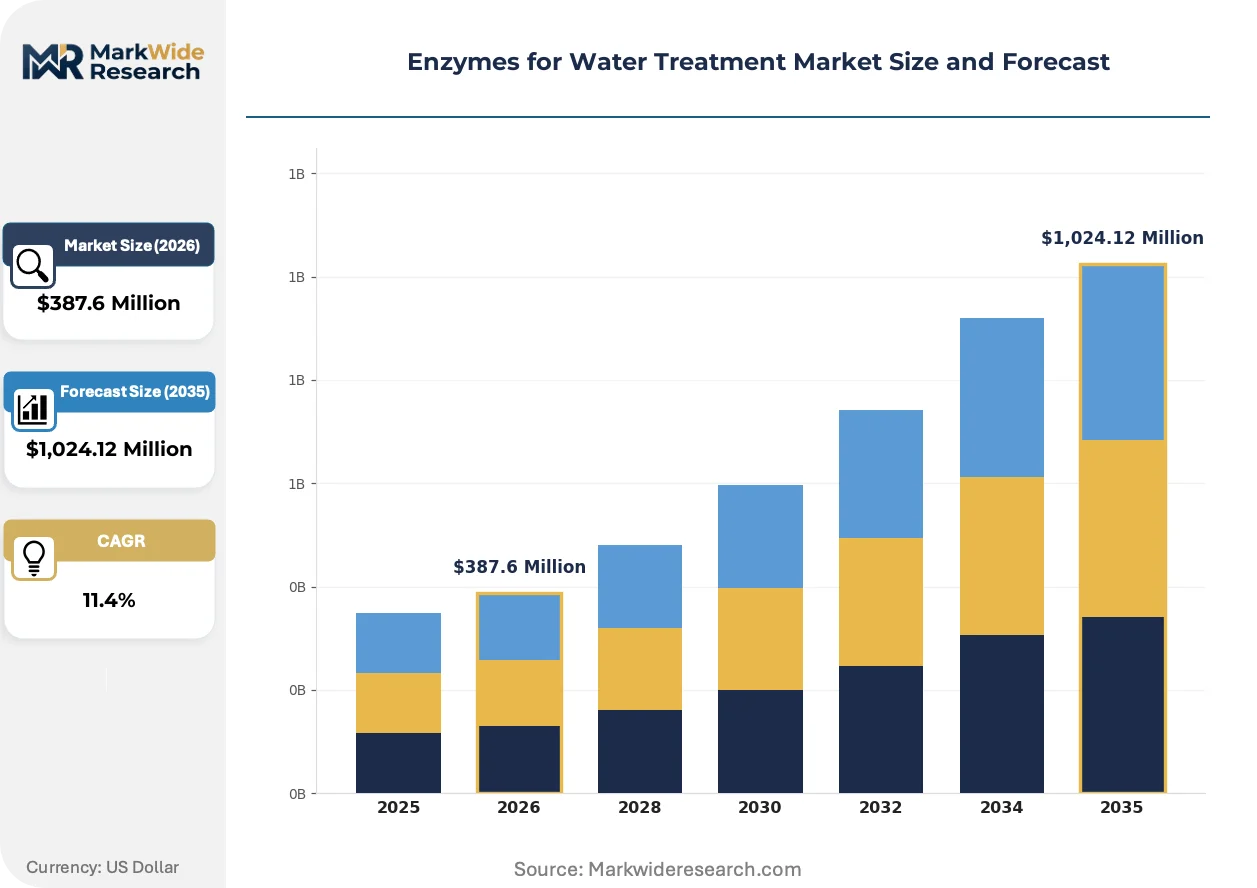
Market Dynamics
Municipal wastewater operators face structural pressure to replace chemical flocculants with enzymatic alternatives as nitrogen discharge limits tighten under EU and EPA frameworks. This shift forces capital reallocation toward biological treatment infrastructure and reskilling of plant operators.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revisions:German and Dutch facilities are expanding enzymatic denitrification capacity to meet stricter nitrogen and phosphorus discharge thresholds, directly expanding enzyme procurement volumes.
- Scandinavian pulp mill effluent streams:Cellulase and laccase formulations are capturing share from aluminum-based coagulants in Nordic bleached kraft operations seeking to eliminate chlorinated organic byproducts.
- Textile dye degradation demand:Laccase-based oxidative systems are penetrating synthetic dye wastewater in Turkey and Bangladesh as brands enforce zero-discharge commitments through supply chain audits.
Market Restraints
- Fermentation feedstock volatility:Corn steep liquor and molasses prices fluctuate with agricultural commodity cycles, compressing margin stability for bulk enzyme producers serving municipal utilities.
- REACH biocidal product registration:European enzyme suppliers face 18-24 month compliance timelines and six-figure dossier costs that exclude smaller fermentation houses from EU tender participation.
- Thermostable formulation gaps:Enzyme activity degradation above 50°C limits deployment in high-temperature industrial effluents where chemical oxidation retains cost advantages.
Strategic Opportunities
- India's CPCB mandate expansion:Central Pollution Control Board enforcement of Common Effluent Treatment Plant standards in Surat and Tiruppur textile clusters creates import demand for thermostable amylase and laccase blends.
- Membrane bioreactor convergence:Hybrid enzymatic-MBR systems are emerging in Singapore and Israel where land scarcity forces compact, high-throughput wastewater footprints.
- Direct-to-utility subscription models:Enzyme suppliers are piloting performance-based dosing contracts that replace upfront chemical procurement with per-cubic-meter-treated pricing in Australian and Canadian municipal markets.
Industry Challenges
- Process control skill gaps:Municipal plant operators trained in chemical dosing protocols require 6-12 month retraining to manage enzyme activity monitoring, pH buffering, and temperature optimization in biological treatment trains.
- Legacy SCADA integration friction:Enzyme dosing automation demands retrofit of analog-era wastewater facilities with IoT-enabled flow sensors and real-time biomass analytics, stretching capital deployment timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzymes for Water Treatment Market Trends and Innovations
Enzymatic water treatment is evolving from batch chemical replacement toward continuous biocatalytic systems integrated with smart monitoring infrastructure. Three convergent developments are restructuring competitive positioning and procurement patterns.
Immobilized laccase carrier systems are decomposing recalcitrant phenolic compounds in olive mill and winery effluents that resist conventional biological oxygen demand reduction. Spanish and Italian cooperatives are deploying fixed-bed enzyme reactors with 90-day operational cycles. This enzymatic decomposition is compressing detention times from 48 hours to 6 hours, enabling smaller footprint treatment plants in vineyard-dense regions.
EPA effluent limitation guidelines for nitrogen and phosphorus are mandating tertiary treatment upgrades across 16,000 U.S. municipal facilities by 2028. The industrial consequence is accelerated tendering for enzymatic denitrification modules that supplement or replace methanol-dependent anoxic zones. Facilities in Chesapeake Bay and Gulf of Mexico watersheds are prioritizing enzyme systems that eliminate external carbon source dependency and reduce sludge volumes.
Textile and food processors are consolidating vendor relationships from multi-chemical portfolios toward single-source enzyme suppliers offering application-specific formulation libraries. Turkish denim laundries and Bangladesh knit dye houses are negotiating annual framework agreements that bundle technical service with enzyme supply. This consolidation is most visible in export-oriented manufacturing zones where ZDHC MRSL compliance audits drive standardization of approved biocatalyst suppliers.
Enzymes for Water Treatment Market Segmentation
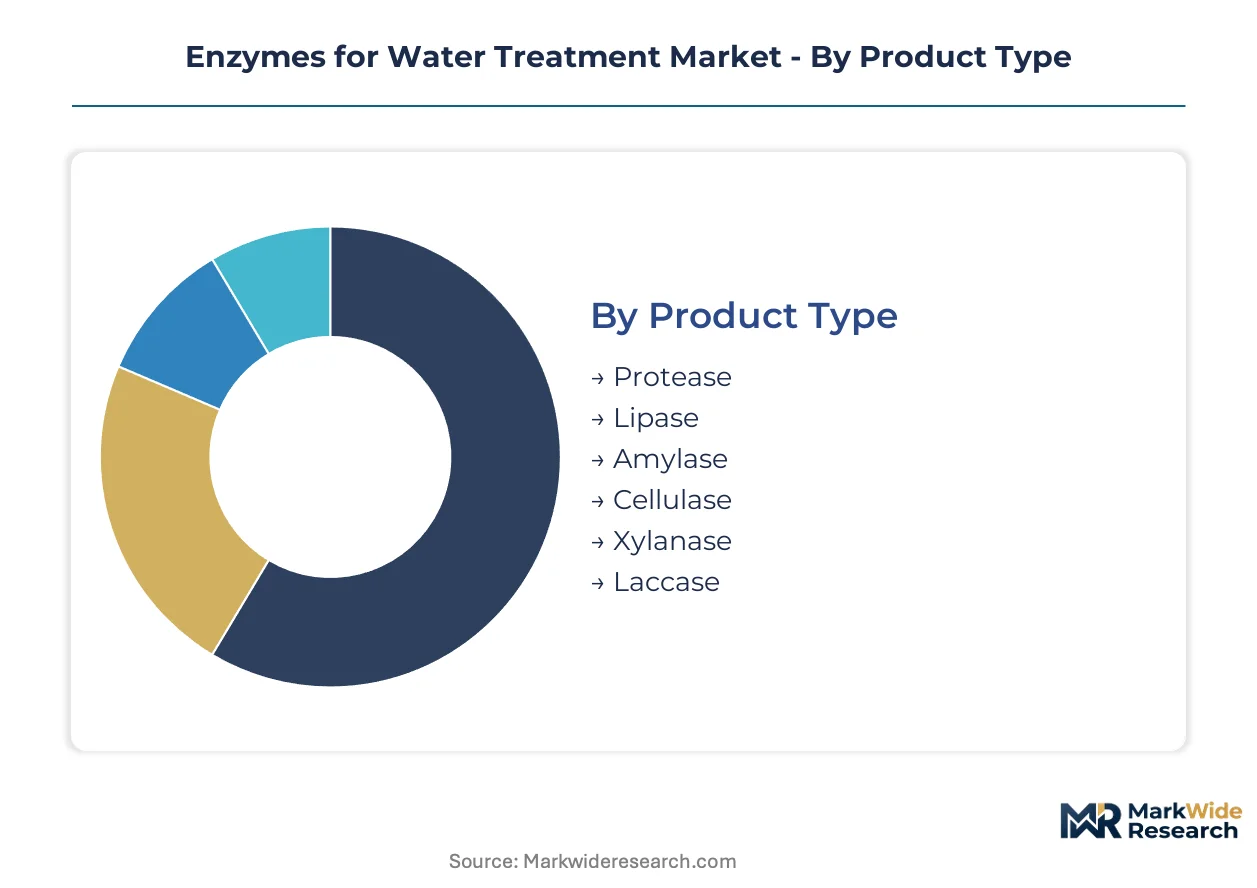
Enzyme suppliers structure their commercial portfolios around substrate specificity and treatment intensity. Segmentation reveals where formulation margins diverge from commodity chemical pricing and which deployment modes unlock recurring revenue streams.
Product Type:
Highest formulation premiums concentrate in oxidative enzymes where substrate complexity demands specialized production.
- Laccase:Multi-copper oxidase enzymes catalyze phenolic compound degradation through radical-mediated pathways. Nordic pulp mills in Finland and Sweden deploy laccase formulations to eliminate chlorinated organic byproducts from bleached kraft effluents, capturing value from EU Industrial Emissions Directive compliance deadlines.
- Cellulase:Endoglucanase-exoglucanase-beta-glucosidase complexes hydrolyze cellulose fibers in lignin-heavy streams. German and Dutch paper manufacturers are expanding procurement volumes as enzymatic alternatives displace aluminum-based coagulants under tightening phosphorus discharge thresholds.
- Protease:Serine and metalloprotease formulations target proteinaceous waste in municipal sewage streams.
- Lipase:Triacylglycerol hydrolases degrade fat and oil residues in food processing effluents.
- Amylase:Alpha- and glucoamylase variants break down starch polymers in beverage and textile pre-treatment.
- Xylanase:Hemicellulose-specific enzymes reduce chlorine demand in pulp bleaching sequences.
Laccase holds installed capacity in Nordic pulp corridors. Cellulase is rotating up the share rankings as European paper mills accelerate chemical substitution programs.
Application:
Revenue concentration tracks regulatory enforcement intensity rather than effluent volume alone.
- Wastewater Treatment:Municipal biological nutrient removal trains deploy nitrifying and denitrifying enzyme consortia. U.S. facilities in Chesapeake Bay watersheds are procuring enzymatic denitrification modules to meet EPA total maximum daily load mandates without methanol dependency.
- Industrial Effluent Management:Factory-scale pre-treatment systems integrate hydrolase blends for high-COD streams. Turkish textile clusters in Bursa and Denizli are installing laccase-based dye degradation units ahead of ZDHC MRSL supply chain audit cycles.
- Drinking Water Purification:Enzymatic biofilm control in distribution networks.
- Sewage Treatment:Primary and secondary biological process enhancement.
- Aquaculture Systems:Pond water quality management through organic waste digestion.
- Soil Remediation:Ex-situ enzymatic degradation of hydrocarbon contaminants.
Wastewater treatment commands the deepest retrofit budgets. Industrial effluent management is expanding most quickly as manufacturing compliance costs outpace municipal rate structures.
End User Industry:
Procurement sophistication varies sharply between regulated utilities and cost-optimized manufacturers.
- Paper & Pulp Mills:Kraft and mechanical pulping operations consume cellulase-laccase blends for effluent decolorization and chlorine reduction. Swedish and Finnish integrated mills are consolidating supplier relationships around single-source enzyme portfolios with embedded technical service.
- Municipal Facilities:Publicly operated wastewater plants face capital constraints and operator retraining requirements. German utilities are piloting performance-based enzyme dosing contracts that replace upfront chemical procurement with per-cubic-meter-treated pricing.
- Food & Beverage Plants:Dairy, brewing, and processing facilities deploy amylase-lipase combinations.
- Chemical Manufacturers:Petrochemical and specialty chemical effluent pre-treatment.
- Textile Processors:Dye house effluent decolorization and desizing operations.
- Mining Operations:Acid mine drainage and process water treatment.
Paper and pulp mills anchor formulation R&D investment. Municipal facilities are climbing the procurement sophistication curve as biological treatment expertise deepens.
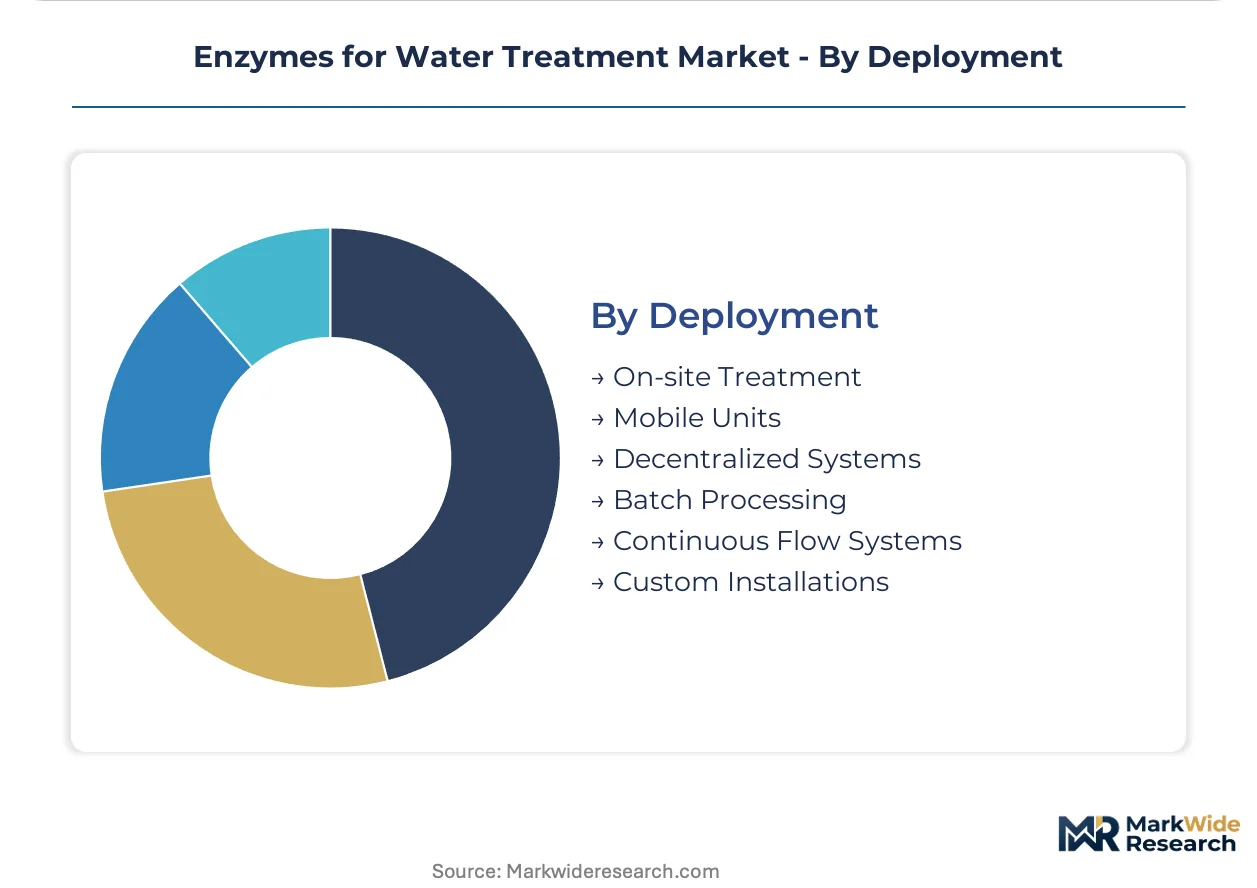
Deployment:
Capital deployment patterns separate recurring revenue opportunities from one-time equipment sales.
- Continuous Flow Systems:Immobilized enzyme reactors with real-time dosing control enable 24-hour operation in high-throughput facilities. Singapore's PUB and Israeli utilities are converging enzymatic stages with membrane bioreactors to compress land footprints in dense urban environments.
- On-site Treatment:Fixed infrastructure at point-source discharge locations.
- Mobile Units:Containerized treatment for temporary or remote operations.
- Decentralized Systems:Cluster-scale treatment for industrial parks or rural communities.
- Batch Processing:Cyclical enzymatic treatment for variable-load effluents.
- Custom Installations:Engineered solutions for non-standard waste profiles.
Continuous flow systems hold technology leadership. Decentralized systems are gaining traction fastest where centralized infrastructure investment lags industrial clustering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in Denmark and the Netherlands supply enzymatic formulations across three continents. Procurement patterns diverge sharply between EU utilities facing REACH compliance deadlines and Asian textile hubs racing ZDHC audit cycles.
Germany
Municipal wastewater operators in North Rhine-Westphalia are retrofitting biological nutrient removal trains with enzymatic denitrification modules. EPA-aligned EU Urban Wastewater Treatment Directive revisions mandate nitrogen discharge reductions by 2027. The Rhine-Ruhr industrial corridor hosts pilot performance-based enzyme dosing contracts that replace upfront chemical procurement.
United States
Chesapeake Bay watershed facilities are procuring enzymatic alternatives to methanol-dependent anoxic zones under EPA total maximum daily load mandates. The agency's effluent limitation guidelines force tertiary treatment upgrades across 16,000 municipal plants by 2028. Gulf Coast petrochemical clusters are trialing thermostable cellulase blends for high-temperature effluent pre-treatment.
India
Textile processors in Surat and Tiruppur face Central Pollution Control Board enforcement of Common Effluent Treatment Plant standards. The MEE wastewater discharge standards reshape import demand for thermostable amylase and laccase formulations. Gujarat's chemical manufacturing belt is consolidating around single-source enzyme suppliers offering bundled technical service.
China
Pulp mills in Shandong and Jiangsu provinces are expanding enzymatic bleaching sequences to meet dual carbon goals and MEE discharge standards. The country's national environmental regulator tightens COD and AOX limits on paper effluents. Yangtze River Delta industrial parks are deploying hybrid enzymatic-membrane bioreactor systems to compress land footprints.
Turkey
Denim laundries in Bursa and Denizli are installing laccase-based dye degradation units ahead of ZDHC MRSL supply chain audit cycles. The country's textile export competitiveness hinges on zero-discharge commitments enforced by EU brand procurement rules. Aegean region knit dye houses are negotiating annual framework agreements that bundle enzyme supply with compliance documentation.
Enzymes for Water Treatment Market Competitive Landscape
Concentration sits with diversified fermentation houses and specialized enzyme suppliers serving distinct end-use verticals. The market structure reflects tiered capabilities: global biocatalyst platforms compete against regional formulation specialists and application-focused technical service providers. Two strategic archetypes dominate—vertically integrated fermentation-scale suppliers and downstream formulation blenders with embedded technical support. Competitive moves center on performance-based contracting pilots and captive supply chain integration to secure municipal utility tender participation.
Among Denmark-based biocatalyst platforms, Novonesis anchors the fermentation-scale tier with laccase supply relationships across Nordic pulp corridors. BASF exemplifies the chemicals conglomerate archetype, anchoring European industrial effluent contracts through integrated enzyme supply chains. International Flavors & Fragrances occupies a position within the specialized application tier, competing in food and beverage pre-treatment segments with dedicated amylase portfolios.
| Leading Market Players |
|---|
| Novonesis |
| International Flavors & Fragrances |
| DSM-Firmenich |
| BASF |
| Amano Enzyme |
| Advanced Enzyme Technologies |
| AB Enzymes |
| Kerry Group |
| Thermax |
| Others |
Pricing and Supply Chain Analysis
Ninety-day fermentation batch cycles and six-month REACH dossier preparation timelines concentrate pricing power with Danish and Dutch fermentation houses serving EU municipal utilities. Inventory buffers for corn steep liquor and molasses feedstocks fluctuate with agricultural commodity indices, compressing margin stability for bulk enzyme suppliers while specialized laccase formulations retain formulation premiums.
Pricing Analysis
EU REACH biocidal product registration dictates the pricing tier structure across the European market. Three-tier pricing structure across premium, standard, and economy levels separates thermostable oxidative enzymes from commodity hydrolase blends, with certification-grade formulations commanding sustained premiums. Cost compression in standard-grade cellulase is intensifying because corn steep liquor prices track volatile agricultural cycles. Municipal wastewater operators exhibit highest price sensitivity due to capital constraint structures, while Nordic pulp mills demonstrate lowest sensitivity given chlorinated byproduct elimination mandates.
Supply Chain Analysis
Fermentation capacity chokepoints in Denmark and the Netherlands underwrite supply security for laccase and cellulase formulations serving European industrial clients. Production gravity centers on Copenhagen-Rotterdam corridor facilities with downstream blending operations in Germany and Sweden. Corn steep liquor, molasses, and specialized copper salts for laccase production constitute critical raw material dependencies. Single-source vulnerability concentrates in thermostable strain development capabilities held by select biocatalyst platforms. Distribution runs through technical service-embedded direct contracts rather than commodity chemical spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through REACH dossier requirements and 18-24 month compliance timelines creates defensive moats for established fermentation houses. Switching costs escalate as municipal operators retrain biological process control expertise.
For Market Incumbents: Compound formulation libraries with embedded technical service to deepen municipal utility relationships. Expand thermostable strain R&D to capture high-temperature industrial effluent segments where chemical oxidation currently retains cost advantages. Defend against emerging biotech platforms through backward integration into proprietary strain development capabilities.
For New Entrants and Emerging Players: Technical service gaps in Indian textile clusters present white-space opportunities where incumbent coverage remains thin. Target Surat and Tiruppur Common Effluent Treatment Plants with thermostable amylase-laccase blends bundled with compliance documentation services. Penetrate through performance-based dosing contracts that replace upfront chemical procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize non-core enzyme divisions. Long-term viability hinges on regulatory compliance infrastructure and fermentation scale rather than formulation differentiation alone. Watch for Central Pollution Control Board enforcement intensity in Indian textile corridors as inflection indicator for import demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Pilots | Per-cubic-meter pricing models align supplier incentives with municipal effluent quality outcomes. |
| Thermostable Strain Development | High-temperature activity unlocks petrochemical and mining effluent segments currently closed to enzymatic treatment. |
| Hybrid MBR-Enzyme System Integration | Singapore PUB deployments demonstrate land-scarce urban markets favor compact continuous-flow configurations. |
| REACH Dossier Completion | Biocidal product registration secures tender participation access across EU municipal procurement cycles. |
| Technical Service Bundling | Turkish denim laundries consolidate vendor relationships around single-source suppliers with embedded compliance support. |
Research Methodology
Cross-validation between primary interviews with municipal plant operators, pulp mill technical directors, and enzyme procurement managers and secondary validation through ECHA registration databases, EPA effluent guideline filings, and EU Industrial Emissions Directive compliance records anchors the qualitative findings. Customs trade data for fermentation equipment imports and SEC filings from diversified chemical conglomerates supplement demand-side triangulation. Bottom-up segmentation modeling and top-down macroeconomic calibration converge on volume estimates.
Sensitivity analysis across regulatory enforcement intensity scenarios and feedstock price volatility bands shapes the projection framework. Segmentation dimensions span enzyme class, application intensity, deployment mode, and end-user industry vertical. CAGRs derive from historical procurement pattern analysis and policy mandate timeline alignment. Industry-specific inputs include REACH registration completion rates and ZDHC MRSL audit cycle frequencies.
Forecasts assume regulatory continuity in EU REACH and EPA effluent limitation regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as China's MEE discharge standard revisions and India's CPCB enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.