
 Global Naphthalene Water Reducers Market | 2026-2036
Global Naphthalene Water Reducers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Naphthalene Water Reducers Market Foresight
Specialized chemical engineering talent is reorganizing competitive dynamics across the naphthalene water reducers sector, with regional shortages in process optimization expertise limiting expansion at mid-scale facilities. Himadri Specialty Chemical Ltd. anchors its position through backward integration into coal-tar distillation, securing captive feedstock for sulfonated naphthalene output. BASF SE leverages its global R&D network to sustain technology leadership in modified naphthalene formulations for high-strength concrete. Rain Carbon dominates carbon feedstock supply to third-party admixture producers across North America and Europe.
Naphthalene water reducers are sulfonated condensation products that lower water-to-cement ratios while maintaining workability, typically achieving 15-25% water reduction in standard concrete mixes; manufacturers produce them through controlled sulfonation of naphthalene followed by formaldehyde polymerization to target specific molecular weight distributions for slump retention. Sulfonated naphthalene retains the largest volume share among product types due to its cost-performance balance in emerging markets, while polycarboxylate formulations capture premium pricing in precast concrete applications requiring extended slump life. Ready-mix concrete commands the dominant application channel, though shotcrete segments are gaining traction in tunneling and mining projects across mountainous terrain.
REACH registration requirements in Europe and GB standards enforcement under China's SAMR are elevating barrier-to-entry for unverified suppliers while redirecting procurement toward certified producers. The EPA's industrial chemical oversight in the United States adds compliance layering for imported sulfonated naphthalene entering concrete supply chains. Stakeholders must monitor regulatory divergence between jurisdictions, as misaligned purity standards threaten to fragment formulation portfolios and inflate qualification costs for multi-region operators.
Market Dynamics
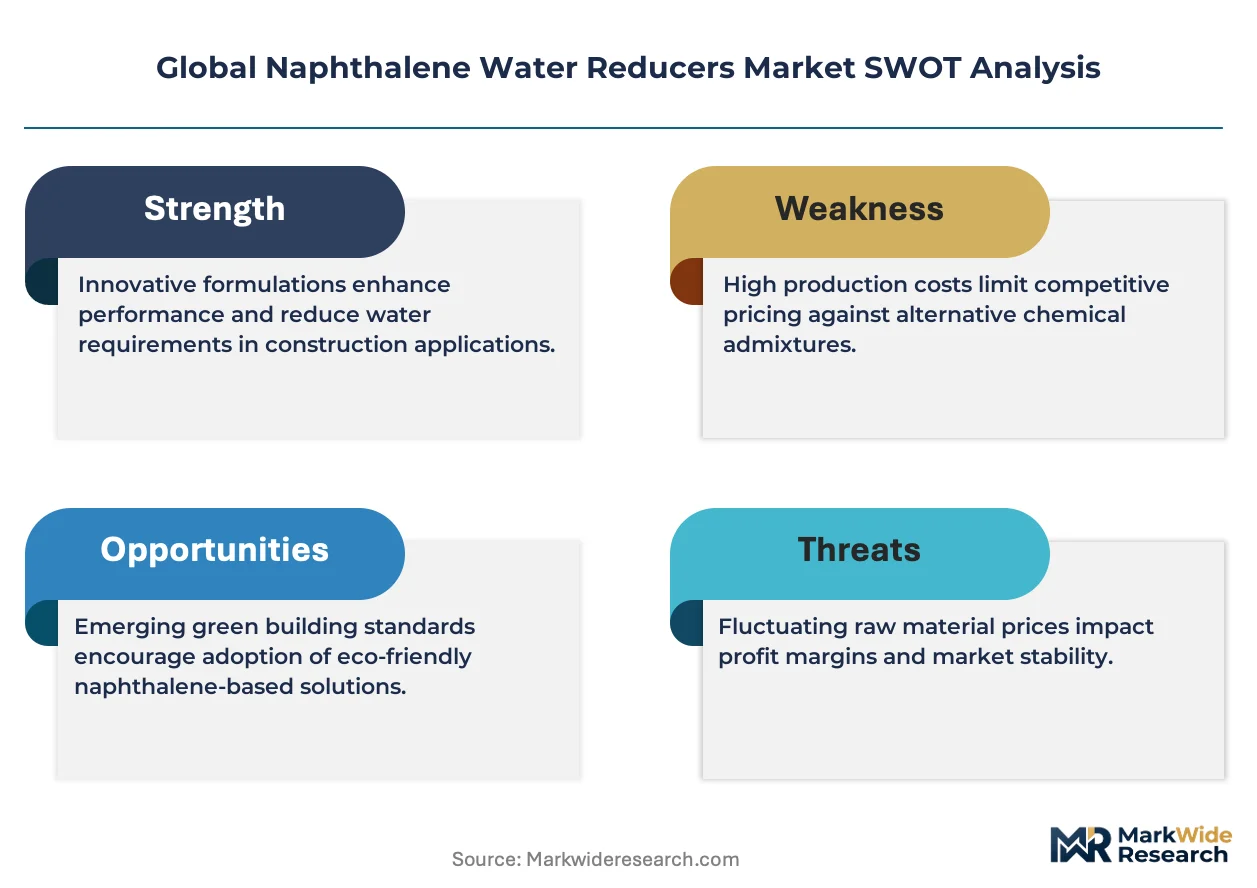
REACH compliance deadlines in Europe and tightening GB standards under China's SAMR are forcing simultaneous reformulation across multiple product lines, compressing margins for non-integrated producers while advantaging suppliers with captive sulfonation capacity.
Growth Catalysts
- India PLI scheme for construction chemicals:Domestic blending capacity is expanding as fiscal incentives draw fresh investment into sulfonated naphthalene production for infrastructure projects.
- High-strength concrete specifications:Modified naphthalene formulations are capturing specification upgrades in precast and ready-mix segments where slump retention requirements exceed conventional admixture performance.
- Urbanization corridors in Southeast Asia:Metro rail and highway projects in Vietnam, Indonesia, and the Philippines are concentrating demand for performance-grade water reducers in dense procurement clusters.
Market Restraints
- Coal-tar naphthalene feedstock concentration:Carbon distillation capacity concentrates among a limited set of integrated refiners, exposing third-party admixture producers to input cost volatility and allocation risk.
- Polycarboxylate ether substitution in premium segments:Extended slump-life requirements in self-consolidating concrete are displacing naphthalene-based products from high-margin specification tiers.
- REACH registration cost layering:ECHA compliance requirements for sulfonated naphthalene polymers are elevating fixed costs for EU market access, filtering smaller exporters from the supply base.
Strategic Opportunities
- Mining and tunneling shotcrete applications:Accelerated excavation projects in Peru, Chile, and Turkey are opening specification windows for rapid-setting naphthalene formulations with controlled viscosity profiles.
- CE marking harmonization:Converging EU construction product regulations are creating pan-European qualification pathways that reduce per-country certification overhead for certified producers.
- Digital dosing and IoT-enabled batching:Integration of real-time rheology sensors with automated admixture injection is enabling performance-based service models that lock in multi-year supply contracts.
Industry Challenges
- Process optimization expertise scarcity:Regional shortages in sulfonation reaction engineering are constraining yield improvements at mid-scale facilities attempting capacity expansion.
- Multi-jurisdiction formulation portfolio complexity:Divergent purity thresholds between REACH, GB standards, and EPA industrial chemical oversight are fragmenting R&D resource allocation and inflating qualification timelines.
- Legacy concrete plant retrofit integration:Admixture dosing system upgrades at established ready-mix facilities require capital coordination with compressed construction schedules, delaying specification transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Naphthalene Water Reducers Market |
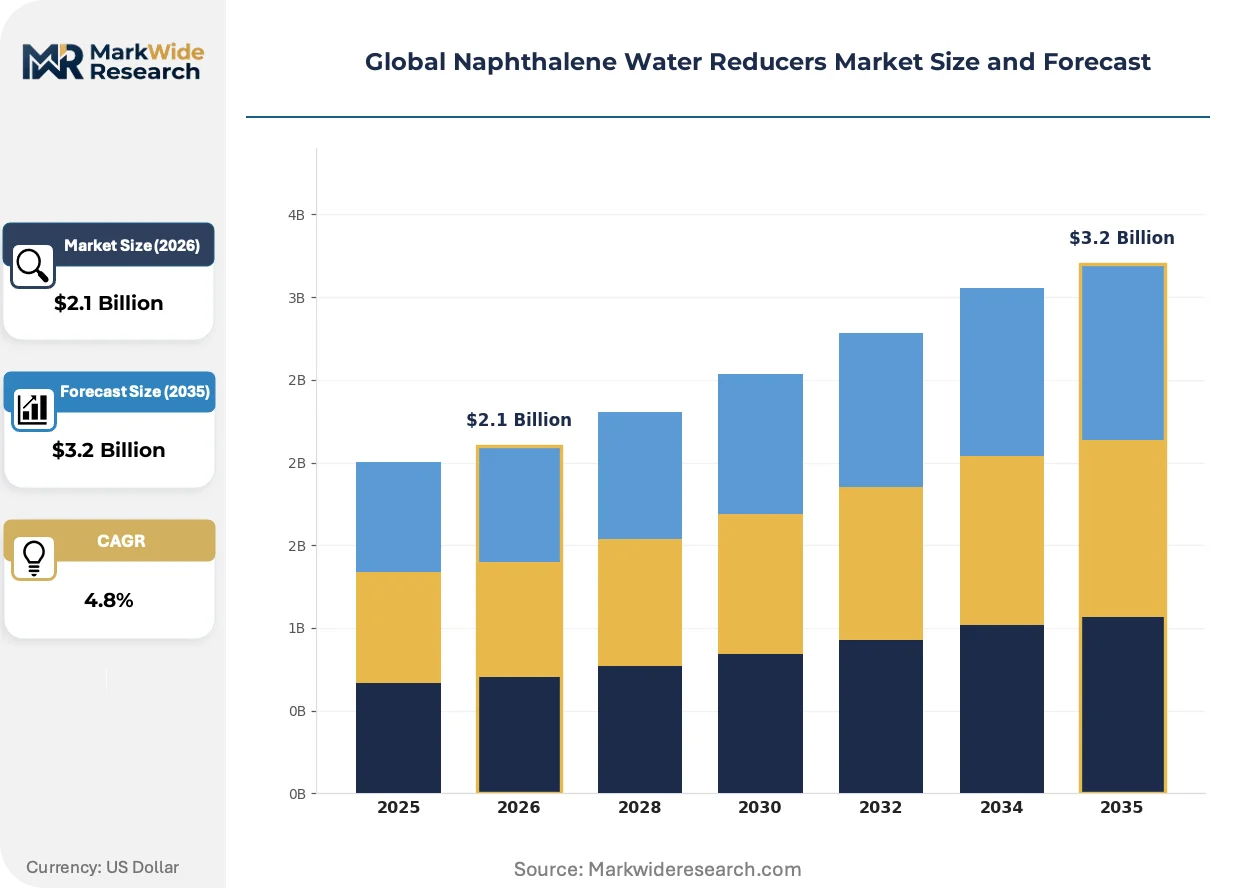
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Naphthalene, Sulfonated Naphthalene, Melamine Formaldehyde, Polycarboxylate, Lignosulfonate Application: Ready-Mix Concrete, Precast Concrete, Grouting, Shotcrete, Cement Mortar End User: Construction Contractors, Concrete Producers, Infrastructure Developers, Civil Engineers, Industrial Fabricators Packaging Type: Bulk Bags, Paper Bags, Plastic Drums, Fiber Drums, Intermediate Bulk Containers |
| Companies Covered | Himadri Specialty Chemical Ltd., Deza, Rain Carbon, ExxonMobil Chemical, BASF SE, Koppers, China Steel Chemical, PCC Group, JFE Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Naphthalene Water Reducers Market Shifts & Advancements
Formulation chemistry and compliance architecture are diverging simultaneously, with molecular engineering advancing in one stream while regulatory verification protocols tighten in another, splitting competitive advantage between technical and certification capabilities.
Sulfonated naphthalene polymer architecture is bifurcating between cost-optimized standard grades for emerging market infrastructure and precision-tailored modified variants for high-performance precast applications. Major ready-mix producers in India and Southeast Asia are specifying standard grades at volume scale, while European precasters are contracting for extended slump-retention formulations. This technical divergence is compressing mid-tier suppliers unable to serve both specification bands with single-product portfolios.
REACH registration renewal cycles and GB standard enforcement under SAMR are elevating analytical documentation requirements for sulfonation byproduct profiles. Industrial chemical oversight in the United States through EPA is layering additional import verification steps for non-domestic producers. Multi-region operators are responding by consolidating formulation platforms around highest-common-denominator purity thresholds to reduce SKU proliferation.
Specification-driven procurement is consolidating around certified producer lists maintained by major construction groups and infrastructure agencies. Third-party admixture distributors are losing position as direct contracting between sulfonated naphthalene manufacturers and concrete producers eliminates margin layers. This channel compression is most visible in India's organized ready-mix sector, where PLI-supported domestic producers are securing multi-year supply agreements with metro rail developers.
Global Naphthalene Water Reducers Market Segmentation
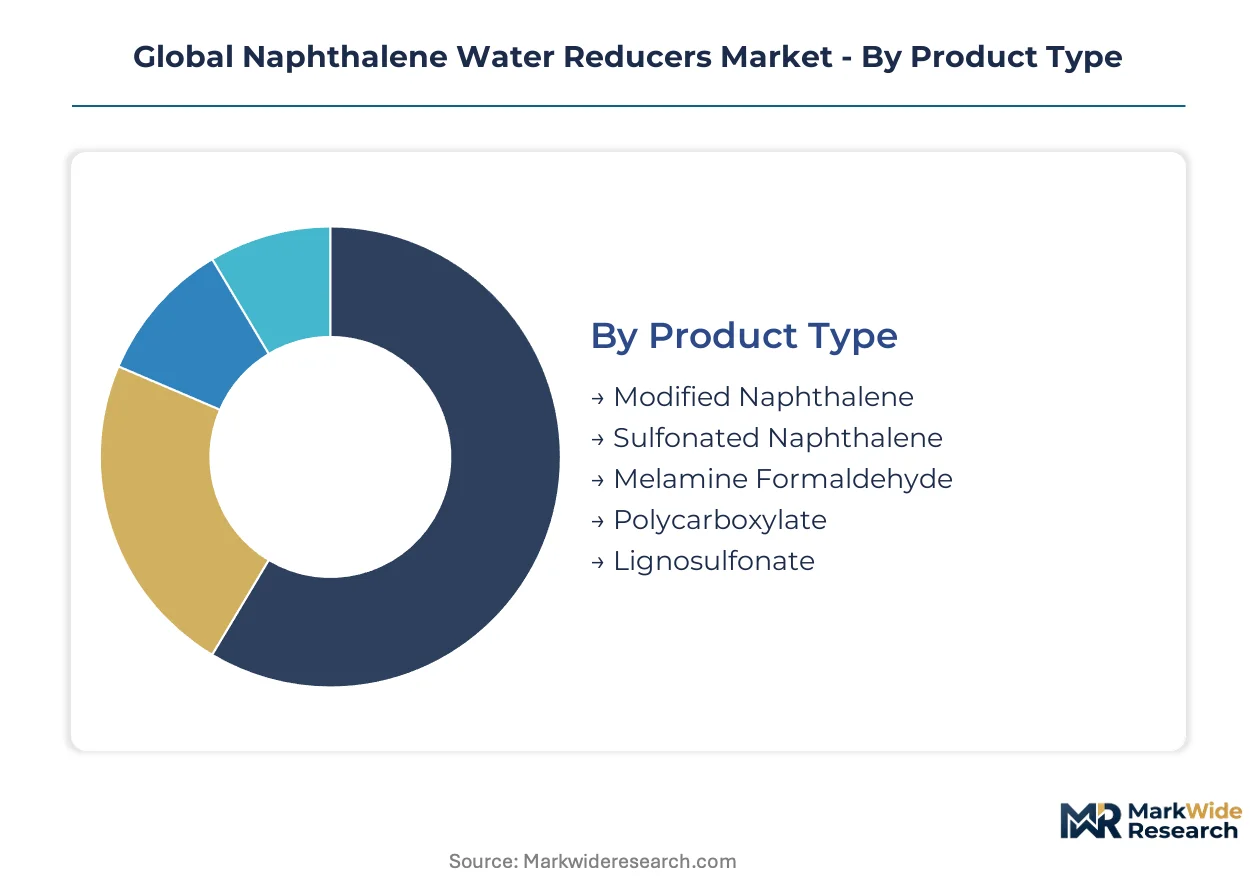
Sulfonated naphthalene formulations span multiple specification tiers, each triggering distinct REACH, GB standard, and EPA compliance pathways. Procurement patterns diverge sharply between cost-sensitive infrastructure projects and performance-driven precast operations.
Product Type:
REACH registration tiers and GB standard purity thresholds fragment competitive positioning across molecular architectures, advantaging producers with captive sulfonation capacity.
- Sulfonated Naphthalene:Standard-grade condensation polymers achieve 15-25% water reduction through controlled formaldehyde polymerization. India's PLI-supported infrastructure projects concentrate procurement in Gujarat and Maharashtra, where metro rail developers specify this grade for volume concrete placement.
- Modified Naphthalene:Engineered molecular weight distributions extend slump retention beyond conventional limits. European precasters in Germany and Poland contract for these formulations where CE-marked high-strength specifications command premium positioning.
- Melamine Formaldehyde:Cross-linked sulfonated structures deliver rapid setting profiles for specialized applications.
- Polycarboxylate:Ether-based polymer backbones displace naphthalene chemistry in self-consolidating concrete tiers.
- Lignosulfonate:Bio-based water reducers serve cost-floor segments with limited slump-life requirements.
Sulfonated naphthalene handles the majority of throughput; modified naphthalene is the fastest mover on share.
Application:
Application selection correlates directly with dosing system sophistication and batching automation levels at concrete production facilities.
- Ready-Mix Concrete:Centralized batch plants integrate liquid dosing systems for continuous naphthalene injection. Vietnam's urbanization corridors and Indonesia's highway programs concentrate demand in Ho Chi Minh City and Jakarta procurement clusters.
- Shotcrete:Accelerated setting requirements in tunneling operations favor rapid-viscosity naphthalene formulations. Mining projects across Peru's Andean copper belt and Turkey's Tunnels specification windows.
- Precast Concrete:Factory-controlled curing environments enable extended slump-life specifications.
- Grouting:Precision flow characteristics serve infrastructure repair and soil stabilization.
- Cement Mortar:Reduced water demand improves workability in masonry and plastering applications.
Ready-mix concrete dominates volume placement; shotcrete is climbing the fastest on specification adoption.
End User:
End-user procurement authority is consolidating around certified producer lists maintained by infrastructure agencies and construction groups.
- Construction Contractors:General contracting firms specify admixtures through project-level tendering. India's organized ready-mix sector is eliminating distributor layers through direct manufacturer contracting.
- Infrastructure Developers:Metro rail and highway agencies maintain pre-qualified supplier registries. Southeast Asian urbanization corridors in the Philippines and Vietnam concentrate procurement authority in state-backed developers.
- Concrete Producers:Dedicated batching operations optimize formulation for regional aggregate chemistry.
- Civil Engineers:Specification writers influence admixture selection through performance-based design standards.
- Industrial Fabricators:Precast and pre-stressed concrete manufacturers demand extended slump retention.
Construction contractors process the largest order volumes; infrastructure developers are gaining specification control fastest.
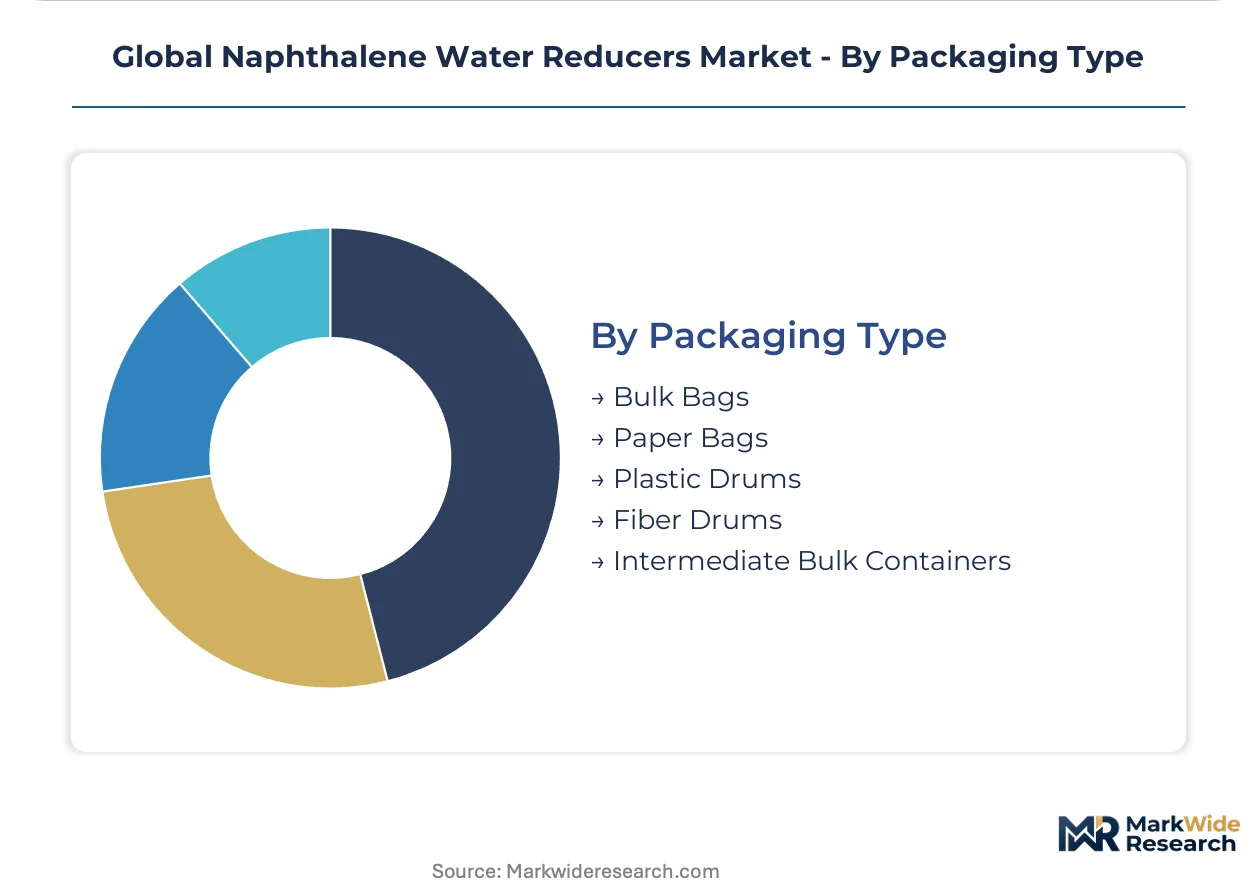
Packaging Type:
Packaging selection tracks logistics infrastructure maturity and site storage constraints across regional markets.
- Bulk Bags:One-ton flexible intermediate containers minimize handling at large-scale batch plants. China's SAMR-regulated GB standard enforcement favors bulk delivery for domestic sulfonated naphthalene distribution.
- Plastic Drums:Liquid formulation containment suits automated dosing systems. European REACH-registered producers favor drum packaging for cross-border supply chain traceability.
- Intermediate Bulk Containers:Reusable totes support closed-loop logistics for high-volume concrete producers.
- Paper Bags:Multi-wall kraft construction protects dry powder formulations.
- Fiber Drums:Rigid cylindrical containers serve specialty formulation segments.
Bulk bags move the highest tonnage; plastic drums are expanding most quickly on automated dosing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European precasters prioritize extended slump-retention formulations under REACH compliance, while Indian and Southeast Asian infrastructure developers optimize for cost-performance ratios in high-volume ready-mix placement.
China
GB standards enforcement under SAMR is elevating purity thresholds for sulfonated naphthalene formulations. The Yangtze River Delta concentration of carbon distillation capacity secures captive feedstock for integrated admixture producers. Shanghai and Jiangsu province batch plants are specifying modified naphthalene grades for metro rail concrete segments.
India
Metro rail and highway projects in Gujarat and Maharashtra are concentrating procurement of standard-grade sulfonated naphthalene. The PLI scheme for construction chemicals is drawing fresh capacity investments into domestic sulfonation facilities. Organized ready-mix producers in Mumbai and Ahmedabad are eliminating distributor layers through direct manufacturer contracting.
Germany
CE-marked high-strength concrete specifications in precast applications command premium positioning for modified naphthalene formulations. ECHA REACH registration renewal cycles are elevating analytical documentation requirements for sulfonation byproduct profiles. Industrial clusters in North Rhine-Westphalia and Bavaria anchor specification-driven procurement for tunneling and infrastructure projects.
United States
EPA industrial chemical oversight layers import verification steps for sulfonated naphthalene entering concrete supply chains. Shotcrete applications in mining and tunneling operations favor rapid-setting naphthalene formulations. Texas and California batch plant networks are integrating automated dosing systems for continuous admixture injection.
Vietnam
Urbanization corridors in Ho Chi Minh City are concentrating demand for performance-grade water reducers in metro rail procurement clusters. Infrastructure agencies maintain pre-qualified supplier registries for high-volume concrete placement. Central government highway programs are specifying standard-grade sulfonated naphthalene for bridge and road construction.
Global Naphthalene Water Reducers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the naphthalene water reducers sector. Captive coal-tar distillation capacity distinguishes the upper tier from third-party admixture producers exposed to feedstock allocation risk. Three archetypes dominate: integrated carbon specialists with backward control over naphthalene supply, multinational chemical conglomerates with global R&D networks, and regional blending specialists serving infrastructure procurement clusters. Capacity expansion and direct-to-producer channel compression represent the dominant competitive moves reshaping supply relationships.
Among integrated carbon specialists, Himadri Specialty Chemical Ltd. and Rain Carbon exemplify the archetype of producers securing captive feedstock through coal-tar distillation operations. BASF SE occupies a position representing multinational technology leadership in modified formulation development. These three anchors illustrate how competitive advantage splits between upstream resource control and downstream specification expertise.
| Leading Market Players |
|---|
| Himadri Specialty Chemical Ltd. |
| Deza |
| Rain Carbon |
| ExxonMobil Chemical |
| BASF SE |
| Koppers |
| China Steel Chemical |
| PCC Group |
| JFE Chemical Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Indian metro rail developers and domestic sulfonated naphthalene producers lock in supply access while anchoring price visibility for multi-year infrastructure buildouts, insulating procurement from spot volatility in coal-tar feedstock markets.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement for volume infrastructure projects, while spot transactions serve smaller ready-mix operators. Three-tier pricing structure across modified naphthalene, standard sulfonated grades, and lignosulfonate floor products differentiates by certification tier under REACH and GB standards. Cost compression in standard-grade segments is intensifying because polycarboxylate substitution erodes premium positioning. Construction contractors in Southeast Asia exhibit highest price sensitivity; European precasters demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for drum-packaged liquid formulations entering EU batch plants. Manufacturing concentrates in China, India, and Germany, with captive coal-tar distillation anchoring supply security for integrated producers. Production draws from naphthalene feedstock, formaldehyde polymerization reagents, and sulfonation catalysts. Single-source vulnerability concentrates around carbon distillation capacity held by limited integrated refiners. Distribution runs through direct manufacturer-to-producer contracting, eliminating third-party distributor margins in organized ready-mix sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as India's PLI scheme accelerates domestic capacity buildout and Southeast Asian urbanization corridors concentrate specification-grade procurement in dense project clusters.
For Market Incumbents: Secure captive sulfonation capacity through backward integration into coal-tar distillation or long-term feedstock offtakes, defending against polycarboxylate substitution in premium tiers. Prioritize REACH and GB standard certification renewals to maintain pre-qualified supplier status with infrastructure agencies. Channel control through direct contracting with organized ready-mix producers eliminates margin leakage to distributors. For New Entrants and Emerging Players: CE marking fast-track through ECHA pre-registration offers pathway into European precast specifications where modified naphthalene commands premium positioning. Target shotcrete applications in Peru, Chile, and Turkey mining corridors where rapid-setting formulation demand outpaces established supply. White-space exists in digital dosing system integration partnerships with automated batch plant networks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated carbon specialists with captive naphthalene supply and regional blending specialists serving India PLI-supported procurement clusters. Long-term viability hinges on regulatory compliance infrastructure and specification-grade formulation capabilities. Watch polycarboxylate penetration rates in self-consolidating concrete as signal for naphthalene displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal-Tar Distillation | Captive naphthalene supply secures feedstock allocation priority amid carbon refinery concentration. |
| REACH and GB Standard Certification Investment | ECHA and SAMR compliance elevates barrier-to-entry, filtering unverified suppliers from procurement lists. |
| Digital Dosing System Partnership | IoT-enabled batching integration locks in multi-year supply contracts through performance-based service models. |
| Shotcrete Formulation Development | Rapid-setting naphthalene grades capture specification windows in Peru, Chile, and Turkey tunneling projects. |
| Direct-to-Producer Channel Compression | Eliminating distributor layers captures margin in India's organized ready-mix sector under PLI incentives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic industry reports, combining interviews with plant managers at sulfonation facilities, procurement leads at ready-mix concrete producers, and technical R&D directors at admixture formulators. Bottom-up capacity assessments triangulate against top-down consumption estimates across the analysis window.
Segmentation dimensions modeled include product grade tier, application channel, end-user procurement authority, and regional production hub concentration. CAGRs derive from slope analysis of historical consumption trajectories and projected infrastructure spending patterns, with specific inputs from metro rail project pipelines and mining excavation forecasts.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure investment and stable regulatory enforcement timelines; material deviation in polycarboxylate substitution velocity or coal-tar feedstock availability would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market