
 South America Membrane Water Treatment Chemicals Market | 2026-2036
South America Membrane Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Membrane Water Treatment Chemicals Market Analytics
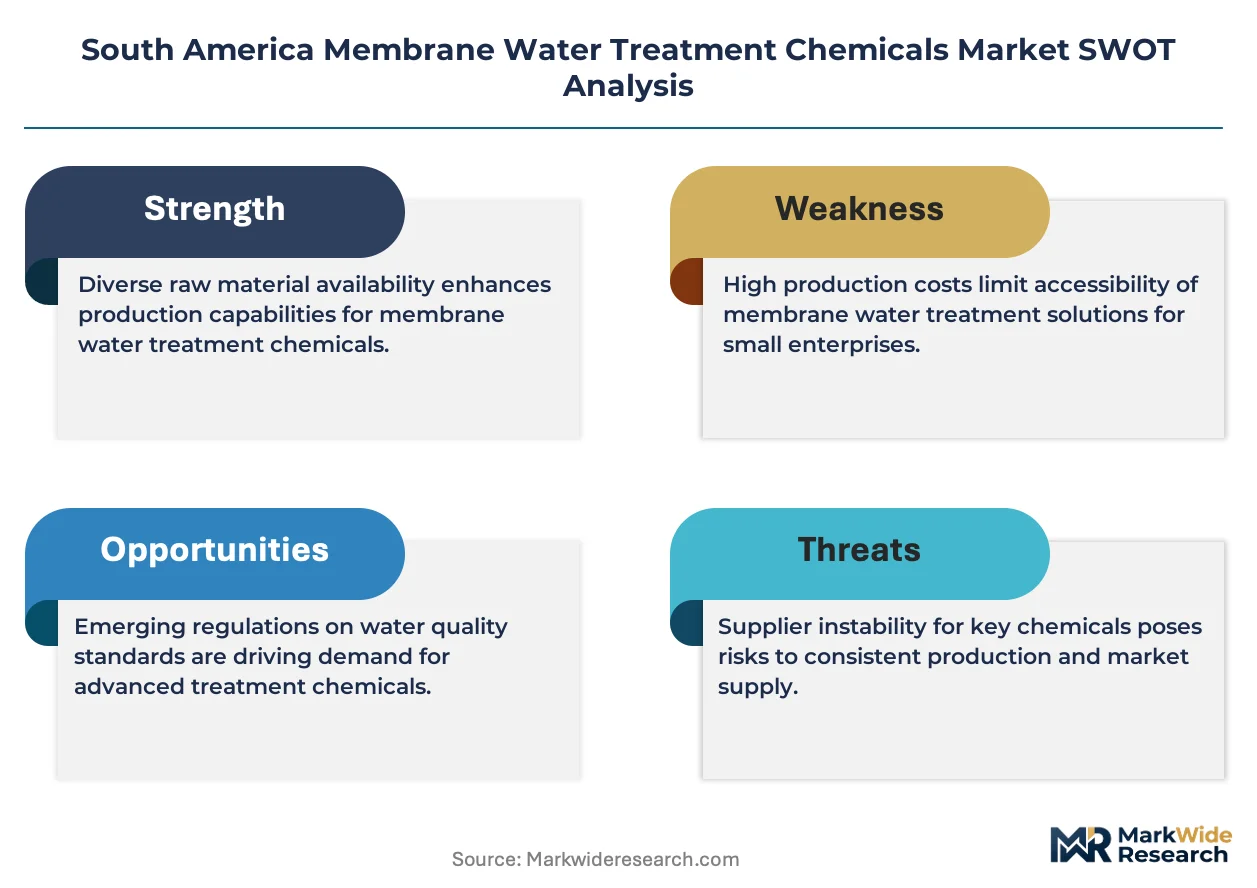
Brazil's updated CONAMA resolution on industrial effluent quality is shifting the cost-of-entry calculus for membrane system operators across the continent. Suez leverages its integrated chemical-services model to anchor municipal contracts in Brazil's southeast. Kemira competes through specialized antiscalant formulations tailored to high-silica Andean feedwaters. Dow extends its position via liquid delivery systems optimized for remote mining installations in Chile and Peru.
Membrane water treatment chemicals encompass antiscalants, biocides, pH adjusters, and cleaners engineered to prevent fouling, scaling, and biological degradation of polyamide and cellulose acetate membranes operating at pressures between 0.5 and 80 bar. These formulations sustain permeate flux rates and extend membrane element lifespans in reverse osmosis, nanofiltration, and ultrafiltration trains deployed for desalination, process water, and wastewater polishing. Antiscalants command the deepest margin pools where silica and sulfate chemistry demands polymer-specific customization, while liquid delivery modes dominate procurement patterns due to dosing precision and handling efficiency in automated feed systems. Municipal end users represent the most structurally entrenched demand segment given long-term concession contracts and tariff-indexed chemical supply agreements.
Chile's Superintendency of the Environment enforces mine closure plans that mandate zero liquid discharge, directly expanding antiscalant and membrane cleaner consumption. Brazil's ANA and Peru's National Water Authority both impose tightening intake and discharge limits that force industrial facilities toward chemical-intensive pretreatment before membrane arrays. Stakeholders must monitor how lithium extraction brine management in Argentina's Salta-Jujuy triangle redirects chemical demand toward extreme-salinity formulations.
Market Dynamics
Brazil's ANA effluent discharge tightening is forcing industrial operators toward chemical-intensive membrane pretreatment, compressing capital planning cycles and reshaping supplier qualification criteria across the continent.
Growth Catalysts
- ANA Resolution 430/2021:Brazil's stricter industrial effluent limits mandate chemical pretreatment before membrane arrays, pulling antiscalant and biocide volumes into São Paulo's manufacturing corridor.
- Zero liquid discharge mandates:Chile's Superintendency of the Environment mine closure protocols require brine concentration and crystallization systems, expanding demand for extreme-salinity antiscalant formulations in Antofagasta and Tarapacá.
- High-silica Andean geology:Feedwater chemistry in Peru's northern mining districts necessitates polymer-specific antiscalant customization, creating premium formulation pull-through.
Market Restraints
- Acrylate and phosphonate feedstock volatility:Antiscalant base chemical prices fluctuate with Asian petrochemical output, compressing blender margins in Brazil and Argentina.
- Single-source supply concentration:Specialty biocide active ingredients concentrate among European and North American producers, exposing South American formulators to currency and freight risk.
- Membrane element substitution:Ceramic and graphene oxide membrane alternatives reduce chemical dependency in high-fouling applications, threatening growth in cleaner and biocide categories.
Strategic Opportunities
- Argentina lithium triangle:Brine extraction operations in Salta-Jujuy provinces generate extreme-salinity wastewater streams requiring novel antiscalant chemistries not yet standardized in existing product lines.
- Peru agricultural processing:Coastal asparagus and avocado packers face tightening discharge limits, opening membrane reuse system adoption with bundled chemical service contracts.
- Remote liquid delivery systems:Automated dosing skids with telemetry integration enable chemical-as-a-service models in Chilean and Peruvian mining camps beyond conventional distribution reach.
Industry Challenges
- Membrane autopsy technician scarcity:Fouling diagnosis requires specialized analytical chemistry skills concentrated in São Paulo and Santiago, creating service response delays in secondary markets.
- CONAMA certification timelines:New chemical registrations face multi-year environmental hazard review, slowing product portfolio refresh cycles for Brazil-focused suppliers.
- Legacy DCS integration:Older reverse osmosis trains lack digital communication protocols, complicating automated chemical feed system retrofits in Brazilian municipal utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Membrane Water Treatment Chemicals Market |
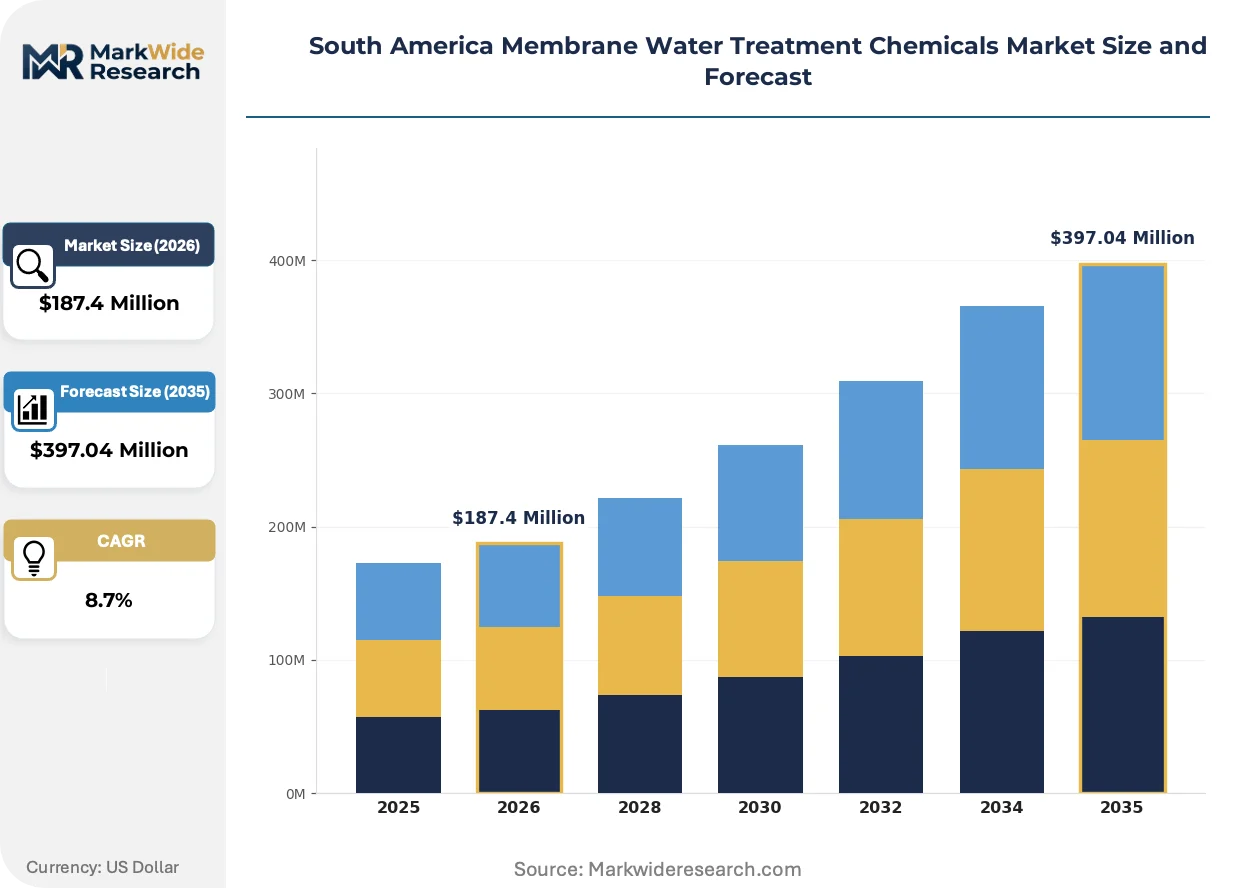
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, Antiscalants End User: Municipal, Industrial, Agricultural, Irrigation Delivery Mode: Liquid, Powder, Granular, Concentrated Packaging Type: Drums, Bags, Tankers, Containers |
| Companies Covered | Suez, Veolia Water Technologies, Kurita Water Industries Ltd, Ecolab, Kemira, Dow, Danaher, Italmatch Chemicals, Genesys International, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Membrane Water Treatment Chemicals Market Evolving Landscape
Digital dosing infrastructure and feedwater chemistry complexity are elevating chemical supplier roles from commodity vendors to process partners, restructuring procurement evaluation criteria and contract architectures.
Continuous conductivity and oxidation-reduction potential sensors embedded in membrane feed headers is automating antiscalant and biocide injection rates in real time. Chilean copper concentrators in the Atacama are deploying these systems most aggressively, reducing membrane cleaning frequency and extending element replacement intervals from eighteen to thirty-six months in high-silica conditions.
Brazil's CONAMA Resolution 430/2021 and Peru's analogous water quality frameworks are mandating online effluent monitoring with data transmission to national environmental agencies. This regulatory architecture forces membrane operators toward validated chemical dosing records, privileging suppliers with digital traceability platforms over conventional bulk chemical traders in municipal and industrial tenders.
Performance-guarantee contracting is displacing volume-based chemical procurement in large Brazilian municipal concessions. Suez and Kemira now structure agreements where chemical costs tie to permeate flux maintenance targets, transferring fouling risk from plant operators to chemical suppliers and compressing competitor qualification to those with membrane autopsy and root-cause analytical capabilities.
South America Membrane Water Treatment Chemicals Market Segmentation
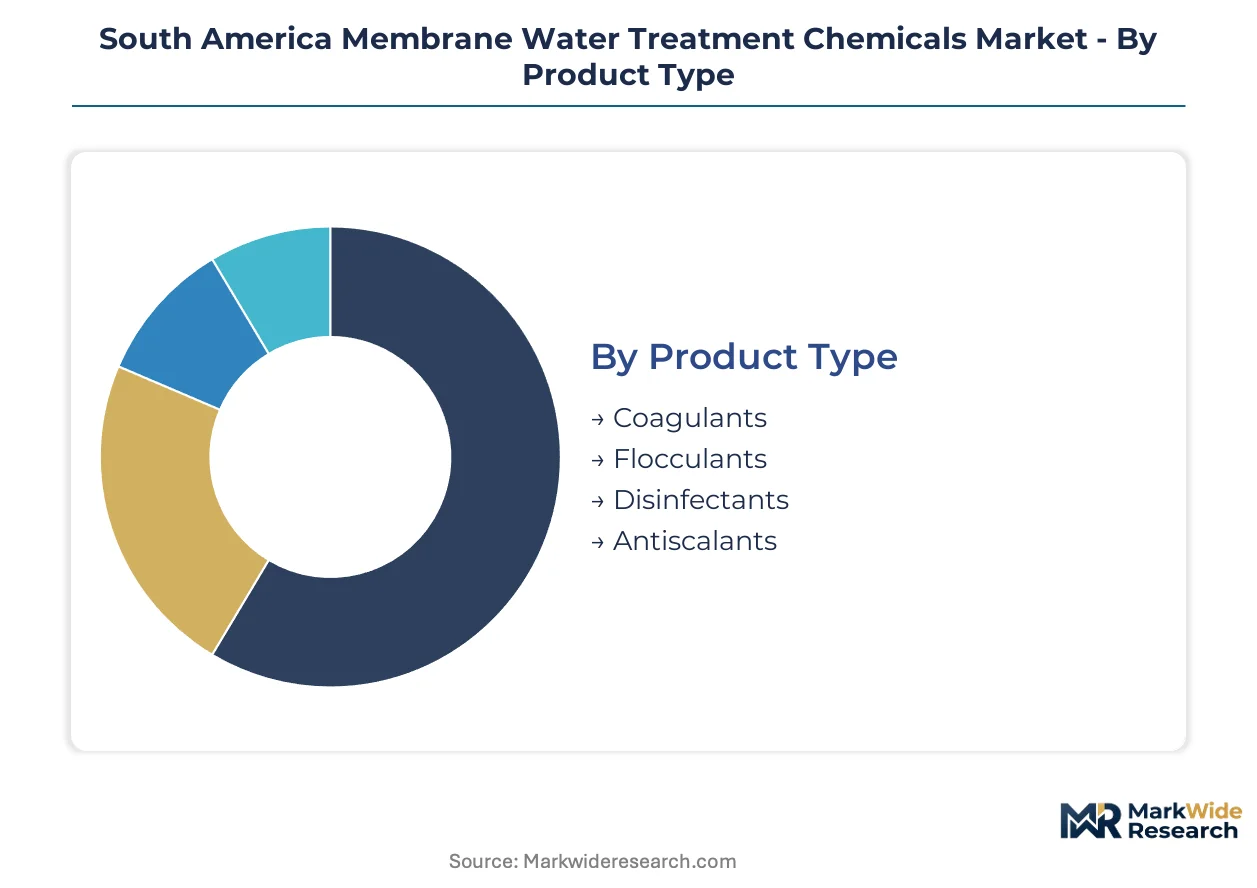
Membrane water treatment chemicals fragment across formulation chemistry, delivery logistics, and end-use specifications. Each segmentation axis carries distinct margin profiles and procurement patterns that reshape supplier positioning across Brazil, Chile, and Peru.
Product Type:
Antiscalants command premium pricing while coagulants and flocculants move in commodity volumes across municipal tenders.
- Antiscalants:Polymer formulations targeting silica, sulfate, and carbonate scaling in high-pressure reverse osmosis trains. Demand concentrates in Chile's Antofagasta copper concentrators and Peru's northern mining districts where Andean feedwater chemistry necessitates customized polymer architecture.
- Coagulants:Aluminum- and iron-based compounds destabilizing colloidal particles ahead of membrane arrays. São Paulo's industrial corridor pulls the deepest volumes as Brazil's ANA Resolution 430/2021 tightens pretreatment mandates for effluent discharge compliance.
- Flocculants:High-molecular-weight polymers aggregating coagulated solids for removal. Brazilian sugar-ethanol processors and Argentine food packers dominate procurement.
- Disinfectants:Oxidizing biocides controlling biofouling in polyamide membrane elements. Coastal desalination plants in Chile's Tarapacá region drive specification intensity.
Today's leader: Antiscalants. Tomorrow's challenger: Disinfectants.
End User:
Municipal concessions lock in long-term supply agreements while industrial users demand performance-guarantee contracting.
- Municipal:Water utilities operating desalination and wastewater reuse facilities under tariff-indexed concession contracts. Brazil's ANA and Peru's National Water Authority tightening discharge standards force chemical-intensive pretreatment adoption across São Paulo and Lima metropolitan systems.
- Industrial:Mining, food processing, and manufacturing facilities with membrane-based process water and effluent polishing. Chile's Superintendency of the Environment zero-liquid-discharge mandates for mine closure plans directly expand antiscalant and cleaner consumption in Antofagasta.
- Agricultural:Coastal asparagus and avocado packers in Peru deploying membrane reuse for irrigation water. Tightening discharge limits open bundled chemical service opportunities.
- Irrigation:Large-scale agricultural water districts treating brackish sources for crop application. Argentina's Mendoza wine region and Brazil's semi-arid northeast show emerging specification development.
Municipal anchors current revenue. Industrial offers the steepest expansion trajectory through performance-based contracting.
Delivery Mode:
Liquid formulations dominate automated feed systems while powder and granular alternatives persist in manual-dosing legacy installations.
- Liquid:Ready-to-dose solutions enabling precision injection through automated skids with telemetry integration. Chilean and Peruvian mining camps beyond conventional distribution reach favor liquid delivery for chemical-as-a-service models.
- Powder:Dry formulations requiring on-site dissolution and batch preparation. Smaller Brazilian municipal utilities with legacy infrastructure maintain powder procurement for cost containment.
- Granular:Slow-dissolving solid forms for low-maintenance dosing applications. Remote agricultural installations in Argentina's interior favor granular for reduced handling frequency.
- Concentrated:High-strength formulations diluting at point-of-use to reduce freight costs. Coastal desalination plants with bulk storage infrastructure specify concentrated antiscalants.
Liquid holds installed-base dominance. Concentrated formulations gain share fastest in freight-sensitive remote deployments.
Packaging Type:
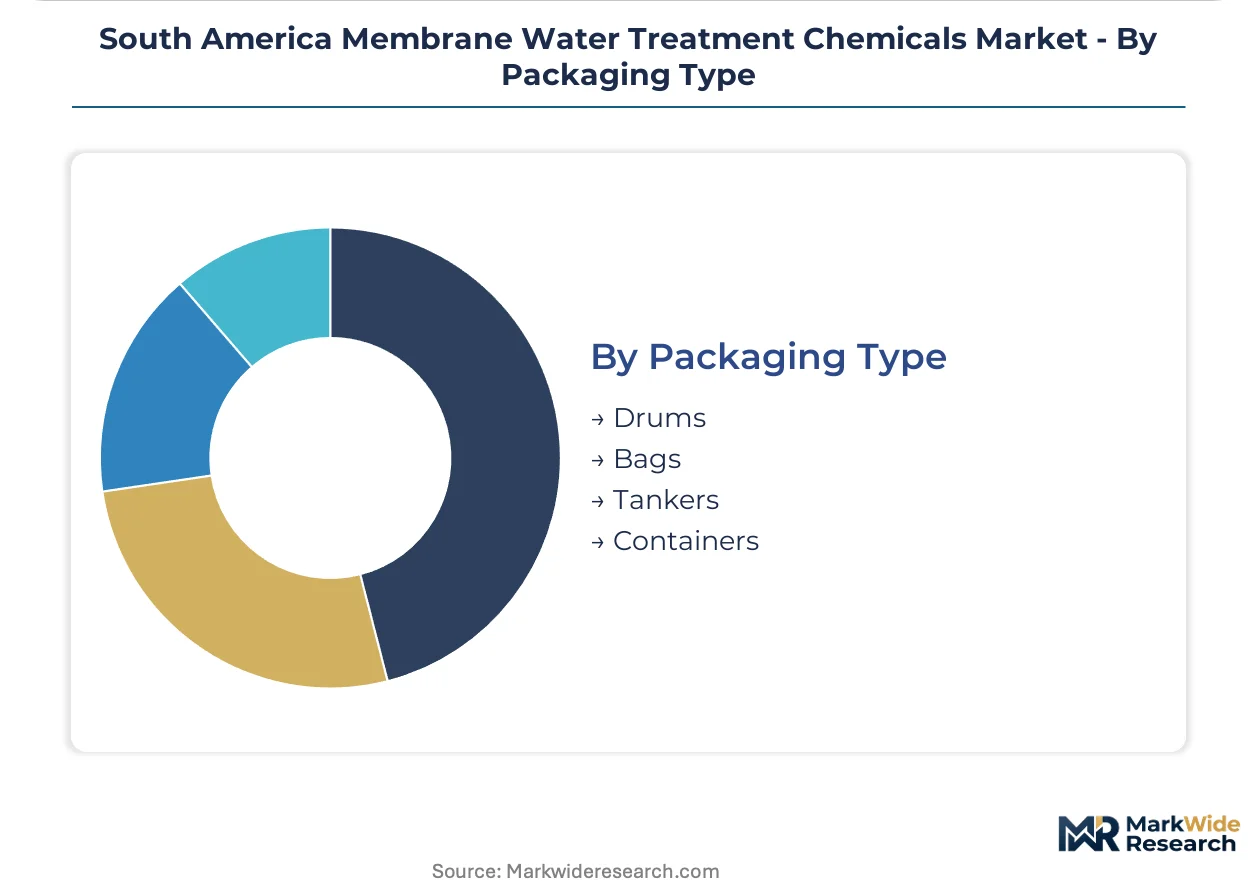
Drums and bags fragment procurement while tankers concentrate in large municipal and mining accounts.
- Drums:Standard 200-liter containers serving mid-scale industrial and municipal operators. Brazil's southeast manufacturing corridor represents the densest drum logistics network.
- Bags:Flexible intermediate bulk containers and smaller sacks for powder and granular products. Argentine agricultural processors favor bagged flocculants for seasonal demand flexibility.
- Tankers:Bulk liquid delivery for high-volume continuous operations. Chilean copper concentrators and Brazilian metropolitan utilities specify tanker supply to minimize packaging waste and handling labor.
- Containers:Intermediate bulk containers and totes bridging drum and tanker volumes. Peru's coastal agricultural packers deploy containers for membrane reuse system startups.
Tankers define the premium tier. Containers represent the fastest-climbing format for mid-scale industrial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized membrane autopsy technicians cluster in São Paulo and Santiago, creating service response bottlenecks that shape supplier qualification across secondary markets.
Brazil
São Paulo's industrial corridor drives antiscalant and biocide volumes as ANA Resolution 430/2021 tightens effluent discharge standards. The National Water Agency mandates chemical-intensive pretreatment before membrane arrays, compressing capital planning cycles for manufacturing facilities. CONAMA certification timelines slow new chemical registrations, favoring established suppliers with existing environmental hazard approvals.
Chile
Antofagasta and Tarapacá mining districts pull extreme-silica antiscalant formulations tailored to Andean feedwater chemistry. The Superintendency of the Environment enforces zero liquid discharge mandates for mine closure plans, expanding brine concentration and crystallization system deployments. Copper concentrators in the Atacama deploy real-time conductivity sensors to automate chemical injection rates.
Peru
Northern mining districts and coastal agricultural packers split membrane chemical demand between high-silica antiscalants and bundled reuse system contracts. The National Water Authority tightens intake and discharge limits, forcing asparagus and avocado processors toward membrane polishing with validated dosing records. Lima metropolitan utilities specify tanker delivery to minimize packaging waste.
Argentina
Salta-Jujuy lithium triangle operations generate extreme-salinity brine streams requiring novel antiscalant chemistries outside existing product lines. Mendoza wine region shows emerging specification development for brackish water treatment in irrigation districts. The country's national water regulator imposes discharge frameworks that redirect chemical demand toward unstandardized formulations.
South America Membrane Water Treatment Chemicals Market Competitive Landscape
The competitive structure tilts toward integrated chemical-services specialists with membrane autopsy capabilities. Suez and Kemira anchor municipal concessions through performance-guarantee contracting, transferring fouling risk from plant operators to suppliers. Three archetypes dominate: European integrated water technology conglomerates, Nordic specialty chemical formulators, and diversified industrial chemical majors. Geographic expansion through automated liquid delivery skids and portfolio diversification into digital dosing telemetry represent the dominant competitive vectors.
Among integrated water technology specialists, Suez and Veolia Water Technologies exemplify the chemical-services model that has displaced volume-based procurement in Brazilian municipal tenders. Kemira represents the specialty formulation archetype competing through polymer-specific customization for high-silica Andean conditions. Dow occupies a position among diversified chemical majors leveraging liquid delivery system optimization for remote mining installations.
| Leading Market Players |
|---|
| Suez |
| Veolia Water Technologies |
| Kurita Water Industries Ltd |
| Ecolab |
| Kemira |
| Dow |
| Danaher |
| Italmatch Chemicals |
| Genesys International |
| Others |
Value Network & Pricing Analysis
Automated liquid dosing infrastructure is displacing manual powder handling across Chilean mining camps and Brazilian municipal utilities, compressing per-unit chemical costs while concentrating procurement power among suppliers with telemetry-integrated service capabilities. This technology shift simultaneously erodes commodity trader margins and elevates integrated chemical-services specialists who bundle formulation expertise with real-time monitoring platforms.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the continent. Unbundled commodity transactions dominate smaller Brazilian utilities with legacy powder systems, while bundled chemical-as-a-service contracts command premium positioning in Chilean copper concentrators. Price differentiation hinges on formulation customization intensity and digital traceability certification under Brazil's CONAMA monitoring mandates. Pricing pressure stems from acrylate and phosphonate feedstock volatility tied to Asian petrochemical output. Municipal concessions show lowest price sensitivity due to tariff-indexed long-term agreements, while Peruvian agricultural packers exhibit acute cost consciousness in reuse system startups.
Supply Chain Analysis
Antiscalant active ingredient supply rests on European and North American specialty chemical producers, with phosphonate and polyacrylate polymer feedstock concentrated in Germany, the United States, and Japan. Biocide active ingredients draw from Swiss and American agrochemical specialists. Single-source concentration for specialty actives exposes South American formulators to currency fluctuation and trans-Atlantic freight risk. Distribution runs through São Paulo-based chemical distributors serving Brazil's southeast manufacturing corridor, with direct tanker delivery penetrating Chilean mining districts and Peruvian coastal processing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by regulatory ratcheting across Brazilian effluent standards and Chilean mine closure mandates, generating predictable chemical volume growth tied to enforcement intensity rather than discretionary capital cycles.
For Market Incumbents: Deepen membrane autopsy capabilities to defend performance-guarantee contract positioning against emerging digital-native competitors. Expand backward integration into phosphonate intermediate production to buffer Asian feedstock volatility compressing blender margins. Prioritize CONAMA pre-certification investments to accelerate product portfolio refresh cycles before multi-year environmental hazard reviews stall competitor entries.
For New Entrants and Emerging Players: Begin with Argentina's Salta-Jujuy lithium triangle, where extreme-salinity brine chemistries lack standardized formulations and incumbent product lines prove inadequate. Target Peruvian coastal agricultural packers facing tightening National Water Authority discharge limits with bundled membrane reuse and chemical service packages. Pursue chemical-as-a-service go-to-market models leveraging automated dosing skids with telemetry integration to bypass established distribution networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators lacking membrane autopsy capabilities but holding CONAMA environmental registrations. Five-to-ten year viability favors specialists with digital dosing platforms and long-term municipal concession anchors. Watch Argentina's lithium extraction brine management regulations as the signal for extreme-salinity formulation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Guarantee Contracting | Transfers fouling risk from plant operators to chemical suppliers under ANA-monitored Brazilian municipal concessions. |
| Backward Integration into Phosphonate Feedstock | Reduces margin compression from Asian petrochemical output volatility affecting antiscalant blenders. |
| Digital Dosing Telemetry Integration | Enables real-time conductivity and oxidation-reduction potential automation in Chilean Atacama copper concentrators. |
| CONAMA Pre-Certification Investment | Accelerates product portfolio refresh cycles before multi-year environmental hazard reviews stall competitor entries. |
| Extreme-Salinity Formulation Development | Addresses unstandardized chemistries required for Argentina's Salta-Jujuy lithium extraction brine management. |
Research Methodology
Coverage spans Brazil, Chile, Peru, and Argentina, with primary inputs from each national market. The research combines structured interviews with membrane system operators, municipal utility procurement managers, mining camp water treatment supervisors, and specialty chemical formulator technical directors with secondary validation from ANA regulatory filings, Chile's Superintendency of the Environment mine closure protocols, Peruvian National Water Authority discharge databases, and customs trade data on antiscalant active ingredient imports. Bottom-up chemical volume estimates triangulate against top-down membrane installation capacity projections.
Granularity extends to product-type formulation chemistry, delivery mode logistics, and end-user sector specifications across the projection horizon. The analytical framework models antiscalant, biocide, coagulant, flocculant, and disinfectant categories separately, with municipal, industrial, agricultural, and irrigation demand segments tracked at country level. CAGRs derive from membrane capacity expansion pipelines, regulatory enforcement timelines, and feedstock cost trajectory assumptions. Silica-specific polymer customization intensity and zero-liquid-discharge mandate penetration serve as industry-specific forecast sensitivity inputs.
Caveats apply where Argentine lithium brine regulation evolution or Brazilian CONAMA certification timeline shifts could materially shift the outlook. Forecasts reflect assumptions on feedstock price stability, membrane element substitution rates by ceramic alternatives, and municipal concession contract renewal patterns. A small set of named triggers—lithium extraction wastewater standards, phosphonate supply disruption, and membrane autopsy technician training program expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market