
 Global Mobile Water Treatment Market | 2026-2036
Global Mobile Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Water Treatment Market Intelligence
An expanding need for temporary water infrastructure in the construction and mining sectors is realigning the end-user base away from a primary focus on disaster relief. This shift favors suppliers with robust, scalable systems capable of handling industrial-grade contaminants. Veolia Water Technologies leverages its extensive service network to deploy containerized plants for long-term projects. SUEZ Water Technologies & Solutions competes with specialized trailer-mounted systems for rapid deployment at construction sites.
Mobile water treatment involves self-contained, transportable systems designed for on-demand water purification. These units integrate technologies like reverse osmosis, capable of rejecting contaminants down to 0.0001 microns, to produce potable or process water. Within the technology segment, reverse osmosis and advanced filtration hold the largest share for their versatility. Containerized plants and trailer-mounted systems represent the dominant deployment types, serving long-duration needs at mining operations and short-term requirements for disaster relief.
Water quality standards dictated by entities like the US EPA and the European Union's Water Framework Directive directly influence system design and treatment efficacy requirements. Additionally, WHO guidelines for drinking-water quality set the benchmark for systems deployed in disaster relief and remote community applications. The critical decision for operators is balancing the capital cost of advanced, multi-barrier treatment systems against the operational risks of non-compliance in diverse regulatory environments.
Market Dynamics
The market's center of gravity is shifting from emergency response towards long-term industrial deployments. This realignment is primarily driven by acute water scarcity and stricter environmental regulations in resource extraction and heavy industry sectors, fundamentally changing system design priorities.
Growth Catalysts
- Stringent Effluent Standards:Regulations like the US EPA's Effluent Limitation Guidelines and Australia's National Water Quality Management Strategy compel industries to adopt advanced, on-site treatment to avoid penalties for non-compliant discharge.
- Remote Industrial Operations:The expansion of mining and energy projects into water-scarce regions, such as the Atacama Desert in Chile and the Pilbara in Australia, creates non-discretionary demand for reliable process water and wastewater management.
- Technology Versatility:The effectiveness of reverse osmosis and advanced filtration technologies in removing a wide spectrum of contaminants makes them suitable for diverse applications, from producing potable water to treating complex industrial wastewater.
Market Restraints
- High Capital Cost:The significant initial investment required for sophisticated multi-barrier treatment systems, particularly for containerized plants, presents a barrier for small to medium-sized enterprises and municipalities with constrained budgets.
- Energy Consumption:The high energy requirement of pressure-driven membrane processes like reverse osmosis results in substantial operational costs, especially in off-grid locations where power must be generated by diesel.
- Logistical Complexity:Transporting, installing, and servicing large-scale mobile treatment units in remote or inaccessible locations involves considerable logistical challenges and costs, impacting project viability and timelines.
Strategic Opportunities
- Agricultural Sector Expansion:There is an opportunity to serve large-scale agricultural operations in water-stressed regions like India and North Africa, providing treated water for irrigation during drought conditions.
- Digital Service Integration:Integrating IoT sensors for real-time monitoring and predictive analytics offers a new service-based revenue stream, allowing for remote system optimization and preemptive maintenance.
- PFAS Remediation:Developing specialized mobile units designed specifically for the remediation of per- and polyfluoroalkyl substances (PFAS) at contaminated industrial sites and military bases creates a high-value niche market.
Industry Challenges
- Specialized Talent Shortage:A deficit of qualified technicians and engineers with the cross-disciplinary skills to operate and maintain increasingly complex, automated mobile water systems in remote field environments constrains service delivery.
- Regulatory Navigation:Operators face the challenge of ensuring system compliance across a patchwork of local, national, and international water quality standards, such as those set by the WHO, which vary significantly by jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Water Treatment Market |
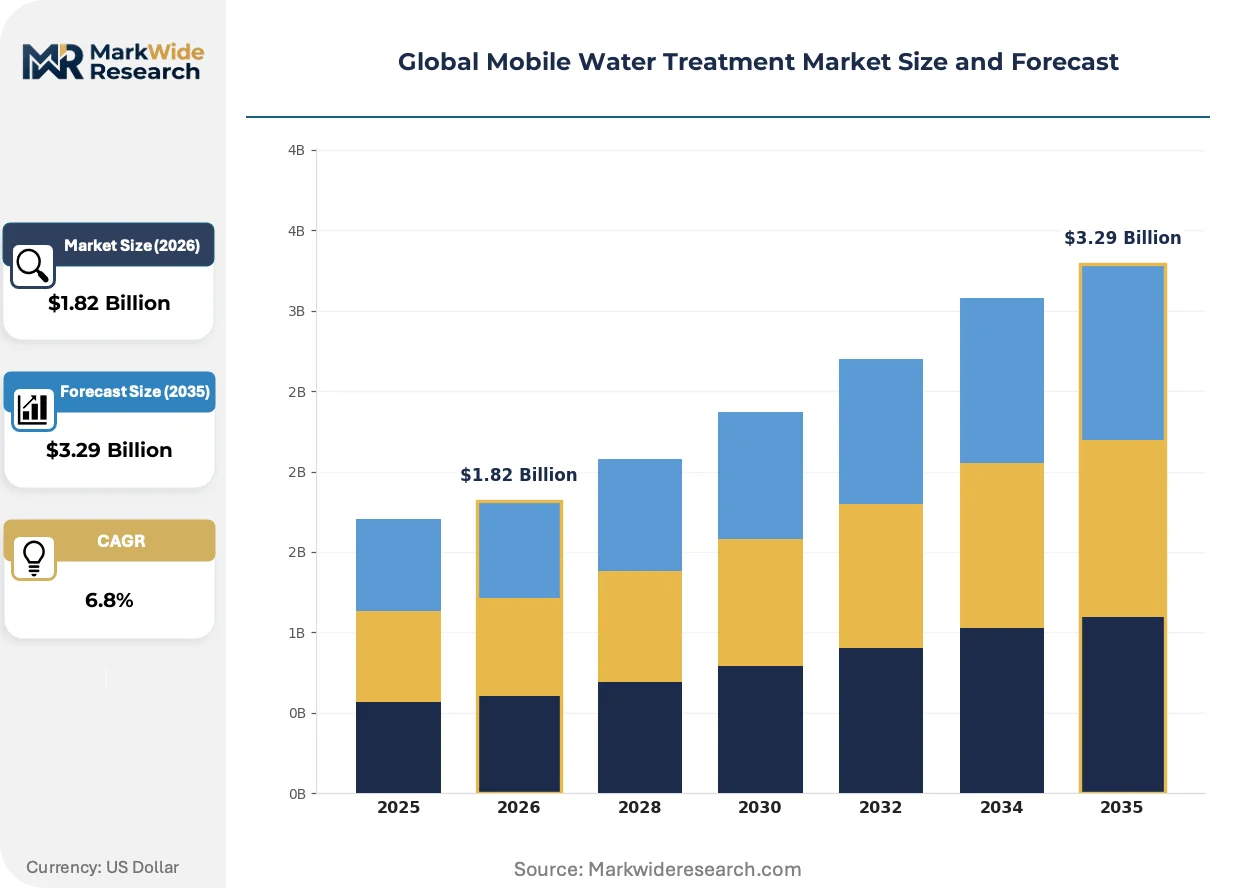
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reverse Osmosis, Ultraviolet, Activated Carbon, Ion Exchange, Chemical Treatment, Filtration Application: Disaster Relief, Military Operations, Construction Sites, Remote Communities, Mining Operations, Festivals & Events Deployment Type: Portable Units, Trailer-Mounted Systems, Containerized Plants, Truck-Mounted Solutions, Skid-Mounted Installations End User: Municipal Authorities, Oil & Gas Operators, NGOs, Defense Forces, Mining Companies, Event Organizers |
| Companies Covered | Xylem Inc., Pentair plc, Veolia Water Technologies, Danaher Corporation, Aquatech International, SUEZ Water Technologies & Solutions, Ecolab Inc., GE Water & Process Technologies, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Water Treatment Market Strategic Shifts & Innovations
Digitalization and advanced materials are transforming mobile water treatment from a reactive, temporary fix into a proactive, data-driven utility service. This evolution enables greater efficiency, reliability, and compliance assurance for end-users across industrial and municipal sectors.
Ceramic membrane filtration provides superior durability and tolerance to harsh chemical environments compared to traditional polymeric alternatives. The food and beverage industry is adopting this technology for challenging high-solids wastewater streams where system longevity is critical. This robust performance is absorbing the market share previously held by less resilient media in demanding industrial process loops.
The European Union's Water Framework Directive establishes stringent, legally binding water quality objectives for all surface and ground waters. This regulation creates a persistent compliance pressure for industrial facilities, including those operating on a temporary or project basis. The industrial end-use segment is most affected, now demanding mobile systems with verifiable performance against specific chemical and biological parameters.
A clear shift toward flexible, service-oriented contracts over outright capital purchase is altering customer behavior. This model disrupts the traditional equipment sales channel, favoring suppliers who offer comprehensive leasing and rental packages that include operation and maintenance. This trend is most prominent in the construction and events industries, where water infrastructure needs are intense but temporary.
Global Mobile Water Treatment Market Segmentation
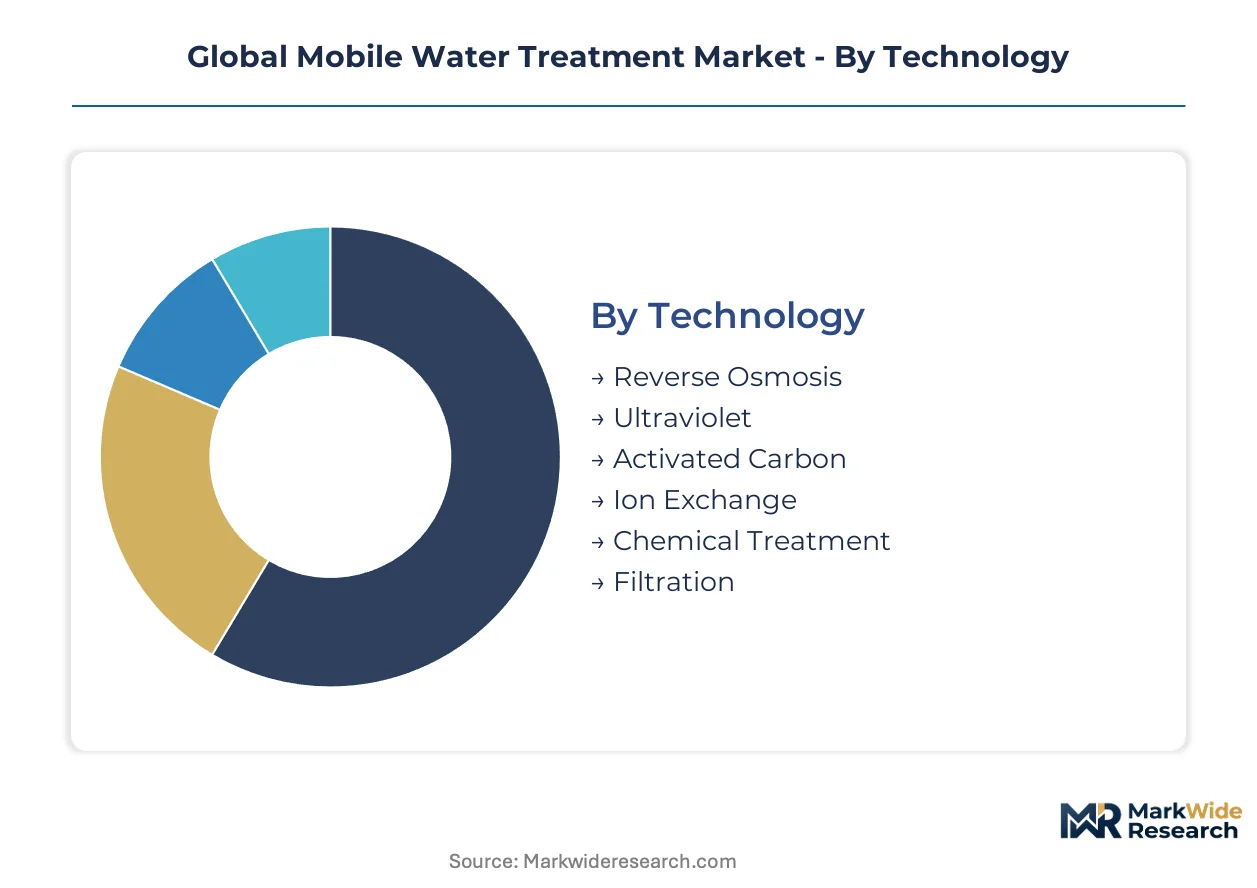
The global mobile water treatment market is characterized by diverse demands across various end-use sectors, necessitating a granular understanding of technology, application, deployment, and user-specific requirements. This segmentation illuminates the varied operational contexts and regulatory pressures shaping procurement decisions for transportable water purification solutions.
Technology:
Buyers in this category differentiate based on the specific contaminants requiring removal and the desired purity level for the treated water output.
- Reverse Osmosis:This membrane-based process rejects dissolved solids down to 0.0001 microns, producing high-purity potable or process water. Demand concentrates in mining operations and remote industrial sites in countries like Chile, driven by stringent effluent standards and the need for ultra-pure water.
- Filtration:Encompasses various physical separation methods like ultrafiltration and microfiltration, primarily removing suspended solids, turbidity, and some microorganisms. Demand is robust in construction sites and disaster relief scenarios, driven by the immediate need for basic water quality improvement.
- Ultraviolet:Utilizes UV-C light to disinfect water by inactivating bacteria, viruses, and protozoa without chemical addition.
- Activated Carbon:Employs porous carbon to adsorb organic compounds, chlorine, and other taste- and odor-causing substances.
- Ion Exchange:Removes specific ionic contaminants such as hardness, nitrates, or heavy metals through chemical exchange resins.
- Chemical Treatment:Involves the addition of chemicals for coagulation, flocculation, pH adjustment, or oxidation of pollutants.
Volume sits with Filtration; growth tilts toward Reverse Osmosis.
Application:
The operational context and duration of water infrastructure needs largely define the application segment requirements.
- Mining Operations:These sites demand substantial volumes of high-quality process water and robust wastewater management solutions for continuous production. Demand is concentrated in resource-rich nations such as Australia, driven by the necessity for sustained operations in water-stressed regions.
- Construction Sites:Require temporary potable water for personnel and process water for various construction activities, often for the duration of a project. Demand is strong in urban development and large infrastructure projects, driven by transient, project-specific water needs.
- Disaster Relief:Provides immediate access to safe drinking water in emergency situations following natural calamities or humanitarian crises.
- Military Operations:Supports troop deployment and base operations in remote or austere environments with reliable water supply for consumption and sanitation.
- Remote Communities:Delivers sustainable water access and treatment for isolated populations lacking permanent infrastructure.
- Festivals & Events:Manages temporary potable water supply and wastewater treatment for large public gatherings over defined periods.
The segment's expansion is primarily driven by industrial operational continuity, with humanitarian needs also contributing.
Deployment Type:
Mobility requirements and the necessary treatment capacity dictate the choice of deployment type for mobile water systems.
- Containerized Plants:These systems offer robust, high-capacity treatment housed within standard ISO shipping containers, suitable for long-term industrial projects. Demand is concentrated in mining and heavy industry sectors, driven by the need for scalable, semi-permanent infrastructure.
- Trailer-Mounted Systems:Provide rapid deployment and mobility for medium-scale, temporary water needs across various locations. Demand is strong in construction sites and emergency response, driven by requirements for quick setup and relocation.
- Portable Units:Small, highly mobile treatment systems designed for individual or small group use, emphasizing ease of transport.
- Truck-Mounted Solutions:Integrate complete treatment systems onto vehicles, offering flexible and mobile water purification capabilities.
- Skid-Mounted Installations:Pre-assembled treatment units mounted on a rigid base, designed for fixed or semi-permanent installations requiring minimal on-site assembly.
Versatility is a hallmark of Trailer-Mounted Systems, while Containerized Plants offer the highest capacity.
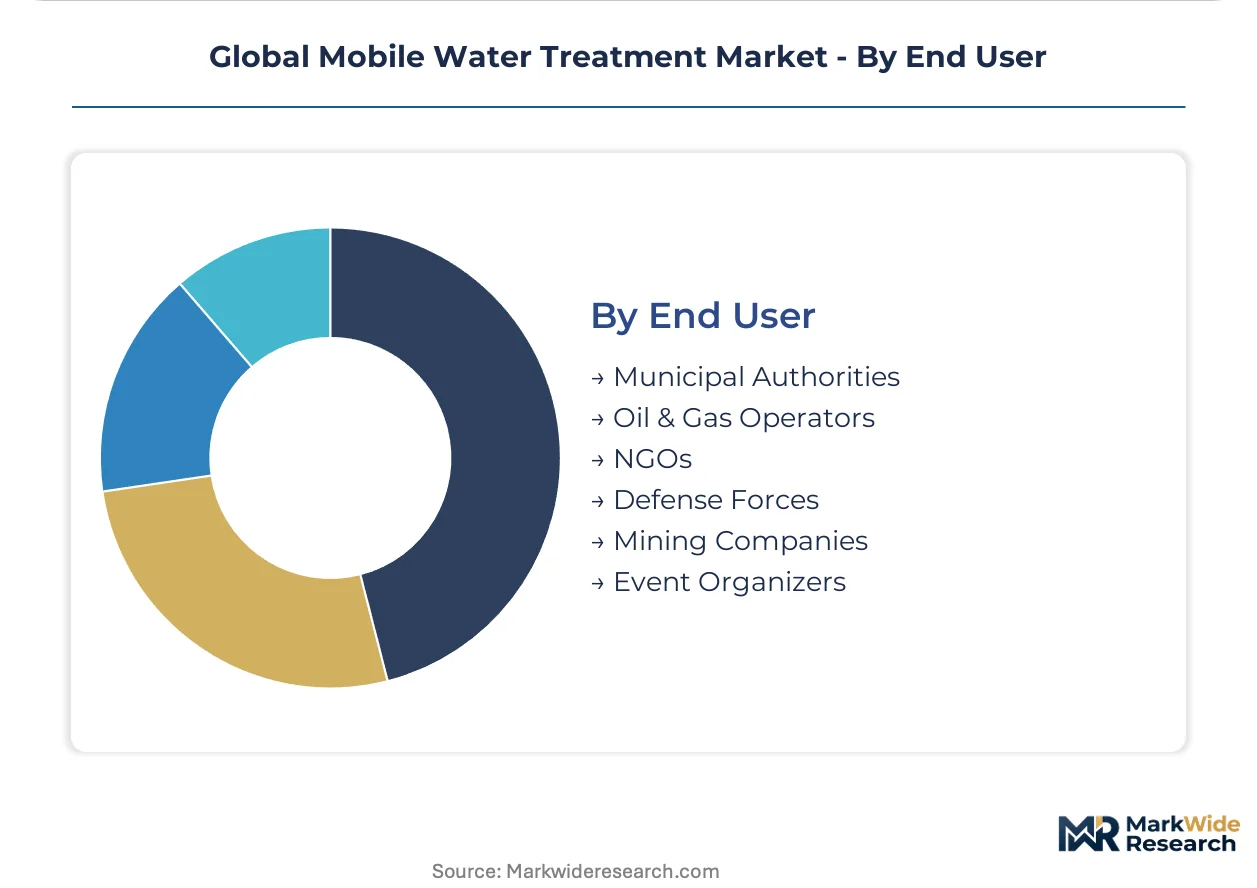
End User:
The organizational mandate and operational scale significantly influence the type and scale of mobile water treatment solutions procured by end users.
- Mining Companies:These entities require extensive water for mineral processing, dust suppression, and camp facilities, alongside robust wastewater treatment. Demand is concentrated in countries like Chile and Australia, driven by the critical need to sustain operations in water-stressed regions.
- Oil & Gas Operators:Need water for drilling, hydraulic fracturing, and managing produced water from extraction activities. Demand is concentrated in regions with active exploration and production, driven by environmental regulations for discharge and reuse.
- Municipal Authorities:Responsible for providing potable water and managing wastewater for public consumption within their jurisdictions.
- NGOs:Deploy mobile units to deliver emergency water supply and sanitation services for humanitarian aid and disaster relief efforts.
- Defense Forces:Ensure water security and supply for military personnel and operations in diverse and often challenging theaters.
- Event Organizers:Manage temporary water supply and sanitation infrastructure for large public gatherings, concerts, and sporting events.
Regulatory compliance heavily influences procurement by Municipal Authorities, while Mining Companies prioritize operational continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resource-rich nations like Australia and Chile drive significant mobile water treatment demand for remote site operations. These regions, acting as specialized economic zones for mineral extraction, heavily influence system procurement. Stricter environmental regulations compel industries to adopt advanced on-site treatment technologies.
United States
Demand for mobile water treatment in the United States stems from stringent effluent standards across industrial sectors. The US EPA's Effluent Limitation Guidelines compel industries to invest in advanced on-site treatment. Oil and gas regions in Texas and Louisiana require robust wastewater management for drilling and hydraulic fracturing. This drives demand for process water and produced water treatment.
Germany
Germany's industrial landscape drives demand for mobile water treatment, particularly in manufacturing and chemical sectors. The European Union's Water Framework Directive establishes legally binding water quality objectives, influencing system design. Industrial hubs like the Ruhr Area and Bavaria require flexible solutions for process water and effluent compliance. Advanced filtration systems are critical for operational continuity.
China
China experiences a surge in mobile water treatment demand due to rapid industrialization and acute water scarcity. The Ministry of Ecology and Environment (MEE) enforces stricter discharge standards, pushing industries towards advanced on-site solutions. Major industrial zones in the Yangtze River Delta and Pearl River Delta utilize mobile units for diverse manufacturing processes. This supports sustainable development in water-stressed areas.
Australia
Australia's expansive mining operations in remote, arid regions generate substantial demand for mobile water treatment. The National Water Quality Management Strategy mandates responsible water use and wastewater discharge for industrial activities. The Pilbara region in Western Australia relies heavily on containerized plants for process water and dust suppression. This ensures continuous operations in challenging environments.
Chile
Chile's booming copper mining industry, primarily in the Atacama Desert, creates critical demand for mobile water solutions. The country's environmental regulations prioritize water conservation and effluent quality in resource extraction. Northern mining regions utilize advanced reverse osmosis systems to produce potable and process water from brackish sources. This addresses severe water stress for continuous operations.
Global Mobile Water Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the mobile water treatment market. The landscape features a mix of large, diversified industrial conglomerates and specialized water technology providers. Strategic archetypes include global solution integrators offering comprehensive service networks and niche players focusing on rapid deployment systems. Portfolio diversification into advanced treatment technologies and strategic partnerships are dominant competitive moves.
Global solution providers like Veolia Water Technologies and SUEZ Water Technologies & Solutions exemplify the trend towards comprehensive service contracts and scalable systems. Veolia Water Technologies leverages its extensive service network for long-term projects, deploying containerized plants for industrial clients. SUEZ Water Technologies & Solutions competes with specialized trailer-mounted systems for rapid deployment at construction sites and emergency response. Xylem Inc., a prominent US-based company, occupies a position focused on addressing the entire water cycle, including advanced mobile treatment solutions for diverse applications. These entities offer advanced membrane technologies and integrated digital services for remote monitoring.
| Leading Market Players |
|---|
| Xylem Inc. |
| Pentair plc |
| Veolia Water Technologies |
| Danaher Corporation |
| Aquatech International |
| SUEZ Water Technologies & Solutions |
| Ecolab Inc. |
| GE Water & Process Technologies |
| Evoqua Water Technologies |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of key membrane technologies anchors the supply position for major players, influencing pricing power for advanced mobile water treatment solutions. This integration allows for better cost control and quality assurance in high-demand industrial applications.
Pricing Analysis
Premium pricing for short lead times rewards suppliers with readily deployable mobile units. Project-based pricing dominates the market, reflecting the customized nature of industrial deployments and disaster relief efforts. Price differentiation stems from the level of customization and the inclusion of comprehensive after-sales service. Pricing pressure stems from the high energy requirement of reverse osmosis systems, particularly in off-grid locations. Municipal authorities exhibit higher price sensitivity compared to mining companies prioritizing operational continuity.
Supply Chain Analysis
Domestic content mandates in countries like the United States and Germany are reshaping sourcing for mobile water treatment components. The supply chain for advanced membrane systems concentrates in specialized manufacturing hubs in Germany and the United States, alongside China for general components. Raw material dependencies include specialized polymers for membranes and various filtration media. Logistics chokepoints, particularly for large containerized units to remote sites, present a structural risk. Distribution runs through direct sales teams and specialized service networks for industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile water treatment market presents a significant cost-of-compliance story, with the European Union's Water Framework Directive creating a regulatory moat for compliant technology providers. This mandates advanced on-site treatment capabilities for industrial operations.
For Market Incumbents: Acquire specialized talent pools in digitalization and advanced materials science to counter emerging tech threats from niche players. Consolidate market share in key industrial segments, such as mining and oil & gas, by offering comprehensive service contracts that include remote monitoring and predictive maintenance. Invest in R&D for energy-efficient membrane technologies to mitigate operational cost pressures.
For New Entrants and Emerging Players: Launch via flexible leasing and rental models to penetrate construction and events industries with lower upfront capital requirements. Target underserved agricultural regions in North Africa with tailored mobile solutions for irrigation, leveraging advanced filtration for basic water quality improvement. Focus on niche applications like PFAS remediation, offering specialized mobile units with verified performance.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated solution providers offering end-to-end services, from deployment to operation and maintenance. The market offers long-term viability, driven by persistent water scarcity and increasingly stringent environmental regulations. Target acquisition archetypes include specialized technology developers focusing on ceramic membranes or digital integration platforms. A key signal to watch is the adoption rate of service-oriented contracts across new industrial segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Service Network | Veolia Water Technologies can enhance its global reach and rapid deployment capabilities across remote industrial sites. |
| Invest in Digitalization | Integrating IoT sensors allows SUEZ Water Technologies & Solutions to optimize system performance and offer predictive maintenance. |
| Develop PFAS Remediation Units | Xylem Inc. can capture a high-value niche market addressing contaminated industrial and military sites. |
| Advance Ceramic Membrane Tech | Evoqua Water Technologies can provide superior durability and chemical tolerance for challenging industrial wastewater streams. |
| Offer Flexible Leasing Models | Aquatech International can attract construction and events clients seeking temporary, cost-effective water infrastructure. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, providing a foundational understanding of market dynamics. Primary interviews with mining operations managers, environmental compliance officers, and water treatment engineers validated and refined these insights. Secondary data sources included government environmental reports, academic research papers, and company annual reports. This approach ensured bottom-up and top-down triangulation of market data.
Market granularity was modeled across technology type, application segment, deployment method, and end-user group over the projection horizon. Volume and value outputs reflect a triangulated approach, integrating current market size with projected growth drivers. Compound annual growth rates were derived from historical trends and anticipated regulatory impacts. Key forecast inputs included projected industrial water demand and the evolution of membrane filtration efficiency.
Shifts in global economic growth, unforeseen regulatory changes, and breakthroughs in water treatment technologies are the dominant revision risks for these forecasts. Forecasts reflect assumptions regarding industrial development and environmental policy enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Water Treatment Market