
 Deionized Water Systems Market | 2026-2036
Deionized Water Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Deionized Water Systems Market Analysis
Buyer concentration in the semiconductor sector is shifting as new fabs diversify procurement across regional system integrators rather than relying solely on established water service conglomerates. Veolia Water Technologies & Solutions leverages its electrodeionization expertise to anchor long-term service contracts with Asian chipmakers. Evoqua Water Technologies competes through modular skid-mounted systems that reduce installation timelines for pharmaceutical greenfield projects. Kurita Water Industries Ltd. dominates Japan's captive ultrapure water segment with chemically regenerated mixed-bed technologies tailored to display-panel manufacturing.
Deionized water systems remove dissolved ionic contaminants through ion-exchange resins, electrodeionization, or reverse-osmosis pre-treatment, achieving resistivity levels exceeding 18.2 megohm-cm for critical industrial processes. Electrodeionization systems are displacing chemically regenerated mixed-bed units in semiconductor fabs because continuous operation eliminates hazardous acid and caustic handling. Pharmaceutical production applications command premium pricing due to FDA validation requirements and redundant polishing loops, while power-generation deionization remains a mature, price-sensitive segment where refurbishment cycles extend equipment life.
The EPA enforces effluent limitation guidelines that compel coal and combined-cycle plants to install advanced demineralization, while China's MEE mandates zero-liquid-discharge standards for new industrial parks that integrate electrodeionization with crystallizers. ISO 14971 risk-management frameworks shape pharmaceutical water-system validation protocols across FDA and EMA jurisdictions. Stakeholders must monitor how semiconductor supply-chain regionalization reshapes service-network density requirements for spare resin inventories and field engineering capacity.
Market Dynamics
Electrodeionization technology is displacing chemically regenerated mixed-bed units across semiconductor fabs, eliminating hazardous acid and caustic handling while enabling continuous ultrapure water production. This technology shift compresses operational timelines and reshapes competitive positioning among system integrators and water service providers.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Coal and combined-cycle power plants face mandated upgrades to demineralization infrastructure, forcing utility procurement of advanced deionization systems.
- Semiconductor Fab Expansion:China, Taiwan, and South Korea are scaling captive ultrapure water capacity faster than any other buyer segment, driving electrodeionization demand.
- Zero-Liquid-Discharge Mandates:China's MEE requires new industrial parks to integrate electrodeionization with crystallizers, creating integrated system demand.
Market Restraints
- Ion-Exchange Resin Supply Concentration:Specialty resin production concentrates among a limited set of chemical manufacturers, exposing buyers to input cost volatility and lead-time risk.
- Capital Intensity of Validation:FDA and EMA pharmaceutical water-system protocols require redundant polishing loops and extensive documentation, extending payback periods.
- Power-Generation Price Sensitivity:Mature demineralization segments favor refurbishment cycles over new equipment purchases, compressing margins for original system suppliers.
Strategic Opportunities
- Battery Gigafactory Integration:Lithium-ion cell manufacturing requires high-purity water for electrolyte preparation, creating captive deionization plant demand in Germany and the United States.
- Service Contract Unbundling:Semiconductor fabs are separating equipment procurement from long-term resin regeneration and field engineering, opening margin pools for regional specialists.
- Modular Skid Standardization:Pre-engineered systems reduce pharmaceutical greenfield installation timelines, enabling faster market entry for mid-scale integrators.
Industry Challenges
- Field Engineering Capacity Scarcity:Semiconductor supply-chain regionalization requires denser service networks for spare resin inventories and emergency response, straining trained technician pools.
- ISO 14971 Validation Complexity:Pharmaceutical risk-management frameworks extend system commissioning timelines, delaying revenue recognition for project-based suppliers.
- Legacy Mixed-Bed Retrofit Integration:Existing chemically regenerated infrastructure requires complex piping and control system modifications to accommodate electrodeionization modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deionized Water Systems Market |
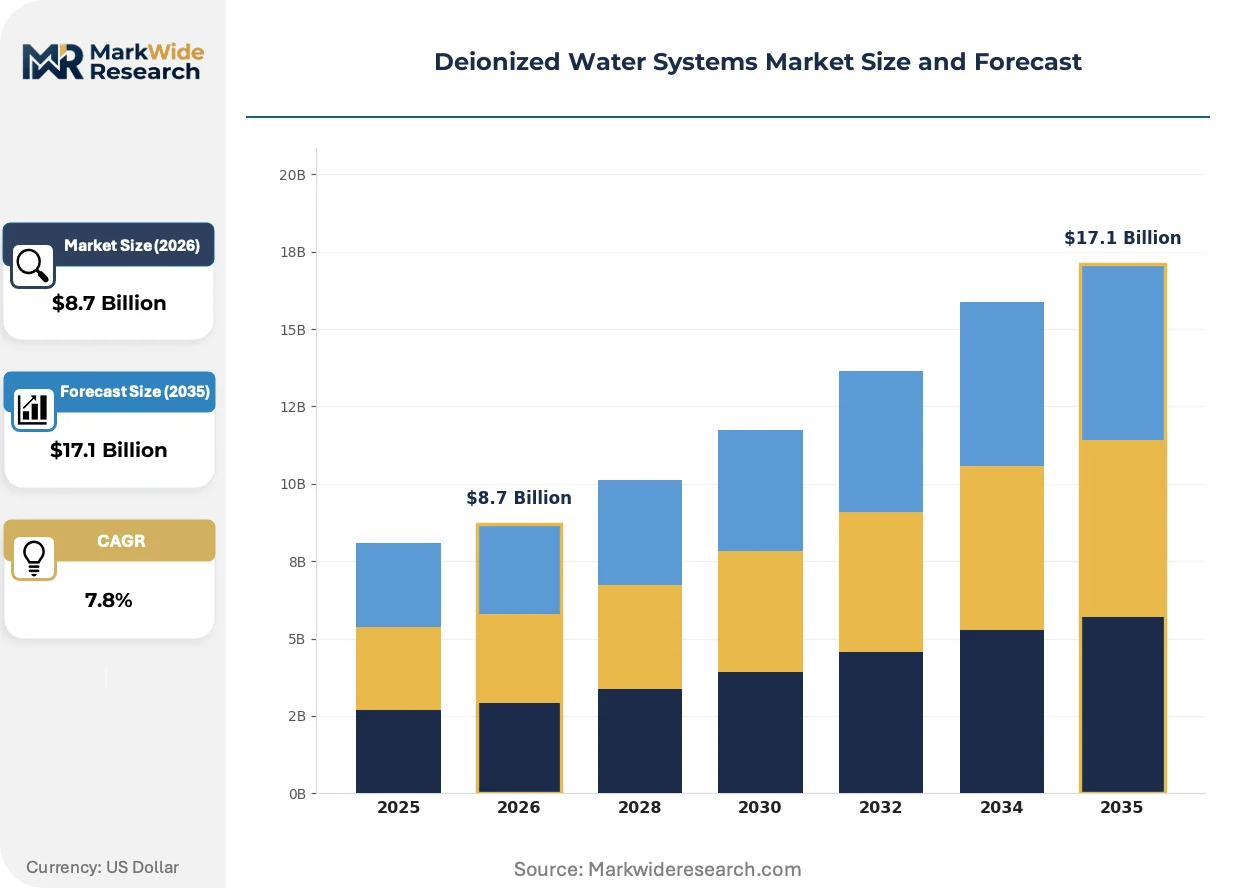
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Deionization, Batch Deionization, Electrodeionization, Mixed Bed Systems Application: Semiconductor Manufacturing, Pharmaceutical Production, Laboratory Use, Power Generation End User: Healthcare Institutions, Research Facilities, Industrial Plants, Educational Institutions Technology: Reverse Osmosis, Ion Exchange, Distillation, UV Purification |
| Companies Covered | Veolia Water Technologies & Solutions, Evoqua Water Technologies, Culligan Water, US Water Systems Inc., Nancrede Engineers Company Inc., Besco Water Treatment Inc., Puretec Industrial Water, Suez Water Technologies & Solutions, Kurita Water Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deionized Water Systems Market Emerging Trajectories
Continuous electrodeionization modules are reshaping how ultrapure water is produced, validated, and serviced across industrial end-uses. Three interconnected developments are compressing technology cycles and redrawing competitive boundaries.
Electrodeionization stacks combine ion-exchange membranes with direct current to remove dissolved ions without chemical regeneration. Semiconductor fabs in Taiwan and South Korea are adopting these systems at scale for sub-10nm process nodes. This technology is converging with predictive maintenance platforms to enable remote monitoring of membrane fouling and voltage efficiency degradation.
The EPA's tightened effluent limitation guidelines for power plants mandate advanced demineralization for coal and combined-cycle facilities. Utilities must install continuous electrodeionization or upgrade chemically regenerated systems to meet discharge limits. The power-generation segment is responding with extended refurbishment contracts that preserve existing infrastructure while adding polishing capacity.
Buyer concentration among Asian chipmakers is fragmenting procurement across regional system integrators rather than defaulting to established water service conglomerates. Long-term service contracts are unbundling from initial equipment sales, with fabs negotiating separate resin regeneration and field engineering agreements. This pattern is most visible in China's domestic foundry buildout, where captive water plants require localized spare parts inventories and Mandarin-speaking technical support.
Deionized Water Systems Market Segmentation
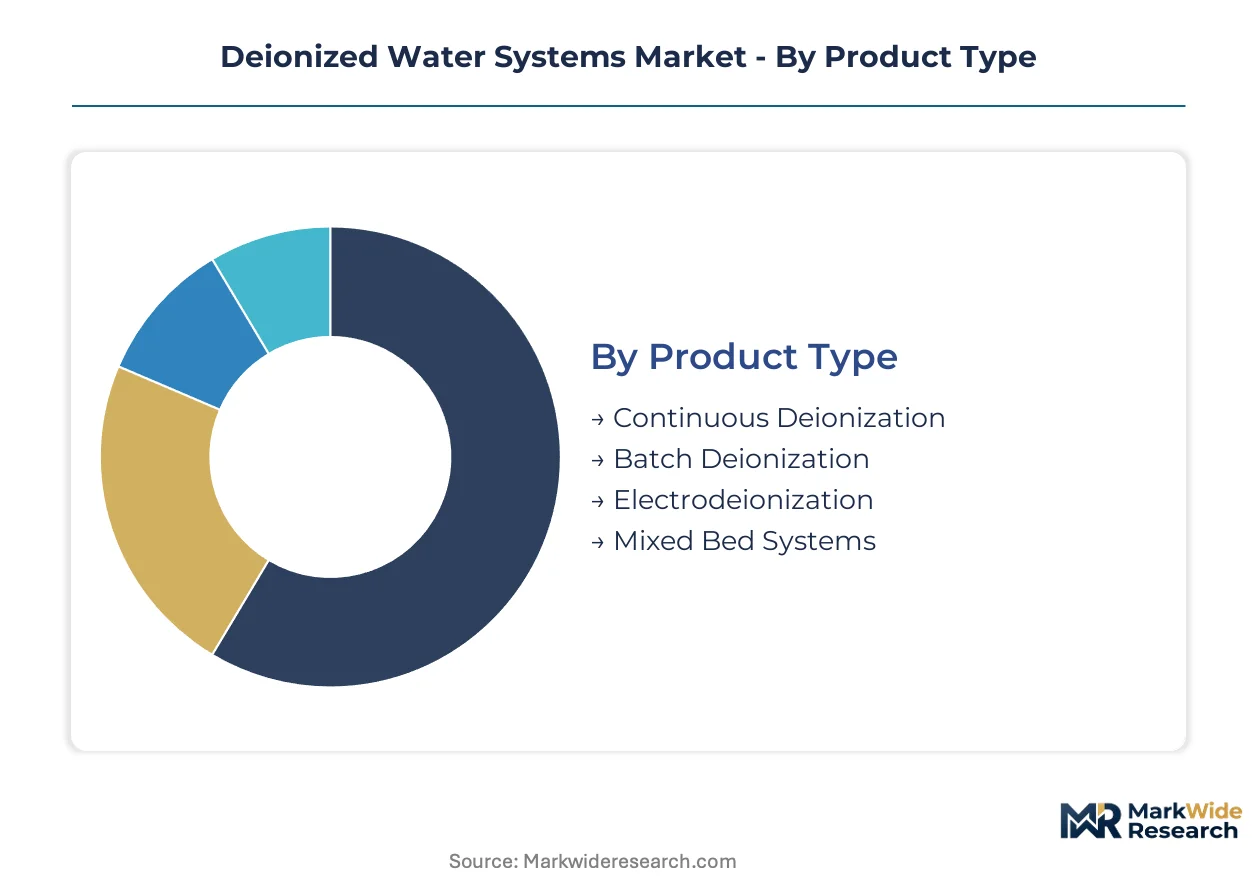
Deionized water systems serve radically different purity requirements across semiconductor fabs, pharmaceutical suites, and power plants. Segmentation reveals which technology configurations command validation premiums versus commodity refurbishment cycles.
Product Type:
FDA 21 CFR Part 211 validation burdens concentrate on continuous production systems, while EPA discharge compliance drives batch regeneration specifications.
- Electrodeionization:Combines ion-exchange membranes with direct current to remove dissolved ions without chemical regeneration. Semiconductor fabs in Taiwan and South Korea deploy these systems for sub-10nm process nodes where continuous ultrapure water supply eliminates downtime risk.
- Continuous Deionization:Integrates multiple purification stages in automated sequences for uninterrupted industrial supply. Pharmaceutical manufacturers in Germany and Switzerland specify these configurations to satisfy EMA Annex 1 validation protocols for water-for-injection production.
- Batch Deionization:Cyclic regeneration systems serving laboratory and small-scale industrial demand with lower capital requirements.
- Mixed Bed Systems:Chemically regenerated ion-exchange columns retaining installed base in mature power-generation infrastructure.
Leading the category by volume: Mixed Bed Systems. Growing fastest: Electrodeionization.
Application:
Application segmentation maps directly to margin tier, with semiconductor and pharmaceutical specifications commanding 3-5x pricing multiples over utility installations.
- Semiconductor Manufacturing:Requires resistivity exceeding 18.2 megohm-cm for wafer cleaning and chemical dilution. China's domestic foundry buildout in Shanghai and Hefei is scaling captive ultrapure water capacity faster than any other demand cluster.
- Pharmaceutical Production:FDA and EMA validation mandates redundant polishing loops and extensive documentation. Swiss and Irish drug manufacturing hubs specify electrodeionization with hot-water sanitization capabilities.
- Laboratory Use:Moderate-purity requirements for analytical chemistry and research protocols.
- Power Generation:Boiler feedwater demineralization subject to EPA effluent limitation guidelines, favoring refurbishment over new system procurement.
Highest margin concentration: Semiconductor Manufacturing. Steepest expansion trajectory: Pharmaceutical Production.
End User:
End user type determines procurement modality, with industrial plants favoring captive installations while research facilities rely on third-party service contracts.
- Industrial Plants:Captive deionization infrastructure integrated into manufacturing processes. Battery gigafactories in Germany and the United States are building dedicated ultrapure water plants for electrolyte preparation.
- Healthcare Institutions:Central sterile processing and laboratory diagnostics requiring validated water quality. Japanese university hospitals specify electrodeionization with endotoxin removal for dialysis applications.
- Research Facilities:Modular systems with flexible capacity for varying experimental protocols.
- Educational Institutions:Cost-sensitive installations prioritizing basic ion removal for teaching laboratories.
Dominant procurement volume: Industrial Plants. Fastest contract value growth: Healthcare Institutions.
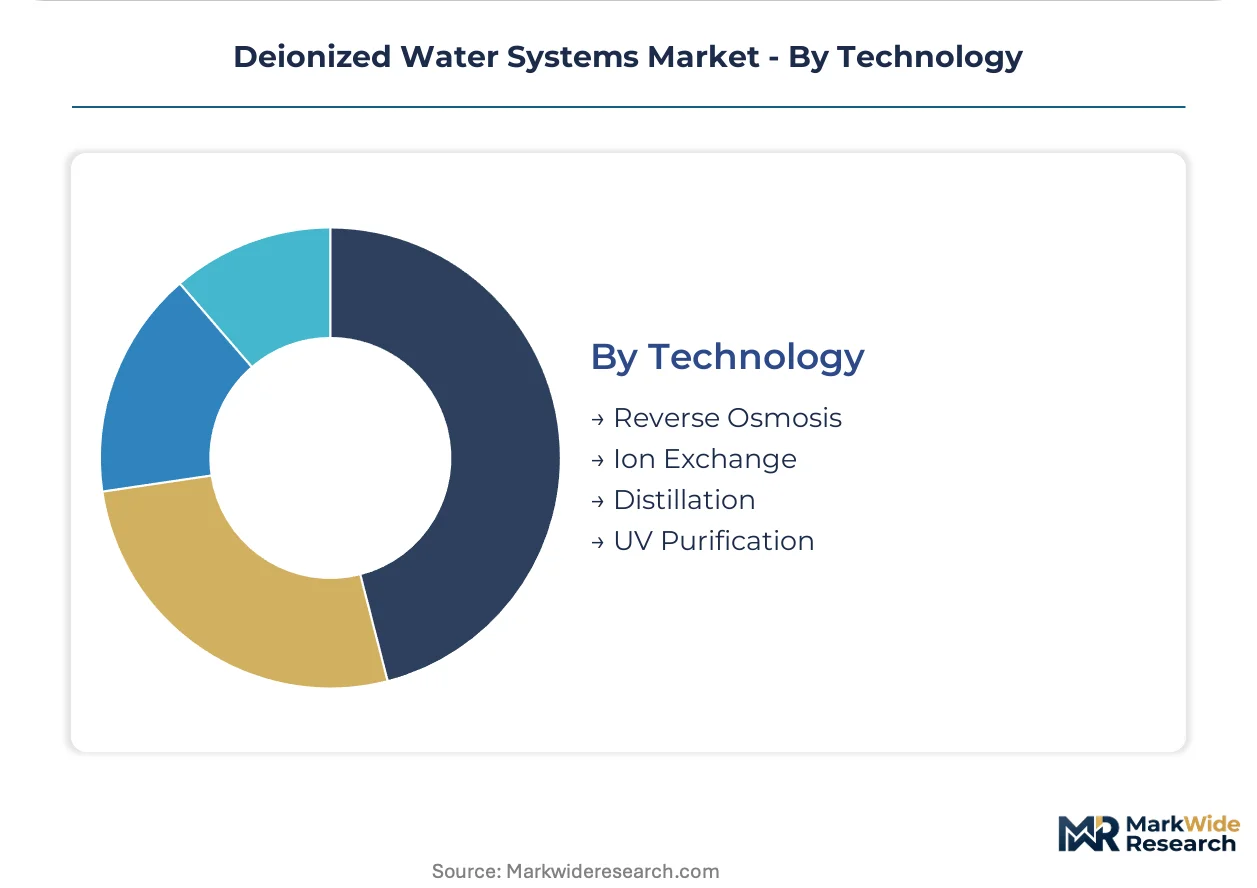
Technology:
Technology selection follows pretreatment requirements and final purity specifications, with reverse osmosis and ion exchange forming the dominant process sequence.
- Reverse Osmosis:Membrane-based pretreatment removing dissolved solids and organic contaminants. Semiconductor fabs integrate high-rejection RO modules upstream of electrodeionization to protect downstream resin from fouling.
- Ion Exchange:Resin-based ion removal achieving megohm-cm resistivity through cation and anion exchange. Specialty resin production concentrates among limited chemical manufacturers, exposing buyers to input cost volatility.
- Distillation:Thermal purification for pharmaceutical water-for-injection where pyrogen removal is mandatory.
- UV Purification:Oxidative degradation of organic compounds and microbial inactivation in polishing stages.
Most deployed in new installations: Reverse Osmosis. Fastest displacement rate: Ion Exchange losing share to electrodeionization modules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the fastest-scaling demand for deionized water systems, driven by domestic semiconductor foundries and battery gigafactories building captive ultrapure water capacity at unprecedented rates. This demand concentration reshapes regional procurement patterns and service-network requirements across the market.
United States
Coal and combined-cycle power plants drive demineralization upgrades under EPA effluent limitation guidelines. The EPA mandates advanced deionization infrastructure to meet tightened discharge standards. Texas and Arizona semiconductor clusters anchor electrodeionization demand for sub-10nm wafer fabrication.
China
Domestic chip foundries in Shanghai and Hefei scale captive ultrapure water plants faster than any other demand cluster. The MEE enforces zero-liquid-discharge standards for new industrial parks integrating electrodeionization with crystallizers. Yangtze River Delta battery gigafactories require high-purity water for electrolyte preparation.
Germany
Pharmaceutical manufacturers in Baden-Württemberg specify electrodeionization with hot-water sanitization for EMA Annex 1 compliance. The EU Green Deal accelerates industrial water recycling mandates. Bavarian automotive battery plants build dedicated deionization infrastructure for cell manufacturing.
Japan
Display-panel manufacturers in Osaka and Nagoya anchor demand for chemically regenerated mixed-bed technologies. METI industrial water standards shape system specifications for captive ultrapure water plants. Tokyo-area university hospitals specify electrodeionization with endotoxin removal for dialysis applications.
South Korea
Memory and logic chip fabs in Seoul Capital Area and Busan-Ulsan deploy continuous electrodeionization for sub-10nm process nodes. MFDS pharmaceutical water standards validate redundant polishing loop configurations. Daegu-Gyeongbuk industrial parks integrate electrodeionization with zero-liquid-discharge crystallizer systems.
Deionized Water Systems Market Vendor Landscape
European water service conglomerates anchor one tier; Asian specialists and North American modular fabricators hold differentiated positions in regional procurement networks. The vendor base stratifies across three archetypes: electrodeionization technology leaders, chemically regenerated mixed-bed incumbents, and modular skid-mounted system integrators. Consolidation pressures concentrate among resin regeneration service providers, while technology licensing agreements reshape competitive boundaries. Geographic expansion and strategic partnerships dominate competitive moves as fabs diversify procurement across regional integrators.
Among the established water service conglomerates, Veolia Water Technologies & Solutions and Suez Water Technologies & Solutions exemplify the European-anchored tier with electrodeionization expertise. Evoqua Water Technologies occupies a position representing North American modular system capabilities. Kurita Water Industries Ltd. anchors the Asian specialist archetype with Japan-based captive ultrapure water dominance. These three names illustrate how competitive positioning fragments across geographic and technological vectors.
| Leading Market Players |
|---|
| Veolia Water Technologies & Solutions |
| Evoqua Water Technologies |
| Culligan Water |
| US Water Systems Inc. |
| Nancrede Engineers Company Inc. |
| Besco Water Treatment Inc. |
| Puretec Industrial Water |
| Suez Water Technologies & Solutions |
| Kurita Water Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
China's zero-liquid-discharge mandates gate both qualified supply and premium-tier pricing access, as electrodeionization system integrators must demonstrate crystallizer integration capability to serve industrial park developers while commanding validation premiums from semiconductor fabs.
Pricing Analysis
The volume-vs-margin split separates pharmaceutical electrodeionization installations commanding certification premiums from power-generation mixed-bed refurbishment cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA validation burden, resistivity specification, and after-sales service bundling. Pricing pressure stems from resin cost volatility as specialty ion-exchange production concentrates among limited chemical manufacturers. Power utilities exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for continuous ultrapure water supply.
Supply Chain Analysis
Freight costs for specialty ion-exchange resins and electrodeionization membranes elevate landed costs for European and North American system integrators sourcing from Asian chemical manufacturers. Production concentrates in Japan, Germany, and the United States for high-purity resins, while membrane stacks draw from South Korea and Taiwan fabrication facilities. Single-source vulnerability concentrates in specialty anion resin grades essential for 18.2 megohm-cm output. Distribution runs through regional system integrators holding localized spare parts inventories for semiconductor fab service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with electrodeionization technology holders pursuing captive resin regeneration capabilities to capture unbundled service contract margins.
For Market Incumbents: Acquire regional field engineering networks to defend semiconductor fab service contracts against emerging Asian specialists. Secure long-term resin supply agreements with Japanese chemical manufacturers to mitigate input cost volatility. Anchor positioning through backward integration into membrane stack production. For New Entrants and Emerging Players: The premium-to-economy pricing gap in pharmaceutical water systems offers entry for modular skid fabricators with hot-water sanitization capabilities. Target mid-scale battery gigafactory installations in Germany and the United States where validation burdens remain lighter than semiconductor specifications. Pursue electrodeionization-leasing models to reduce capital barriers for captive industrial plants. For Investors and Strategic Acquirers: Semiconductor fab unbundling of equipment procurement from service contracts is the leading indicator that resin regeneration specialists will consolidate into platformed water service providers. Five-to-ten year viability favors vertically integrated operators spanning membrane production through field engineering. Monitor electrodeionization patent filing velocity from Chinese domestic foundry suppliers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Captures margin pools from electrodeionization stack manufacturing currently concentrated in South Korea. |
| Regional Field Engineering Network Expansion | Meets Mandarin-speaking technical support requirements from China's domestic foundry buildout in Shanghai and Hefei. |
| Resin Regeneration Service Platform | Consolidates fragmented aftermarket providers serving power-generation mixed-bed refurbishment cycles. |
| Modular Skid Standardization Program | Compresses pharmaceutical greenfield installation timelines for EMA Annex 1 validation protocols. |
| Crystallizer Integration Partnership | Addresses China's MEE zero-liquid-discharge mandates for new industrial park developments. |
Methodological Framework
Document review covered EPA effluent limitation guidelines, EMA Annex 1 validation protocols, and semiconductor industry water specifications, complemented by interviews with plant engineers at captive ultrapure water facilities, procurement leads at battery gigafactories, resin regeneration service operators, and electrodeionization system integrators. Secondary validation drew from MEE discharge standards filings, ISO 14971 risk-management documentation, and customs data for ion-exchange resin trade flows. Bottom-up demand modeling triangulated against top-down market sizing across technology and application segments.
Cross-referencing historical installation data against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology configuration, end-use purity specification, procurement modality, and regional regulatory cluster. CAGRs derived from unit economics analysis of electrodeionization versus mixed-bed total cost of ownership, incorporating resin replacement cycles and energy consumption trajectories. Forecast inputs incorporated semiconductor fab capacity expansion announcements and pharmaceutical manufacturing facility buildout pipelines.
Inputs from EPA and MEE regulatory filings were available through the study window; gaps in proprietary electrodeionization system performance data introduce uncertainty bands around technology displacement rate assumptions. Forecasts reflect documented assumptions regarding resin supply concentration and field engineering capacity scaling. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market