
 South America Water Treatment Chemicals Market | 2026-2036
South America Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Water Treatment Chemicals Market Analytics
NSF/ANSI 60-certified chemical grades is redrawing competitive thresholds across the South America Water Treatment Chemicals Market. Solenis leverages its captive polymer manufacturing network to secure specification-grade contracts with Brazilian pulp mills. Kemira sustains technical service density across Chilean mining water circuits, a segment where on-site dosing precision anchors long-term supply agreements. Ecolab dominates the food and beverage sanitation-linked water treatment channel through integrated hygiene-to-process-water protocols.
Water treatment chemicals comprise formulated active ingredients including cationic and anionic polymers, aluminum-based coagulants, and oxidizing biocides designed to remove suspended solids, control microbial fouling, and adjust pH in aqueous systems. These chemicals function through charge neutralization, flocculation bridging, and oxidative disinfection mechanisms to meet effluent discharge or potable intake standards. Coagulants occupy the largest volume position due to universal deployment across municipal clarification and industrial pretreatment stages, while biocides capture disproportionate margin pools in cooling tower and oilfield injection applications where microbial control failures carry high operational penalties. Cationic polymers lead growth in pulp and paper effluent treatment as Brazilian mills tighten suspended solids recovery to meet environmental licensing conditions.
ANVISA governs biocide registration and potable water contact safety for chemicals deployed in Brazilian public supply systems, creating multi-year approval timelines that filter out speculative suppliers. Brazil's CONAMA resolution standards for industrial effluent discharge and Chile's SMA environmental enforcement framework collectively elevate coagulant and flocculant dosage precision requirements, pushing end users toward technical-grade formulations over commodity alternatives. Peru's OEFA oversight of mining water management adds a third compliance layer for suppliers serving Andean extractive operations. Stakeholders must track how pending updates to Mercosur technical regulations on chemical migration limits will reshape cross-border formulation standards and testing burdens.
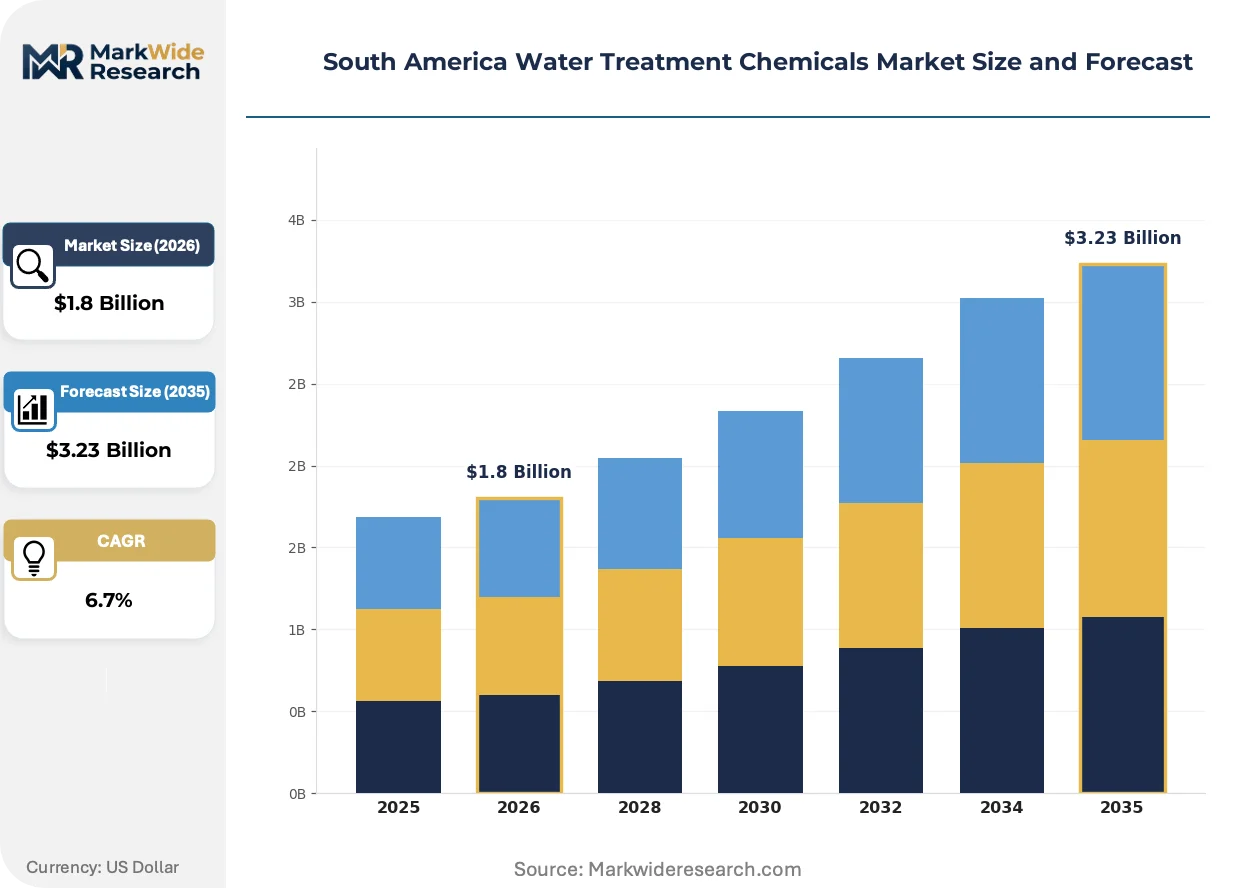
Market Dynamics
ANVISA's multi-year biocide registration timelines and CONAMA's tightening effluent standards are concentrating procurement power among technically credentialed suppliers across Brazilian municipal and industrial water systems.
Growth Catalysts
- ANVISA potable water resolutions:Tightening biocide efficacy requirements are filtering out speculative suppliers and rewarding formulation-grade manufacturers with approved registrations.
- Southeastern industrial corridor expansion:São Paulo and Minas Gerais states are driving concentrated chemical procurement for pulp mill effluent treatment and mining water circuits.
- Cationic polymer technology:Brazilian mills are deploying advanced flocculants to meet environmental licensing conditions for suspended solids recovery.
Market Restraints
- Alumina and caustic soda price volatility:Input cost swings for aluminum-based coagulants compress margin pools for commodity-grade suppliers serving price-sensitive municipal utilities.
- Multi-year ANVISA approval cycles:Registration friction creates structural barriers to market entry for new biocide formulations targeting public supply systems.
- Commodity polymer substitution:Unformulated bulk polymers from Asian suppliers threaten specification-grade margins in less regulated industrial segments.
Strategic Opportunities
- Chilean mining water circuits:SMA enforcement and copper extraction expansion create demand for precision dosing systems and on-site technical service density.
- Peruvian Andean operations:OEFA oversight of mining water management opens procurement channels for compliant coagulant and flocculant suppliers.
- Mercosur technical regulation convergence:Pending chemical migration limit harmonization will reshape cross-border formulation standards and testing burdens.
Industry Challenges
- NSF/ANSI 60 certification timelines:Third-party potable water contact safety testing creates operational bottlenecks for suppliers seeking Brazilian municipal specification.
- Legacy dosing infrastructure:Aging chemical feed systems at Brazilian utilities complicate precision delivery of advanced polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Water Treatment Chemicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cationic Polymers, Anionic Polymers, Coagulants, Biocides End Use Industry: Textile, Pulp & Paper, Food & Beverage, Oil & Gas Application: Wastewater Treatment, Drinking Water Treatment, Industrial Water Treatment, Process Water Treatment Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Solenis, Ecolab, Kemira, Kurita Water Industries Ltd., Suez, BASF, Nouryon, Solvay, Lonza, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Water Treatment Chemicals Market Evolving Landscape
Formulation chemistry and service delivery models are evolving in response to regulatory precision requirements and end-user demands for operational reliability rather than commodity supply.
High-molecular-weight cationic polymers with tailored charge density profiles are supplanting conventional alum coagulants in Brazilian pulp mill effluent treatment. Mills in São Paulo state are adopting these polymers at accelerating rates to meet CONAMA resolution suspended solids limits. The shift is compressing volume demand for commodity aluminum sulfate while expanding margin pools for specification-grade flocculant suppliers.
ANVISA's updated biocide registration framework is extending approval timelines and elevating efficacy documentation requirements for chemicals deployed in public water supply systems. The regulatory tightening is favoring incumbent suppliers with established technical dossiers and filtering out speculative market entrants. Municipal utilities across Brazil's southeastern states are responding by consolidating procurement around pre-qualified formulation houses.
Technical service contracts bundling chemical supply with on-site dosing optimization are displacing transactional bulk chemical purchasing in Chilean mining operations. Copper and lithium extractors are unbundling procurement from equipment maintenance and awarding integrated water management agreements to qualified suppliers. The model is most visible in Antofagasta Region operations where SMA enforcement elevates precision requirements.
South America Water Treatment Chemicals Market Segmentation
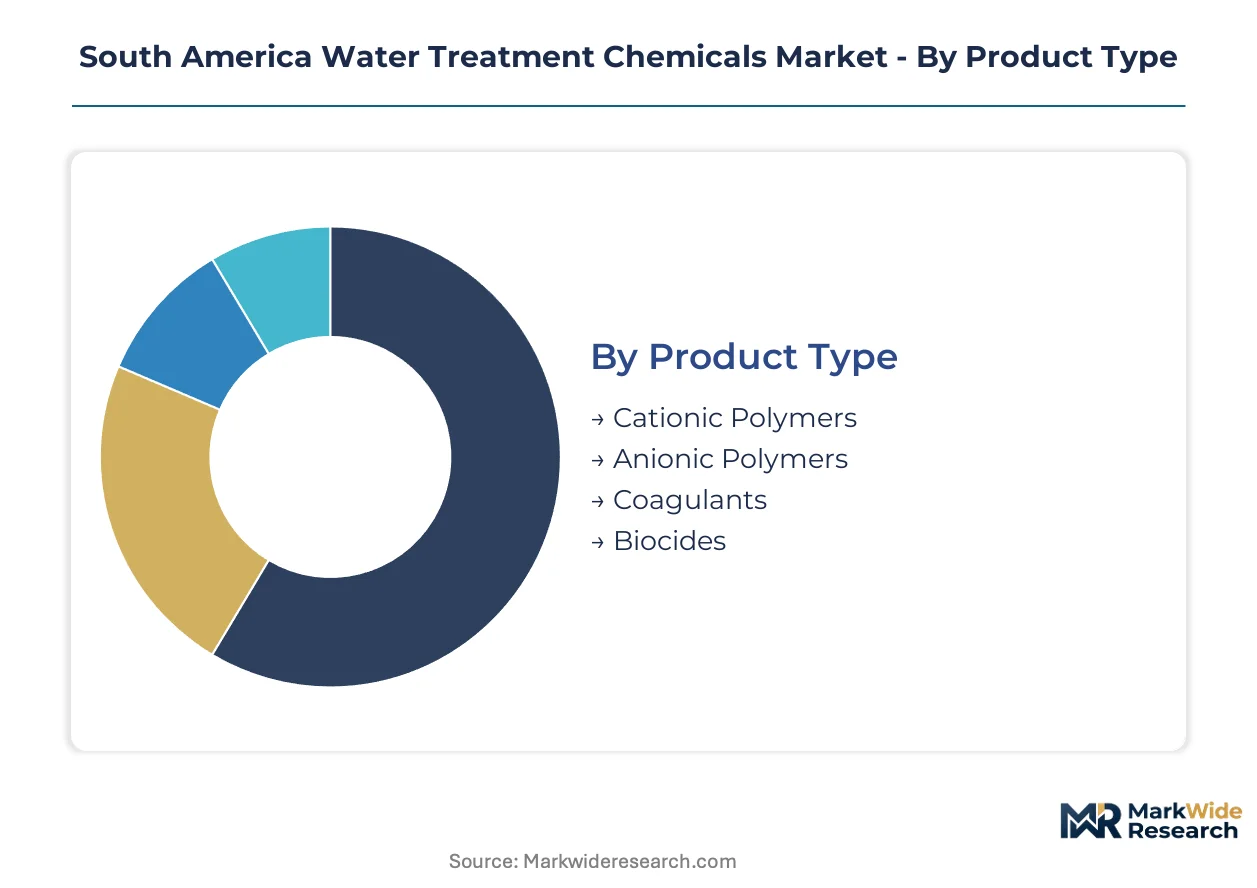
Segmentation reveals where formulation-grade suppliers defend margin pools against commodity substitution and which channels concentrate procurement power among technically credentialed vendors.
Product Type:
Coagulants face the most acute substitution pressure from unformulated bulk polymers, while biocides remain protected by ANVISA registration barriers.
- Cationic Polymers:High-molecular-weight flocculants with tailored charge density profiles enable suspended solids recovery in Brazilian pulp mill effluent. São Paulo state mills deploy these polymers to meet CONAMA resolution limits, displacing conventional alum in clarification stages.
- Coagulants:Aluminum-based formulations including aluminum sulfate and polyaluminum chloride serve universal municipal clarification and industrial pretreatment. Brazilian utilities in Minas Gerais specify technical-grade variants despite price sensitivity to alumina input volatility.
- Anionic Polymers:Negatively charged flocculants target mineral processing and mining tailings dewatering in Chilean copper operations.
- Biocides:Oxidizing and non-oxidizing antimicrobial formulations for cooling towers and oilfield injection systems require ANVISA registration for potable water contact.
Coagulants anchor the volume base while cationic polymers gain share at the steepest rate.
End Use Industry:
Customer concentration varies sharply across cost tiers, with mining and pulp operations demanding precision service while food and beverage prioritizes integrated hygiene protocols.
- Pulp & Paper:Brazilian mills in the southeastern corridor drive specification-grade polymer consumption for effluent suspended solids compliance. Environmental licensing conditions tighten recovery requirements, favoring advanced flocculant formulations over commodity alternatives.
- Oil & Gas:Produced water treatment and injection biocide applications in Brazil's pre-salt fields demand on-site dosing precision. Operational penalties for microbial fouling failures sustain premium pricing for registered formulations.
- Food & Beverage:Process water sanitation requirements link chemical procurement to integrated hygiene protocols across Brazilian bottling and processing facilities.
- Textile:Dyehouse effluent decolorization and COD reduction applications in São Paulo state's industrial clusters utilize coagulant-flocculant combinations.
Pulp & Paper commands the deepest technical service integration while Oil & Gas delivers the highest per-ton margin realization.
Application:
Volume distribution tracks regulatory enforcement intensity, with wastewater and drinking water applications facing the most stringent compliance verification.
- Wastewater Treatment:Industrial effluent clarification and municipal sewage processing deploy coagulants and polymers for solids removal. CONAMA resolution standards elevate dosage precision requirements across Brazilian discharge permits.
- Drinking Water Treatment:Potable clarification and disinfection applications require ANVISA-registered biocides and NSF/ANSI 60-certified coagulants. Municipal utilities in Brazil's southeastern states consolidate procurement around pre-qualified suppliers.
- Industrial Water Treatment:Cooling tower biocide programs and boiler water conditioning serve manufacturing facilities across Chile's mining and industrial corridors.
- Process Water Treatment:Food and beverage sanitation-linked applications integrate chemical dosing with hygiene protocols.
Wastewater Treatment absorbs the largest chemical volumes while Drinking Water Treatment imposes the steepest certification barriers to supplier entry.
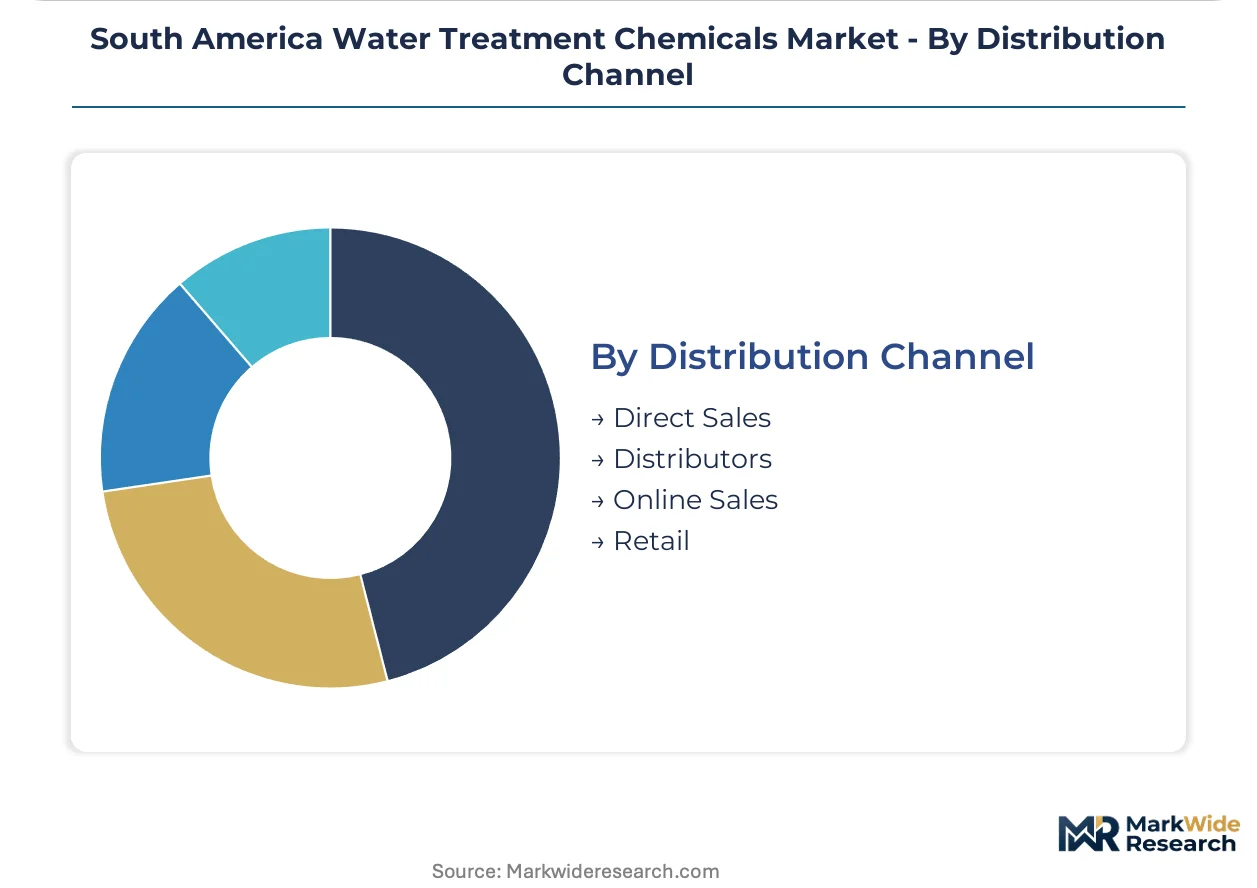
Distribution Channel:
Channel selection reflects customer scale and technical complexity, with direct relationships dominating where dosing optimization requires on-site service density.
- Direct Sales:Technical service contracts bundling chemical supply with dosing system optimization serve Chilean mining operations and Brazilian pulp mills. SMA enforcement and environmental licensing elevate precision requirements that favor integrated supplier relationships.
- Distributors:Regional chemical distributors serve mid-sized industrial accounts and municipal utilities with standardized formulation requirements across Brazil's interior states.
- Online Sales:E-procurement platforms capture commodity polymer and standard biocide replenishment for smaller industrial facilities with established specification parameters.
- Retail:Point-of-sale channels address maintenance-scale biocide and pH adjustment chemical needs for small commercial water systems.
Direct Sales commands the highest service-integrated revenue per account while Distributors extend geographic coverage most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in water treatment chemicals across South America tilt toward formulation-grade imports from North American and European suppliers, while domestic production concentrates in Brazil's southeastern chemical corridor. Regional trade patterns reflect regulatory barriers that favor pre-certified suppliers over commodity traders.
Brazil
Municipal utilities in São Paulo and Minas Gerais states drive procurement volume for ANVISA-registered biocides and NSF/ANSI 60-certified coagulants. CONAMA resolution standards for industrial effluent discharge tighten dosage precision requirements across pulp mill operations. The southeastern industrial corridor spanning São Paulo state's metropolitan region concentrates demand for advanced polymer formulations in effluent clarification systems.
Chile
Copper and lithium extractors in the Antofagasta Region deploy precision dosing systems for mining water circuits under SMA environmental enforcement. Technical service contracts bundling chemical supply with on-site optimization displace transactional purchasing. Northern mining districts anchor procurement for anionic polymers in tailings dewatering applications.
Argentina
Pulp producers in the Mesopotamia region utilize coagulant-flocculant combinations for effluent treatment amid provincial environmental licensing conditions. Municipal water systems in Buenos Aires province specify imported technical-grade formulations over domestic commodity alternatives. The Paraná River industrial corridor sustains demand for drinking water clarification chemicals.
Peru
OEFA oversight of mining water management creates compliance layers for coagulant suppliers serving Andean extractive operations. Cerro de Pasco and Ancash region concentrators require precision flocculant dosing for acid mine drainage treatment. Central highland mining districts concentrate procurement for pH adjustment and heavy metals precipitation chemicals.
Colombia
Oilfield water treatment in the Llanos Basin drives biocide consumption for produced water injection systems. Regional environmental authorities tighten discharge standards for refinery and petrochemical effluents. The Magdalena River valley industrial corridor sustains demand for municipal coagulants in mid-sized city water systems.
South America Water Treatment Chemicals Market Competitive Landscape
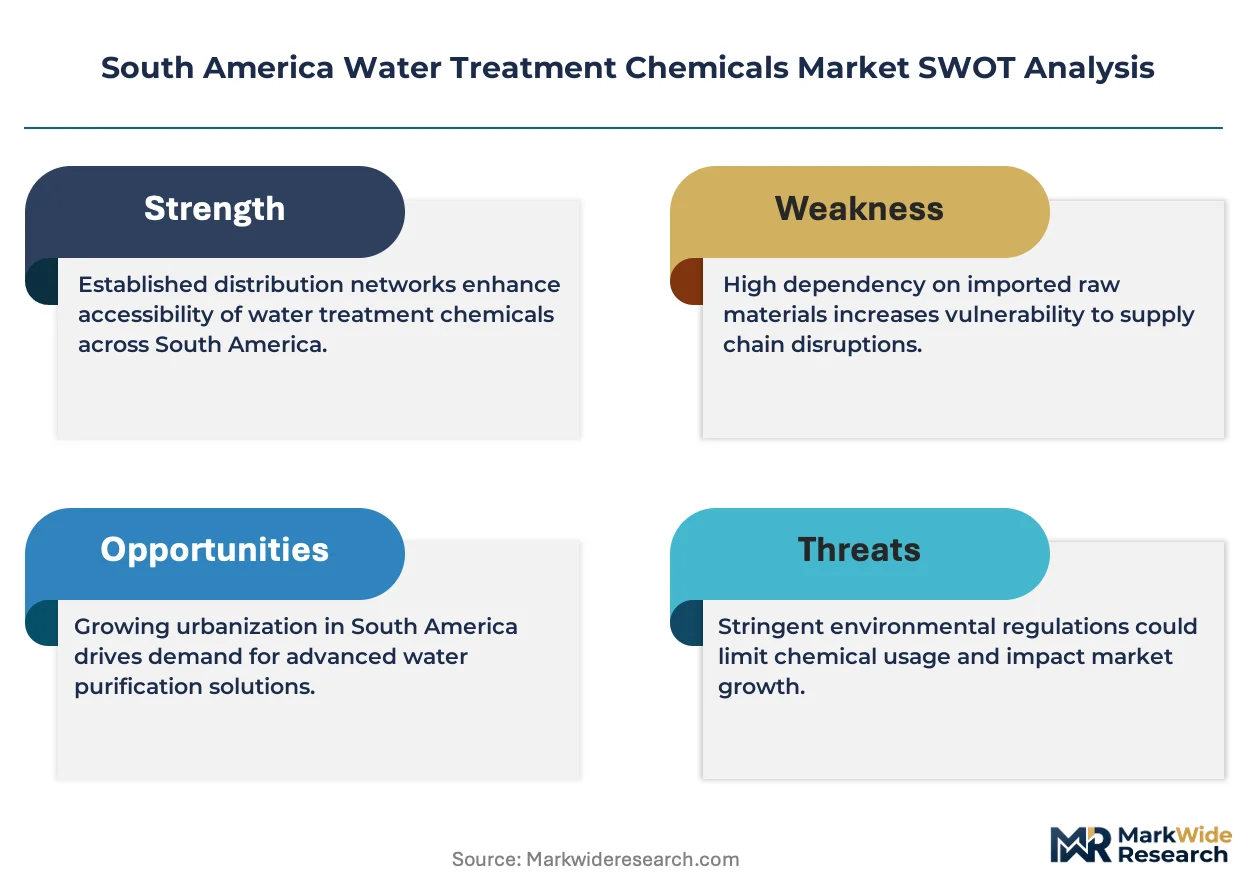
Concentration sits with multinational formulation houses possessing ANVISA registrations and NSF/ANSI 60 certifications that commodity traders cannot replicate. Three archetypes dominate: integrated water management providers bundling chemicals with equipment service, specification-grade polymer manufacturers with captive resin production, and regional distributors serving price-sensitive municipal accounts with standardized formulations. Competitive moves center on technical service contract expansion and backward integration into polymer resin manufacturing.
Among the integrated service providers, Solenis, Ecolab, and Kemira exemplify the technical-credentialing archetype that Brazilian pulp mills and Chilean mining operators favor for long-term supply agreements. These entities occupy positions where on-site dosing precision and regulatory dossier depth anchor procurement decisions. Solenis represents the captive manufacturing model with polymer production control, while Ecolab anchors the hygiene-to-process-water integration channel, and Kemira sits within the mining-specialized technical service tier.
| Leading Market Players |
|---|
| Solenis |
| Ecolab |
| Kemira |
| Kurita Water Industries Ltd. |
| Suez |
| BASF |
| Nouryon |
| Solvay |
| Lonza |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day ANVISA registration timelines for biocide formulations compress inventory buffers at Brazilian municipal utilities, concentrating procurement leverage among pre-qualified suppliers while amplifying price premiums for specification-grade coagulants over commodity alternatives. This lead-time rigidity forces utilities into long-term offtake contracts that insulate incumbent formulation houses from spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across the South America Water Treatment Chemicals Market. Three-tier pricing separates ANVISA-registered biocides from NSF/ANSI 60-certified coagulants from unformulated bulk polymers, with certification grade and technical service bundling as the primary differentiation drivers. Cost compression in commodity aluminum sulfate is intensifying because alumina and caustic soda input volatility, while municipal utilities in Brazil's interior states exhibit the sharpest price sensitivity against mining operators in Chile's Antofagasta Region.
Supply Chain Analysis
Strategic stockpile preferences dominate among Chilean mining operators confronting SMA enforcement deadlines, while Brazilian pulp mills run leaner just-in-time polymer inventories tied to environmental licensing timelines. Manufacturing concentration rests on Brazil's southeastern chemical corridor, U.S. Gulf Coast polymer resin complexes, and German specialty chemical production hubs. Raw material dependencies center on alumina feedstock, acrylamide monomer, and oxidizing biocide precursors. Single-source vulnerability from Asian bulk polymer suppliers threatens specification-grade margins. Distribution runs through direct technical service contracts for large industrial accounts and regional chemical distributors for mid-tier municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility procurement consolidation across Brazil's southeastern states is shifting buyer power toward technically credentialed suppliers with ANVISA dossiers, fragmenting price competition among commodity-grade vendors.
For Market Incumbents: Compound technical service density in Chilean mining circuits and captive polymer manufacturing control to defend against unformulated Asian bulk polymer substitution. Backward integration into acrylamide monomer production secures margin pools against raw material volatility. For New Entrants and Emerging Players: Anchor in Peruvian Andean mining operations under OEFA oversight where compliance layering has filtered incumbent concentration, and target mid-sized Brazilian municipal utilities in Minas Gerais interior districts underserved by technical service teams. A distributor partnership model with standardized NSF/ANSI 60-certified formulations offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates divesting non-core water treatment divisions lacking regional ANVISA registrations. Long-term viability hinges on regulatory credential moats deepening over multi-year approval cycles. Watch ANVISA biocide registration queue backlogs as the inflection signal for supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captive acrylamide production shields Brazilian suppliers from Asian monomer price volatility. |
| ANVISA Registration Expansion | Extended biocide dossiers filter speculative entrants from public supply system procurement. |
| Technical Service Contract Bundling | On-site dosing optimization anchors long-term agreements at Chilean copper extractors. |
| NSF/ANSI 60 Certification Investment | Third-party potable water safety testing unlocks municipal utility specification in São Paulo. |
| Regional Distributor Network Strengthening | Geographic coverage extension captures mid-tier industrial accounts in Brazil's interior states. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility procurement managers, pulp mill environmental compliance officers, mining water circuit engineers, and specialty chemical distribution executives. Secondary validation drew from ANVISA registration databases, CONAMA resolution filings, Brazilian customs trade statistics, and SEC 10-K disclosures of multinational formulation houses. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across the analysis window.
Across the modeling period, forecasts segment by product type grade tier, end-use industry concentration, application regulatory intensity, and regional enforcement framework cluster. CAGRs were derived from trend extrapolation of historical procurement volumes adjusted for pending Mercosur technical regulation convergence. Industry-specific inputs include ANVISA approval pipeline velocity and SMA enforcement incident rates in Chilean mining districts.
Material uncertainties — alumina price volatility spikes, ANVISA registration timeline extensions, Asian bulk polymer import surges — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and raw material supply stability. Revision becomes warranted when CONAMA resolution suspended solids limits tighten beyond current licensing conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market