
 Global Wood Activated Carbon Market | 2026-2036
Global Wood Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Activated Carbon Market Foresight
Modular bulk-supply contracts with on-site reactivation services is hardening as the dominant procurement configuration for municipal buyers. Cabot Corporation leverages its North American reactivation network to anchor long-term utility partnerships. Kuraray Co. Ltd. sustains premium positioning through specialized pharmaceutical-grade production. Jacobi Carbons competes on global distribution density across emerging water treatment markets.
Wood activated carbon consists of carbonaceous material derived from hardwood or softwood feedstocks, thermally processed to create internal pore structures ranging from micropores (<2 nm) to mesopores (2–50 nm) for contaminant adsorption. Steam activation at 800–1,000°C remains the predominant manufacturing route, yielding products with iodine numbers between 800–1,200 mg/g for liquid-phase applications. Granular configurations occupy the largest volume share due to fixed-bed reactor compatibility in municipal water treatment systems. Powdered grades command margin premiums in food and beverage decolorization where rapid kinetics justify higher dosing costs. Chemical activation using phosphoric acid produces specialized grades with enhanced mesopore distribution for air purification and volatile organic compound capture.
The EPA Safe Drinking Water Act and EU Drinking Water Directive establish contaminant thresholds that directly expand activated carbon replacement cycles in municipal infrastructure. Japan's Ministry of Health, Labour and Welfare maintains stringent pharmaceutical adsorbent purity standards that filter market access for uncertified suppliers. Indonesia's Ministry of Environment and Forestry regulates sustainable feedstock sourcing for carbon producers serving export markets. Stakeholders must monitor tightening per- and polyfluoroalkyl substances limits across multiple jurisdictions, as these emerging contaminants require activated carbon system upgrades or alternative adsorbent deployment decisions.
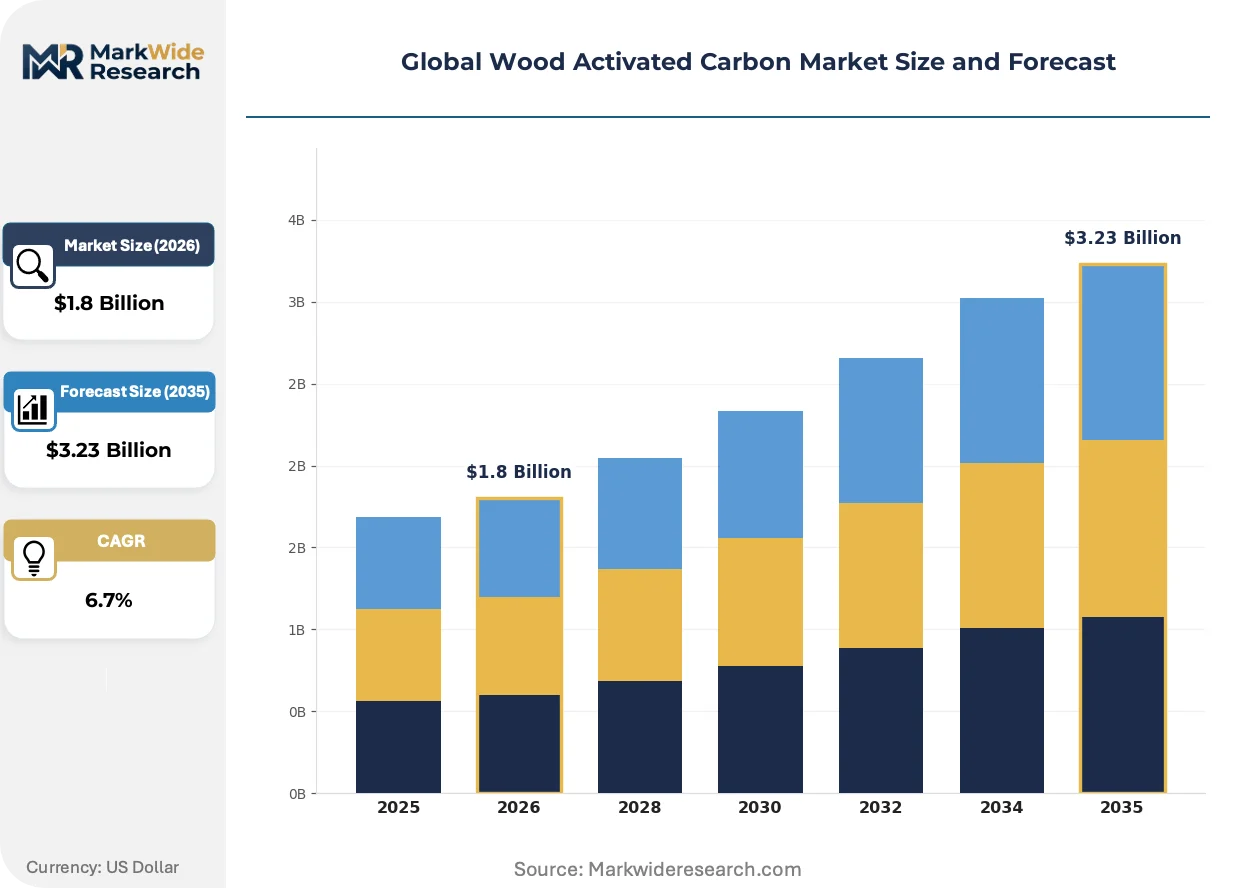
Market Dynamics
Modular bulk-supply contracts with on-site reactivation services are hardening as the dominant procurement configuration for municipal buyers, compressing traditional spot-market purchasing and locking in multi-year utility partnerships.
Growth Catalysts
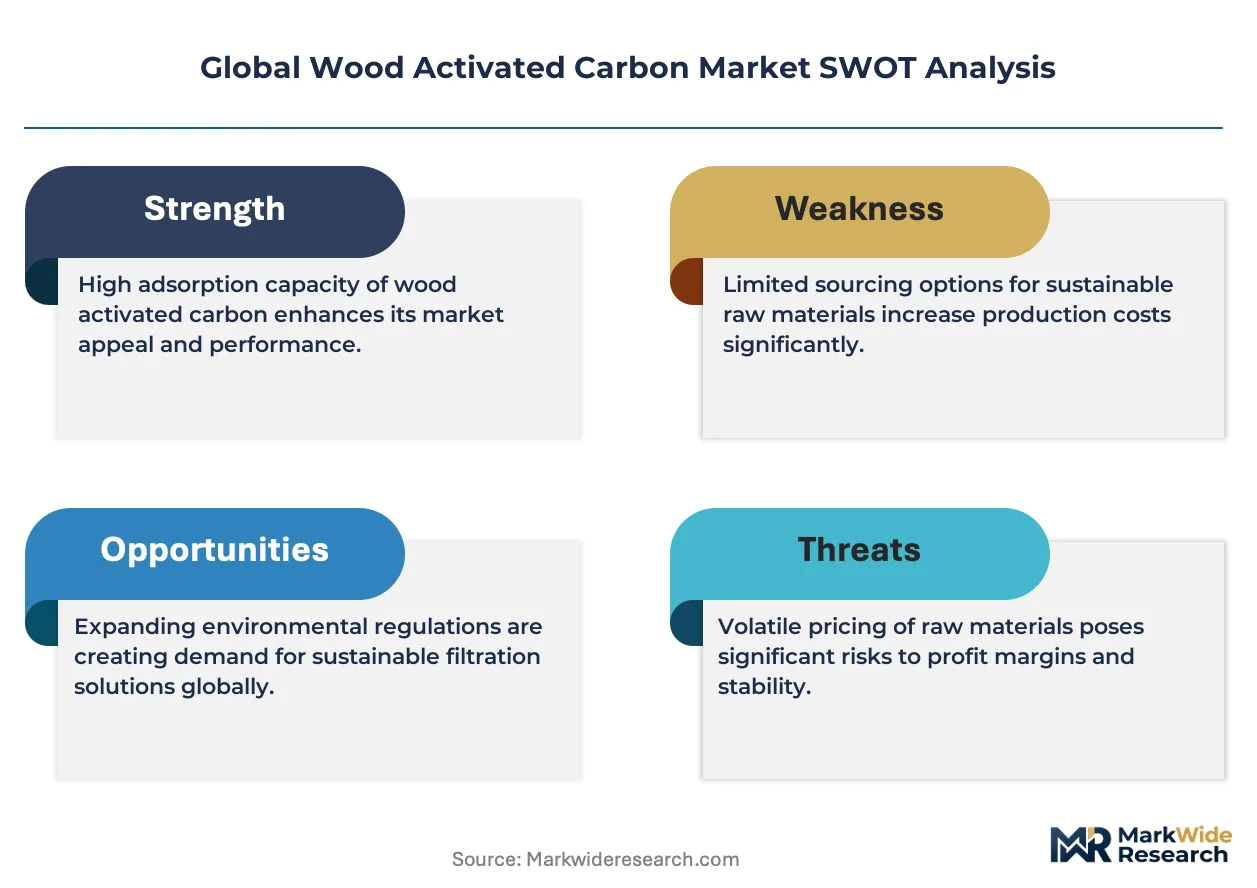
- EU REACH regulation:Chemical adsorbent safety mandates are accelerating substitution toward certified wood-based grades, displacing coal-derived alternatives in European water treatment infrastructure.
- Per- and polyfluoroalkyl substances limits:Tightening thresholds across US EPA Safe Drinking Water Act jurisdictions require activated carbon system upgrades for municipal compliance.
- Southeast Asia pulp-to-carbon integration:Indonesia and Vietnam are maturing regional supply chains that reduce feedstock transport costs and improve export competitiveness.
Market Restraints
- Hardwood feedstock volatility:Sustainable forestry certification requirements under Indonesia's Ministry of Environment and Forestry regulations constrain raw material flexibility for export-oriented producers.
- Steam activation energy intensity:Thermal processing at 800–1,000°C creates exposure to natural gas price swings that compress margins for non-integrated manufacturers.
- Coconut shell carbon substitution:Competing vegetable-based activated carbons with established food-grade certifications limit wood-based penetration in premium decolorization applications.
Strategic Opportunities
- Vietnam municipal water expansion:Provincial utilities are scaling activated carbon filtration capacity to meet tightening potable water standards with limited domestic supplier competition.
- Pharmaceutical-grade mesopore tailoring:Chemical activation using phosphoric acid enables specialized grades for volatile organic compound capture in air purification systems.
- Japan pharmaceutical adsorbent certification:Ministry of Health, Labour and Welfare purity standards create premium positioning for qualified suppliers in high-margin medical applications.
Industry Challenges
- Reactivation technician scarcity:On-site carbon regeneration services require specialized field engineering capabilities that outpace vocational training pipeline output.
- Multi-jurisdiction PFAS compliance:Divergent emerging contaminant limits across EPA, EU Drinking Water Directive, and prefectural Japanese standards fragment product certification requirements.
- Legacy fixed-bed reactor incompatibility:Municipal infrastructure upgrade cycles lag behind granular carbon performance improvements, delaying premium product adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Activated Carbon Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powdered, Pellets, Extruded Activation Method: Chemical, Steam, Phosphoric Acid, Potassium Hydroxide End Use Industry: Water Treatment, Air Purification, Food & Beverage, Pharmaceuticals, Petrochemicals Application: Adsorption, Decolorization, Deodorization, Catalyst Support |
| Companies Covered | Cabot Corporation, Calgon Carbon Corporation, Kuraray Co. Ltd., Jacobi Carbons, Osaka Gas Co. Ltd., Haycarb PLC, Donau Carbon GmbH, Silcarbon Aktivkohle GmbH, CarboTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Activated Carbon Market Shifts & Advancements
Technology convergence and regulatory tightening are compressing product lifecycles while opening premium niches for certified grades. Three developments are restructuring competitive positioning.
Containerized reactivation units are decentralizing carbon lifecycle management for municipal utilities. These skid-mounted systems allow on-site regeneration of spent granular carbon, eliminating transport costs and hazardous waste liabilities. European water treatment operators are piloting distributed models that reduce supply chain vulnerability.
REACH chemical adsorbent safety protocols are mandating feedstock traceability and reactivation documentation for wood-based grades entering EU markets. The regulation forces coal-carbon incumbents to retrofit certification systems or cede share to pre-qualified wood suppliers. German municipal procurement frameworks now specify renewable-origin carbon in technical specifications.
Utility buyers are consolidating vendor relationships around full-service contracts bundling supply, reactivation, and compliance reporting. This displaces fragmented spot purchasing through distributors. Indonesian and Vietnamese regional champions are capturing these integrated contracts by leveraging captive pulp feedstock and proximity to Southeast Asian water infrastructure investment.
Global Wood Activated Carbon Market Segmentation
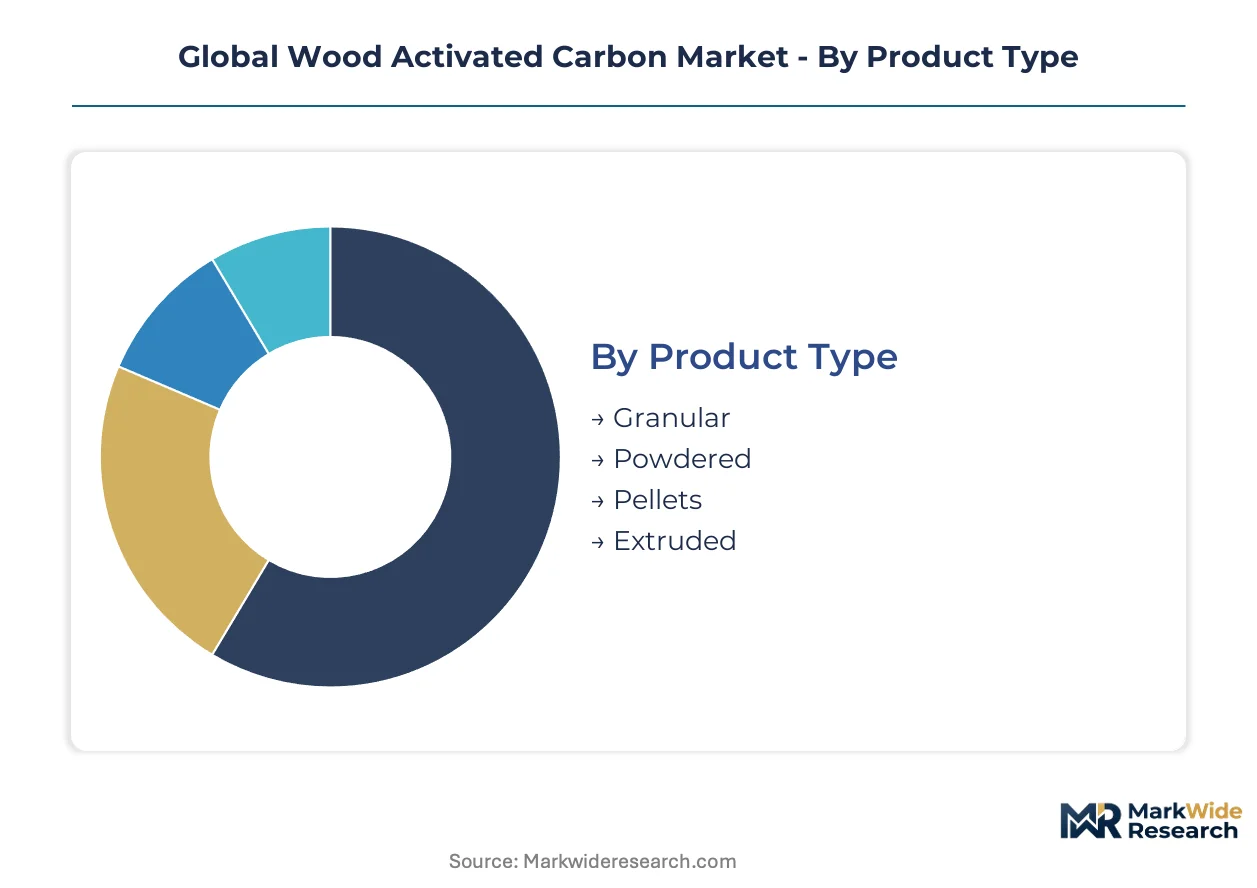
Wood activated carbon markets fragment across physical form, activation chemistry, and end-use specifications that dictate procurement patterns. Each segmentation axis carries distinct margin profiles and technical certification requirements that reshape supplier positioning.
Product Type:
Supply concentration tilts toward configurations compatible with fixed-bed municipal infrastructure and high-volume industrial processing.
- Granular:Irregular particles sized 0.2-5 mm dominate liquid-phase filtration. Municipal water utilities in Indonesia and Vietnam specify this grade for fixed-bed reactor compatibility, locking in bulk procurement contracts with integrated reactivation services.
- Powdered:Finely ground material below 0.18 mm enables rapid adsorption kinetics. Food and beverage decolorization in Japan and EU markets absorbs this output, where Ministry of Health standards and REACH traceability requirements filter supplier access.
- Pellets:Cylindrical extrusions optimize pressure-drop characteristics in gas-phase applications. Air purification systems specify this geometry.
- Extruded:Uniform diameter rods suit specialized catalyst support applications in petrochemical processing.
Granular absorbs the bulk of installed capacity; powdered is expanding most quickly.
Activation Method:
Cost tier differentiation separates mass-market steam activation from premium chemical routes commanding certification premiums.
- Steam:Thermal processing at 800-1,000°C with water vapor yields standard liquid-phase grades. This route concentrates in Southeast Asian integrated pulp-to-carbon facilities serving export markets.
- Chemical:Zinc chloride or phosphoric acid impregnation creates enhanced mesopore structures. Pharmaceutical and air purification applications in Japan and Germany specify these grades for volatile organic compound capture.
- Phosphoric Acid:Specialized mesopore tailoring targets high-value decolorization and medical adsorbent certifications.
- Potassium Hydroxide:Alkali activation produces ultra-high surface area grades for niche supercapacitor and advanced filtration applications.
Steam activation anchors volume production; chemical activation is climbing the fastest.
End Use Industry:
Application maturity determines whether segments compete on specification compliance or total cost of ownership.
- Water Treatment:Municipal and industrial filtration systems specify iodine numbers 800-1,200 mg/g for contaminant removal. EPA Safe Drinking Water Act and EU Drinking Water Directive thresholds drive replacement cycles across US and German utilities.
- Air Purification:Volatile organic compound capture and industrial emissions control demand specialized mesopore distribution. Japanese manufacturing facilities and EU industrial clusters specify certified grades.
- Food & Beverage:Decolorization and purification operations require food-grade certifications that coconut shell competitors often hold.
- Pharmaceuticals:Purity standards from Japan's Ministry of Health filter market access to qualified suppliers.
- Petrochemicals:Catalyst support and process purification applications tolerate broader specification ranges.
Water treatment commands the largest volume commitment; pharmaceuticals is gaining share fastest.
Application:
Customer type segmentation separates specification-driven buyers from price-sensitive commodity purchasers.
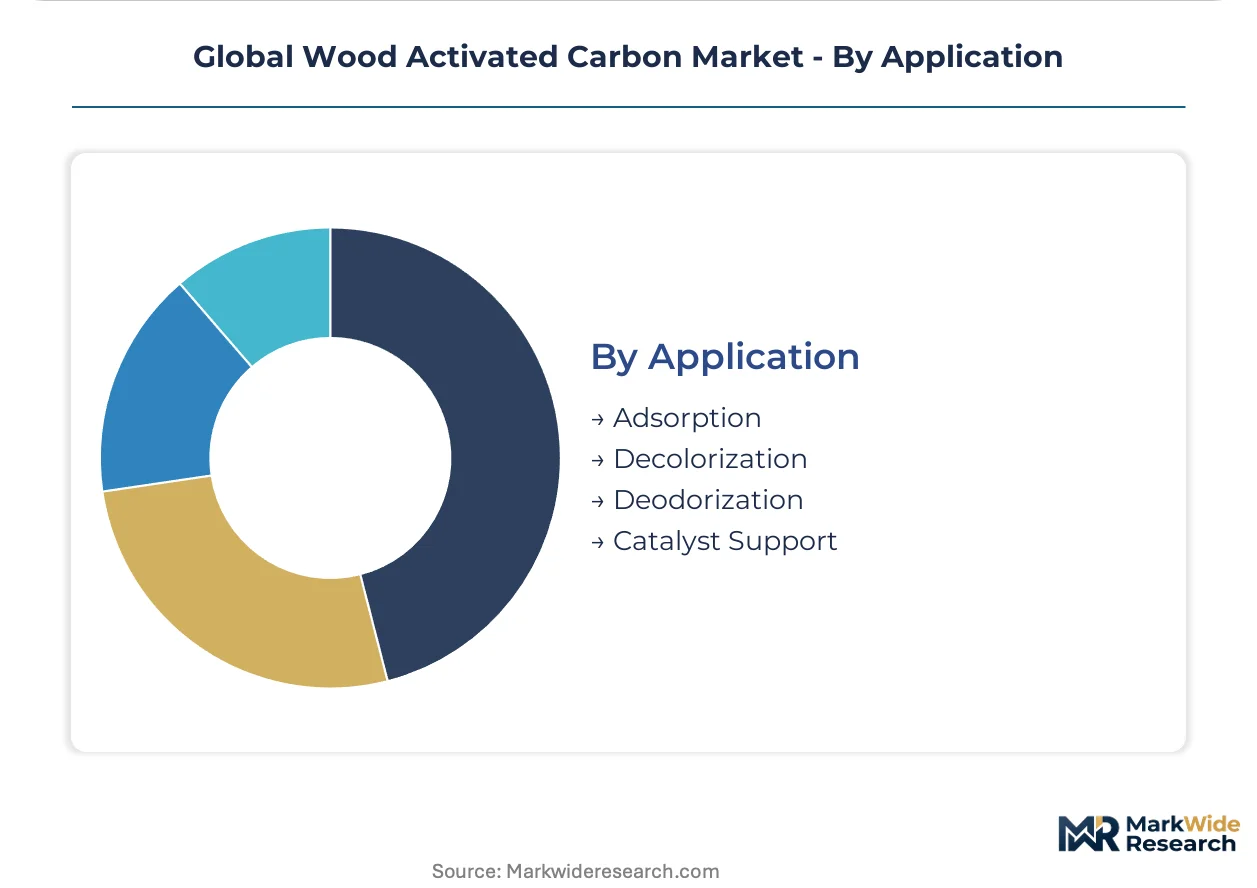
- Adsorption:Contaminant removal from liquids and gases represents the core functional application. Municipal utilities in Vietnam and Indonesia scale capacity to meet tightening potable standards.
- Decolorization:Rapid pigment and impurity removal in food processing and chemical manufacturing demands powdered grades with rapid kinetics.
- Deodorization:Odor compound capture in air treatment and consumer products applications.
- Catalyst Support:High surface area substrates for chemical reaction acceleration in petrochemical and specialty chemical production.
Adsorption carries the heaviest capacity allocation; decolorization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian producers dominate feedstock supply while North American and European utilities absorb the bulk of high-specification consumption. This geographic split shapes trade flows and certification requirements across the value chain.
United States
EPA Safe Drinking Water Act enforcement drives municipal replacement cycles for granular carbon in fixed-bed systems. The agency's tightening per- and polyfluoroalkyl substances thresholds force utilities toward upgraded adsorption infrastructure. Midwestern water treatment clusters around Chicago and Detroit anchor bulk procurement volumes.
Germany
EU REACH chemical adsorbent protocols mandate feedstock traceability for wood-based grades entering potable water applications. The country's municipal procurement frameworks now specify renewable-origin carbon in technical specifications. Industrial water users in the Ruhr Valley and chemical processing clusters along the Rhine accelerate certified-grade uptake.
Indonesia
The Ministry of Environment and Forestry regulates sustainable hardwood sourcing for carbon producers serving export markets. Integrated pulp-to-carbon facilities in Sumatra and Kalimantan reduce feedstock transport costs. Regional champions leverage captive supply chains to capture Southeast Asian municipal water infrastructure contracts.
Japan
The Ministry of Health, Labour and Welfare maintains stringent pharmaceutical adsorbent purity standards that filter market access. Kansai manufacturing corridors around Osaka specify certified mesopore-tailored grades for volatile organic compound capture. Domestic buyers consolidate vendor relationships around bundled supply and compliance reporting.
Vietnam
Provincial utilities scale activated carbon filtration capacity to meet tightening national potable water standards. Limited domestic supplier competition opens procurement opportunities for integrated regional producers. Mekong Delta water infrastructure investment concentrates demand for granular configurations compatible with fixed-bed reactors.
Global Wood Activated Carbon Market Competitive Landscape
The competitive structure tilts toward integrated specialists with captive feedstock and reactivation networks. Tier-one positions cluster around North American reactivation infrastructure, Japanese pharmaceutical-grade certification, and Southeast Asian pulp-to-carbon integration. Two strategic archetypes dominate: full-service contractors bundling supply with on-site regeneration, and premium-grade specialists targeting medical and food-grade certifications. Capacity expansion and multi-year utility partnerships represent the dominant competitive moves, displacing fragmented spot-market purchasing.
Among North American service-integrated operators, Cabot Corporation exemplifies the full-service archetype through its reactivation network density. Calgon Carbon Corporation occupies a parallel position in municipal utility contracting. Kuraray Co. Ltd. represents the premium-tier specialist model, with Jacobi Carbons anchoring global distribution coverage across emerging water treatment markets. Osaka Gas Co. Ltd. and Haycarb PLC sit within regional feedstock-integrated tiers, while Donau Carbon GmbH and Silcarbon Aktivkohle GmbH exemplify European certification-focused positioning.
| Leading Market Players |
|---|
| Cabot Corporation |
| Calgon Carbon Corporation |
| Kuraray Co. Ltd. |
| Jacobi Carbons |
| Osaka Gas Co. Ltd. |
| Haycarb PLC |
| Donau Carbon GmbH |
| Silcarbon Aktivkohle GmbH |
| CarboTech |
| Others |
Supply & Pricing Matrix
Captive pulp-to-carbon integration across Indonesian and Vietnamese supply chains anchors both feedstock security and pricing power for regional producers serving export markets. This backward integration insulates integrated operators from hardwood spot-market volatility while compressing margins for non-integrated manufacturers exposed to natural gas price swings in thermal processing.
Pricing Analysis
Margin tightening in standard steam-activated grades reflects energy cost pass-through limitations and coconut shell carbon substitution pressure. Three-tier pricing structure across pharmaceutical-certified, municipal-grade, and industrial-standard levels separates Kuraray's premium medical positioning from commodity bulk supply. Cost-down pressure on granular configurations accelerates as Vietnamese provincial utilities consolidate procurement around full-service contracts bundling reactivation services. Municipal buyers exhibit highest price sensitivity through competitive tendering, while pharmaceutical and food-grade purchasers absorb certification premiums with limited volume elasticity.
Supply Chain Analysis
Indonesia's Ministry of Environment and Forestry domestic-content mandates on sustainable hardwood sourcing are reshaping procurement patterns for export-oriented producers. Feedstock supply concentrates in Indonesia, Vietnam, and select Baltic states with certified forestry operations. Manufacturing draws from hardwood pulp, phosphoric acid for chemical activation, and natural gas for thermal processing. Single-source vulnerability sits with Southeast Asian hardwood supply given EU REACH traceability requirements and limited alternative certified sources. Distribution runs through bulk-term contracts with integrated reactivation services, displacing fragmented spot-market purchasing through distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: reactivation technician scarcity and certified feedstock bottlenecks prop pricing power for qualified incumbents.
For Market Incumbents: Acquire regional reactivation service networks to anchor multi-year utility partnerships before technician training pipelines mature. Lock in backward integration into certified hardwood plantations under Indonesia's sustainable forestry regulations to defend against feedstock access restrictions. Prioritize pharmaceutical-grade certification investment to escape commodity pricing pressure from coconut shell substitutes in decolorization applications.
For New Entrants and Emerging Players: EU REACH chemical adsorbent safety protocols in Germany open a window for pre-qualified wood-based suppliers to displace coal-carbon incumbents lacking certification infrastructure. Target Vietnam's Mekong Delta provincial utilities scaling filtration capacity with limited domestic competition. Enter through containerized reactivation unit partnerships that reduce customer capital burden and accelerate contract capture.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking carbon adsorbent verticals. Long-term viability favors specialists with captive pulp supply and reactivation network density over pure-play manufacturers. Watch Japan's Ministry of Health pharmaceutical purity standard revisions as inflection signal for medical-grade capacity valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Hardwood Plantations | Secures EU REACH-compliant feedstock traceability for export market access. |
| Containerized Reactivation Unit Deployment | Captures Vietnamese municipal contracts through distributed service models. |
| Pharmaceutical-Grade Mesopore Certification | Unlocks Japan Ministry of Health-qualified medical adsorbent premiums. |
| Long-Term Municipal Supply Partnerships | Displaces spot-market purchasing through bundled reactivation services. |
| Green Manufacturing Transition | Aligns with German renewable-origin carbon procurement specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across carbon plant managers, municipal procurement officers, water utility technical directors, and pharmaceutical manufacturing supply chain leads. EPA Safe Drinking Water Act enforcement documentation, EU ECHA REACH substance registration databases, and Indonesia Ministry of Environment forestry certification registries provided demand-side validation. Bottom-up capacity assessments triangulated against top-down consumption estimates across activation chemistry and end-use segments.
Segment-level modeling tracked physical form, activation method, end-use industry, and application dimensions across the projection horizon. Steam versus chemical activation routes were modeled separately given divergent capital intensity and certification requirements. CAGRs derived from installed capacity expansion announcements, utility capital expenditure disclosures, and regulatory compliance timeline analysis. Forecast inputs incorporated natural gas price sensitivity for thermal processing and hardwood feedstock availability under sustainable forestry constraints.
Caveats apply where PFAS regulatory limit revisions, energy price volatility, or coconut shell carbon certification expansions could materially shift the outlook. Forecasts reflect assumptions around reactivation technician training pipeline output and Southeast Asian pulp-to-carbon integration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market