
 Feedwater Treatment Chemicals Market | 2026-2036
Feedwater Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Feedwater Treatment Chemicals Market Analytics
Buyer concentration in the power generation sector is pivoting toward integrated utilities with multi-site boiler operations that demand centralized chemical procurement programs. Ecolab leverages its global service network to embed dosing equipment and remote monitoring alongside chemical supply, locking in long-term facility contracts. Kemira anchors its position in pulp and paper integrated mills where feedwater chemistry ties directly to process efficiency and fiber recovery rates. Solenis competes through specialized oxygen scavenger formulations tailored to high-pressure boiler systems in refineries and petrochemical complexes.
Feedwater treatment chemicals comprise formulated additives—corrosion inhibitors, oxygen scavengers, scale inhibitors, and biocides—designed to protect boiler and steam generation systems from mineral deposition, metal oxidation, and microbiological fouling, typically dosed at parts-per-million levels based on water hardness, temperature, and pressure parameters. The primary industrial purpose centers on extending asset life, maintaining thermal transfer efficiency, and preventing unplanned shutdowns in continuous-process operations. Oxygen scavengers command the deepest technical moats due to formulation complexity and the performance penalties of under-dosing in high-pressure environments, while corrosion inhibitors generate the broadest cross-industry pull across power, refining, and chemical processing applications. Biocides represent the fastest-growing chemistry class as cooling tower and condensate systems face escalating microbial resistance and regulatory limits on halogenated discharge.
The US EPA enforces effluent limitations under the Clean Water Act that directly govern boiler blowdown and cooling tower discharge chemistry, compelling plants to optimize chemical selection for both performance and environmental compliance. China's MEE implements GB standards for industrial wastewater that mandate stricter control of phosphorus and heavy metals in boiler treatment residuals, reshaping formulation requirements for suppliers operating in that market. The EU REACH framework and F-Gas Regulation constrain biocide active ingredients and volatile components, forcing reformulation investments across European supply chains. Stakeholders must monitor how tightening discharge standards in multiple jurisdictions simultaneously alter the economic calculus between traditional chemical programs and emerging electrochemical or membrane-based pretreatment alternatives.
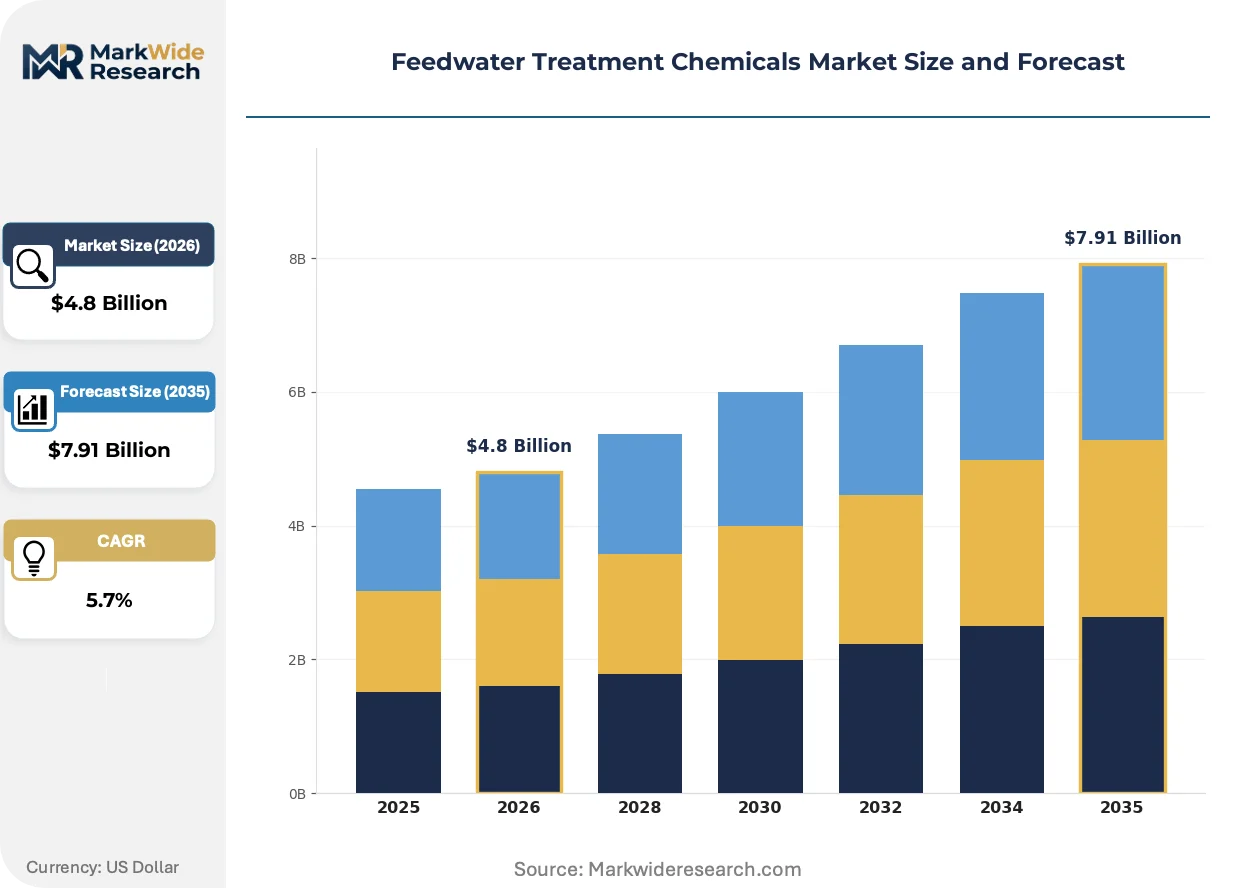
Market Dynamics
Power plant operators face simultaneous pressure from EPA discharge limits and rising boiler operating pressures, forcing a recalibration of chemical program economics toward higher-performance oxygen scavengers and integrated monitoring systems.
Growth Catalysts
- EPA Steam Electric Power Generating Effluent Guidelines:Tightened discharge limits for coal-fired and combined-cycle facilities are mandating upgraded chemical treatment programs to meet blowdown chemistry standards.
- China's manufacturing expansion:Utilities and industrial parks in the Yangtze and Pearl River Delta regions are scaling boiler water treatment capacity to support grid reliability targets and process steam demand.
- High-pressure boiler proliferation:Advanced ultra-supercritical power generation units require precision-dosed oxygen scavenger formulations that prevent metal oxidation at extreme temperature-pressure regimes.
Market Restraints
- Feedstock volatility:Hydrazine and carbohydrazide precursor costs fluctuate with ammonia and urea commodity pricing, compressing formulation margins for oxygen scavenger producers.
- Supplier concentration:Specialty biocide active ingredient production clusters in the Rhine-Ruhr industrial corridor, creating single-source vulnerability for European formulators.
- Electrochemical substitution:Membrane deaeration and vacuum degassing systems in greenfield power plants are displacing chemical oxygen scavenging in low-pressure steam applications.
Strategic Opportunities
- India's industrial corridor buildout:The Delhi-Mumbai Industrial Corridor and dedicated freight corridors are attracting process industries with captive power needs, creating first-mover positioning for integrated chemical service providers.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases used in certain biocide delivery systems are opening formulation windows for bio-based and mineral acid alternatives.
- Remote monitoring convergence:IoT-enabled dosing controllers paired with cloud-based water chemistry analytics are enabling predictive chemical replenishment models that lock in multi-year facility contracts.
Industry Challenges
- Certified water treatment specialist scarcity:Boiler water chemistry expertise concentrated among aging plant operators is not replenishing at the pace of facility expansion, particularly in Southeast Asian markets.
- Legacy DCS integration friction:Chemical dosing automation systems must interface with decades-old distributed control systems in existing power plants, extending deployment timelines and raising commissioning costs.
- REACH registration burden:Biocide active substance approval timelines under EU BPR and REACH are stretching 18-36 months, delaying product launches and freezing formulation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feedwater Treatment Chemicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Oxygen Scavengers, Scale Inhibitors, Biocides Application: Power Generation, Manufacturing, Oil & Gas, Water Treatment End User: Industrial Plants, Utilities, Municipalities, Chemical Processors Packaging Type: Drums, IBC Containers, Bags, Bulk Tanks |
| Companies Covered | Ecolab, Kemira, Veolia, BASF SE, Kurita Water Industries Ltd, Solenis, Dow, Nouryon, Buckman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feedwater Treatment Chemicals Market Evolving Landscape
Formulation science and digital dosing infrastructure are advancing in parallel, with chemical suppliers embedding sensor networks and algorithmic control to transform static treatment programs into adaptive, condition-responsive systems.
Film-forming amine technology is converging with traditional oxygen scavenger programs to provide dual-function protection against both oxygen pitting and flow-accelerated corrosion in condensate return systems. Combined-cycle operators in the US Gulf Coast and North Sea offshore platforms are piloting these hybrid chemistries at 15-20% dosage reductions versus conventional programs. The structural consequence is converging with equipment OEM service offerings, as boiler manufacturers bundle chemical supply into long-term asset performance guarantees.
China's MEE is enforcing GB 31570 and GB 31571 standards for petroleum refining and chemical synthesis wastewater, including stricter phosphorus and heavy metal limits in boiler blowdown streams. Formulators serving Sinopec and PetroChina facilities are reformulating scale inhibitors to eliminate phosphonate content, substituting polyacrylic acid and polymaleic acid alternatives. The affected segment spans high-pressure boiler systems in coastal refining clusters, where discharge directly into sensitive marine ecosystems triggers heightened regulatory scrutiny.
Integrated utilities with multi-site boiler operations are consolidating chemical procurement under enterprise-wide framework agreements that specify performance metrics rather than product volumes. This displaces the traditional transactional model where individual plant chemists specified brands and dosages. The shift is most visible in German municipal utilities and US independent power producers with geographically dispersed combined heat and power assets, where centralized technical oversight now governs field-level chemical selection.
Feedwater Treatment Chemicals Market Segmentation
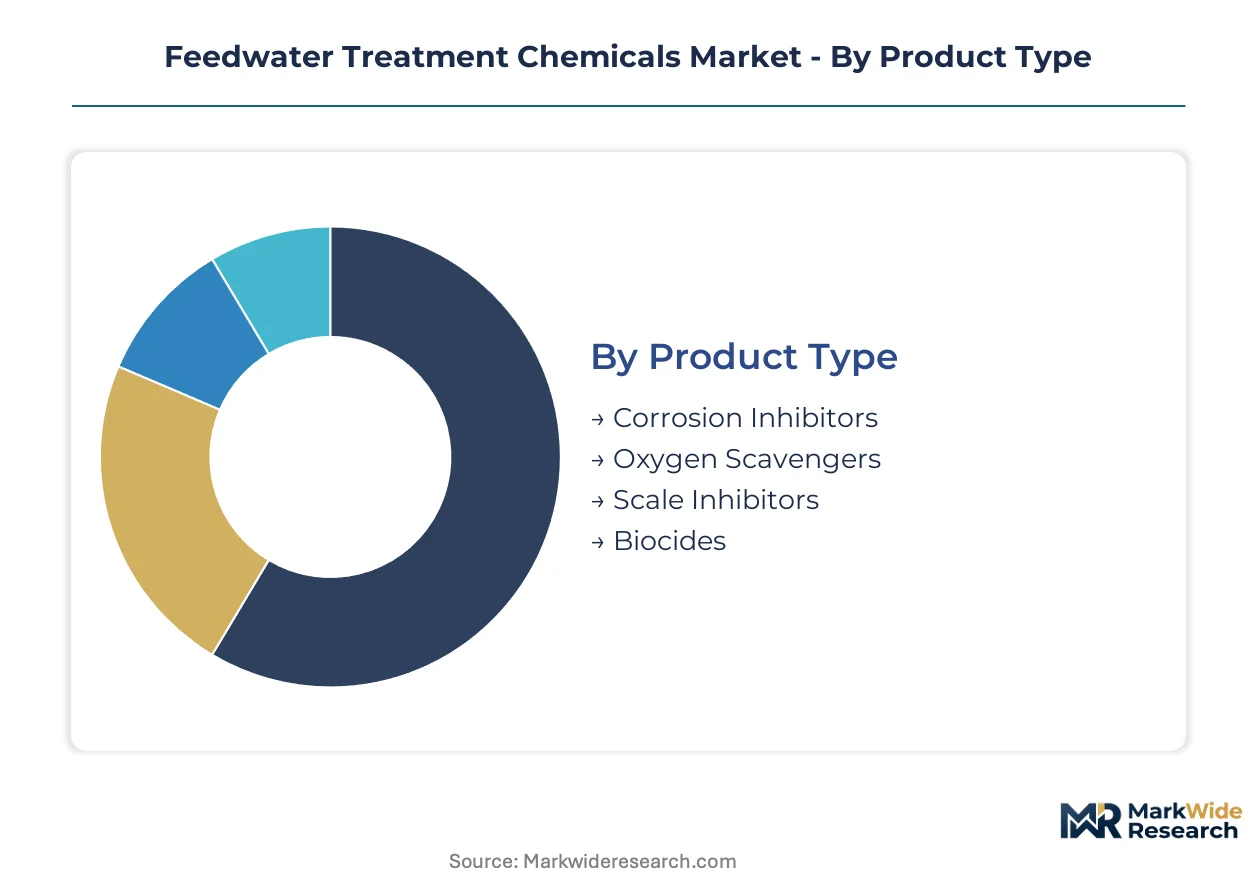
Feedwater treatment chemical selection hinges on boiler operating pressure, water chemistry baselines, and discharge compliance requirements. Specification mismatches between product type and application environment trigger accelerated asset degradation or regulatory penalties. Procurement patterns increasingly favor integrated chemical service contracts over discrete product purchases.
Product Type:
Formulation chemistry determines protection mechanisms against distinct failure modes in steam generation systems.
- Oxygen Scavengers:Carbohydrazide and DEHA-based formulations chemically reduce dissolved oxygen to prevent pitting corrosion in high-pressure boiler tubes. Demand concentrates in ultra-supercritical power plants across China's coastal provinces, where GB standards mandate stringent blowdown chemistry. These formulations command technical premiums due to dosage precision requirements at extreme temperature-pressure regimes.
- Corrosion Inhibitors:Blended amine and phosphate compounds establish protective films on metal surfaces throughout condensate return networks. US Gulf Coast refineries and petrochemical complexes drive specification intensity, balancing neutralizing capacity against EPA discharge limits for phosphorus-containing effluent.
- Scale Inhibitors:Phosphonate and polymer-based dispersants interrupt crystal nucleation to prevent mineral deposition on heat transfer surfaces. Industrial parks in India's Delhi-Mumbai corridor specify these for mixed-source makeup water with variable hardness profiles.
- Biocides:Oxidizing and non-oxidizing microbiological control agents target biofilm formation in cooling towers and condensate systems. EU F-Gas Regulation phase-downs are accelerating reformulation toward mineral acid and bio-based alternatives in German and Dutch chemical processing facilities.
Mature deployment sits with corrosion inhibitors. Newer deployment is concentrated in biocides.
Application:
End-use environment dictates chemical program complexity and monitoring infrastructure investment.
- Power Generation:Coal-fired, combined-cycle, and nuclear facilities require continuous chemical injection to protect critical boiler and turbine assets. China's state grid utilities are scaling treatment capacity to support manufacturing expansion and reliability targets across the Yangtze River Delta.
- Oil & Gas:Refineries and upstream production facilities face aggressive water chemistry from produced water co-treatment. North Sea offshore platforms pilot film-forming amine hybrids at reduced dosage versus conventional programs.
- Manufacturing:Pulp and paper integrated mills, food processing, and textiles demand process steam consistency where feedwater chemistry ties directly to product quality. Kemira anchors supply relationships in Nordic pulp operations where fiber recovery rates depend on precise chemical control.
- Water Treatment:Municipal and industrial wastewater facilities incorporate boiler blowdown management within broader effluent compliance frameworks. US EPA Steam Electric Power Generating Effluent Guidelines are tightening discharge limits that reshape chemical selection across this segment.
Volume concentration tracks power generation. Margin expansion concentrates in oil and gas applications.
End User:
Procurement authority and technical capability vary sharply across customer archetypes.
- Utilities:Integrated power producers with multi-site boiler operations demand enterprise-wide framework agreements specifying performance metrics rather than product volumes. German municipal utilities exemplify this shift toward centralized technical oversight.
- Industrial Plants:Captive power and process steam operations in steel, cement, and chemicals balance chemical costs against unplanned shutdown risk. Southeast Asian facility expansion is outpacing certified water treatment specialist availability.
- Chemical Processors:Complex multi-product sites require customized formulation portfolios addressing varied pressure regimes and contamination profiles simultaneously. REACH registration timelines for biocide actives are stretching product launch schedules.
- Municipalities:District heating networks and combined heat and power assets prioritize operational simplicity and regulatory compliance over performance optimization. Legacy DCS integration friction extends deployment timelines for automated dosing systems.
Contract sophistication peaks with utilities. Technical support intensity concentrates with chemical processors.
Packaging Type:
Logistics configuration aligns with consumption scale, site storage constraints, and inventory management protocols.
- Bulk Tanks:Permanent on-site storage for high-volume continuous operations with dedicated chemical unloading infrastructure. Coastal refining clusters in China's Pearl River Delta favor this format for scale inhibitor and oxygen scavenger programs.
- IBC Containers:Intermediate bulk format balancing transport efficiency with handling flexibility for mid-scale industrial users. Remote monitoring convergence is enabling predictive replenishment models tied to IBC exchange schedules.
- Drums:Standard 55-gallon units for smaller boiler operations, pilot trials, and multi-product sites with limited storage. US independent power producers with dispersed combined heat and power assets rely on drum shipments for operational agility.
- Bags:Powder and solid chemical formats for oxygen scavenger precursors and specialty biocide actives requiring dry storage. Precursor cost volatility for hydrazine and carbohydrazide derivatives is compressing margins in this packaging tier.
Operational scale drives bulk tank specification. Flexibility requirements sustain drum and IBC demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ammonia and urea feedstock corridors in the US Gulf Coast and China's Shandong Peninsula anchor regional formulation capacity for oxygen scavenger precursors. Geographic demand patterns track boiler installation intensity across power generation and refining clusters.
United States
Combined-cycle capacity additions along the Texas-Louisiana Gulf Coast drive specification intensity for high-pressure oxygen scavenger programs. EPA Steam Electric Power Generating Effluent Guidelines mandate upgraded blowdown chemistry at coal-fired facilities. The Permian Basin refining corridor scales chemical treatment capacity to manage produced water co-treatment demands.
China
Ultra-supercritical power units across Jiangsu and Zhejiang provinces require precision-dosed carbohydrazide formulations at extreme operating regimes. MEE enforcement of GB 31570 and GB 31571 standards eliminates phosphonate scale inhibitors from coastal refinery discharge streams. The Yangtze River Delta industrial park cluster concentrates procurement for integrated boiler-cooling tower chemical programs.
Germany
Municipal utility consolidation under framework agreements shifts procurement authority from plant chemists to centralized technical offices. EU REACH and F-Gas Regulation timelines stretch biocide active substance approvals, freezing formulation pipelines. The Rhine-Ruhr chemical processing belt pilots mineral acid alternatives to fluorinated biocide delivery systems.
India
Captive power investment along the Delhi-Mumbai Industrial Corridor outpaces certified water treatment specialist availability. Central Electricity Authority mandates tighten boiler water chemistry standards for grid-connected industrial generators. Gujarat's Special Economic Zones attract integrated chemical service providers for multi-site boiler operations.
Saudi Arabia
Integrated refinery-power complexes at Jubail and Yanbu specify corrosion inhibitor programs balancing neutralizing capacity against discharge limits. The country's national environmental regulator enforces stricter industrial wastewater standards for phosphorus-containing effluent. Red Sea coastal facilities face heightened scrutiny on halogenated biocide discharge into sensitive marine ecosystems.
Feedwater Treatment Chemicals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital dosing convergence and predictive replenishment models. The vendor base stratifies between integrated service networks and specialized formulation houses. Three archetypes dominate: global chemical-service integrators bundling equipment and monitoring; regional specialists anchoring single-industry verticals; and diversified material science conglomerates leveraging feedstock integration. Competitive moves concentrate on IoT-enabled dosing controller deployment and multi-year facility performance contracts.
Within the integrated service tier, Ecolab and Veolia exemplify the equipment-chemical bundling model that locks in long-term facility relationships. Kemira occupies a position among Nordic specialists with pulp and paper vertical concentration. Solenis sits within the high-pressure boiler formulation segment, representing the specialized oxygen scavenger archetype for refinery and petrochemical applications. Dow and BASF SE anchor the material science conglomerate tier, leveraging upstream chemical integration into downstream water treatment formulations.
| Leading Market Players |
|---|
| Ecolab |
| Kemira |
| Veolia |
| BASF SE |
| Kurita Water Industries Ltd |
| Solenis |
| Dow |
| Nouryon |
| Buckman |
| Others |
Value Network & Pricing Analysis
Membrane deaeration and electrochemical pretreatment adoption in greenfield power plants simultaneously compresses chemical oxygen scavenger volumes and shifts procurement authority toward integrated service contracts with embedded equipment leasing. This technology transition concentrates pricing power among suppliers bundling remote monitoring infrastructure with formulated chemistry, while transactional spot markets for commodity biocides face margin erosion from feedstock volatility.
Pricing Analysis
Service-bundling separates integrated chemical programs with embedded dosing controllers and predictive analytics from unbundled commodity chemical transactions. Three-tier pricing structure across premium, standard, and economy levels tracks formulation complexity and monitoring integration depth. Pricing pressure stems from hydrazine and carbohydrazide precursor cost volatility tied to ammonia and urea commodity cycles. Industrial plants with captive power operations exhibit highest price sensitivity due to unplanned shutdown risk calculus, while ultra-supercritical power utilities prioritize performance guarantees over unit cost.
Supply Chain Analysis
Reverse-logistics flows for IBC container return and refurbishment programs anchor replenishment scheduling for mid-scale industrial users, with predictive exchange models reducing working capital requirements. Formulation capacity concentrates in the United States Gulf Coast, China's Shandong Peninsula, and Germany's Rhine-Ruhr corridor. Production draws from ammonia and urea feedstock clusters, phosphonate and polymer intermediates, and specialty biocide active ingredients. Single-source vulnerability for European biocide actives creates structural risk. Distribution runs through integrated service networks for high-volume utilities and regional chemical distributors for fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH and BPR registration timelines stretch 18-36 months, freezing formulation pipelines and forcing sub-scale players toward exit.
For Market Incumbents: Cement multi-year facility contracts through IoT-enabled dosing controller deployment paired with cloud-based water chemistry analytics. Deepen backward integration into carbohydrazide and DEHA precursor production to offset ammonia feedstock volatility. Lock in enterprise-wide framework agreements with German municipal utilities and US independent power producers before electrochemical substitution accelerates in low-pressure applications. For New Entrants and Emerging Players: District heating networks and combined heat and power assets in Nordic and Baltic markets remain underserved by integrated chemical service providers. India's Delhi-Mumbai Industrial Corridor captive power installations outpace certified water treatment specialist availability, creating white-space for technical service bundling. Target first-mover positioning through mineral acid biocide alternatives aligned with EU F-Gas Regulation phase-down timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by material science conglomerates seeking downstream water treatment formulation capabilities. Long-term viability favors suppliers with captive feedstock integration and digital dosing infrastructure deployed across multi-site utility networks. Monitor EPA enforcement patterns on Steam Electric Power Generating Effluent Guidelines as inflection indicator for chemical program upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive ammonia and urea supply locks in oxygen scavenger margins against commodity volatility. |
| IoT-Enabled Dosing Controller Deployment | Cloud-based water chemistry analytics transform transactional chemical sales into multi-year performance contracts. |
| Mineral Acid Biocide Reformulation | EU F-Gas Regulation compliance opens substitution windows in German and Dutch chemical processing facilities. |
| Enterprise Framework Agreement Consolidation | Centralized technical oversight displaces plant-level procurement in German municipal utilities. |
| Film-Forming Amine Hybrid Pilot Programs | North Sea offshore platforms validate 15-20% dosage reduction versus conventional oxygen scavenger programs. |
Research Methodology
Multi-period observation of boiler installation intensity, EPA enforcement actions, and MEE standard implementation anchored the trend analysis, supplemented by interviews with plant managers at power generation facilities, procurement leads at integrated refineries, chemical distribution channel partners, and technical R&D directors at formulation houses. Secondary validation drew from EIA power plant databases, EPA effluent guideline dockets, Chinese customs trade data, and SEC 10-K filings from publicly traded chemical suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting across product type, application environment, end-user procurement authority, and packaging format determined value allocation. CAGRs were derived from regression analysis of historical consumption patterns against projected boiler capacity additions and regulatory compliance timelines. Industry-specific forecast inputs included ultra-supercritical power unit commissioning schedules in China's coastal provinces and REACH biocide active substance approval pipeline status.
Revisions become necessary when EPA effluent guideline enforcement intensity shifts, electrochemical pretreatment adoption accelerates beyond baseline assumptions, or feedstock corridor disruptions materialize in the US Gulf Coast or Shandong Peninsula. Practitioners should monitor MEE standard enforcement patterns and greenfield power plant technology selection for early signals of chemical program displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market