
 Asia-Pacific Boiler Water Treatment Chemicals Market | 2026-2036
Asia-Pacific Boiler Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Boiler Water Treatment Chemicals Market Outlook
A shortage of certified water chemists and boiler-treatment technicians is reorganizing how facilities across the Asia-Pacific source and apply treatment programs. Ecolab leverages its regional technical service network to embed specialists directly at power and manufacturing sites. Kurita Water Industries Ltd anchors its position through deep R&D partnerships with Japanese heavy industry. Thermax Limited competes by dominating India's domestic supply chain for customized boiler water solutions.
Boiler water treatment chemicals comprise formulated additives including corrosion inhibitors, scale inhibitors, pH adjusters, and biocides designed to maintain thermal efficiency and prevent metallurgical failure in steam-generating systems. These formulations typically operate within narrow pH windows and must comply with conductivity limits to avoid caustic embrittlement or oxygen pitting in high-pressure boilers. Among product types, corrosion inhibitors command the largest current volume share due to relentless demand from aging power infrastructure, while biocides represent the fastest-expanding category as cooling tower and boiler hybrid systems proliferate across tropical climates. Liquid formulations lead distribution owing to ease of automated dosing, though powder and tablet forms gain traction in remote mining and food processing installations where storage stability matters.
China's MEE enforces progressively stricter discharge limits that elevate chemical performance requirements, while India's CEA mandates boiler water quality standards for thermal power stations that directly shape procurement specifications. Japan's METI promotes energy-efficiency guidelines that incentivize advanced treatment chemistries reducing blowdown rates. Stakeholders must monitor regulatory divergence across these jurisdictions to align product registration strategies with evolving compliance thresholds.
Market Dynamics
China's MEE discharge mandates and India's CEA boiler water standards are forcing simultaneous capital outlays across aging thermal fleets and new industrial installations, compressing procurement cycles and elevating technical service intensity.
Growth Catalysts
- MEE Wastewater Standards:China's tightened discharge limits under Ministry of Ecology and Environment oversight compel power and chemical facilities to upgrade from basic phosphate programs to advanced polymer-based scale inhibitors.
- Biocide Demand Surge:Tropical climates across Southeast Asia drive rapid adoption of oxidizing biocide programs in hybrid cooling-tower-boiler systems at textile and food processing clusters.
- High-Silica Feedwater Prevalence:Geological conditions in Indonesia and the Philippines necessitate specialized antiscalant formulations for geothermal and coal-fired plants managing silica-laden source water.
Market Restraints
- Phosphoric Acid Volatility:Price swings in phosphate rock feedstock destabilize formulation costs for conventional corrosion inhibitors, squeezing margins on legacy product lines.
- Technical Talent Scarcity:Certified boiler water chemists remain concentrated in Japan and Australia, leaving Indonesian and Vietnamese facilities dependent on intermittent foreign technical support.
- Substitution by Membrane Pretreatment:Reverse osmosis systems at greenfield power plants in South Korea reduce chemical dependency for boiler feed conditioning.
Strategic Opportunities
- Vietnam's Thermal Expansion:New coal and gas capacity in the Mekong Delta corridor creates first-mover positioning for integrated chemical-plus-service providers.
- Japan's METI Efficiency Incentives:Subsidies for reduced blowdown rates accelerate demand for advanced all-polymer programs that cut water and chemical consumption simultaneously.
- Digital Dosing Platforms:IoT-enabled automated chemical injection systems open channel partnerships with industrial automation distributors in Australia's mining regions.
Industry Challenges
- CEA Certification Timelines:India's Central Electricity Authority approval processes for new chemical formulations extend 18-24 months, delaying product launches for thermal power station contracts.
- Legacy Control System Integration:Aging SCADA infrastructure at Philippine and Indonesian power plants complicates deployment of real-time water quality monitoring and automated chemical adjustment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Boiler Water Treatment Chemicals Market |
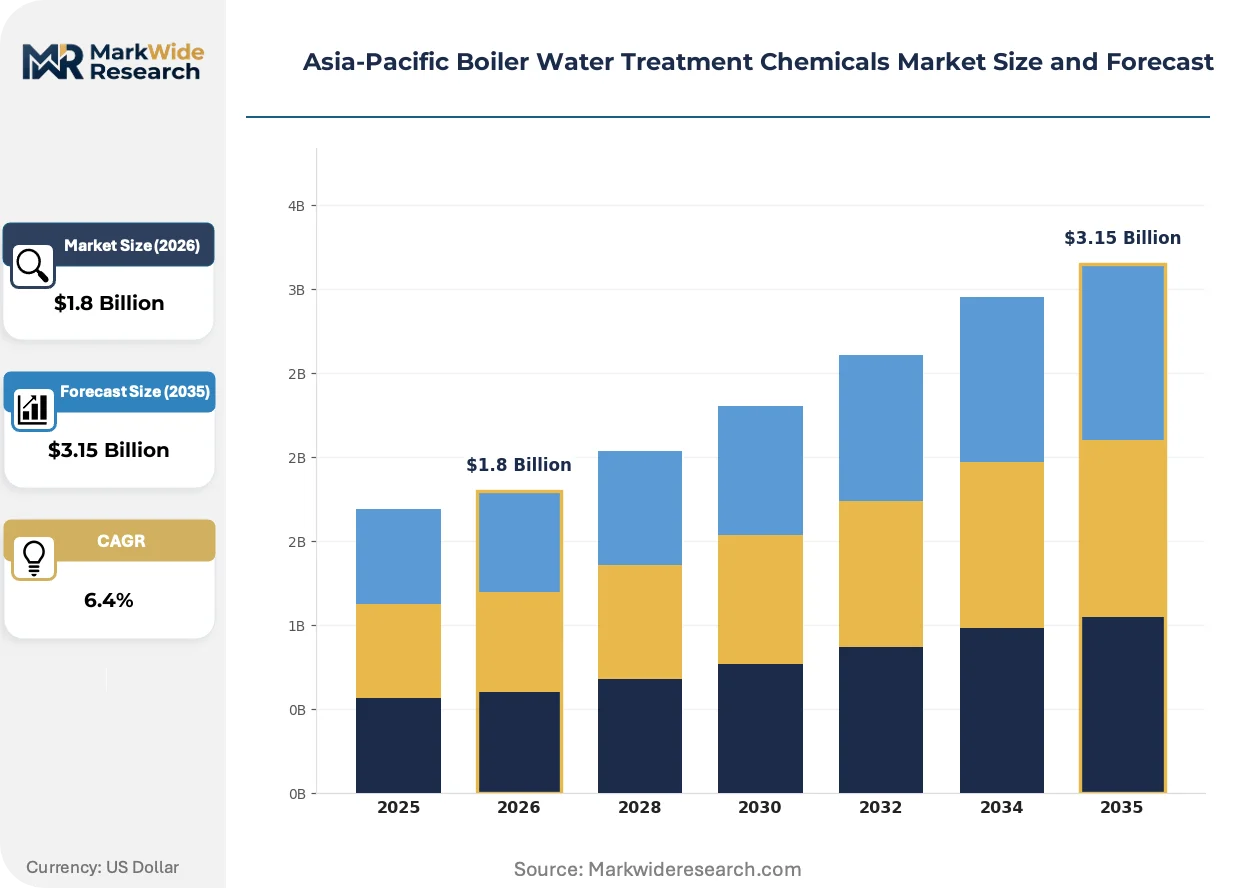
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Scale Inhibitors, pH Adjusters, Biocides End User: Power Generation, Oil & Gas, Food & Beverage, Manufacturing Formulation: Liquid, Powder, Granular, Tablet Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Ecolab, Kemira, Solenis, Kurita Water Industries Ltd, SUEZ, Veolia Water Technologies, BASF, ChemTreat, Thermax Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Boiler Water Treatment Chemicals Market Strategic Shifts
Formulation chemistry, regulatory enforcement mechanisms, and procurement structures are undergoing simultaneous transformation across the Asia-Pacific thermal power and manufacturing base.
All-polymer scale inhibitor technology is miniaturizing the footprint of traditional boiler water treatment programs. Japanese heavy industry adopters are phasing out coordinated phosphate-pH control in favor of single-drum polymer dosing. This convergence is compressing supplier margins on commodity phosphates while elevating value capture for formulation specialists with proprietary polymer platforms.
India's CEA has mandated online silica and conductivity monitoring for all utility-scale thermal stations, effective for new installations and major retrofits. This instrumentation requirement is forcing chemical suppliers to bundle sensor hardware with treatment programs. Gujarat and Tamil Nadu power corridors are experiencing the fastest compliance-driven procurement cycles as state regulators enforce deadlines ahead of federal schedules.
Integrated chemical-plus-service contracts are displacing transactional product sales at Australian mining and Southeast Asian petrochemical complexes. Buyers are unbundling equipment maintenance from chemical supply, then rebundling both under single accountability structures with penalty clauses for steam purity failures. This restructuring concentrates vendor selection power among facilities engineering directors and away from traditional procurement officers.
Asia-Pacific Boiler Water Treatment Chemicals Market Segmentation
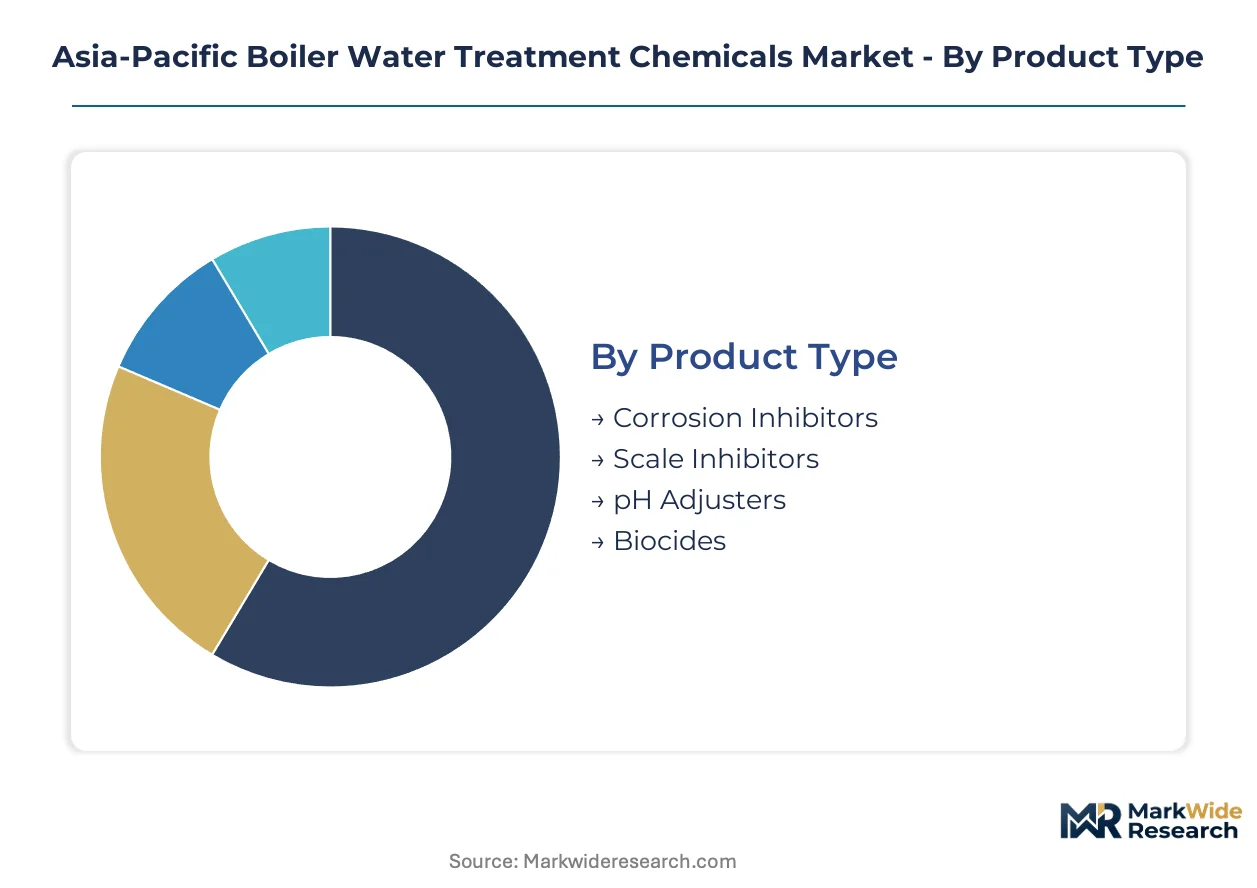
Segmentation in the Asia-Pacific boiler water treatment chemicals market reveals how regulatory divergence across China, India, and Japan fragments procurement specifications. Buyers select formulations based on discharge mandates, boiler pressure ratings, and local technical service availability rather than uniform performance metrics.
Product Type:
China's MEE wastewater standards and India's CEA boiler water mandates create divergent performance requirements that reshape formulation demand across corrosion control, scale prevention, and microbial management.
- Corrosion Inhibitors:Phosphate-based and polymer-amine formulations protect metallurgical integrity in high-pressure steam systems. Aging coal fleets across India's Uttar Pradesh and Maharashtra states drive relentless consumption as utilities defer boiler replacement. China's shift from coordinated phosphate-pH programs to all-polymer alternatives compresses margins on legacy offerings.
- Scale Inhibitors:Polyacrylate and phosphonate chemistries prevent calcium, magnesium, and silica deposition on heat transfer surfaces. Indonesia's geothermal plants and Philippine coal facilities managing high-silica feedwater concentrate demand for specialized antiscalant blends. Japan's METI efficiency incentives accelerate adoption of single-drum polymer dosing that reduces blowdown rates.
- pH Adjusters:Caustic soda and ammonia-based alkalinity controllers maintain narrow operational windows. Food processing clusters in Thailand and Vietnam favor food-grade formulations with documented purity certifications.
- Biocides:Oxidizing and non-oxidizing microbiological control agents combat biofilm formation. Tropical textile and palm oil processing facilities across Malaysia and Indonesia expand programs rapidly.
Corrosion inhibitors handle the majority of throughput; biocides are the fastest mover on share.
End User:
Capital expenditure cycles and regulatory enforcement intensity vary sharply across power utilities, hydrocarbon processors, and manufacturing verticals.
- Power Generation:Utility and captive thermal stations consume bulk volumes for high-pressure drum and once-through boilers. India's CEA-mandated online silica monitoring for all utility-scale stations forces bundled procurement of sensors plus treatment chemicals. Vietnam's Mekong Delta coal expansion creates first-mover opportunities for integrated service providers.
- Oil & Gas:Refinery steam systems and enhanced oil recovery operations require high-purity boiler feed conditioning. Australian LNG train expansions specify low-conductivity formulations to protect gas turbine steam injectors.
- Food & Beverage:Steam-in-contact applications demand food-grade certification and documented batch traceability. Japanese beverage canning lines and Australian dairy processors lead formulation premiumization.
- Manufacturing:Textile dyeing, chemical synthesis, and pharmaceutical production use medium-pressure boilers with varying purity requirements. Gujarat and Tamil Nadu industrial corridors in India concentrate procurement volume.
Power generation commands absolute volume leadership; manufacturing segments climb fastest as industrial boiler installations proliferate.
Formulation:
Physical form selection trades automated dosing compatibility against storage stability and remote site logistics.
- Liquid:Pump-ready solutions dominate automated injection systems at continuous-process facilities. Southeast Asian power plants and petrochemical complexes standardize on bulk liquid delivery with telemetry-linked inventory management.
- Powder:Concentrated dry blends reduce freight costs for remote mining and food processing sites with limited bulk liquid handling infrastructure. Western Australian iron ore camps and Indonesian nickel smelters favor powder logistics.
- Granular:Free-flowing particulate forms suit manual dosing at small industrial boilers and institutional heating systems. Philippine provincial manufacturing zones with intermittent technical support specify granular for shelf-life reliability.
- Tablet:Slow-dissolving compressed formulations serve remote or unmanned installations requiring minimal intervention. Mongolian mining camps and Papua New Guinea processing sites adopt tablet programs where supply chain frequency is constrained.
Liquid formulations carry the volume base; tablet formats expand most quickly in remote resource extraction corridors.
Distribution Channel:
Account complexity and technical service requirements determine whether suppliers engage directly or through intermediaries.
- Direct Sales:Integrated chemical-plus-service contracts at Australian mining and Southeast Asian petrochemical complexes bypass distributors entirely. Ecolab and Kurita embed technical specialists on-site under multi-year accountability structures with steam purity penalties.
- Distributors:Regional chemical handlers stock standard formulations for small and mid-size industrial boilers across India's state-level manufacturing clusters. Thermax leverages domestic distributor density to penetrate Gujarat and Tamil Nadu corridors.
- Online Sales:E-procurement platforms gain traction for standardized commodity chemicals at facilities with established treatment protocols. South Korean and Japanese industrial buyers pilot digital purchasing for routine replenishment.
- Retail:Local trade counters serve small commercial heating systems and institutional kitchens with packaged consumer-grade formulations. Urban centers across Southeast Asia maintain retail presence for maintenance contractors.
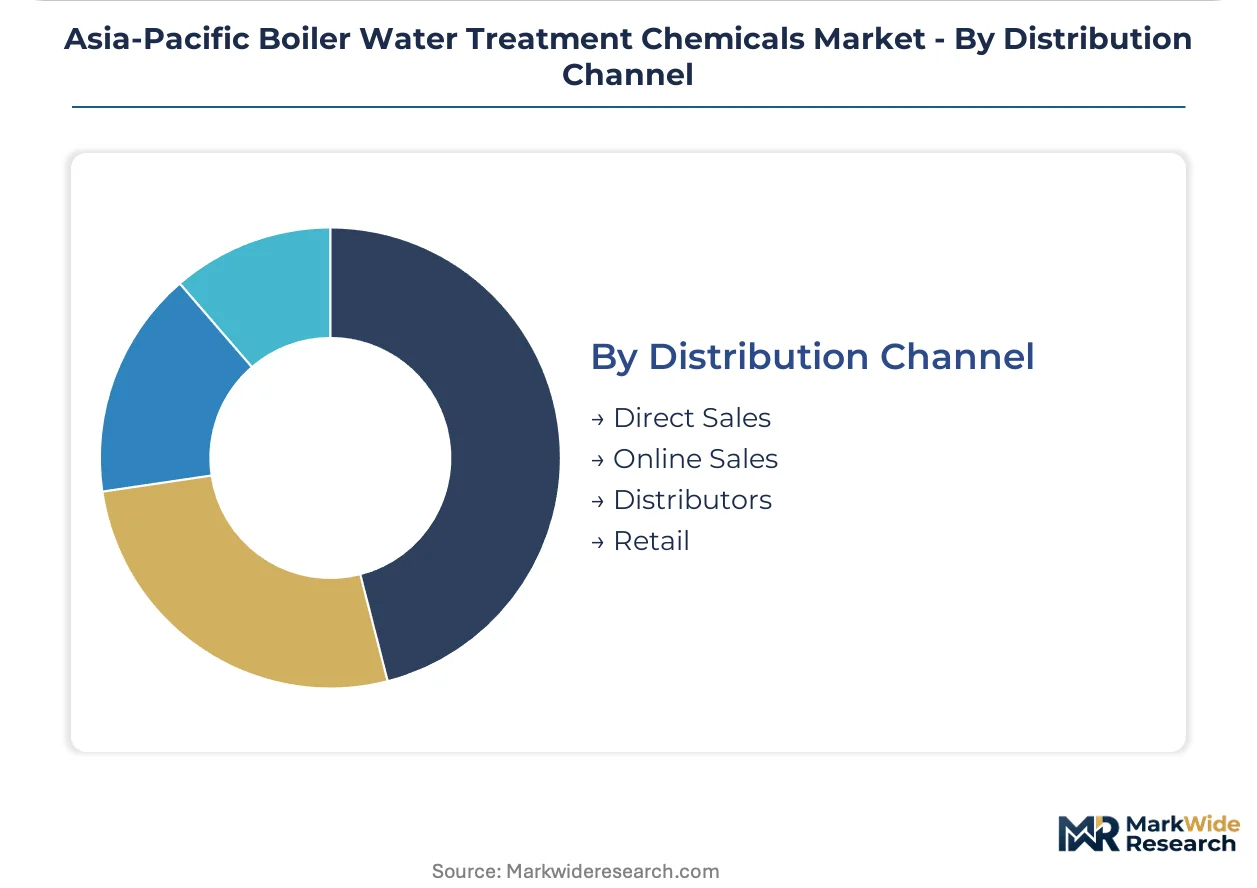
Direct sales capture the premium service-intensive segment; online channels post the steepest expansion trajectory as procurement digitization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands formulation premiums through METI efficiency mandates while Indonesia competes on volume via geothermal expansion and coal fleet growth. This pricing-power asymmetry shapes procurement patterns across the Asia-Pacific thermal power and manufacturing base.
China
Coal-fired capacity additions and chemical manufacturing expansion drive sustained chemical consumption across Shandong and Jiangsu provinces. MEE wastewater discharge standards compel facilities to abandon legacy phosphate programs for advanced polymer formulations. Yangtze River Delta industrial clusters are retrofitting treatment protocols ahead of 2025 compliance deadlines.
India
Utility-scale thermal stations and captive power plants in Gujarat and Tamil Nadu concentrate bulk procurement volume. CEA-mandated online silica monitoring forces bundled sensor-plus-chemical contracts for all major retrofits. Maharashtra's aging coal fleet defers boiler replacement while escalating chemical intensity to maintain operational integrity.
Japan
Heavy industry adopters phase out coordinated phosphate-pH control in favor of single-drum polymer dosing systems. METI energy-efficiency guidelines subsidize reduced blowdown rates that cut water and chemical consumption simultaneously. Kansai and Chubu manufacturing belts lead adoption of all-polymer scale inhibitor technology.
Indonesia
Geothermal plants and coal facilities managing high-silica feedwater necessitate specialized antiscalant formulations. Tropical climates drive oxidizing biocide adoption in hybrid cooling-tower-boiler systems at textile and palm oil processing clusters. Java-Bali power corridor expansion creates procurement scale for integrated chemical-plus-service providers.
Vietnam
New coal and gas capacity in the Mekong Delta corridor generates first-mover positioning opportunities for treatment program vendors. Technical talent scarcity leaves facilities dependent on foreign specialist support for system commissioning. Northern industrial zones around Hanoi experience fastest growth in medium-pressure boiler installations.
Asia-Pacific Boiler Water Treatment Chemicals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific boiler water treatment chemicals market. Japanese and European specialists anchor premium formulation development while domestic Indian and Chinese suppliers compete on localized logistics and price positioning. The vendor base stratifies into three tiers: integrated multinational service providers, regional formulation specialists with R&D partnerships, and domestic commodity distributors. Competitive moves concentrate on embedding technical specialists at customer sites and securing multi-year integrated service contracts with steam purity accountability clauses.
Among multinational integrated service providers, Ecolab leverages its regional technical network to embed specialists directly at power and manufacturing facilities. Kurita Water Industries Ltd exemplifies the Japanese specialist archetype through deep R&D partnerships with domestic heavy industry. Thermax Limited anchors the domestic Indian tier by penetrating Gujarat and Tamil Nadu industrial corridors through dense distributor networks and customized boiler water solutions.
| Leading Market Players |
|---|
| Ecolab |
| Kemira |
| Solenis |
| Kurita Water Industries Ltd |
| SUEZ |
| Veolia Water Technologies |
| BASF |
| ChemTreat |
| Thermax Limited |
| Others |
Value Chain & Pricing Dynamics
Integrated chemical-plus-service contracts spanning three to five years lock in supply access for power utilities while anchoring price visibility against phosphate rock volatility. These bundled accountability structures with steam purity penalty clauses concentrate procurement power among facilities engineering directors in India's CEA-regulated corridors and Australia's mining belts.
Pricing Analysis
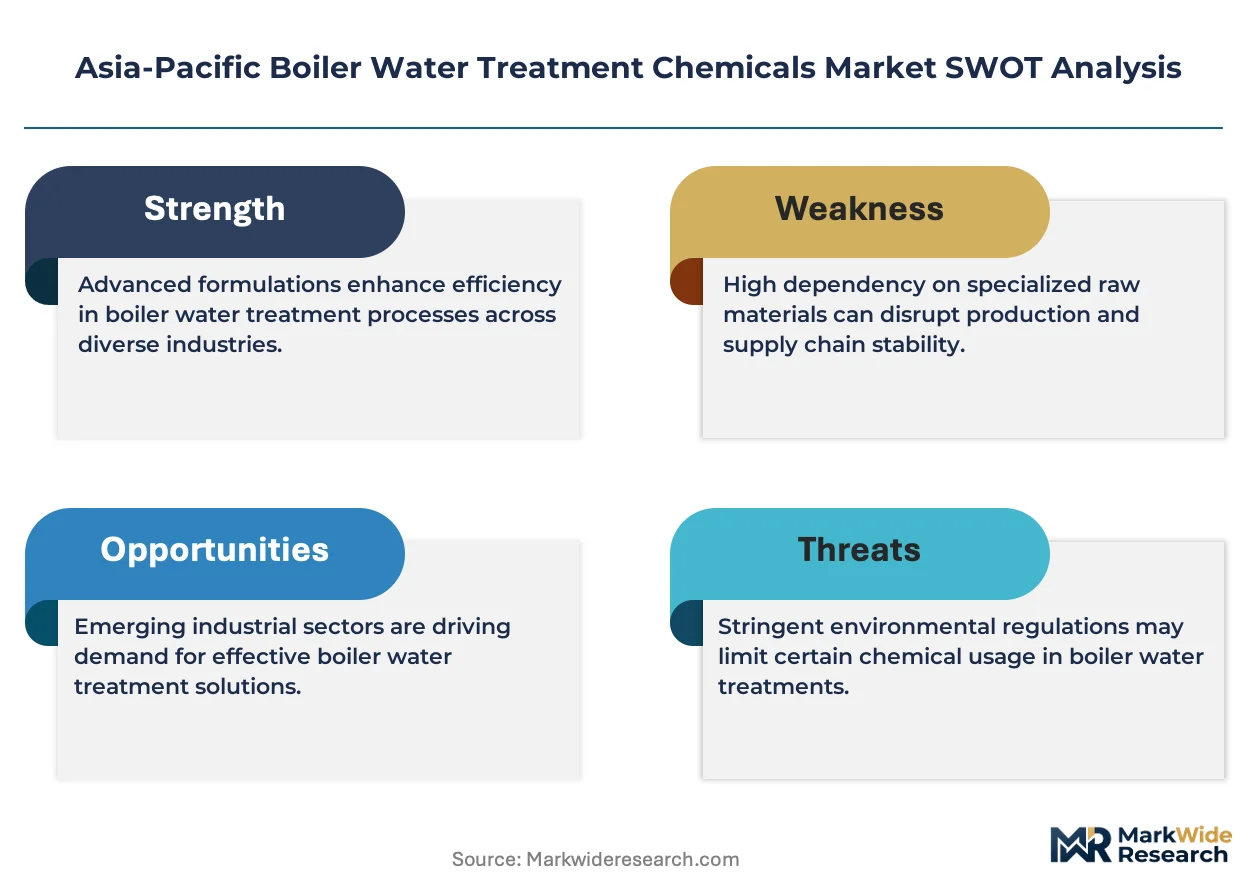
The customization-premium spread separates configured-to-order polymer formulations from standard phosphate-based programs by margins exceeding thirty percent. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and bundled technical service intensity. Cost compression in legacy phosphate tiers is intensifying because Chinese MEE discharge mandates force rapid formulation upgrades. Captive power plants in Vietnam and Indonesia exhibit highest price sensitivity, while Japanese heavy industry adopters under METI efficiency guidelines show lowest sensitivity to premium polymer pricing.
Supply Chain Analysis
Phosphoric acid feedstock transit through the Strait of Malacca underwrites cost stability for Southeast Asian formulators. Manufacturing concentration centers on China, India, and Japan for active ingredient synthesis, with blending operations distributed across Indonesia and Vietnam. Raw material dependencies rest on phosphate rock from Morocco and Jordan, ethylene amines from South Korea, and specialized polymers from Japanese R&D partnerships. Single-source vulnerability in certified water chemist talent pools constrains technical service expansion. Distribution runs through direct embedded specialist teams for integrated contracts, with regional chemical handlers covering mid-tier industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring technical service revenue expands faster than commodity chemical sales. Integrated monitoring and dosing system subscriptions now outpace standalone formulation growth across utility-scale installations.
For Market Incumbents: Fortify embedded specialist presence at CEA-regulated Indian thermal stations before certification timelines lengthen further. Secure backward integration into polymer active ingredient production to defend margins against phosphate volatility. Lock in multi-year sensor-plus-chemical bundled contracts in Vietnam's Mekong Delta expansion corridor to preempt emerging competitor entry.
For New Entrants and Emerging Players: Remote technical support gaps in Indonesian and Vietnamese facilities where certified boiler water chemists remain scarce offer first-mover positioning. Target Australia's mining automation partnerships for IoT-enabled dosing platform distribution. Penetrate through digital dosing platform channel partnerships rather than head-to-head formulation competition.
For Investors and Strategic Acquirers: Regional formulation specialists with proprietary polymer platforms and existing CEA approval status represent priority acquisition targets. Long-term viability hinges on regulatory compliance acceleration across Asia-Pacific jurisdictions rather than commodity volume scale. Watch MEE enforcement intensity in China's Yangtze River Delta as inflection indicator for premium formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Active Ingredients | Secures margin protection against phosphate rock price volatility affecting legacy corrosion inhibitor programs. |
| Long-term Supply Agreement | Locks in offtake volumes with Vietnam's Mekong Delta coal expansion projects ahead of competitor entry. |
| Joint Venture | Combines Japanese polymer R&D expertise with Indian distributor density for CEA-compliant bundled offerings. |
| Capacity Expansion | Adds blending capacity in Indonesia to serve geothermal and coal facilities managing high-silica feedwater. |
| Geographic Expansion | Establishes technical service presence in Australia's mining automation corridors for IoT dosing platform deployment. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with thermal power plant chemists, CEA compliance officers, industrial procurement leads, and technical service directors at formulation specialists. Secondary validation drew from MEE discharge standard filings, CEA boiler water quality circulars, METI efficiency guideline documentation, and customs trade data for phosphate and polymer imports. Bottom-up chemical consumption estimates triangulated against top-down power generation capacity projections.
Across the analysis window, forecasts model formulation demand by product type, end-use industry, physical form, and distribution channel structure, with additional segmentation by regulatory jurisdiction cluster. CAGRs derive from installed base expansion rates, regulatory compliance acceleration curves, and formulation substitution elasticities. Key inputs include CEA certification timeline trajectories, MEE enforcement intensity indices, and METI subsidy uptake rates for reduced blowdown programs.
Underlying assumptions cover continued coal fleet operation in India and Indonesia, with deviation risk concentrated in accelerated membrane pretreatment substitution at South Korean greenfield plants. Forecasts reflect these assumptions with explicit scenario weighting. Revision becomes warranted when CEA certification timelines compress below twelve months or MEE discharge standards tighten beyond current polymer formulation capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market