
 North America Meglitinide Market | 2026-2036
North America Meglitinide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Meglitinide Market Analytics
Reformulated excipient blends is repositioning cost structures for meglitinide tablet production. Novo Nordisk leverages its diabetes therapy portfolio depth to sustain formulary access across North American payers. Glenmark Pharmaceuticals anchors its position through generic repaglinide supply contracts with regional pharmacy chains. Novartis differentiates via nateglinide brand recognition among endocrinology specialists.
Meglitinides constitute a class of non-sulfonylurea insulin secretagogues that bind to ATP-dependent potassium channels on pancreatic beta cells, triggering rapid, glucose-dependent insulin release with a half-life of approximately one hour. These agents serve primarily as prandial glucose regulators for type 2 diabetes patients with erratic meal timing or sulfonylurea intolerance. Repaglinide formulations dominate prescription volume among product types due to established efficacy data and broader reimbursement coverage, while combination therapies with metformin represent the fastest-expanding segment as clinicians seek simplified regimens. The homecare delivery channel is maturing rapidly, though hospital-based initiation protocols still capture the highest-margin patient encounters.
FDA bioequivalence requirements and Health Canada Therapeutic Products Directorate standards govern generic substitution pathways, directly influencing manufacturer R&D allocation and patent litigation exposure. The IRA Medicare price negotiation provisions reshape long-term revenue forecasting for branded meglitinide assets in the United States. Stakeholders must monitor how CMS formulary tiering decisions and provincial pharmacy benefit manager policies in Canada redistribute patient access between originator and generic alternatives.
Market Dynamics
IRA Medicare price negotiation provisions are compressing branded meglitinide revenue forecasts and forcing manufacturers to reallocate R&D investment toward complex generic formulations and biosimilar-ready production platforms.
Growth Catalysts
- Outpatient diabetes management expansion:Integrated health networks in the United States are embedding prandial glucose regulators into standardized care protocols for type 2 diabetes patients with irregular meal patterns.
- FDA bioequivalence pathway clarity:Updated guidance on complex generic standards is accelerating manufacturer entry into repaglinide and nateglinide generic segments.
- Metformin combination therapy uptake:Clinicians across Canadian provincial health systems are prescribing fixed-dose combinations to reduce pill burden and improve adherence.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for meglitinides clusters in South Asian contract manufacturers, exposing North American formulators to shipping disruption and customs delays.
- Sulfonylurea substitution pressure:Lower-cost sulfonylurea alternatives retain preferred formulary status in many U.S. state Medicaid programs, limiting meglitinide access for price-sensitive populations.
- Health Canada Therapeutic Products Directorate review timelines:Extended approval cycles for reformulated excipient blends delay product launches by 18-24 months versus FDA pathways.
Strategic Opportunities
- Homecare channel maturation:Direct-to-patient delivery platforms in the United States are capturing medication adherence data that supports value-based contracting with Medicare Advantage plans.
- Provincial pharmacy benefit manager integration:Ontario and British Columbia are consolidating formularies, creating single-point negotiation leverage for manufacturers with broad generic portfolios.
- Continuous glucose monitor convergence:Pairing meglitinide dosing algorithms with real-time glucose data streams is opening closed-loop prandial insulin management for tech-enabled diabetes clinics.
Industry Challenges
- Formulation scientist scarcity:North American pharmaceutical labor markets lack sufficient expertise in rapid-dissolution excipient engineering required for prandial timing optimization.
- Patent litigation exposure:Generic manufacturers face infringement disputes over polymorph-specific repaglinide crystallization methods, elevating legal reserve requirements.
- Legacy EHR integration friction:Hospital-based initiation protocols require manual data entry into electronic health record systems that lack meglitinide-specific dosing decision support modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Meglitinide Market |
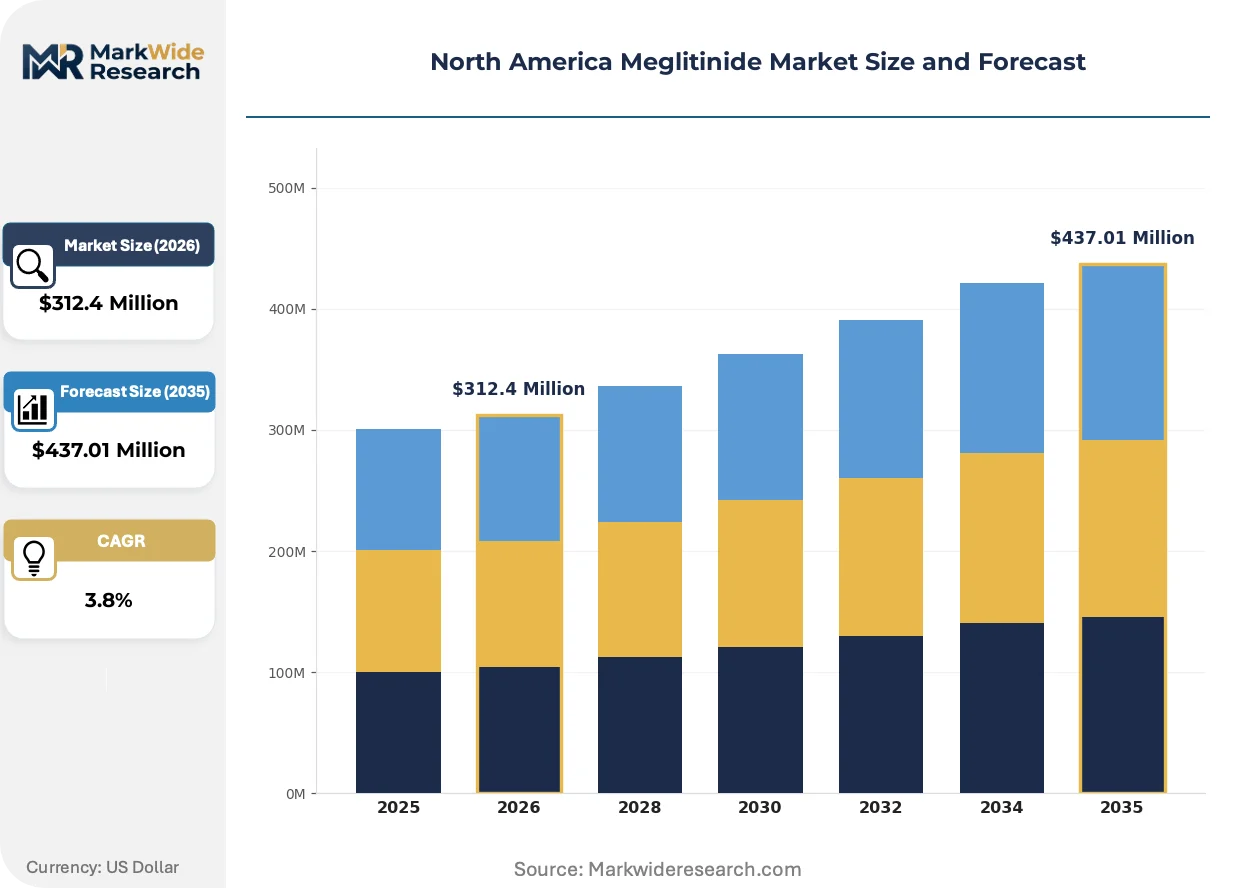
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repaglinide, Nateglinide, Combinations, Generics End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Type 2 Diabetes, Endocrine Disorders, Metabolic Syndrome, Obesity Delivery Mode: Oral, Injectable, Continuous, Inhalable |
| Companies Covered | Novo Nordisk, Novartis, Glenmark Pharmaceuticals, Boehringer Ingelheim, Biocon, Sanofi, Merck & Co., Pfizer, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Meglitinide Market Evolving Landscape
Reformulation science and reimbursement mechanics are converging to reshape how prandial insulin secretagogues reach patients across North American care settings.
Modified-release excipient platforms is electrifying tablet dissolution profiles, enabling more predictable insulin secretion curves that align with irregular meal timing. Endocrinology practices in U.S. academic medical centers are piloting these formulations for shift workers and frequent travelers. The technology is electrifying competitive positioning by differentiating originator products from commodity generics on clinical outcome metrics rather than price alone.
IRA Medicare price negotiation implementation is forcing branded manufacturers to accelerate complex generic pipeline investment or exit the meglitinide category entirely. The industrial consequence is a bifurcation between high-volume generic suppliers and niche innovators pursuing combination therapies. U.S. integrated delivery networks are responding by consolidating formularies around single-source generics with guaranteed supply contracts.
Specialty pharmacy channel capture is displacing traditional retail distribution for Medicare-covered populations, with home delivery and adherence packaging bundled into total cost-of-care contracts. This shift is compressing retail pharmacy margins while elevating data-rich specialty distributors. The transformation is most visible in Florida and Texas, where Medicare Advantage penetration exceeds national averages and payers demand real-world evidence of glycemic control.
North America Meglitinide Market Segmentation
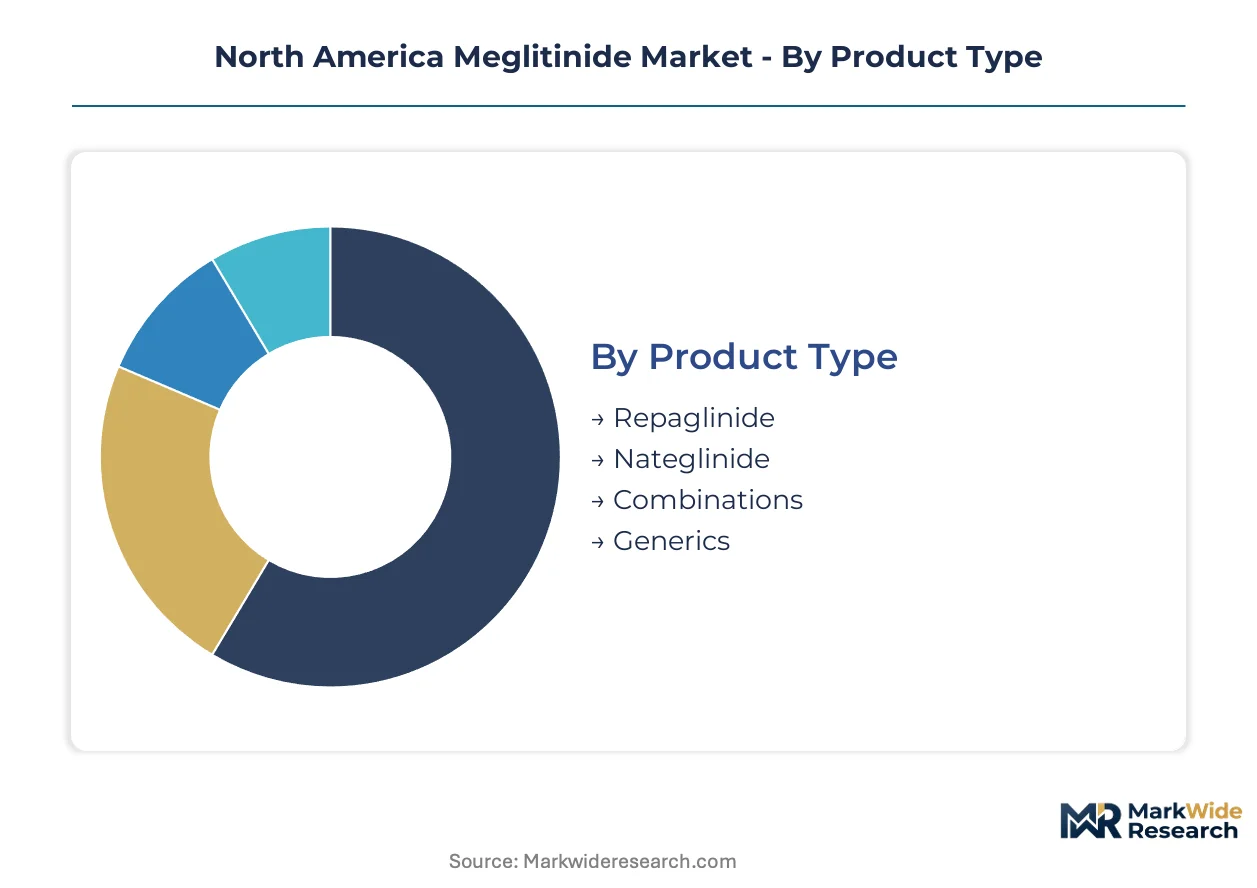
Meglitinide segmentation reveals how regulatory pathways, reimbursement tiers, and clinical settings fragment commercial opportunity across North America. Understanding these divisions exposes where FDA bioequivalence standards and CMS formulary decisions concentrate manufacturer investment.
Product Type:
FDA bioequivalence requirements for complex generics impose distinct certification burdens across molecular variants, with crystallization method patents and polymorph specifications creating divergent litigation exposure for manufacturers.
- Repaglinide:ATP-dependent potassium channel binder with established efficacy data and broader reimbursement coverage across U.S. Medicare formularies. Demand concentrates in integrated health networks managing type 2 diabetes patients with irregular meal patterns, though sulfonylurea substitution pressure limits Medicaid access.
- Nateglinide:D-phenylalanine derivative with shorter onset of action and distinct metabolic profile appealing to endocrinology specialists in Canadian academic medical centers. Ontario and British Columbia provincial formularies favor this agent for prandial glucose regulation in shift workers.
- Combinations:Fixed-dose metformin pairings reduce pill burden and improve adherence metrics.
- Generics:Complex generic pathways governed by FDA bioequivalence guidance accelerate manufacturer entry.
Repaglinide sits at the top of the volume ranking, with combinations climbing the fastest.
End User:
Margin structures vary sharply across delivery settings, with hospital-based initiation protocols commanding premium pricing and homecare channels trading margin for volume scale.
- Hospitals:Academic medical centers capture highest-margin patient encounters through protocol-driven initiation of prandial glucose regulators. Texas and Florida integrated delivery networks bundle meglitinide initiation into total cost-of-care contracts with Medicare Advantage plans.
- Clinics:Outpatient diabetes management programs embed insulin secretagogues into standardized care pathways. U.S. endocrinology practices pilot modified-release formulations for patients with erratic meal timing.
- Homecare:Specialty pharmacy direct-to-patient delivery captures adherence data supporting value-based contracting.
- Pharmacies:Traditional retail distribution faces margin compression from channel migration.
Hospitals retain the premium pricing tier, while homecare is gaining share fastest.
Therapy Area:
Reimbursement codes and clinical evidence requirements stratify addressable populations across metabolic conditions, with type 2 diabetes commanding the most favorable coverage terms.
- Type 2 Diabetes:Core indication driving prescription volume, with prandial glucose regulators serving patients with sulfonylurea intolerance or unpredictable meal schedules. Medicare-covered populations in the United States represent the concentrated demand base.
- Endocrine Disorders:Adjunctive use in polyglandular autoimmune syndromes and insulinoma management.
- Metabolic Syndrome:Off-label utilization for prediabetic populations with postprandial hyperglycemia.
- Obesity:Emerging application in weight management protocols pairing glucose-dependent insulin secretion with appetite regulation.
Type 2 diabetes dominates volume, with metabolic syndrome showing the steepest expansion trajectory.
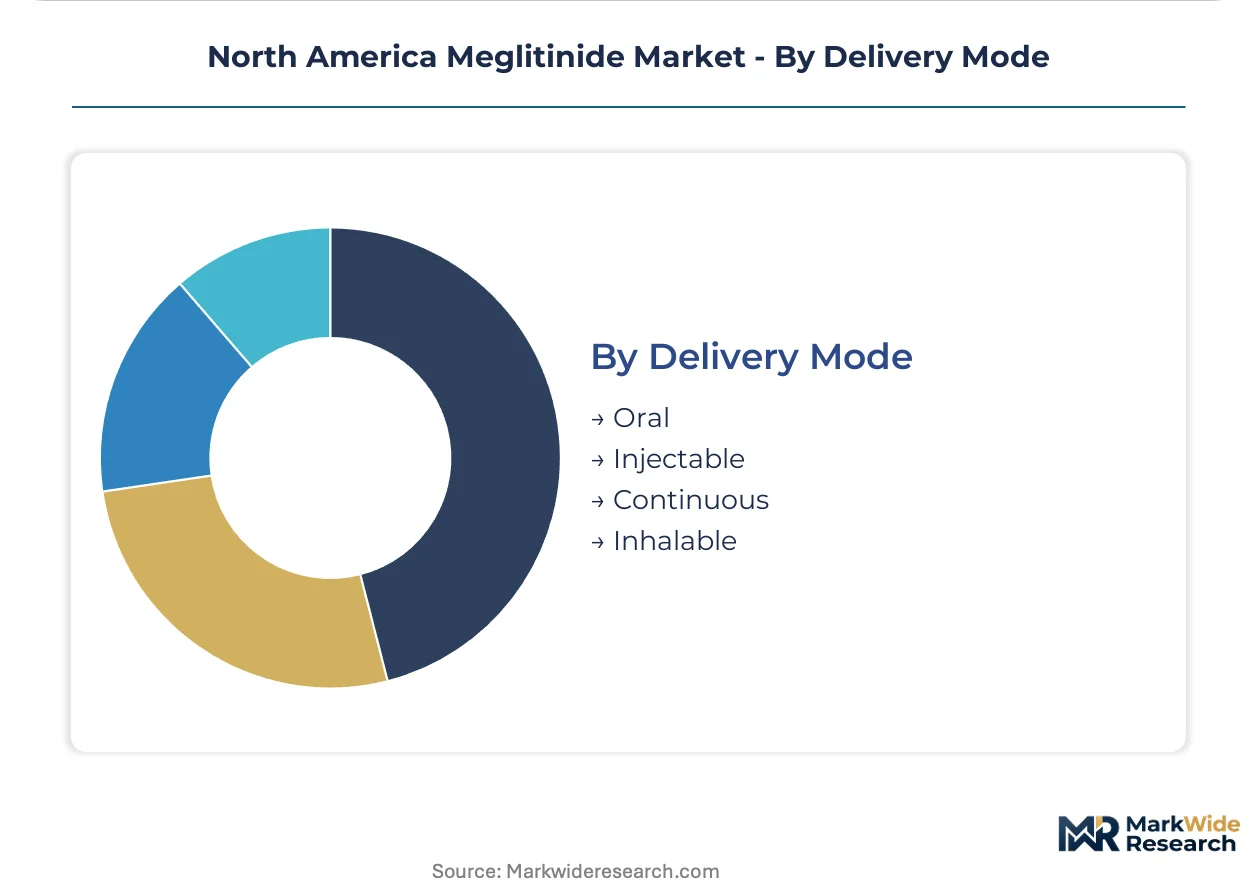
Delivery Mode:
Technology maturity and manufacturing complexity create divergent competitive barriers, with oral formulations benefiting from established supply chains and novel delivery systems requiring capital-intensive platform investment.
- Oral:Immediate-release and modified-release tablet formulations dominate commercial volume, with reformulated excipient platforms enabling dissolution profile optimization. Rapid-dissolution engineering addresses prandial timing requirements for shift workers and frequent travelers.
- Injectable:Subcutaneous delivery systems under development for combination therapy administration.
- Continuous:Experimental closed-loop systems pairing meglitinide dosing algorithms with real-time glucose monitors.
- Inhalable:Early-stage pulmonary delivery research for ultra-rapid prandial insulin secretion.
Oral delivery holds the volume leadership position, with continuous systems advancing most quickly in pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge pharmaceutical corridor anchors North American meglitinide development activity, hosting specialized formulation research and clinical trial infrastructure for prandial glucose regulators.
United States
Medicare-covered populations in Florida and Texas drive concentrated demand through integrated delivery networks bundling diabetes management into Medicare Advantage contracts. FDA bioequivalence guidance on complex generics accelerates manufacturer entry into repaglinide segments. The Research Triangle Park cluster in North Carolina hosts contract research organizations supporting meglitinide formulation studies for regional pharmaceutical firms.
Canada
Ontario and British Columbia provincial formularies favor nateglinide for shift workers with erratic meal patterns, creating distinct prescribing preferences versus U.S. markets. Health Canada Therapeutic Products Directorate review timelines for reformulated excipients extend product launch cycles by 18-24 months versus FDA pathways. The Toronto-Waterloo corridor concentrates generic manufacturing capacity serving provincial pharmacy benefit managers.
Mexico
Private health networks in Mexico City and Monterrey expand outpatient diabetes management programs incorporating meglitinide therapy for type 2 patients with sulfonylurea intolerance. COFEPRIS regulatory alignment with FDA standards facilitates accelerated generic approval pathways for regional manufacturers. The Querétaro pharmaceutical cluster supplies active pharmaceutical ingredients to North American formulators.
North America Meglitinide Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers respond to IRA Medicare price negotiation pressures on branded assets. The vendor base stratifies between high-volume generic suppliers and originator firms pursuing modified-release differentiation. Three archetypes occupy distinct positions: multinational diabetes therapy portfolios, regional generic specialists, and biopharmaceutical innovators. Capacity expansion in rapid-dissolution excipient engineering and strategic partnerships with specialty pharmacy distributors represent the dominant competitive moves reshaping market access.
Among multinational diabetes therapy portfolios, Novo Nordisk leverages its endocrinology franchise depth to sustain formulary relationships across U.S. integrated health networks. Novartis occupies a position anchored in nateglinide brand recognition among academic medical center specialists. Glenmark Pharmaceuticals exemplifies the regional generic specialist archetype through supply contracts with North American pharmacy chains.
| Leading Market Players |
|---|
| Novo Nordisk |
| Novartis |
| Glenmark Pharmaceuticals |
| Boehringer Ingelheim |
| Biocon |
| Sanofi |
| Merck & Co. |
| Pfizer |
| Teva Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Generic-specialist consolidation through private-equity roll-ups has tightened pricing discipline across North American meglitinide supply, linking batch-size economics to formulary tier positioning and squeezing originator margin recovery through volume guarantees rather than list-price premiums.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from South Asian contract manufacturers governs finished-product pricing dynamics across North American formulators. Pricing stratifies across originator brand, authorized generic, and commodity generic tiers, with FDA bioequivalence certification tier and guaranteed supply contracts serving as the primary differentiation drivers. Pricing pressure stems from IRA Medicare price negotiation provisions compressing branded revenue forecasts. State Medicaid programs exhibit highest price sensitivity, while Medicare Advantage integrated delivery networks trade premium pricing for adherence data and total cost-of-care guarantees.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive meglitinide formulations remain underdeveloped, exposing specialty pharmacy distributors to write-off risk from cold-chain excursions and limiting generic manufacturer appetite for just-in-time inventory models. Active pharmaceutical ingredient production concentrates in India and China, with finished-dose formulation in the United States and Canada. Supply chains draw from piperidine derivatives and benzoic acid intermediates as critical chemical inputs. Single-source vulnerability in crystallization-method patents for polymorph-specific repaglinide elevates litigation risk. Distribution runs through specialty pharmacy direct-to-patient channels for Medicare-covered populations and retail pharmacy networks for cash-pay segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Meglitinide Market functions as a regulatory compounder where IRA Medicare price negotiation implementation accelerates manufacturer consolidation and reshapes investment horizons across the diabetes therapy landscape.
For Market Incumbents: Lock in formulary access through multi-year supply guarantees with Ontario and British Columbia provincial pharmacy benefit managers, while accelerating backward integration into rapid-dissolution excipient engineering to defend against sulfonylurea substitution pressure in Medicaid programs. Originators must pursue modified-release differentiation or exit to complex generic platforms before Medicare price negotiation compresses branded assets to commodity economics. For New Entrants and Emerging Players: Continuous glucose monitor convergence algorithms offer a technology-first wedge into tech-enabled diabetes clinics piloting closed-loop prandial insulin management. Target the homecare delivery channel in Florida and Texas Medicare Advantage markets where adherence data monetization remains underpenetrated, and lead with value-based contracting proposals rather than price-based commodity bids. For Investors and Strategic Acquirers: Valuations sit cheapest among regional generic specialists with Health Canada approval pathways and captive API sourcing relationships. Long-term viability hinges on consolidation plays that aggregate provincial formulary negotiation leverage across Ontario, British Columbia, and emerging Mexican private health networks. Monitor CMS formulary tiering decisions for early signals of generic preference acceleration versus originator retention.| Strategic Initiative | Industry Significance |
|---|---|
| Complex Generic Pipeline Investment | IRA provisions force branded manufacturers toward FDA bioequivalence-ready production platforms or category exit. |
| Provincial PBM Consolidation | Ontario and British Columbia single-point negotiations reward manufacturers with broad generic portfolios and guaranteed supply. |
| Specialty Pharmacy Channel Capture | Direct-to-patient delivery bundles adherence data for value-based Medicare Advantage contracting in Florida and Texas. |
| Modified-Release Formulation Development | Rapid-dissolution excipient engineering differentiates originator products on clinical outcomes versus commodity pricing. |
| COFEPRIS Alignment Strategy | Mexican regulatory convergence with FDA standards accelerates generic approval for Querétaro-based regional manufacturers. |
Research Methodology
Multiple input streams — formulary database audits, FDA bioequivalence filing reviews, and provincial pharmacy benefit manager contract disclosures — were reconciled against primary interviews with diabetes therapy portfolio directors, regulatory affairs specialists, and hospital procurement managers. Secondary validation incorporated Health Canada Therapeutic Products Directorate submission timelines, CMS Medicare Part D claims patterns, and SEC 10-K disclosures from listed pharmaceutical manufacturers. Bottom-up prescription volume modeling and top-down revenue reconciliation triangulated market size estimates.
Cross-referencing historical approval-cycle data against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular variant, delivery setting, patient population risk stratification, and regional regulatory cluster. CAGRs derived from patent expiry schedules, generic entry probability assessments, and reimbursement policy trajectory analysis. Forecast inputs incorporated IRA Medicare price negotiation implementation pace and continuous glucose monitor adoption curves in integrated delivery networks.
The model holds under stable FDA bioequivalence guidance and IRA implementation timelines; deviation in Health Canada review cycle extensions or API export restriction triggers would shift generic entry assumptions. Practitioners should monitor CMS formulary tiering decisions and South Asian customs clearance patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Global Antacids Market