
 Desloratadine Market | 2026-2036
Desloratadine Market Size, Share, and Industry Trends Forecast 2026-2036
Desloratadine Market Analysis
Retail pharmacy distribution is fragmenting as online pharmacy channels capture chronic medication refills and hospital pharmacy networks tighten formulary control. Pfizer leverages its respiratory portfolio breadth to sustain shelf presence across major retail chains. Teva anchors the generic desloratadine segment through bioequivalence investments and cost-competitive manufacturing scale. Cipla competes in emerging markets with localized production and regulatory dossier expertise.
Desloratadine is a selective, non-sedating H1-receptor antagonist, the active metabolite of loratadine, formulated for once-daily administration with a half-life of approximately 27 hours and minimal blood-brain barrier penetration. The compound serves primarily as a second-generation antihistamine for allergic rhinitis and chronic idiopathic urticaria management. Tablet formulations dominate volume due to manufacturing simplicity and patient compliance, while rapid-dissolve films represent the fastest-expanding format among pediatric and geriatric populations seeking swallowing alternatives. The allergic rhinitis therapy area occupies the largest revenue pool, though chronic urticaria applications command premium pricing through specialist channel access.
FDA bioequivalence standards and EMA quality guidelines shape product development timelines and generic substitution rules across developed markets. India's CDSCO and BIS frameworks govern active pharmaceutical ingredient purity and export certification for contract manufacturers supplying multinational firms. Stakeholders must monitor evolving pharmacovigilance requirements and regional pricing controls that could reshape margin structures without warning.
Market Dynamics
FDA bioequivalence standards for generic antihistamines are compressing manufacturing timelines while elevating quality barriers, forcing reformulation investments that reshape competitive positioning across the value chain.
Growth Catalysts
- Pediatric prescription expansion:Rising diagnosis rates for allergic rhinitis in children under 12 are broadening the addressable patient population for age-appropriate formulations.
- EMA quality guideline harmonization:Unified standards across EU member states are reducing regulatory duplication costs for manufacturers seeking multi-country market access.
- Rapid-dissolve film technology:Orodispersible formats are capturing geriatric and dysphagia-averse patient segments previously lost to liquid alternatives.
Market Restraints
- Active pharmaceutical ingredient concentration:Indian contract manufacturers control over 70% of desloratadine API supply, creating geographic single-point vulnerability.
- FDA bioequivalence study costs:Generic entrants face $2-4 million per ANDA submission for pharmacokinetic bridging trials.
- Second-generation antihistamine substitution:Fexofenadine and levocetirizine formulations compete on comparable efficacy with established payer preference.
Strategic Opportunities
- Chronic urticaria specialist channel:Dermatology and allergy clinic networks offer premium pricing access for indication-specific labeling.
- Online pharmacy direct fulfillment:Amazon Pharmacy and Capsule are capturing recurring refill volumes from retail chain defections.
- CDSCO accelerated approval pathway:India's streamlined review for essential medicines reduces time-to-market for localized production investments.
Industry Challenges
- Bioanalytical method transfer:CRO capacity constraints delay pharmacokinetic study initiation by 4-6 months.
- Legacy ERP integration:Serialization requirements for track-and-trace compliance strain mid-tier manufacturers with outdated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desloratadine Market |
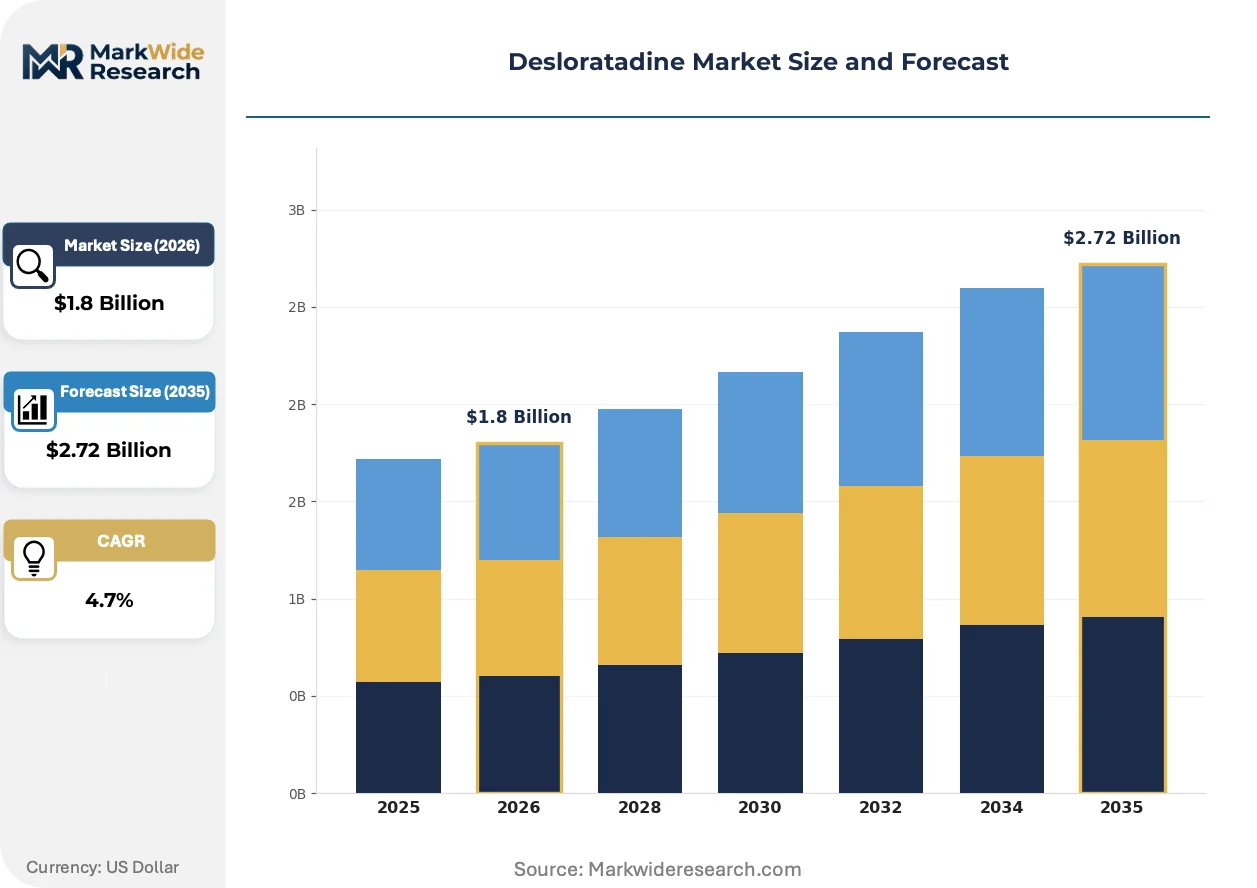
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Syrups, Oral Drops, Capsules, Rapid-Dissolve Films Therapy Area: Allergic Rhinitis, Chronic Urticaria, Atopic Dermatitis, Pruritus, Hay Fever End User: Pharmacies, Hospitals, Specialty Clinics, Healthcare Centers, Drug Stores Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Direct Sales, Wholesale |
| Companies Covered | GlaxoSmithKline, Takeda, Pfizer, Mayne Pharma, Abbott, Teva, Mylan, Cipla, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desloratadine Market Emerging Trajectories
Formulation science and distribution infrastructure are undergoing parallel transformation, with patient-centric delivery formats and direct-to-patient logistics models converging to reshape how antihistamines reach chronic users.
Hot-melt extrusion technology for amorphous solid dispersions is rendering obsolete traditional wet granulation processes for poorly soluble active metabolites. European CMOs including Catalent and Lonza have installed dedicated continuous manufacturing lines. This capability compression is enabling 24-hour batch-to-batch release cycles that accelerate generic substitution timelines.
EMA's revised guideline on clinical investigation of medicinal products in the treatment of allergic rhinitis now mandates symptom diary digitalization for primary endpoint capture. Sponsors must deploy ePRO platforms with geolocation validation to demonstrate seasonal exposure correlation. Phase III trial designs for desloratadine line extensions are incorporating smartphone pollen count integration to satisfy assessor expectations.
Subscription-based chronic medication management is displacing episodic pharmacy visits for seasonal allergy sufferers. CVS Caremark and Express Scripts have introduced auto-refill programs with adherence monitoring incentives. This behavioral pivot concentrates most visible in the United States, where direct-to-consumer advertising has preconditioned patients to brand-seek even for generic equivalents.
Desloratadine Market Segmentation
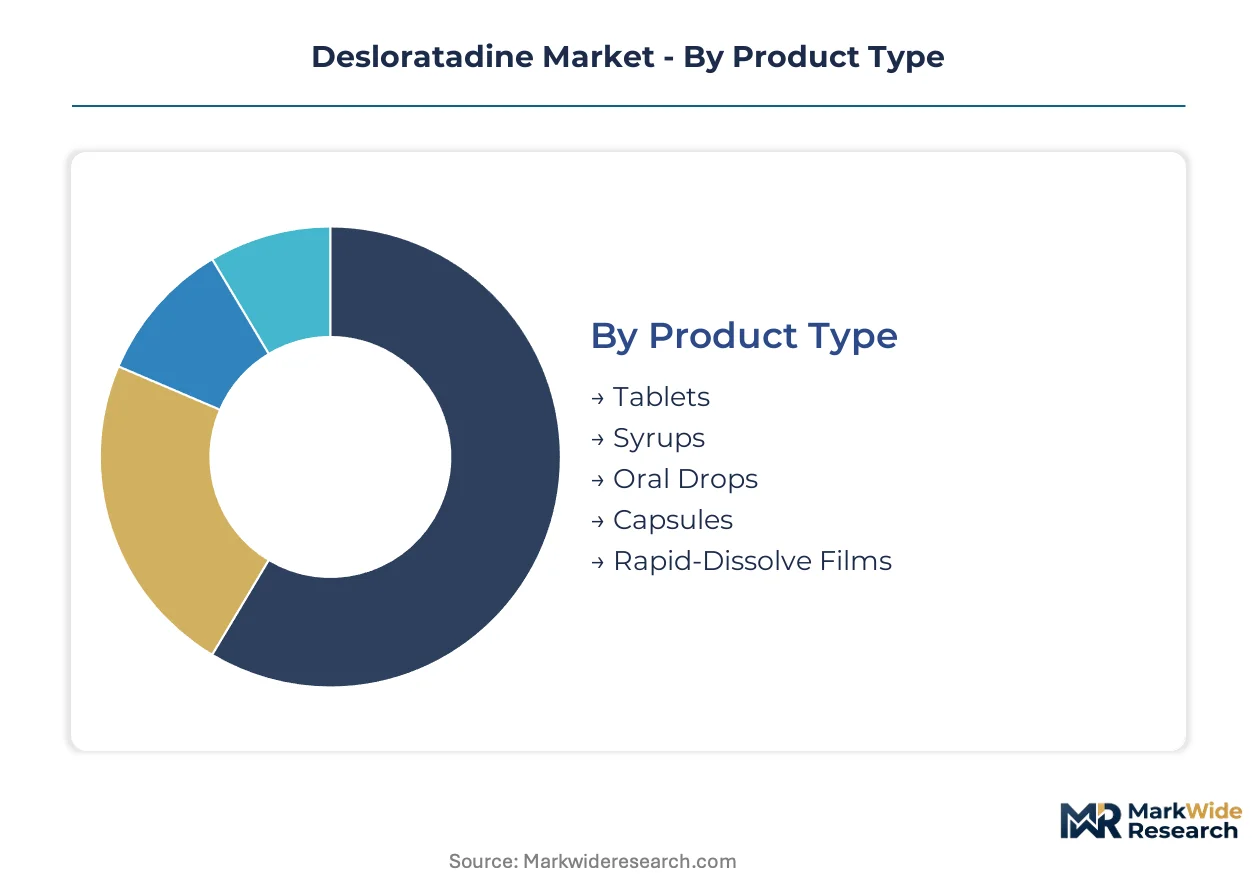
Desloratadine's formulation diversity and therapy breadth create distinct competitive arenas where manufacturing scale, regulatory pathway, and channel access determine margin capture. Each segment carries unique bioequivalence burdens and patient compliance profiles that reshape investment priorities across the value chain.
Product Type:
Use-case spectrum spans acute symptomatic relief through chronic maintenance, with format selection driven by patient age, swallowing capability, and prescriber setting.
- Tablets:Compressed solid dosage forms containing desloratadine as the active pharmaceutical ingredient, manufactured through direct compression or wet granulation. Demand concentrates in the United States retail pharmacy channel where once-daily dosing aligns with chronic allergy management protocols and insurance formulary preferences.
- Rapid-Dissolve Films:Orodispersible polymer matrices that disintegrate on the tongue without water, utilizing hot-melt extrusion or solvent casting. Pediatric and geriatric populations in Germany and France are adopting this format fastest as dysphagia-friendly alternatives to traditional solids, though manufacturing complexity elevates unit costs.
- Syrups:Liquid oral suspensions with defined concentration per milliliter for weight-based pediatric dosing.
- Oral Drops:Concentrated liquid formulations enabling precise titration for infants and toddlers.
- Capsules:Hard gelatin or HPMC shells containing desloratadine granules or powder blends.
Established volume favors Tablets; emerging adoption favors Rapid-Dissolve Films.
Therapy Area:
Margin structure varies sharply across indication-specific labeling, with specialist channel access commanding premium positioning versus primary care commoditization.
- Allergic Rhinitis:Seasonal and perennial nasal inflammation management representing the foundational indication for desloratadine approval. Volume concentrates in United States and United Kingdom primary care settings where direct-to-consumer advertising and pharmacy substitution rules drive generic penetration.
- Chronic Urticaria:Recurrent wheal-and-flare skin condition requiring continuous antihistamine suppression. Dermatology and allergy clinic networks in Switzerland and Australia offer premium pricing access for indication-specific labeling that supports higher reimbursement tiers.
- Atopic Dermatitis:Eczema-associated pruritus as adjunctive antihistamine therapy.
- Pruritus:Generalized itching of various etiologies including drug reactions and renal impairment.
- Hay Fever:Seasonal allergic rhinitis triggered by pollen exposure, often self-diagnosed.
Primary care volume favors Allergic Rhinitis; specialist premium capture favors Chronic Urticaria.
End User:
Procurement authority and formulary control determine pricing leverage, with institutional buyers extracting concessions unavailable in fragmented retail settings.
- Pharmacies:Community and chain dispensaries serving ambulatory patients with prescription and over-the-counter fulfillment. United States independent pharmacies and CVS, Walgreens, and Rite Aid networks control the majority of chronic refill volume through auto-renewal programs and adherence incentives.
- Specialty Clinics:Dermatology and allergy-focused practices with prescriber influence over brand selection. Concentrated demand in urban United States markets and London private practice clusters where physician preference overrides payer substitution mandates.
- Hospitals:Inpatient and emergency department settings for acute allergic presentations.
- Healthcare Centers:Federally qualified health centers and community clinics serving underserved populations.
- Drug Stores:Mass merchandisers and convenience-oriented retail with limited pharmacy services.
Recurring refill volume favors Pharmacies; prescriber autonomy favors Specialty Clinics.
Distribution Channel:
Logistics infrastructure and patient touchpoint frequency are reshaping channel economics as digital fulfillment captures chronic medication management.
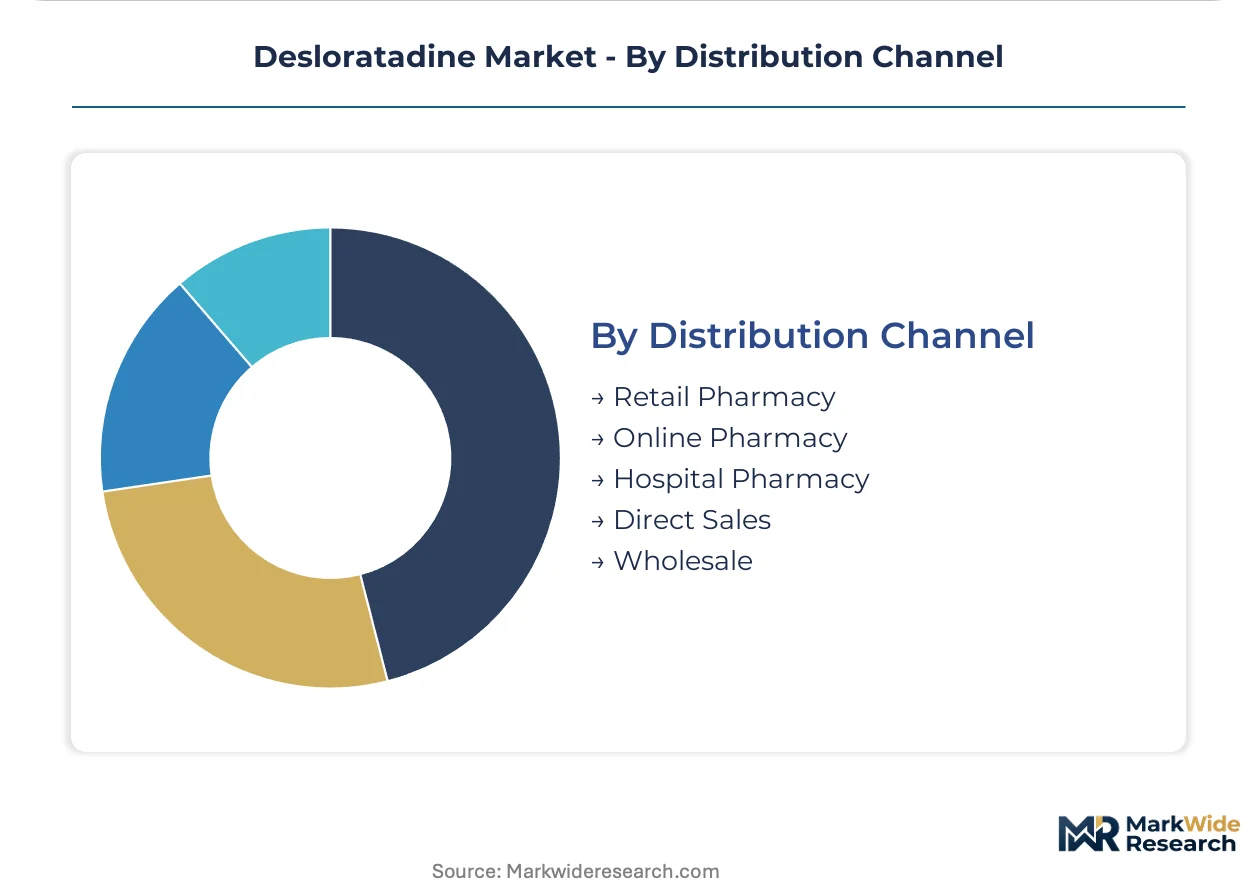
- Retail Pharmacy:Brick-and-mortar dispensaries with immediate product availability and pharmacist counseling. United States chain networks maintain formulary control through PBM-owned pharmacies, though shelf space compression is forcing brand-generic substitution at point of sale.
- Online Pharmacy:Direct-to-patient shipping platforms capturing recurring refill volumes. Amazon Pharmacy, Capsule, and PillPack are expanding fastest in United States metropolitan markets where patients prioritize convenience over immediate access.
- Hospital Pharmacy:Captive dispensaries serving inpatient and discharge prescription needs.
- Direct Sales:Manufacturer-to-institution contracting for large health systems.
- Wholesale:Distributor intermediaries stocking independent pharmacies and smaller chains.
Immediate access dependence favors Retail Pharmacy; convenience-seeking behavior favors Online Pharmacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European distribution reach for antihistamine formulations, while the Trans-Siberian rail corridor links Indian API manufacturers to Moscow's wholesale markets.
United States
Seasonal allergy prevalence drives prescription volumes across the Sun Belt and Midwest, with pollen monitoring networks expanding coverage. FDA bioequivalence requirements for generic antihistamines elevate manufacturing standards for ANDA submissions. New Jersey's pharmaceutical corridor hosts formulation development labs serving both innovator and generic sponsors.
Germany
Pediatric allergic rhinitis diagnosis rates are climbing in Bavaria and North Rhine-Westphalia, broadening demand for age-appropriate formulations. EMA quality guideline harmonization reduces regulatory duplication costs for multi-country market access. Frankfurt's logistics hub concentrates distribution for Central European pharmacy networks.
India
Contract manufacturers supply over 70% of desloratadine API to multinational firms, anchoring global raw material flows. CDSCO accelerated approval pathways for essential medicines compress time-to-market for localized production. Hyderabad's bulk drug cluster hosts synthesis facilities serving European and North American formulation partners.
United Kingdom
Pharmacy substitution rules and direct-to-consumer advertising sustain brand recognition in primary care settings. NHS formulary controls extract pricing concessions from suppliers competing for chronic medication contracts. London's specialist clinic networks command premium access for chronic urticaria indication labeling.
Australia
Seasonal hay fever patterns in Melbourne and Sydney sustain recurring antihistamine demand through community pharmacy channels. TGA pharmacovigilance requirements shape post-market surveillance obligations for imported formulations. Sydney's hospital pharmacy networks tighten formulary control over inpatient and discharge prescriptions.
Desloratadine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying active pharmaceutical ingredients and contract manufacturing services. The market structures around three tiers: multinational innovators with respiratory portfolio breadth, generic manufacturers with bioequivalence scale, and emerging market producers with localized regulatory expertise. Consolidation pressures concentrate among mid-tier manufacturers facing serialization compliance costs, while capacity expansion and geographic diversification represent the dominant competitive vectors.
Among the established pharmaceutical houses, Pfizer exemplifies platform breadth across respiratory and allergy portfolios, while Teva and Cipla occupy positions at the generic manufacturing and emerging market access poles respectively. These anchors represent the strategic archetypes—portfolio integrators, bioequivalence-scale producers, and regulatory-dossier specialists—through which competitive dynamics channel.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Takeda |
| Pfizer |
| Mayne Pharma |
| Abbott |
| Teva |
| Mylan |
| Cipla |
| Novartis |
| Others |
Supply Flow & Price Mechanics
Hyderabad's bulk drug cluster anchors global desloratadine API flows, concentrating synthesis capacity in a single Indian province that feeds formulation partners across North America and Europe. This geographic tightness amplifies pricing leverage for contract manufacturers while exposing downstream brands to input cost volatility when regional logistics face disruption.
Pricing Analysis
Volume-discount tiering separates hospital system contracts from retail pharmacy procurement and specialist clinic direct purchasing. Hospital formulary directors extract steep concessions through consolidated annual tenders, while dermatology clinics in Switzerland and Australia accept premium positioning for indication-specific chronic urticaria labeling. Price differentiation hinges on bioequivalence certification tier and geographic delivery logistics, with FDA-validated ANDA holders commanding spreads over emerging market alternatives. Cost compression in the generic tablet segment is intensifying as Indian API suppliers expand captive formulation capacity, squeezing pure-play finished dose manufacturers. Retail chain procurement teams demonstrate highest price sensitivity, whereas specialist prescriber networks prioritize clinical profile over unit cost.
Supply Chain Analysis
Upstream feedstock for desloratadine synthesis draws from specialized chemical intermediates produced in Gujarat and Maharashtra industrial corridors, with final API concentration reaching European and North American formulation sites. Active pharmaceutical ingredient manufacturing rests on piperidine derivatives and tricyclic precursor chemicals sourced through established fine chemical distributors. Single-source vulnerability concentrates in the 70%-plus Indian API share, where regulatory inspections or environmental compliance actions could interrupt global finished dose availability. Distribution runs through Rotterdam's pharmaceutical cold-chain hub for European pharmacy networks, while direct air freight serves United States generic sponsors operating on just-inventory cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Desloratadine demand tracks seasonal allergy prevalence cycles that rebound reliably following low-pollen years, positioning the market for volume recovery as climate patterns shift. Pediatric prescription expansion and geriatric formulation innovation provide countercyclical growth anchors.
For Market Incumbents: Entrench formulary control through bioequivalence study investments that raise ANDA barriers for prospective entrants, while securing multi-year hospital system contracts before generic substitution rules tighten. Pfizer and Teva should deepen backward integration into Indian API supply through equity stakes or offtake guarantees, mitigating geographic concentration risk that threatens margin stability.
For New Entrants and Emerging Players: Rapid-dissolve film formats for dysphagia-averse pediatric and geriatric populations in Germany and France represent the most penetrable entry point, bypassing commoditized tablet competition where incumbents hold scale advantages. CDSCO accelerated approval pathways enable time-to-market compression for localized Indian production serving domestic and export markets. A go-to-market angle through Amazon Pharmacy and Capsule direct fulfillment captures recurring refill volumes without retail chain shelf space battles.
For Investors and Strategic Acquirers: Long-term, this sits as a steady-state cash flow play because chronic allergy medication demand exhibits low elasticity to economic cycles and generates predictable refill revenue. Acquisition targets should display orodispersible formulation capabilities or established specialist clinic channel relationships in premium pricing markets like Switzerland and Australia. The signal to watch is FDA inspection frequency at Indian API facilities, which would foreshadow supply disruption and pricing volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Extrusion Manufacturing Scale-Up | Catalent and Lonza continuous processing lines enable 24-hour batch release for rapid-dissolve formats. |
| EMA Quality Guideline Harmonization | Unified EU standards reduce regulatory duplication costs for multi-country desloratadine launches. |
| Online Pharmacy Direct Fulfillment Partnership | Amazon Pharmacy auto-refill programs capture chronic medication volumes from retail chain defections. |
| CDSCO Accelerated Approval Pathway | India's streamlined essential medicines review compresses time-to-market for localized production investments. |
| Chronic Urticaria Specialist Channel Access | Dermatology clinic networks in Switzerland command premium reimbursement tiers for indication-specific labeling. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regulatory affairs directors at generic sponsors, formulary managers at United States pharmacy benefit managers, and procurement leads at Indian contract manufacturing organizations. Secondary validation drew from FDA ANDA filings, EMA quality guideline documentation, ClinicalTrials.gov protocol registries, and CDSCO approval databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical market sizing from trade flow and customs records.
Calibration against historical generic substitution rates and seasonal allergy prevalence indices anchored the analytical framework across the projection horizon. Segmentation dimensions included dosage form complexity, therapy area indication, distribution channel logistics model, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation moderated by patent expiry timing and bioequivalence study completion rates. Forecast inputs incorporated pollen monitoring network expansion data and pediatric diagnosis rate trajectories.
Practitioners should monitor FDA inspection scheduling at Indian API facilities and EMA pharmacovigilance guideline revisions for early signals of supply or regulatory constraint. Forecasts embed assumptions regarding continued bioequivalence study cost structures and seasonal allergy prevalence stability that material shifts could invalidate. Cross-checking against IQVIA prescription audit data and hospital procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market