
 Pharmacy Dark Store Market | 2026-2036
Pharmacy Dark Store Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacy Dark Store Market Insights
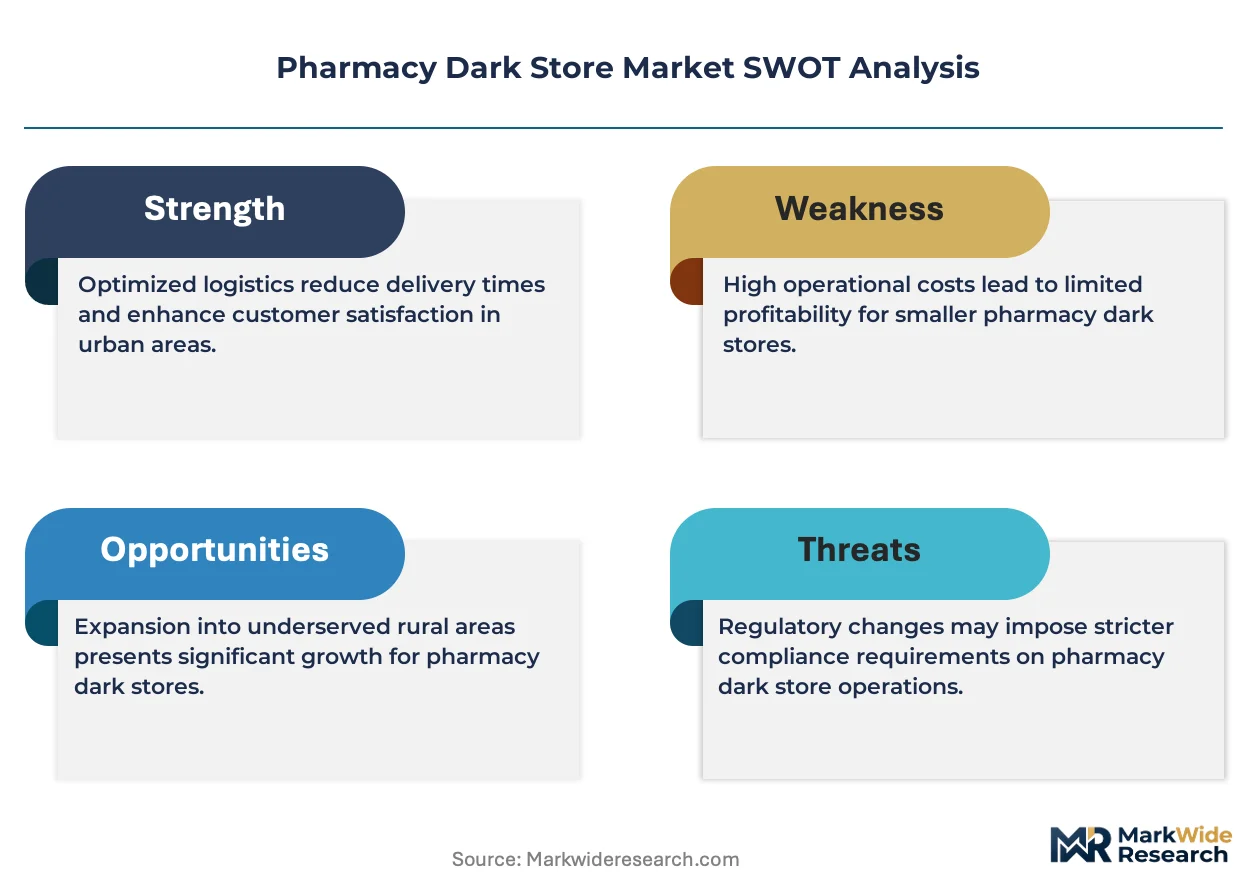
FDA's 503B outsourcing facility regulations is broadening the cost-of-entry calculus for entities seeking to operate central-fill pharmacy operations without retail storefronts. Amazon leverages its robotics-heavy fulfillment architecture to sustain same-day prescription delivery density in major metropolitan zones. Kroger anchors its dark store strategy around vertical integration with its existing grocery logistics backbone. Walgreens Boots Alliance competes through specialized cold-chain infrastructure that supports biologic medication storage requirements.
Pharmacy dark stores represent dedicated, non-customer-facing fulfillment centers where prescription and over-the-counter medications are stored, picked, packed, and dispatched using automated systems and pharmacy technicians under remote pharmacist oversight. These facilities typically maintain temperature zones ranging from ambient to frozen, employ barcode-verification workflows, and integrate directly with pharmacy benefit managers and prescriber electronic health record systems to process refill authorizations. Prescription Drugs dominates product type revenue due to recurring refill volumes and higher per-order values, while Telepharmacy Consultation within service type exhibits the fastest structural expansion as synchronous video counseling satisfies regulatory counseling requirements without on-site pharmacists. Chronic Patients within customer type generates the most predictable demand profile, though Busy Professionals drives premium same-day delivery attach rates.
FDA oversight of 503B compounding and state board of pharmacy licensure requirements collectively determine facility design standards, staffing ratios, and permissible dispensing geographies for dark store operators. DSCSA serialization mandates and state-level pedigree laws shape inventory tracking technology investments and partner qualification protocols. Stakeholders must monitor evolving state-level scope-of-practice expansions for pharmacy technicians and remote pharmacist supervision rules, as these regulatory variables will determine whether dark store economics achieve unit-cost parity with traditional retail pharmacy fulfillment.
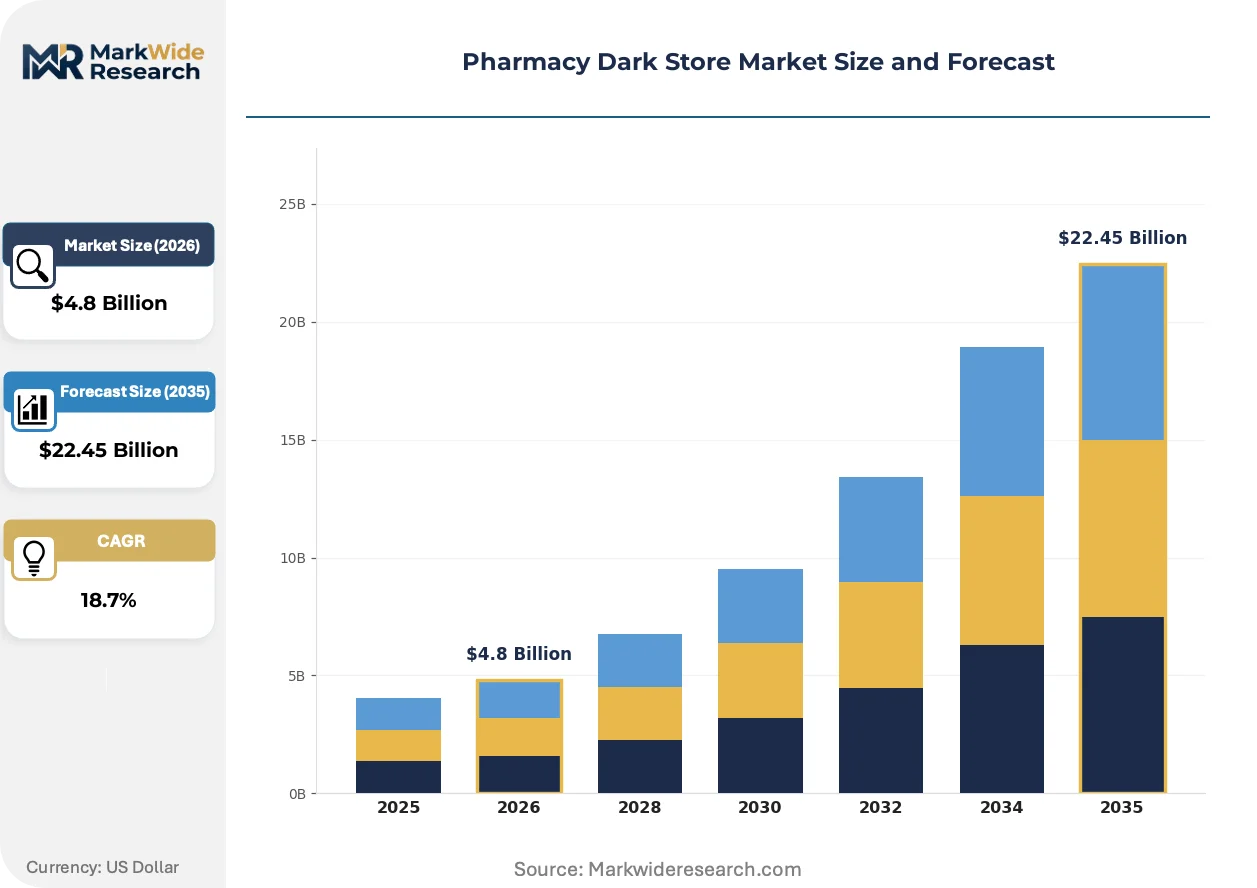
Market Dynamics
Central-fill pharmacy automation is compressing per-prescription labor costs while DSCSA track-and-trace mandates force wholesale infrastructure upgrades across the fulfillment network.
Growth Catalysts
- FDA 503B outsourcing facility framework:Regulatory clarity around non-retail compounding permits hospital systems to consolidate sterile preparation into dedicated dark store facilities without retail storefront overhead.
- Robotic dispensing cell technology:Automated pill-counting and verification systems reduce technician labor per script by half while maintaining accuracy rates above retail pharmacy benchmarks.
- Integrated health network consolidation:Multi-hospital systems in the United States are centralizing outpatient pharmacy fulfillment to capture scale economies in purchasing and inventory management.
Market Restraints
- Cold-chain infrastructure capex:Biologic medications requiring frozen storage demand specialized HVAC and backup power systems that inflate facility buildout costs substantially above ambient-only operations.
- State-level pharmacist supervision rules:Variation in board of pharmacy requirements for remote oversight creates operational friction for multi-state dark store networks.
- Limited 340B contract pharmacy eligibility:Restrictions on which entities qualify for federal drug pricing discounts constrain addressable volume for certain dark store operators.
Strategic Opportunities
- Specialty medication concentration:Oncology and immunology biologics with high per-dose values justify premium cold-chain infrastructure investments that generalist retail pharmacies cannot replicate.
- Synchronous telepharmacy counseling:Video-based patient consultation platforms satisfy regulatory counseling requirements while enabling technician-staffed facilities in underserved rural counties.
- Same-day delivery density zones:Urban cluster fulfillment networks anchored in major metropolitan areas capture recurring refill volumes from chronic patient populations.
Industry Challenges
- Pharmacy technician certification pipelines:State-mandated training hours and examination requirements create bottlenecks in staffing scaled operations.
- DSCSA serialization system integration:Legacy warehouse management platforms require expensive retrofitting to achieve unit-level traceability compliance by statutory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacy Dark Store Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Health Supplements, Medical Devices, Wellness Products Service Type: Home Delivery, Click & Collect, Telepharmacy Consultation, Subscription Services, Emergency Refill Customer Type: Chronic Patients, Elderly Consumers, Busy Professionals, Caregivers, Healthcare Providers Distribution Channel: Online Platforms, Mobile Apps, Call Centers, Partner Pharmacies, Automated Kiosks |
| Companies Covered | Amazon, Walmart, Target Brands, Instacart, Kroger, Ocado, Albertsons, CVS Health, Walgreens Boots Alliance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacy Dark Store Market Trends and Innovations
Automation architecture is fragmenting into configurable subsystems that dark store operators can deploy incrementally rather than through monolithic capital commitments.
Autonomous mobile robotics for inventory transport is modularizing fulfillment floor layouts. Hospital-affiliated dark stores are deploying these systems in phased rollouts across ambient and refrigerated zones. The technology is modularizing how operators scale throughput without proportional facility expansion.
EMA's forthcoming guidance on remote pharmacy supervision is pressuring European operators to invest in audit-ready video documentation systems. The industrial consequence is accelerated procurement of integrated telepharmacy platforms that combine counseling, verification, and compliance logging. Hospital systems in Germany and France are responding by consolidating national fulfillment networks under centralized pharmacist oversight hubs.
Chronic patient refill behavior is compressing toward synchronized 90-day cycles aligned with insurance benefit structures. Mail-order and same-day delivery channels are displacing traditional 30-day retail pickup patterns among commercially insured populations. This shift concentrates most visibly in United States metropolitan corridors where benefit design and logistics density coincide.
Pharmacy Dark Store Market Segmentation
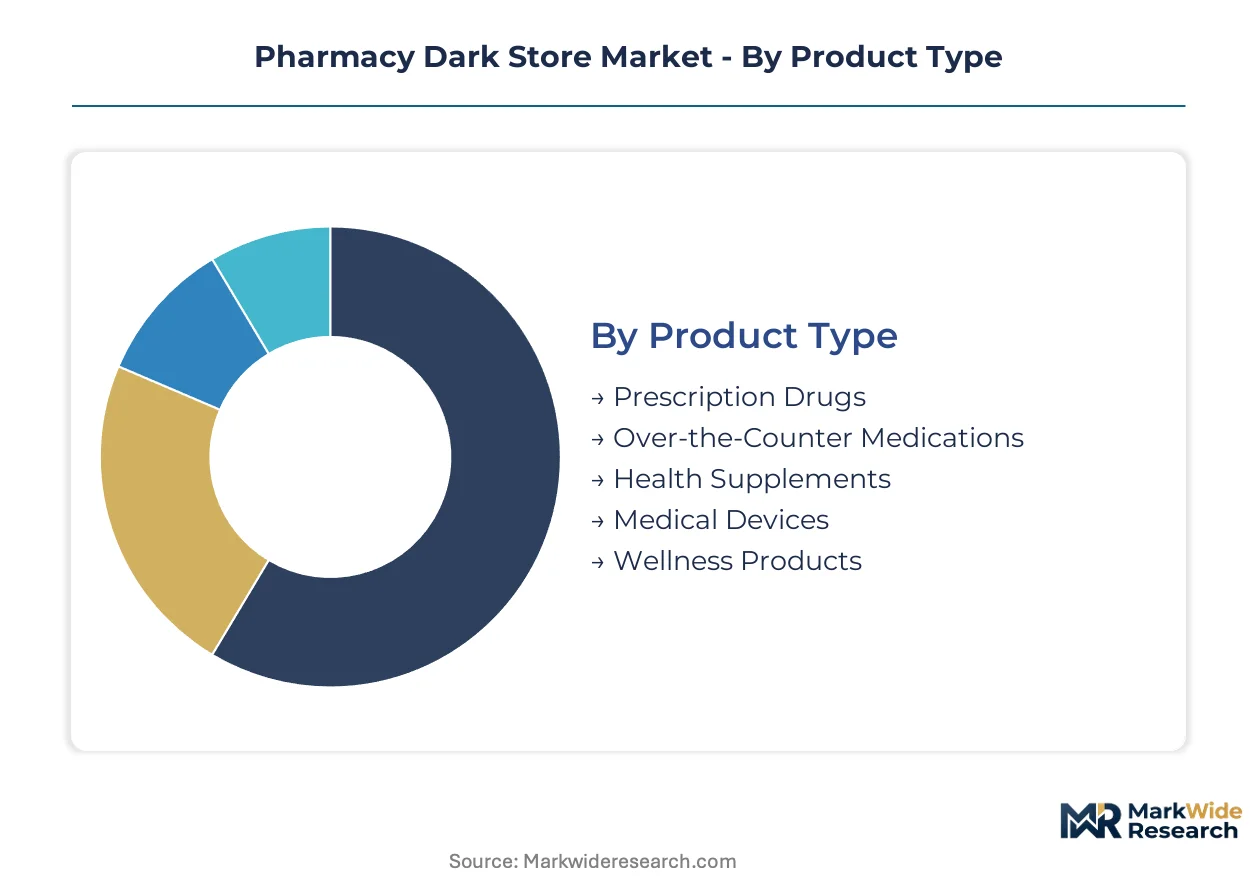
Segmentation in pharmacy dark stores reveals divergent infrastructure requirements across product temperature classes and counseling modalities. Each dimension carries distinct regulatory footprints and automation investment profiles that reshape facility design economics.
Product Type:
Volume concentration favors high-velocity categories with recurring refill patterns, while premium margins attach to temperature-controlled biologics requiring specialized handling infrastructure.
- Prescription Drugs:Chronic medication categories—antihypertensives, statins, diabetes therapies—generate predictable replenishment cycles that justify robotic dispensing cell deployment. Demand clusters in United States metropolitan corridors where integrated health networks centralize outpatient fulfillment under FDA 503B outsourcing frameworks.
- Over-the-Counter Medications:Analgesics, cold remedies, and digestive aids move through ambient-temperature zones with minimal regulatory friction. United States same-day delivery networks attach these items to prescription orders, driving basket economics in urban density zones.
- Health Supplements:Vitamins and nutraceuticals occupy fulfillment floor space with lower per-cube value than pharmaceuticals.
- Medical Devices:Glucose monitors and inhalers require distinct packaging workflows and patient instruction protocols.
- Wellness Products:Skincare and personal care items compete for shelf space with lower margin profiles than core pharmacy categories.
Today's leader: Prescription Drugs. Tomorrow's challenger: Over-the-Counter Medications.
Service Type:
Service configuration determines staffing models and technology stack investments, with synchronous counseling capabilities unlocking rural market access under evolving supervision rules.
- Telepharmacy Consultation:Video-based synchronous counseling satisfies state board of pharmacy requirements for patient consultation without on-site pharmacist presence. United States rural counties and German hospital networks deploy these platforms to extend coverage into technician-staffed facilities.
- Home Delivery:Same-day and next-day fulfillment networks anchor urban market share for chronic patient populations. United States logistics density in major metropolitan zones enables competitive delivery windows that retail pharmacies cannot match.
- Click & Collect:Curbside and locker-based pickup options bridge digital ordering with physical retrieval convenience.
- Subscription Services:Automated 90-day refill programs align with insurance benefit structures and improve adherence metrics.
- Emergency Refill:Urgent same-day processing for acute medication needs commands premium pricing and specialized inventory positioning.
Telepharmacy Consultation is climbing the fastest as regulatory acceptance of remote supervision expands addressable geography.
Customer Type:
Patient lifecycle stage and care dependency level segment operational complexity, from automated refill management to caregiver coordination protocols.
- Chronic Patients:Diabetes, cardiovascular, and respiratory condition populations generate 90-day synchronized refill demand that maximizes robotic dispensing utilization. United States Medicare Part D and commercial benefit designs concentrate volume in mail-order and same-day channels.
- Elderly Consumers:Polypharmacy management and medication adherence support require enhanced packaging and counseling touchpoints. Caregiver coordination protocols add operational layers to fulfillment workflows.
- Busy Professionals:Commercially insured urban populations drive premium same-day delivery attach rates and mobile-first ordering behavior.
- Caregivers:Proxy ordering for dependent patients necessitates identity verification and authorization workflows.
- Healthcare Providers:Hospital discharge and clinic-based prescribing generates institutional volume with distinct billing and prior authorization requirements.
Chronic Patients dominate current volume. Busy Professionals represent the steepest expansion trajectory for premium service tiers.
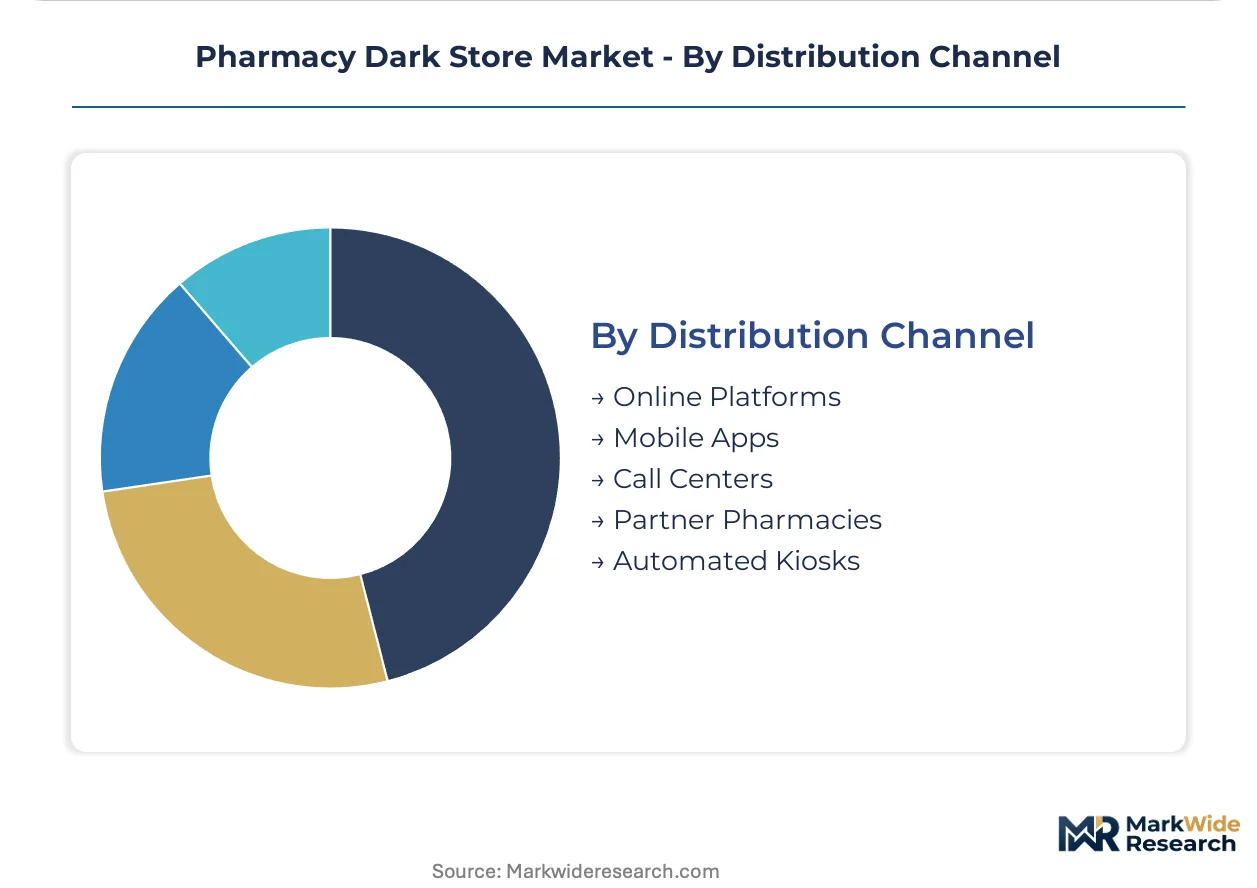
Distribution Channel:
Channel selection reflects patient digital literacy and urgency requirements, with mobile interfaces capturing growing share among working-age populations.
- Mobile Apps:Prescription management, refill scheduling, and delivery tracking consolidate into unified patient interfaces. United States health systems and retail pharmacy chains prioritize native app development for chronic patient retention.
- Online Platforms:Web-based ordering serves desktop-preferred demographics and complex multi-medication transactions. EHR-integrated portals streamline prior authorization workflows for specialty medications.
- Call Centers:Voice-based ordering persists among elderly populations and urgent refill scenarios.
- Partner Pharmacies:Physical retail locations serve as pickup points and last-mile delivery nodes for dark store networks.
- Automated Kiosks:Locker-based retrieval systems extend pickup convenience into non-traditional hours and locations.
Mobile Apps command current investment priority. Automated Kiosks are gaining share fastest in campus and employer settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy technicians and automation engineers concentrate in jurisdictions where FDA 503B clarity and DSCSA mandates have matured, anchoring facility investment decisions to regulatory predictability.
United States
Hospital systems and integrated health networks drive demand for central-fill automation in metropolitan corridors. FDA 503B outsourcing facility regulations permit sterile compounding consolidation without retail storefront overhead. The Dallas-Fort Worth metroplex hosts multiple dark store facilities serving regional health networks with same-day delivery density.
Germany
Hospital network consolidation creates procurement scale for centralized pharmacy fulfillment. EMA guidance on remote pharmacy supervision pressures operators toward audit-ready video documentation systems. The Rhine-Ruhr industrial corridor anchors national fulfillment networks under centralized pharmacist oversight hubs.
United Kingdom
NHS trust outsourcing generates institutional volume for dedicated non-retail pharmacy facilities. MHRA alignment with EMA serialization standards shapes inventory tracking technology investments. The Greater London area concentrates same-day delivery infrastructure for chronic patient populations.
France
Regional hospital groups centralize outpatient pharmacy fulfillment to capture purchasing economies. ANSM oversight of sterile compounding determines facility design standards and staffing ratios. The Île-de-France region deploys telepharmacy platforms to extend coverage into technician-staffed rural facilities.
Canada
Provincial health authority outsourcing creates demand for automated dispensing in urban clusters. Health Canada and PMRA track-and-trace mandates align with DSCSA-equivalent serialization requirements. The Greater Toronto Area anchors cold-chain infrastructure for biologic medication distribution networks.
Pharmacy Dark Store Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fulfillment infrastructure tiers. The vendor base separates into three structural layers: integrated retail-healthcare hybrids, dedicated pharmacy automation firms, and logistics-platform entrants. Consolidation pressure concentrates among hospital-affiliated operators seeking captive supply control. Dominant competitive moves include strategic partnerships with pharmacy benefit managers and capacity expansion into specialty medication cold-chain zones.
Among integrated retail-healthcare operators, Amazon, Kroger, and Walgreens Boots Alliance occupy distinct archetype positions. Amazon exemplifies the logistics-platform model leveraging robotics-heavy fulfillment architecture for metropolitan same-day density. Kroger represents vertical integration with grocery logistics backbone for cost-positioned central-fill operations. Walgreens Boots Alliance anchors the specialized cold-chain tier supporting biologic storage requirements that generalist competitors cannot replicate.
| Leading Market Players |
|---|
| Amazon |
| Walmart |
| Target Brands |
| Instacart |
| Kroger |
| Ocado |
| Albertsons |
| CVS Health |
| Walgreens Boots Alliance |
| Others |
Pricing and Supply Chain Analysis
Hospital system consolidation into regional procurement alliances is compressing per-prescription fulfillment costs and forcing dark store operators to unbundle premium cold-chain services from standard ambient dispensing.
Pricing Analysis
Bundled subscription models for chronic medication 90-day cycles dominate contract structures, while unbundled per-dose pricing applies to specialty biologics requiring frozen storage. Price differentiation hinges on automation density and DSCSA serialization compliance tier. Cost compression in standard ambient fulfillment is intensifying because robotic dispensing cells are commoditizing base-level services. Hospital systems exhibit highest price sensitivity due to 340B pricing exposure, while integrated health networks with captive specialty pharmacy demand show lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates for critical pharmaceutical infrastructure are reshaping sourcing toward US-based automation equipment and qualified cold-chain component suppliers. Geographic concentration centers on the United States, Germany, and China for robotic dispensing systems, barcode verification hardware, and HVAC engineering. Raw material dependencies include stainless steel fabrication, refrigerants compliant with F-Gas Regulation, and pharmaceutical-grade packaging films. Single-source vulnerability in specialized compressor systems for ultra-low temperature zones threatens fulfillment continuity. Distribution runs through hub-and-spoke networks anchored in metropolitan density corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacy dark store economics function as a geographic-arbitrage play where FDA 503B regulatory clarity in the United States contrasts with fragmented European supervision rules, creating cost-structure advantages for US-based central-fill operators.
For Market Incumbents: Deepen backward integration into robotic dispensing cell manufacturing to defend against logistics-platform entrants with proprietary automation architectures. Lock in multi-year cold-chain infrastructure leases in Dallas-Fort Worth and Greater Toronto Area corridors to preempt capacity constraints. Prioritize DSCSA serialization system retrofit completion ahead of statutory enforcement windows. For New Entrants and Emerging Players: Telepharmacy platform providers represent the most penetrable partnership channel for technician-staffed rural facilities in France and Germany. Target synchronous video counseling deployments in ANSM-regulated territories where centralized pharmacist oversight hubs are consolidating. Pursue white-label fulfillment contracts with hospital systems seeking to outsource 503B compounding without capital deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cold-chain infrastructure operators serving oncology biologics, where per-dose values justify premium facility investments that generalist competitors cannot replicate. Five-to-ten-year viability hinges on regulatory permanence of remote pharmacist supervision rules. Monitor state board of pharmacy scope-of-practice expansions for pharmacy technicians as the decisive inflection signal for unit-cost parity achievement.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Dispensing Cell Deployment | Automated pill-counting systems halve technician labor per script while maintaining FDA-mandated accuracy benchmarks. |
| Cold-Chain Infrastructure Expansion | Frozen storage capacity for biologics commands premium pricing in oncology and immunology fulfillment networks. |
| Telepharmacy Platform Integration | Video counseling modules satisfy EMA and state board requirements for remote pharmacist oversight in technician-staffed facilities. |
| DSCSA Serialization System Upgrade | Unit-level traceability compliance enables continued wholesale distribution partnerships under FDA mandates. |
| Hospital System Partnership Consolidation | Captive outpatient pharmacy volumes from integrated health networks anchor predictable 90-day refill demand. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with pharmacy operations directors, regulatory affairs specialists at 503B facilities, hospital procurement managers, and automation engineering leads informed operational assumptions. Secondary sources include FDA 503B registration databases, EMA outsourcing guidance documents, state board of pharmacy supervision rule compilations, and DSCSA implementation timelines. Bottom-up facility capacity modeling and top-down health system spending analysis were triangulated against cross-referenced estimates.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift effects and pricing dynamics. Segmentation dimensions modeled include product temperature class, service counseling modality, customer chronic condition profile, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves applied to automation adoption rates and health network consolidation trajectories. Forecast inputs incorporate 340B contract pharmacy eligibility restrictions and evolving telepharmacy reimbursement codes.
Revisions become necessary when FDA 503B enforcement priorities shift, EMA remote supervision guidance is finalized, or state-level pharmacist-to-technician ratio mandates change materially. Forecasts reflect documented assumptions regarding automation deployment timelines and health system outsourcing propensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Global Encephalitis Vaccine Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Global Pulmonary Drugs Market