
 Infliximab Market | 2026-2036
Infliximab Market Size, Share, and Industry Trends Forecast 2026-2036
Infliximab Market Foresight
A shortage of trained infusion nurses and specialized rheumatology pharmacists is unwinding capacity expansion plans at major treatment centers. Janssen Biotech anchors originator market presence through deep clinical trial archives and established reimbursement pathways. Samsung Bioepis leverages its Korean manufacturing base to supply European and Asian markets with cost-competitive biosimilar alternatives. Celltrion dominates intravenous infusion formats through vertically controlled production from cell line to finished vial.
Infliximab is a chimeric monoclonal immunoglobulin G1 antibody targeting tumor necrosis factor-alpha, manufactured through mammalian cell culture in bioreactors exceeding 10,000-liter scale, formulated for intravenous or subcutaneous delivery to suppress autoimmune-mediated inflammation. The biosimilars segment captures the fastest volume expansion as hospital formularies in Germany and the United States prioritize interchangeability-designated alternatives to manage pharmacy budgets. Original branded product still commands premium positioning in Crohn's Disease where physicians resist switching stable patients. Rheumatoid Arthritis therapy area generates the deepest patient pool though faces pressure from newer oral JAK inhibitors and IL-23 biologics.
FDA interchangeability standards and EMA biosimilar approval pathways determine which products gain automatic substitution rights at the pharmacy level, directly shaping market access depth for Samsung Bioepis and Celltrion relative to originator defenses. The country's national pharmaceutical regulator in Japan maintains distinct immunogenicity testing requirements that extend review timelines for foreign-manufactured biosimilars. Stakeholders must monitor whether CMS reimbursement parity adjustments or EMA manufacturing inspection backlogs alter the competitive balance between originator defenders and biosimilar challengers.
Market Dynamics
FDA interchangeability guidance and EMA biosimilar approval pathways are compressing originator defense windows while hospital formularies accelerate automatic substitution protocols across Germany, the United States, and Japan.
Growth Catalysts
- Interchangeability designation:FDA's biosimilar interchangeability standards grant automatic pharmacy-level substitution rights, accelerating uptake in United States hospital systems managing Crohn's Disease and Rheumatoid Arthritis patient pools.
- Gastroenterology capacity expansion:Major hospital systems are installing dedicated biologic infusion centers with cold-chain infrastructure to handle intravenous infliximab administration at scale.
- EMA centralized approval:The European Medicines Agency's single-marketing authorization enables simultaneous market access across 27 member states, reducing regulatory duplication for biosimilar manufacturers.
Market Restraints
- Trained infusion nurse scarcity:Specialized biologic administration requires certified oncology/immunology nurses, with workforce gaps unwinding capacity expansion timelines at major treatment centers.
- Originator clinical trial archives:Janssen Biotech's decades of Crohn's Disease data create switching hesitation among physicians managing stable patients despite biosimilar equivalence.
- JAK inhibitor displacement:Oral small-molecule Rheumatoid Arthritis therapies are capturing treatment-naive patients before biologic initiation, compressing infliximab's addressable pool.
Strategic Opportunities
- Subcutaneous formulation penetration:Self-administration formats bypass infusion center bottlenecks, opening home-care channels in Germany where patient copay structures favor reduced clinic visits.
- PMDA immunogenicity pathway optimization:Japan's distinct foreign-manufactured biosimilar review requirements represent a regulatory white space for sponsors investing in localized immunogenicity testing infrastructure.
- Vertically integrated production:Captive cell-line-to-vial manufacturing control reduces COGS and batch-to-batch variability, enabling aggressive tender participation in European hospital procurement.
Industry Challenges
- Specialized rheumatology pharmacist recruitment:Biologic stewardship programs require pharmacists trained in immunogenicity monitoring and therapeutic drug monitoring interpretation, with talent concentrated at academic medical centers.
- Manufacturing inspection backlog navigation:EMA facility inspections and FDA pre-approval manufacturing reviews face queue delays that extend launch timelines for new biosimilar entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infliximab Market |
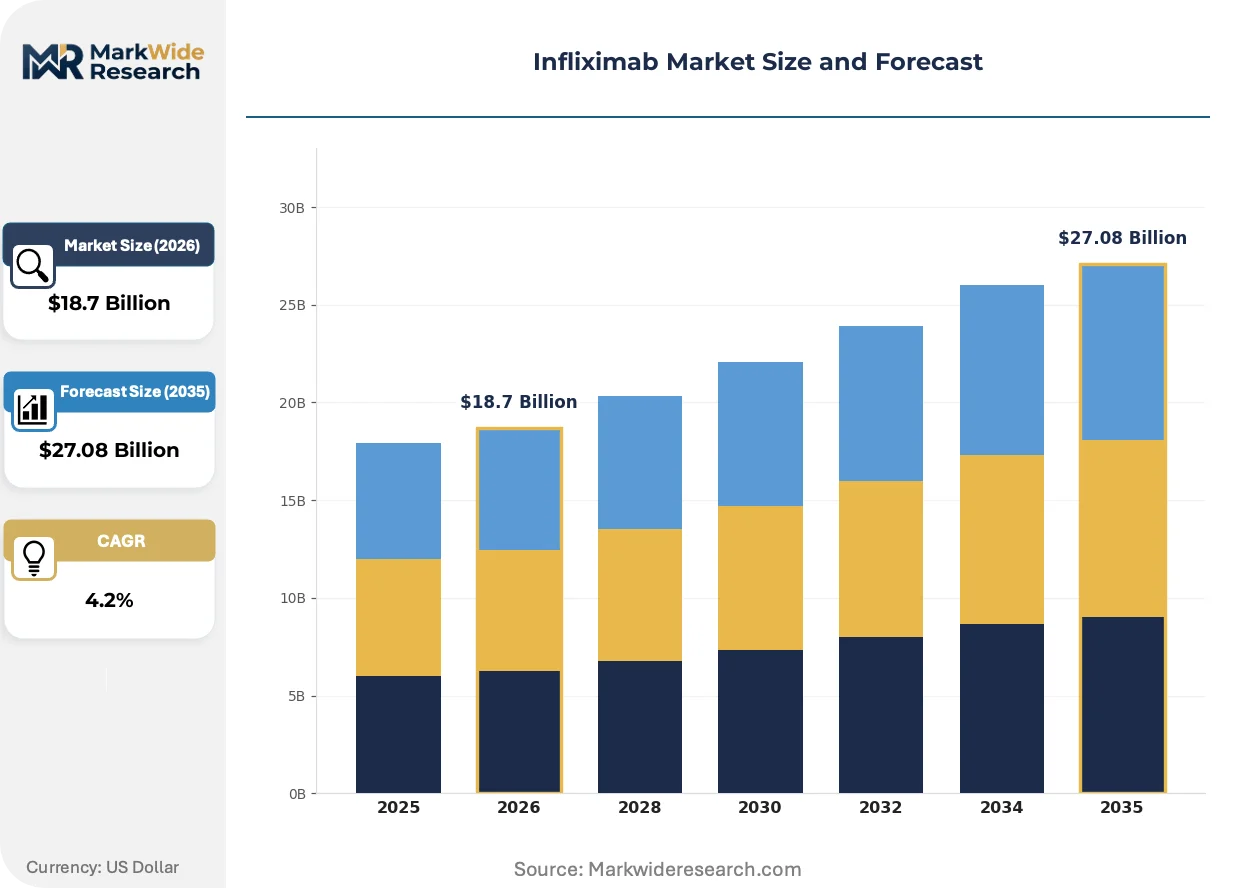
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Infusion, Biosimilars, Original Therapy Area: Rheumatoid Arthritis, Psoriasis, Crohn's Disease, Ulcerative Colitis End User: Hospitals, Clinics, Home Care, Research Institutions Administration Route: Intravenous, Subcutaneous, Intramuscular, Orally |
| Companies Covered | Merck and Co., Samsung Bioepis, Janssen Biotech, Novartis, Boehringer Ingelheim, Celltrion, Amgen, Coherus BioSciences, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infliximab Market Shifts & Advancements
Biosimilar manufacturing scale and regulatory science advances are compressing the cost-position gap with originator products while administration format innovation opens new care settings.
Continuous perfusion bioreactor technology is displacing fed-batch mammalian cell culture as the dominant production platform for infliximab biosimilars. Samsung Bioepis and Celltrion have adopted 15,000-liter single-use perfusion systems at their Korean manufacturing bases, yielding higher cell densities and reduced batch failure rates. This platform shift is displacing legacy stainless-steel infrastructure and enabling cost structures that support 40-60% list-price discounts while maintaining margin.
EMA's revised biosimilar monoclonal antibody guidance now accepts analytical similarity packages with reduced clinical efficacy trial requirements for well-characterized products. The industrial consequence is compressed development timelines and reduced Phase III patient exposure costs for sponsors with robust physicochemical characterization capabilities. Rheumatoid Arthritis indications are most affected, with sponsors redirecting resources toward real-world evidence generation post-launch rather than extensive pre-market efficacy trials.
Hospital procurement consortia in Germany are consolidating infliximab purchasing through tender mechanisms that award multi-year sole-source contracts to lowest-qualified bidders. The pharmacy and therapeutics committees at these institutions are displacing individual physician preference with formulary-driven automatic substitution protocols. This behavioral shift is most visible in North Rhine-Westphalia and Bavaria, where hospital network consolidation has concentrated purchasing power among three major procurement alliances.
Infliximab Market Segmentation
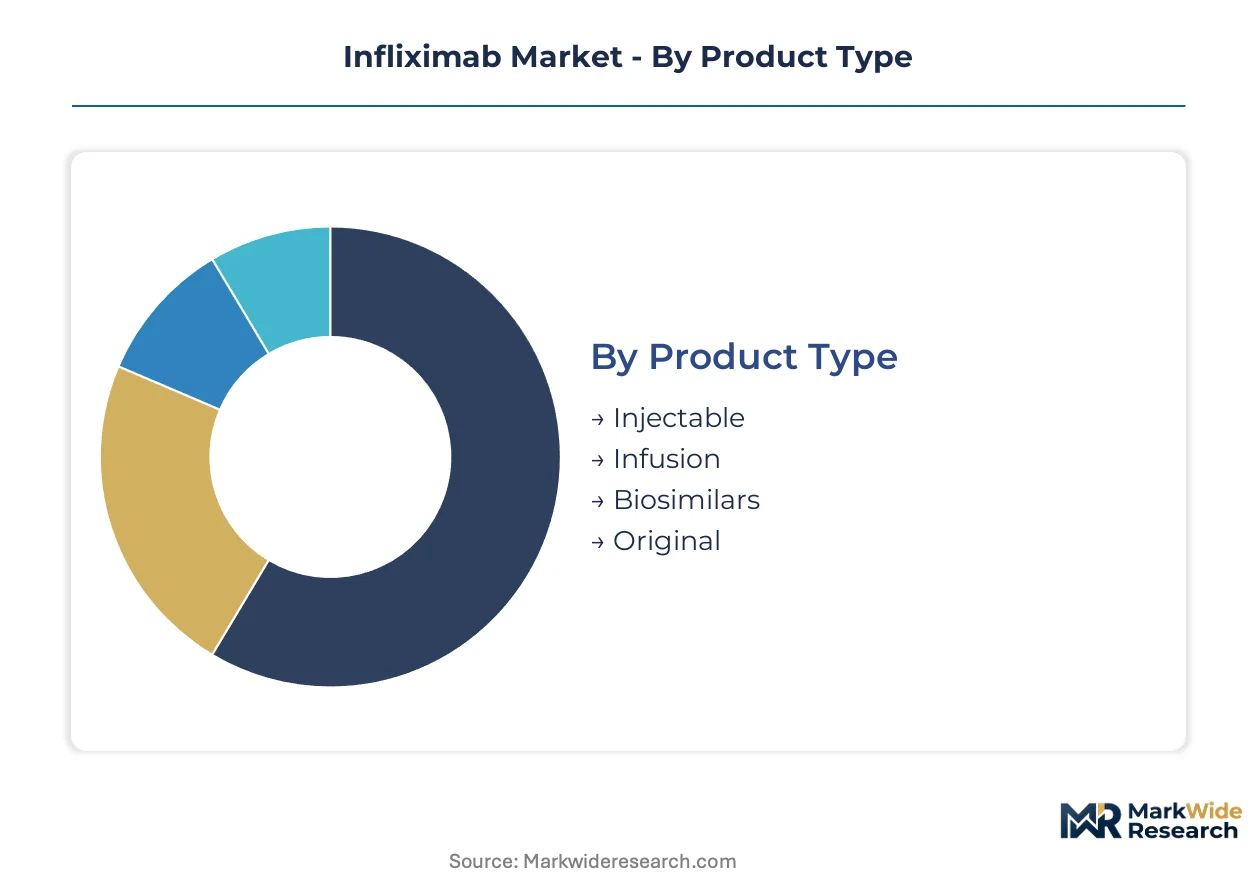
Regulatory pathways and reimbursement structures fragment the infliximab landscape across administration formats and therapeutic indications. Each segment carries distinct manufacturing requirements, clinical evidence thresholds, and prescriber switching dynamics that shape competitive positioning.
Product Type:
FDA interchangeability standards and EMA centralized approvals create tiered market access conditions across manufacturing-origin categories.
- Injectable:Prefilled syringe and autoinjector formats enable self-administration outside infusion centers. Demand concentrates in Germany where patient copay structures favor reduced clinic visits, though cold-chain logistics requirements limit rural pharmacy distribution.
- Infusion:Intravenous administration in controlled clinical settings requires specialized nursing capacity and biologic-compatible infusion infrastructure. Hospital systems in the United States prioritize this format for Crohn's Disease maintenance therapy where therapeutic drug monitoring protocols are established.
- Biosimilars:Analytical similarity packages with reduced clinical efficacy requirements accelerate development timelines for sponsors with robust physicochemical characterization. Samsung Bioepis and Celltrion supply European and Asian markets through cost-competitive Korean manufacturing bases.
- Original:Janssen Biotech's originator maintains premium positioning through decades of Crohn's Disease clinical trial archives and established reimbursement pathways. Physicians managing stable patients exhibit persistent switching hesitation despite biosimilar equivalence demonstrations.
Established volume favors infusion formats; emerging adoption favors self-administration injectables.
Therapy Area:
Prescriber resistance to switching stable patients varies sharply across immunologic indications, with gastroenterology maintaining tighter originator loyalty than rheumatology.
- Rheumatoid Arthritis:The deepest patient pool faces displacement pressure from oral JAK inhibitors and IL-23 biologics capturing treatment-naive patients before biologic initiation. Hospital formularies in Germany and the United States accelerate automatic substitution protocols in this indication.
- Crohn's Disease:Physician resistance to switching stable patients remains most pronounced here, with Janssen Biotech's clinical trial archives reinforcing originator preference. Gastroenterology departments in major hospital systems are expanding dedicated biologic infusion capacity to handle intravenous administration at scale.
- Psoriasis:Dermatology prescribing patterns favor newer IL-17 and IL-23 pathway biologics with superior skin clearance endpoints, compressing infliximab's addressable pool in this indication.
- Ulcerative Colitis:Similar immunologic mechanism to Crohn's Disease with somewhat less entrenched originator loyalty, creating faster biosimilar penetration in hospital procurement consortia.
Treatment-naive inflows favor Rheumatoid Arthritis; originator defense durability favors Crohn's Disease.
End User:
Care setting economics and reimbursement parity determine channel concentration, with site-of-service differentials shaping manufacturer contracting strategies.
- Hospitals:Consolidated purchasing power through procurement alliances in Germany's North Rhine-Westphalia and Bavaria regions drives tender-based sole-source contracts. Pharmacy and therapeutics committees displace individual physician preference with formulary-driven automatic substitution protocols.
- Clinics:Independent rheumatology and gastroenterology practices maintain greater prescriber autonomy but face reimbursement compression under CMS payment parity adjustments in the United States.
- Home Care:Subcutaneous formulation penetration opens this channel where patient copay structures and convenience preferences align, particularly in European markets with established home nursing infrastructure.
- Research Institutions:Academic medical centers concentrate specialized rheumatology pharmacist talent for biologic stewardship programs, with therapeutic drug monitoring interpretation capabilities concentrated at these sites.
Procurement consolidation favors hospitals; patient convenience tailwinds favor home care.
Administration Route:
Format innovation directly addresses workforce scarcity constraints while opening new reimbursement and care setting possibilities.
- Intravenous:The dominant historical format requires certified oncology/immunology nurses, with workforce gaps unwinding capacity expansion timelines at major treatment centers. Celltrion controls this segment through vertically integrated production from cell line to finished vial.
- Subcutaneous:Self-administration bypasses infusion center bottlenecks entirely, enabling home-care channels where regulatory and reimbursement frameworks permit. Samsung Bioepis has invested in formulation technology to compete in this expanding category.
- Intramuscular:Limited clinical application for infliximab due to immunogenicity concerns and pharmacokinetic variability relative to intravenous delivery.
- Orally:Not commercially viable for monoclonal antibody biologics due to gastrointestinal degradation; included for completeness in route taxonomy.
Clinical familiarity favors intravenous delivery; expansion trajectory favors subcutaneous alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA interchangeability standards anchor the United States as the dominant geography, with EMA centralized approvals and Japan's PMDA pathways creating distinct regulatory environments that fragment competitive positioning across major markets.
United States
Hospital formularies in the United States accelerate automatic substitution protocols for Crohn's Disease and Rheumatoid Arthritis patient pools. CMS reimbursement parity adjustments compress site-of-service differentials between hospital and clinic settings. Major health systems in the Northeast Corridor and California are installing dedicated biologic infusion centers with cold-chain infrastructure.
Germany
Procurement consortia in North Rhine-Westphalia and Bavaria consolidate purchasing through tender mechanisms awarding multi-year sole-source contracts. EMA centralized approval enables simultaneous market access across member states, reducing regulatory duplication. Hospital network concentration in these regions displaces individual physician preference with formulary-driven protocols.
Japan
PMDA maintains distinct immunogenicity testing requirements that extend review timelines for foreign-manufactured biosimilars. METI industrial policy supports domestic biopharmaceutical manufacturing capacity expansion. The Kanto region around Tokyo concentrates specialized rheumatology pharmacist talent for biologic stewardship programs.
South Korea
MFDS regulatory pathways align with international standards while supporting export-oriented manufacturing bases. Samsung Bioepis and Celltrion leverage Korean production facilities to supply European and Asian markets with cost-competitive alternatives. The Seoul Capital Area anchors bioreactor manufacturing scale exceeding 10,000-liter capacity.
United Kingdom
NHS England procurement frameworks prioritize interchangeability-designated biosimilars to manage pharmacy budgets across hospital trusts. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards while streamlining national assessment timelines. The London/Southeast corridor concentrates academic medical center capacity for therapeutic drug monitoring interpretation.
Infliximab Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with originator defenders leveraging clinical trial archives against biosimilar challengers optimizing manufacturing scale. The market structure consolidates around established biologics manufacturers with vertically controlled production capabilities. Three archetypes dominate: originator incumbents with deep indication-specific data, Korean manufacturing specialists with perfusion bioreactor scale, and diversified pharmaceutical conglomerates with broad immunology portfolios. Competitive moves center on capacity expansion in continuous perfusion platforms and strategic partnerships for subcutaneous formulation technology.
Among originator defenders, Janssen Biotech anchors premium positioning through decades of Crohn's Disease clinical evidence. Samsung Bioepis and Celltrion occupy the manufacturing-scale tier, with both representing Korean-based specialists that have captured European and Asian biosimilar volume through cost-competitive supply. These three exemplify the archetype segmentation shaping prescribing patterns across hospital formularies.
| Leading Market Players |
|---|
| Merck and Co. |
| Samsung Bioepis |
| Janssen Biotech |
| Novartis |
| Boehringer Ingelheim |
| Celltrion |
| Amgen |
| Coherus BioSciences |
| Pfizer |
| Others |
Supply & Pricing Matrix
Ninety-day cold-chain inventory buffers at Korean manufacturing sites concentrate pricing power with Celltrion and Samsung Bioepis against European tender pressure. This lead-time structure lets originator defenders command maintenance-therapy premiums while biosimilar challengers absorb procurement compression through perfusion-scale economies.
Pricing Analysis
Forty-to-sixty percent list-price spreads separate German hospital tender awards from United States originator maintenance contracts. Three-tier pricing structure across originator premium, interchangeable biosimilar, and non-interchangeable economy levels tracks FDA designation status and EMA centralized approval. Cost compression in the interchangeable tier intensifies as procurement consortia consolidate sole-source awards. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity; gastroenterology departments managing stable Crohn's Disease patients show lowest.
Supply Chain Analysis
South Korea anchors mammalian cell culture manufacturing through Samsung Bioepis and Celltrion facilities exceeding 15,000-liter perfusion capacity. Production draws from Chinese-sourced cell culture media, German-engineered bioreactor systems, and United States-origin purification resins. Single-source vulnerability concentrates in Korean fill-finish capacity for European markets. Distribution runs through hospital procurement alliances in Germany, specialty distributor networks in the United States, and regional wholesaler consortia in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across Germany's North Rhine-Westphalia and Bavaria regions shifts buyer power toward formulary-driven automatic substitution, compressing originator defense windows.
For Market Incumbents: Consolidate Crohn's Disease clinical evidence archives into switching-resistance protocols at academic medical centers. Deepen backward integration into cell-line development to protect perfusion-scale cost positions against Korean manufacturing specialists. Anchor defensive positioning through therapeutic drug monitoring service bundling that biosimilar challengers cannot replicate without stewardship-program infrastructure. For New Entrants and Emerging Players: Anchor in Japan's PMDA immunogenicity pathway white space where foreign-manufactured biosimilar review timelines create incumbent protection gaps. Target ulcerative colitis as the most penetrable indication with softer originator loyalty than Crohn's Disease. Pursue subcutaneous formulation partnerships to bypass infusion-center capacity constraints that throttle intravenous volume capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized biologics manufacturing infrastructure and stalled immunology pipelines. Five-to-ten-year viability hinges on continuous perfusion platform adoption and subcutaneous delivery technology access. Monitor EMA manufacturing inspection queue lengths as inflection signal for biosimilar launch timing and competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Perfusion Scale-Up | 15,000-liter single-use systems at Korean facilities enable 40-60% cost positions against fed-batch legacy. |
| FDA Interchangeability Pursuit | Automatic pharmacy substitution rights unlock hospital formulary access against Janssen Biotech originator defense. |
| Subcutaneous Formulation Development | Self-administration formats bypass certified nurse scarcity constraints in United States infusion centers. |
| EMA Centralized Approval Pathway | Single marketing authorization accelerates simultaneous access across 27 member state procurement consortia. |
| Japan PMDA Localization Investment | Dedicated immunogenicity testing infrastructure compresses foreign-manufactured biosimilar review timelines. |
Research Methodology
The analysis maps biosimilar development pathways, originator defense strategies, and procurement alliance structures, each validated through hospital formulary directors, biologic stewardship pharmacists, and regulatory affairs specialists. Primary interviews with infusion center nursing directors and pharmaceutical tender managers combined with secondary validation against FDA biosimilar approval databases, EMA centralized procedure records, ClinicalTrials.gov archives, and hospital procurement contract disclosures. Bottom-up patient-volume modeling and top-down manufacturer capacity assessments triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include administration route, interchangeability designation status, therapy area, and regional regulatory cluster. CAGRs derive from patient population epidemiology, treatment-line progression rates, and biosimilar substitution elasticity by indication. Forecast inputs incorporate infusion center capacity expansion timelines and PMDA review queue dynamics.
Material uncertainties — regulatory approval delays, manufacturing inspection backlogs, and prescriber switching resistance — sit outside the modeled envelope. Forecasts reflect documented assumptions about interchangeability designation velocity and procurement alliance consolidation trajectories. Recalibration cycles align with material shifts in CMS reimbursement parity adjustments and EMA biosimilar guidance revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Dermatitis Drugs Market