
 Global Antacids Market | 2026-2036
Global Antacids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antacids Market Foresight
Single-dose sachet and on-the-go strip packaging is restructuring how consumers evaluate antacid portability and trial thresholds. Bayer AG leverages its European pharmacy network to sustain shelf dominance in magnesium hydroxide tablets. Haleon plc anchors the North American retail landscape through pharmacy chain exclusivity and private-label partnerships. Sun Pharmaceutical Industries Ltd. competes on cost-engineered calcium carbonate formulations across emerging Asian markets.
Antacids are alkaline compounds, typically calcium carbonate, magnesium hydroxide, aluminum hydroxide, or proton pump inhibitor adjuncts, formulated to neutralize gastric acid through chemical reaction with hydrogen chloride in the stomach lumen, primarily serving symptomatic relief of dyspepsia, gastroesophageal reflux, and peptic irritation. Combination formulations now command the widest margin pools as clinicians favor multi-mechanism acid suppression over single-salt regimens. Liquid suspensions represent the fastest-growing form segment as pediatric and geriatric populations reject tablet swallowing.
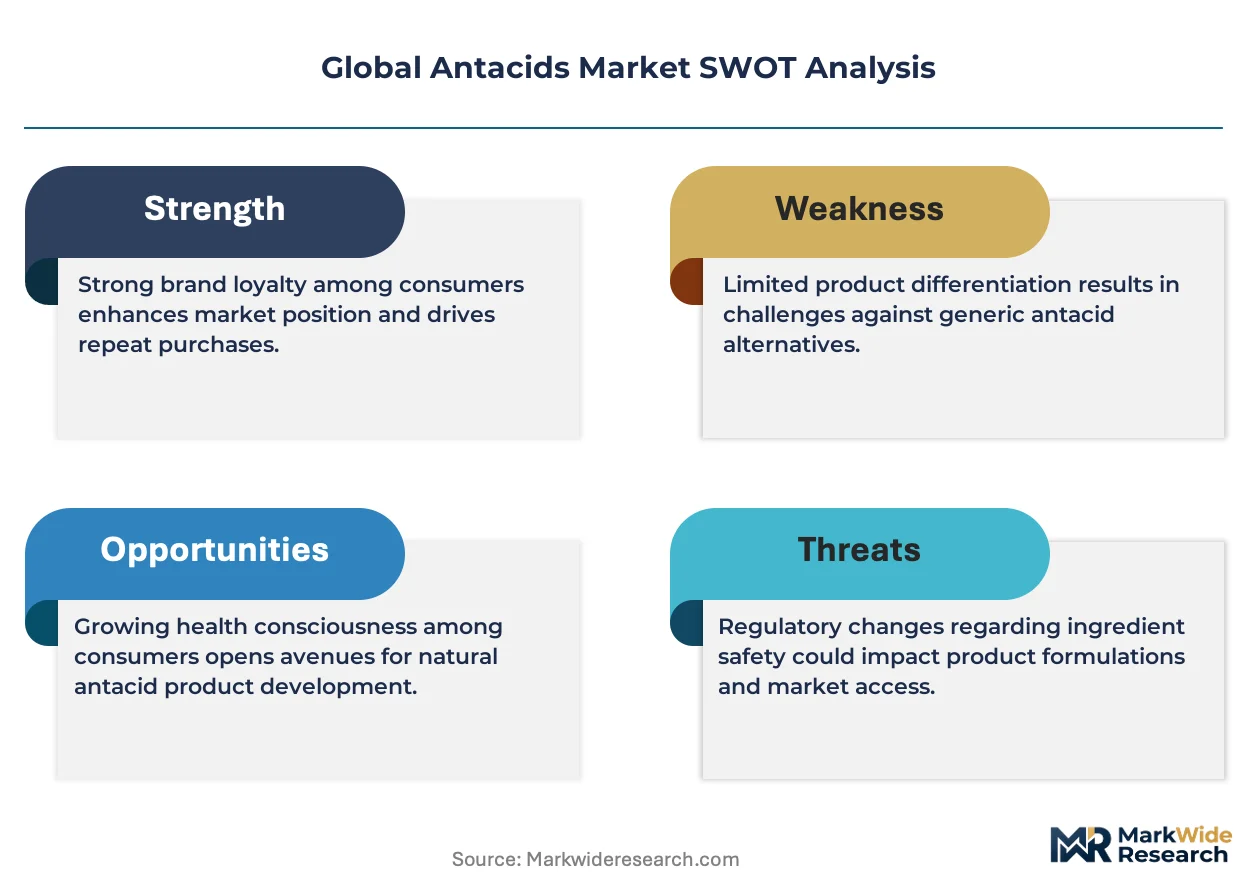
The FDA regulates over-the-counter antacid monographs under 21 CFR 331, while the EMA oversees centralized marketing authorization for combination products across EU member states, and the WHO maintains essential medicines criteria that shape national procurement tenders in low-income health systems. These frameworks elevate manufacturing documentation burdens but also consolidate market access for compliant producers. Stakeholders must monitor evolving aluminum exposure limits and biosimilar proton pump inhibitor competition to preserve formulation relevance.
Market Dynamics
Formulation chemistry is pivoting away from aluminum-based salts as the FDA tightens 21 CFR 331 exposure thresholds, forcing manufacturers to revalidate magnesium-dominant and calcium-carbonate production lines while geriatric polypharmacy protocols normalize routine gastrointestinal prophylaxis in long-term care facilities.
Growth Catalysts
- EMA centralized marketing authorization:Combination antacid products gain streamlined EU-wide access, consolidating procurement for pharmacy chains and hospital formularies across member states.
- Geriatric polypharmacy protocols:Long-term care facilities in Japan and Germany now embed acid suppression into standard medication regimens, expanding institutional purchase volumes.
- Magnesium hydroxide tablet innovation:Reformulated rapid-dissolve coatings improve palatability for dysphagia patients, opening pediatric and elderly segments previously served by liquids alone.
Market Restraints
- Aluminum supply chain concentration:Bauxite refining capacity clusters in Guinea and Australia, exposing formulation costs to geopolitical disruption and freight volatility.
- Proton pump inhibitor substitution:Biosimilar omeprazole and esomeprazole erode antacid use in chronic GERD management, compressing repeat-purchase frequency.
- REACH compliance burden:ECHA documentation requirements for excipient safety data elevate R&D costs for European market entry, favoring incumbents with established dossiers.
Strategic Opportunities
- Indian pharmacy modernization:CDSCO streamlined OTC monograph pathways enable first-mover positioning in tier-2 and tier-3 cities where organized retail penetration remains below 35 percent.
- Single-dose sachet formats:On-the-go strip packaging captures commuter and travel segments in Brazil and Mexico, commanding shelf-space premiums in convenience channels.
- WHO essential medicines alignment:National procurement tenders in low-income health systems favor antacids meeting WHO criteria, creating volume anchors for compliant manufacturers.
Industry Challenges
- Aluminum-to-magnesium formulation revalidation:Stability testing and bioequivalence studies for salt-substituted products extend time-to-market by 18-24 months, straining R&D pipelines.
- Liquid suspension manufacturing scale-up:Aseptic filling capacity for pediatric and geriatric formulations requires capital-intensive cleanroom expansion, constraining mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antacids Market |
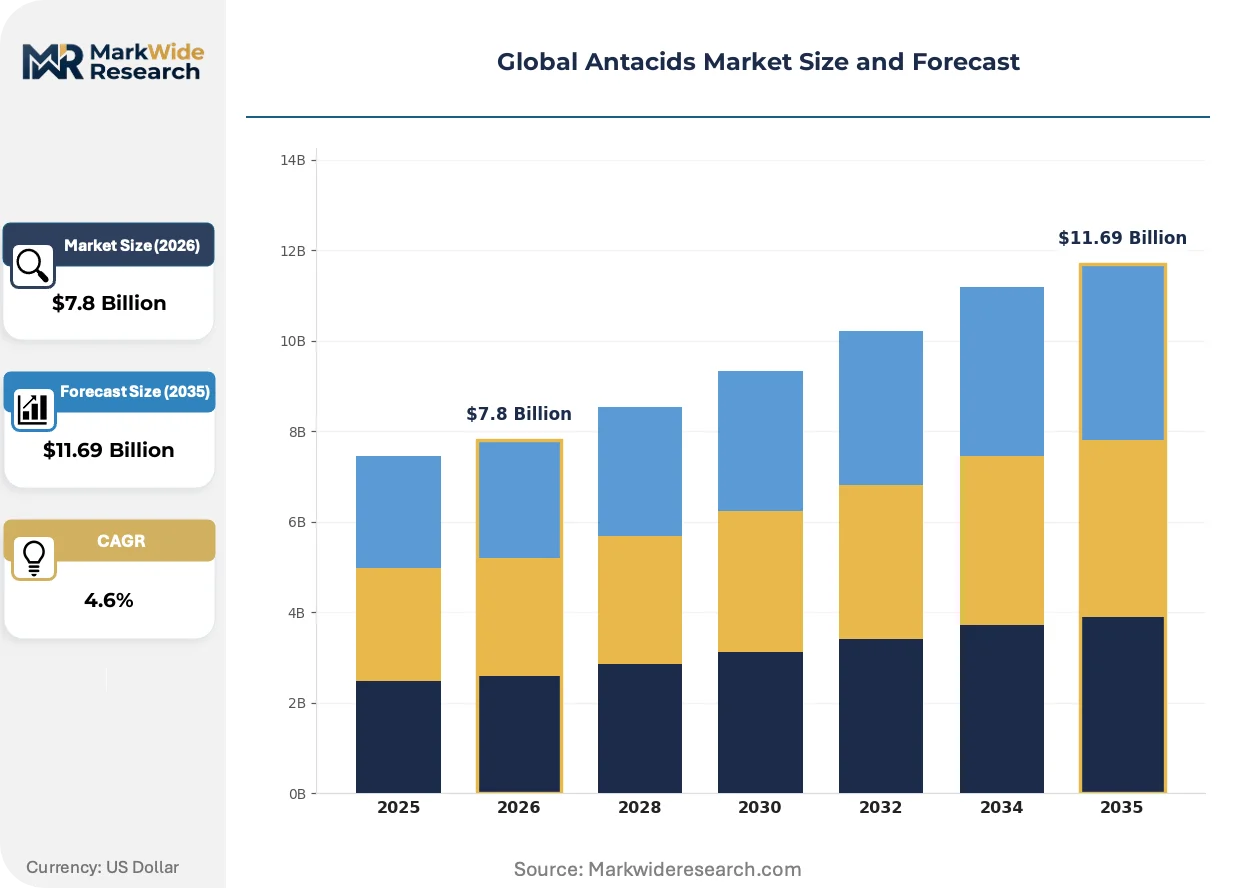
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Magnesium Hydroxide, Aluminum Hydroxide, Combination Formulations Form: Tablets, Chewable Tablets, Liquid Suspensions, Powders Application: Indigestion Relief, Acid Reflux Control, Ulcer Treatment, Heartburn Prevention End User: Pharmacies, Hospitals, Clinics, Online Retailers |
| Companies Covered | GlaxoSmithKline plc, Bayer AG, Haleon plc, Sanofi, Pfizer Inc., Reckitt Benckiser Group plc, Sun Pharmaceutical Industries Ltd., Johnson & Johnson, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antacids Market Shifts & Advancements
Packaging format innovation and multi-mechanism formulation chemistry are restructuring competitive differentiation, while regulatory aluminum thresholds and direct-to-consumer channel expansion reshape how manufacturers prioritize R&D investment and geographic rollout sequencing.
Dual-salt combination tablets integrating calcium carbonate with magnesium hydroxide are modularizing how clinicians approach acid suppression, enabling titrated dosing protocols that single-salt regimens cannot match. Hospital formularies in France and Spain are adopting these platforms for post-operative dyspepsia management. The technology is compressing margin pools for standalone calcium and magnesium products while expanding the addressable prescriber base.
REACH authorization timelines for novel excipients are extending pre-market qualification periods, forcing manufacturers to lock formulation architectures earlier in development cycles. ECHA's 2024 updated guidance on nanomaterial characterization applies to colloidal suspensions, affecting liquid antacid dossiers. German and Dutch regulators are requesting additional stability data, delaying launches by 12-18 months for non-compliant applicants.
Employer-sponsored wellness programs in the United States are unbundling antacid provision from traditional pharmacy benefits, creating direct-ship subscription channels that bypass retail markup. Large self-insured employers in Texas and California negotiate formulary placement directly with manufacturers. This channel disintermediation is most visible in the technology and financial services verticals, where workforce wellness budgets exceed sector averages.
Global Antacids Market Segmentation
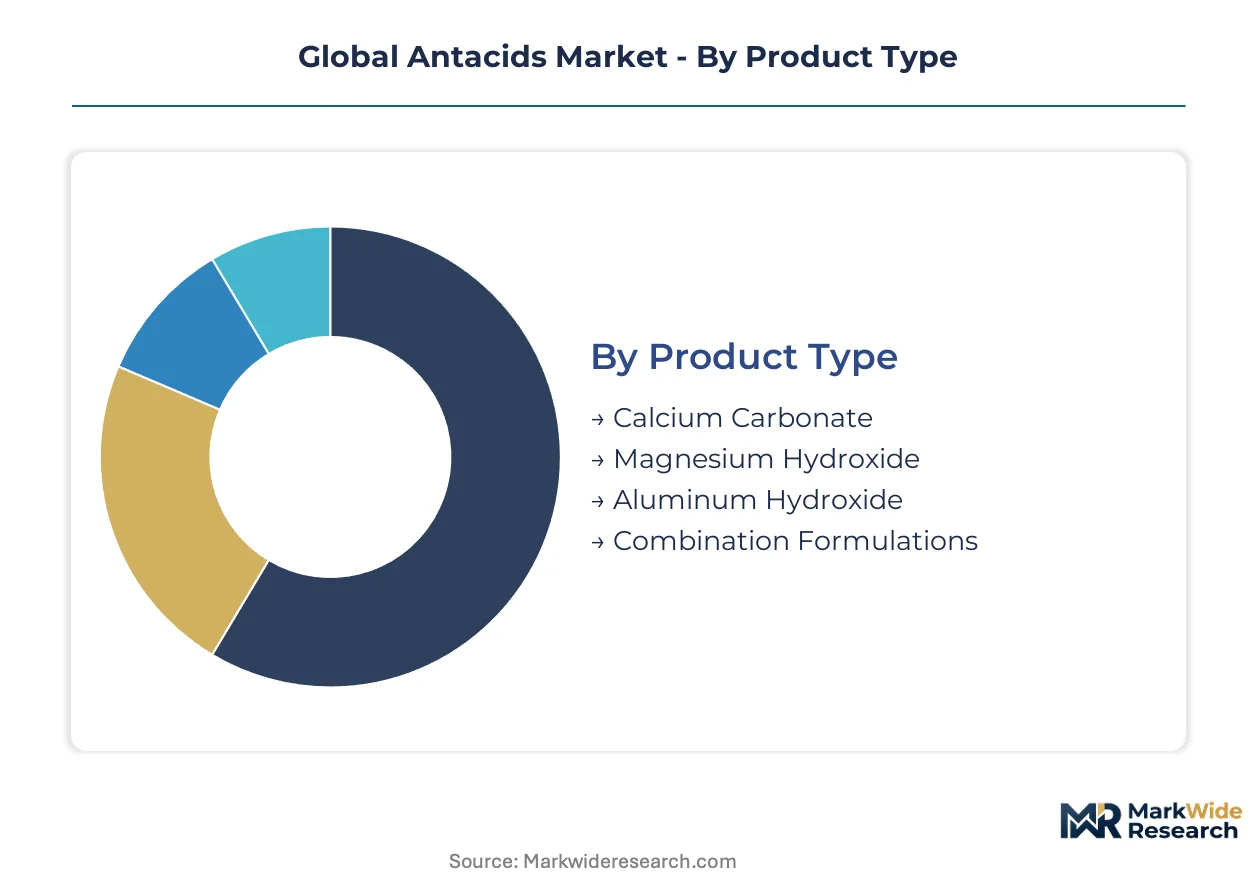
Antacid manufacturers configure product portfolios around formulation chemistry, delivery format, and channel access. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape investment priorities.
Product Type:
Buyers differentiate by acid-neutralizing capacity, electrolyte load tolerance, and contraindication profiles in polypharmacy settings.
- Calcium Carbonate:Rapid acid neutralization with calcium supplementation delivers dual utility for osteoporotic patients. Demand concentrates in United States pharmacy chains where employer wellness programs favor calcium-positive regimens. FDA 21 CFR 331 compliance costs remain lowest for this salt category.
- Magnesium Hydroxide:Laxative-sparing formulations address constipation-sensitive geriatric populations. German hospital formularies expanded magnesium-dominant procurement after EMA guidance tightened aluminum exposure thresholds. Reformulated rapid-dissolve coatings now penetrate dysphagia segments previously served by liquids.
- Aluminum Hydroxide:Phosphate-binding properties retain niche utility in renal dialysis protocols despite regulatory headwinds.
- Combination Formulations:Multi-salt chemistry enables titrated dosing protocols that command widest margin pools in prescriber-driven channels.
Calcium carbonate leads volumes today; combination formulations are gaining share fastest.
Form:
Patient swallowing capability and dosing precision requirements determine format selection across age cohorts.
- Tablets:Standard compressed dosage forms dominate institutional procurement for cost-engineered acid suppression. Japanese long-term care facilities standardize on scored tablets for dose flexibility in weight-varying geriatric populations.
- Chewable Tablets:Palatability-enhanced formulations capture pediatric and adolescent trial thresholds where swallowing aversion persists. Brazilian pharmacy chains promote fruit-flavored variants through point-of-sale placement in family-oriented retail zones.
- Liquid Suspensions:Aseptic filling requirements constrain supply concentration among manufacturers with cleanroom scale. Pediatric and geriatric rejection of solid dosage forms drives steepest expansion trajectory in this category.
- Powders:Reconstitutable sachets serve travel and commuter segments requiring portable, TSA-compliant packaging.
Tablets retain volume leadership; liquid suspensions expand most quickly.
Application:
Symptom severity and chronicity dictate whether consumers self-select OTC or seek clinician-directed therapy.
- Indigestion Relief:Postprandial discomfort drives highest-frequency purchase cycles in convenience retail. Mexican supermarket chains position single-dose sachets at checkout to capture impulse trial.
- Acid Reflux Control:Recumbent positioning symptoms require sustained-release chemistry that bridges to PPI adjunct therapy. United States direct-to-consumer subscription channels disintermediate retail markup for chronic sufferers in technology sector employment clusters.
- Ulcer Treatment:H. pylori eradication protocols relegate antacids to symptomatic adjunct status, compressing standalone revenue potential.
- Heartburn Prevention:Pre-emptive dosing before trigger foods captures wellness-oriented consumers in Australian pharmacy loyalty programs.
Indigestion relief dominates transaction volume; acid reflux control climbs the fastest.
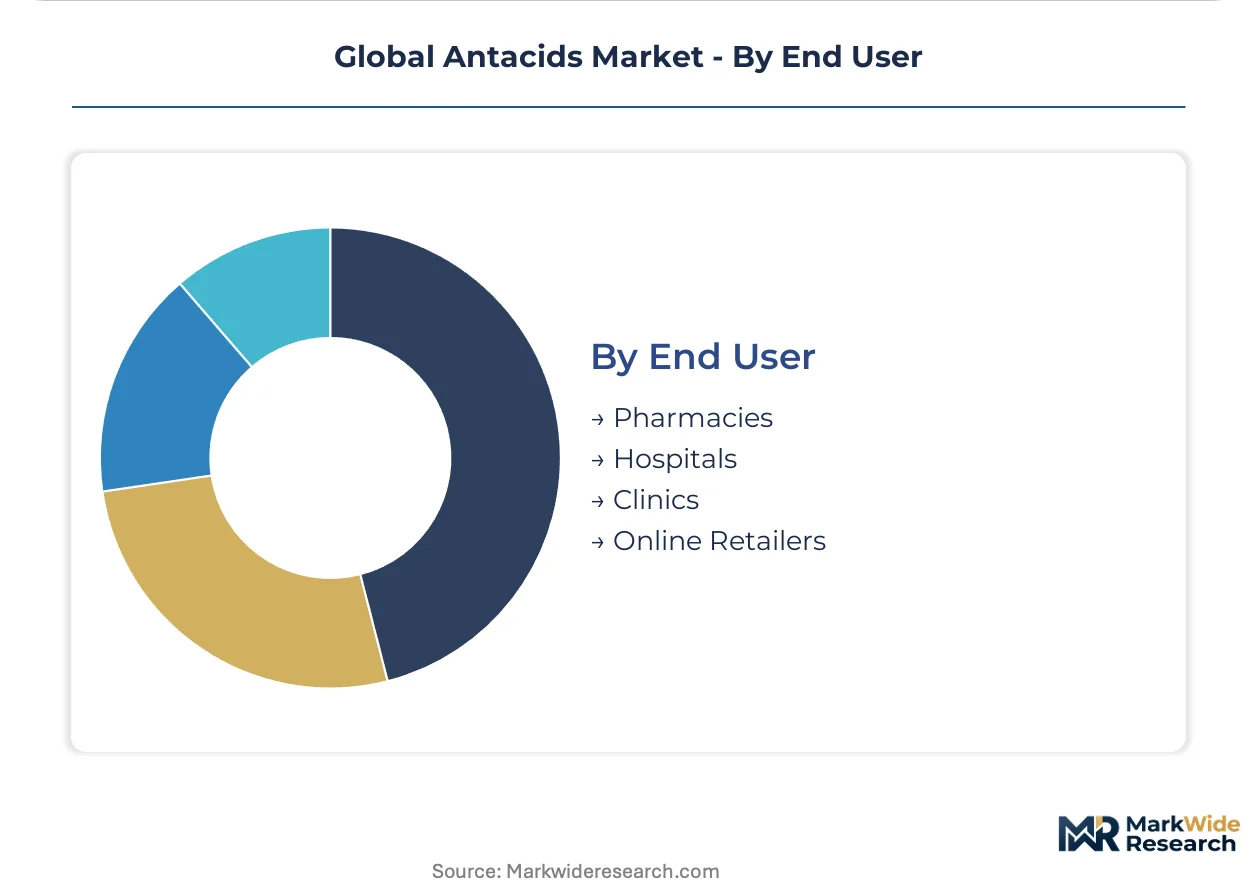
End User:
Channel economics and formulary control determine pricing power and brand loyalty mechanics.
- Pharmacies:Shelf-space negotiations and private-label partnerships define competitive dynamics in organized retail. Haleon plc anchors North American pharmacy chain exclusivity through volume rebate structures.
- Hospitals:Centralized procurement tenders favor combination formulations with multi-mechanism acid suppression profiles. French post-operative dyspepsia protocols standardize on dual-salt platforms.
- Clinics:Physician sample programs and starter packs influence patient brand retention upon discharge to self-pay channels.
- Online Retailers:Subscription mechanics and auto-replenishment algorithms capture chronic users with predictable consumption patterns. Indian tier-2 city penetration lags as CDSCO streamlined OTC pathways mature.
Pharmacies command volume leadership today; online retailers show steepest share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antacid manufacturing traces its industrial roots to early 20th-century German pharmaceutical chemistry, where Bayer AG pioneered standardized aluminum hydroxide formulations before global production dispersed across multiple regulatory jurisdictions.
United States
Employer-sponsored wellness programs and direct-to-consumer subscription channels sustain the highest per-capita antacid consumption among developed economies. FDA 21 CFR 331 monographs govern OTC formulation standards, with ongoing tightening of aluminum exposure thresholds reshaping manufacturer compliance strategies. Texas and California technology sector employers negotiate formulary placement directly with producers, bypassing traditional retail markup.
Germany
Hospital formularies in Bavaria and North Rhine-Westphalia expanded magnesium-dominant procurement following EMA guidance on aluminum exposure limits. ECHA REACH documentation requirements for excipient safety data elevate market entry barriers, favoring established dossier holders. The Rhine-Ruhr industrial corridor hosts concentrated aseptic filling capacity for liquid suspension exports across EU member states.
Japan
Long-term care facilities embed acid suppression into standard polypharmacy protocols, driving institutional purchase volumes for scored tablets with dose flexibility. PMDA oversees marketing authorization for combination products, while METI industrial standards shape manufacturing equipment specifications. The Kanto region around Tokyo anchors domestic production clusters serving aging demographic demand.
India
CDSCO streamlined OTC monograph pathways enable first-mover positioning in tier-2 and tier-3 cities where organized retail penetration remains below 35 percent. Cost-engineered calcium carbonate formulations dominate price-sensitive segments across emerging Asian markets. Maharashtra and Gujarat host contract manufacturing capacity serving export demand to Middle East and African markets.
Brazil
Single-dose sachet formats capture commuter and travel segments, commanding shelf-space premiums in convenience channels. ANVISA regulates pharmaceutical advertising and OTC classification, shaping how manufacturers position combination formulations. São Paulo pharmacy chains promote fruit-flavored chewable variants through point-of-sale placement in family-oriented retail zones.
Global Antacids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and channel access tiers. The vendor base clusters around three strategic archetypes: multinational pharmaceutical conglomerates with integrated R&D and regulatory dossier libraries, mid-scale regional specialists leveraging cost-engineered production for emerging market penetration, and private-label contractors serving pharmacy chain exclusivity arrangements. Dominant competitive moves include salt-substitution revalidation for aluminum-to-magnesium transitions and aseptic filling capacity expansion for liquid suspension segments.
Among European-anchored conglomerates, Bayer AG and GlaxoSmithKline plc occupy positions reflecting century-long pharmaceutical heritage, while Haleon plc exemplifies the consumer health spin-off archetype with concentrated North American retail presence. Sun Pharmaceutical Industries Ltd. represents the emerging market cost-leader model, leveraging Indian manufacturing scale for calcium carbonate export competitiveness.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Bayer AG |
| Haleon plc |
| Sanofi |
| Pfizer Inc. |
| Reckitt Benckiser Group plc |
| Sun Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Aluminum-to-magnesium formulation revalidation is simultaneously elevating R&D cost structures and concentrating supply leverage among manufacturers with established EMA dossiers and aseptic filling infrastructure. This chemistry transition feeds pricing stratification as smaller competitors absorb 18-24 month time-to-market penalties while integrated conglomerates capture margin premiums on compliant combination products.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates combination formulations with multi-mechanism acid suppression from single-salt generics and private-label commodities. Price differentiation hinges on FDA 21 CFR 331 compliance tier and EMA centralized marketing authorization status. Cost compression in aluminum-based segments is intensifying because REACH documentation requirements for novel excipients extend pre-market timelines. Institutional buyers in German hospital formularies demonstrate lowest price sensitivity, while price-conscious consumers in Indian tier-2 cities drive economy-tier volume.
Supply Chain Analysis
Bauxite refining capacity rests on concentrated mining and processing infrastructure in Guinea and Australia, exposing magnesium hydroxide and calcium carbonate feedstock costs to freight volatility and geopolitical disruption. Raw material dependencies span bauxite ore, magnesium chloride brines, and pharmaceutical-grade calcium carbonate from Indian and Chinese chemical processors. Single-source vulnerability concentrates in aseptic filling equipment for liquid suspensions, where German and Dutch cleanroom engineering capabilities dominate. Distribution runs through pharmacy chain exclusivity arrangements in North America, direct-to-consumer subscription channels for chronic users, and national procurement tenders aligned with WHO essential medicines criteria in low-income health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where geriatric polypharmacy protocols and employer-sponsored wellness programs tilt demand toward premium specifications with documented bioequivalence and rapid-dissolve coatings.
For Market Incumbents: Extend magnesium-dominant formulation portfolios through rapid-dissolve coating patents that capture dysphagia segments previously served by liquids alone. Deepen backward integration into Indian pharmaceutical-grade calcium carbonate supply to offset bauxite concentration risk. Channel control through pharmacy chain exclusivity remains essential as biosimilar proton pump inhibitors erode chronic GERD repeat-purchase frequency. For New Entrants and Emerging Players: Launch via single-dose sachet formats targeting commuter and travel segments in Brazilian and Mexican convenience channels where shelf-space premiums reward portability innovation. White-space concentration sits in Indian tier-2 and tier-3 cities where CDSCO streamlined OTC pathways mature and organized retail penetration remains below threshold. Direct-to-consumer subscription mechanics offer the most penetrable go-to-market angle for chronic acid reflux sufferers in technology sector employment clusters. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists with cost-engineered production capacity and underutilized aseptic filling infrastructure. Long-term viability favors manufacturers with locked EMA dossiers and WHO essential medicines alignment that secures volume anchors in low-income procurement tenders. Watch ECHA guidance updates on nanomaterial characterization as the signal for accelerated consolidation among liquid suspension producers facing 12-18 month launch delays.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-to-Magnesium Formulation Revalidation | FDA 21 CFR 331 compliance deadlines force 18-24 month stability testing investments that strain R&D pipelines. |
| Aseptic Filling Capacity Expansion | German cleanroom engineering capabilities concentrate supply leverage for pediatric and geriatric liquid suspensions. |
| Direct-to-Consumer Subscription Launch | Texas and California technology sector employers bypass retail markup through formulary placement negotiations. |
| WHO Essential Medicines Alignment | National procurement tenders in low-income health systems favor compliant manufacturers with volume anchors. |
| Rapid-Dissolve Coating Patent Investment | Dysphagia patient segments in Japanese long-term care facilities standardize on scored tablets with dose flexibility. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and channel procurement records — were reconciled against primary interviews with pharmaceutical manufacturing executives, hospital formulary directors, pharmacy chain category managers, and CDSCO regulatory affairs leads. Secondary validation drew from FDA 21 CFR 331 monograph updates, EMA centralized marketing authorization submissions, ECHA REACH guidance documents, and WHO essential medicines procurement databases. Bottom-up volume modeling across formulation chemistry, delivery format, and channel access segments triangulated against top-down macroeconomic indicators.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, form, application, end user, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume patterns adjusted for salt-substitution revalidation timelines and aseptic filling capacity constraints. Forecast inputs incorporated geriatric demographic projections, polypharmacy protocol adoption rates, and employer wellness program penetration by sector.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA nanomaterial guidance acceleration or bauxite supply disruption scenarios. Projections reflect assumptions about aluminum exposure threshold enforcement continuity and biosimilar proton pump inhibitor substitution velocity. Material deviation in FDA 21 CFR 331 compliance timelines or CDSCO OTC pathway maturation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Efinaconazole Market