
 Global Preventive Vaccines Market | 2026-2036
Global Preventive Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Preventive Vaccines Market Foresight
mRNA platform technology is reconfiguring how preventive vaccines are designed, manufactured, and scaled for pandemic readiness. Pfizer Inc. leverages its BioNTech partnership to sustain leadership in mRNA-based respiratory vaccines. GSK plc anchors its competitive position through differentiated adjuvant systems and established viral vector capabilities. Sanofi competes across multiple modalities while navigating manufacturing complexity for global supply security.
Preventive vaccines are biologic preparations containing attenuated or inactivated pathogens, purified subunits, nucleic acid sequences, or recombinant proteins that stimulate adaptive immunity without causing disease; they require cold-chain distribution between 2°C and 8°C for most formulations, with mRNA candidates demanding ultra-low temperature storage at -70°C. The live attenuated category occupies established positions in measles and polio eradication programs where single-dose efficacy creates cost advantages for public health systems. mRNA and viral vector segments represent the fastest-growing technology platforms as manufacturers invest in flexible manufacturing infrastructure capable of rapid antigen adaptation. Pediatric centers and public health clinics concentrate demand through government program procurement, while retail pharmacies and online channels extend access for adult boosters and travel vaccines.
The FDA's accelerated approval pathways and the EMA's adaptive licensing frameworks shape how novel platforms reach patients, with WHO prequalification requirements determining access to procurement through Gavi and UNICEF. India's CDSCO and the PLI scheme for biotechnology manufacturing are building domestic fill-finish capacity that reduces import dependence for national immunization programs. Stakeholders must monitor how regulatory convergence on mRNA manufacturing standards affects technology transfer agreements and local production requirements in middle-income countries.
Market Dynamics
mRNA platform standardization is collapsing traditional development timelines while cold-chain infrastructure investments determine which manufacturers capture pandemic preparedness contracts. This structural shift rewards flexible bioreactor capacity over legacy egg-based production systems.
Growth Catalysts
- India's PLI scheme for biotechnology:Domestic fill-finish capacity expansion reduces import dependence for national immunization programs while building regional export hubs.
- Pediatric immunization program expansion:Government procurement in emerging economies anchors volume demand for combination vaccines and measles-rubella formulations.
- Self-amplifying RNA platforms:Lower dose requirements per immunization compress manufacturing costs and enable distributed production models.
Market Restraints
- Ultra-low temperature infrastructure:mRNA storage at -70°C limits distribution to urban centers with specialized cold-chain equipment, excluding rural clinics.
- Serum protein supply concentration:Bovine serum albumin and recombinant protein inputs concentrate in North American and European suppliers, creating input cost volatility.
- WHO prequalification timelines:Stringent stability data requirements delay access to Gavi and UNICEF procurement for novel adjuvant formulations.
Strategic Opportunities
- Indonesia's archipelago distribution challenge:Thermostable vaccine formulations unlock procurement from the national immunization program for outer island provinces.
- Retail pharmacy channel expansion:Adult booster and travel vaccine demand migrates from public clinics to CVS, Walgreens, and Boots networks with refrigerated storage.
- Combination respiratory vaccines:COVID-influenza-RSV trivalent candidates align with FDA accelerated approval pathways for platform technologies.
Industry Challenges
- Bioreactor operator skill scarcity:mRNA lipid nanoparticle formulation requires specialized training absent in legacy vaccine manufacturing workforces.
- Fill-finish line validation timelines:CDSCO, EMA, and FDA divergent sterility testing protocols extend facility commissioning by 18-24 months.
- Legacy ERP integration:Electronic batch record systems for continuous manufacturing clash with paper-based quality systems at acquired facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Preventive Vaccines Market |
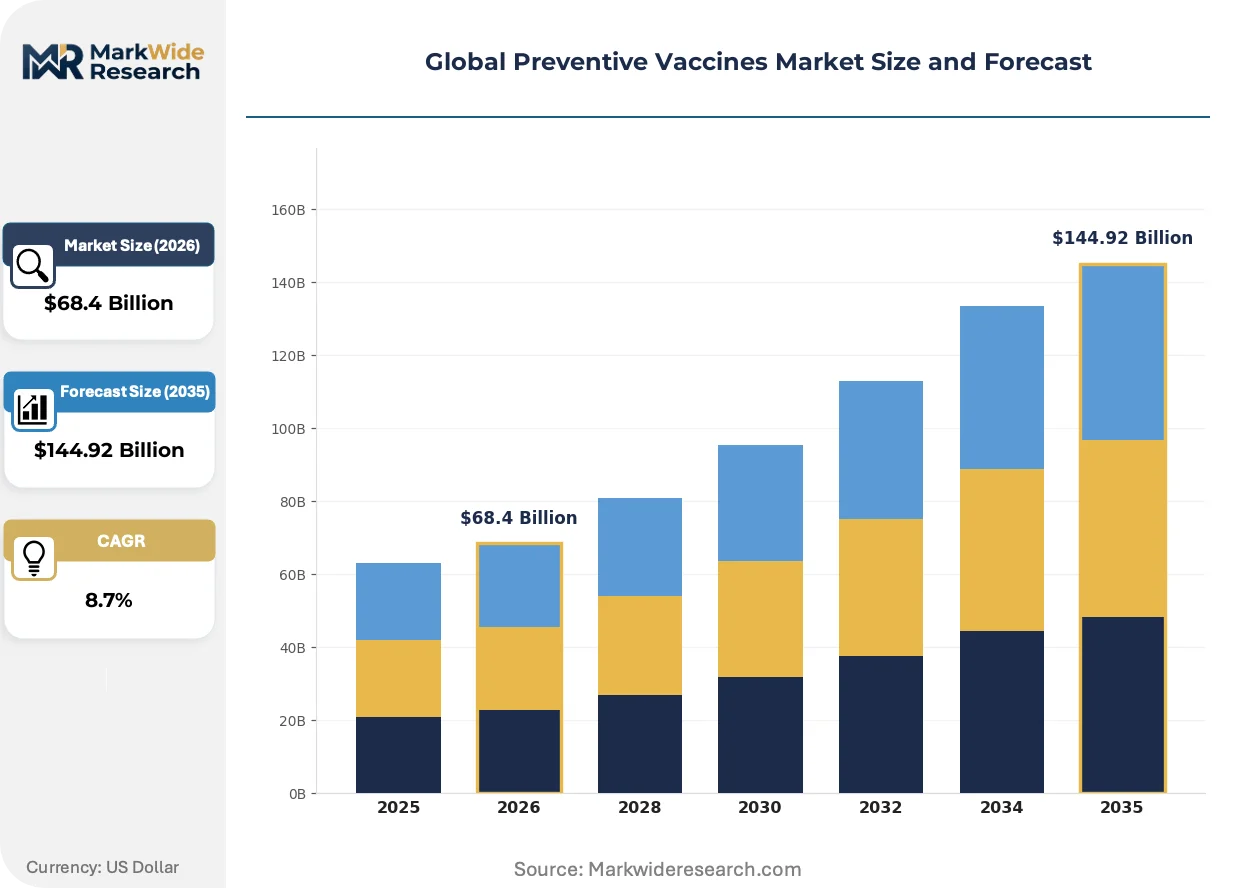
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, mRNA, Viral Vector, Toxoid Disease Target: Influenza, Hepatitis B, Human Papillomavirus, Diphtheria, Polio, Measles End User: Public Health Clinics, Pediatric Centers, Travel Medicine Clinics, Occupational Health Units, Military Medical Facilities Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Government Programs, Private Clinics |
| Companies Covered | Pfizer Inc., GSK plc, Sanofi, Merck & Co. Inc., Johnson & Johnson Services, Inc., AstraZeneca PLC, CSL Limited, Serum Institute of India Pvt. Ltd., Novavax Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Preventive Vaccines Market Shifts & Advancements
Platform technology convergence is collapsing the boundary between preventive and therapeutic vaccine development, with manufacturers repurposing pandemic infrastructure for oncology and chronic disease applications.
Microfluidic lipid nanoparticle synthesis is collapsing traditional mixing-scaleup bottlenecks by enabling continuous rather than batch production. Contract development and manufacturing organizations in Switzerland and Massachusetts are adopting these systems to serve mid-size biotech clients. The structural consequence is collapsing minimum efficient scale thresholds, allowing regional fill-finish facilities to achieve cost parity with centralized plants.
The EMA's adaptive licensing frameworks now permit rolling review of manufacturing process changes for platform technologies, compressing post-approval modification timelines. Vaccine developers submit CMC updates as real-time stability data accumulates rather than awaiting complete dossiers. This shift most affects mRNA and viral vector segments where process analytical technology investments enable parametric release.
Government procurement agencies are consolidating supplier lists to single-source or dual-source arrangements for critical antigens, displacing fragmented multi-vendor purchasing. Brazil's Ministry of Health and Nigeria's National Primary Health Care Development Agency now negotiate multi-year volume commitments with fill-finish partners. This concentration is most visible in pentavalent and hexavalent pediatric combinations where long-term antigen supply security overrides price competition.
Global Preventive Vaccines Market Segmentation
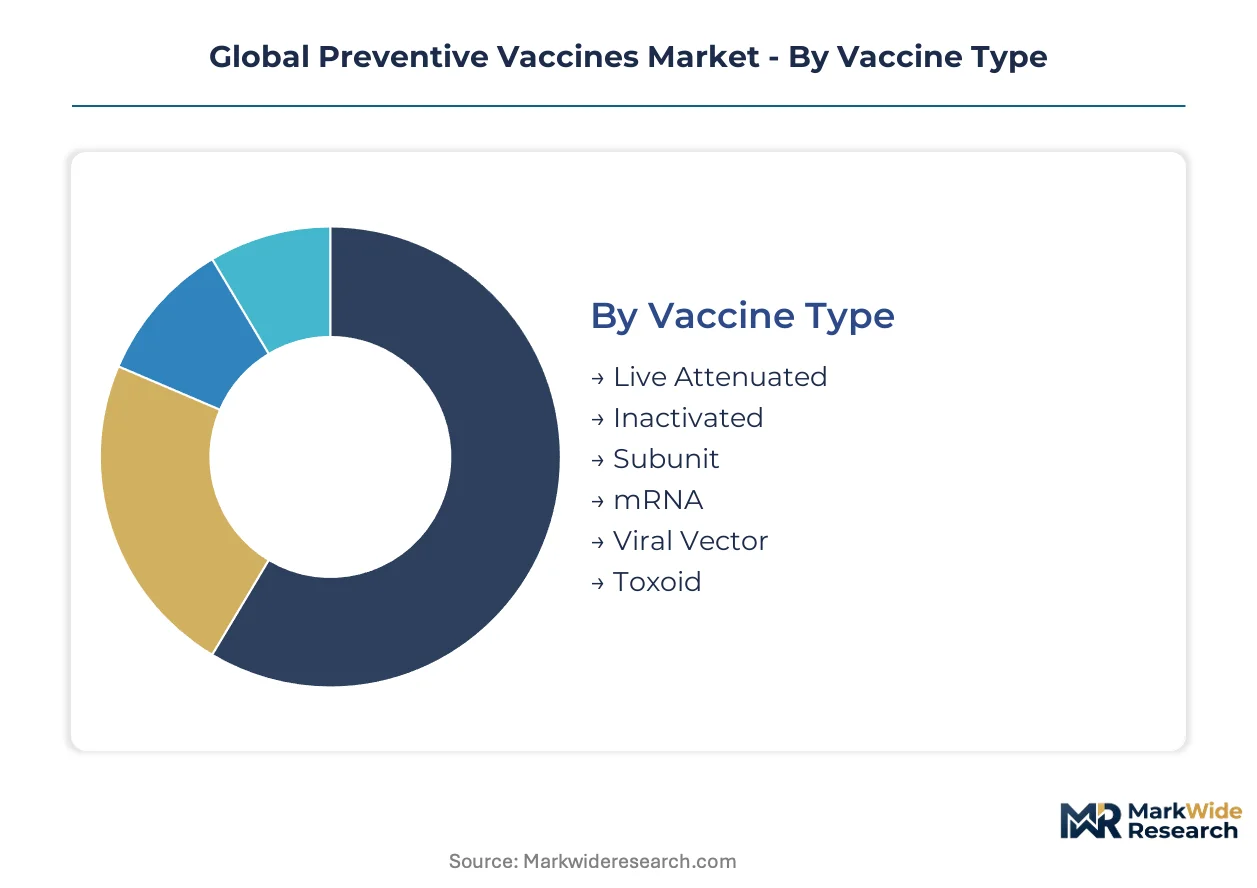
Vaccine market segmentation reveals how technology platforms, disease priorities, and procurement channels allocate manufacturing capacity and pricing power. Distinct cold-chain requirements and regulatory pathways create divergent margin structures across each category.
Vaccine Type:
Technology platform selection determines manufacturing infrastructure investment, cold-chain specifications, and regulatory approval pathways.
- Live Attenuated:Contains weakened pathogen strains that replicate minimally in host cells to stimulate durable cellular immunity. Demand concentrates in India's Universal Immunization Programme and Nigeria's national campaigns where single-dose measles and oral polio formulations reduce logistics burden.
- mRNA:Nucleic acid sequences encoding target antigens delivered via lipid nanoparticles, enabling rapid antigen redesign without cell culture. Pfizer-BioNTech and Moderna capacity expansions in Massachusetts and Belgium anchor supply for respiratory combination candidates.
- Inactivated:Chemically or heat-killed whole pathogens requiring adjuvant enhancement for immunogenicity.
- Subunit:Purified protein or polysaccharide antigens selected for specific epitope targeting.
- Viral Vector:Replication-deficient viruses delivering genetic cargo, with GSK and Janssen manufacturing networks supporting platform flexibility.
- Toxoid:Formaldehyde-inactivated bacterial exotoxins for diphtheria and tetanus prevention in pediatric combination schedules.
Live attenuated platforms command the established base in emerging economy procurement. The steepest expansion runs through mRNA as self-amplifying RNA formats reduce dose requirements and enable distributed manufacturing.
Disease Target:
Disease prioritization reflects epidemiological burden, eradication campaign funding, and adolescent versus infant immunization scheduling.
- Influenza:Seasonal strain selection by WHO Global Influenza Surveillance and Response System drives annual manufacturing campaigns. Serum Institute of India and Sanofi Pasteur dominate southern hemisphere formulation supply for Australia's National Immunisation Program and Brazil's Ministry of Health procurement.
- Human Papillomavirus:Recombinant VLP-based formulations targeting oncogenic serotypes. Gavi subsidy expansion in sub-Saharan Africa and Southeast Asia accelerates two-dose schedule adoption for 9-14 year old cohorts.
- Hepatitis B:Recombinant surface antigen vaccines integrated into pentavalent pediatric combinations.
- Diphtheria:Toxoid component within DTaP and Tdap formulations for infant and adolescent boosters.
- Polio:IPV and bOPV formats in WHO-coordinated eradication transition protocols.
- Measles:Monovalent and measles-rubella combinations in catch-up campaign formats.
Influenza anchors seasonal manufacturing volume and capacity utilization planning. Human papillomavirus claims the steepest volume trajectory as national programs expand adolescent coverage and single-dose schedule evidence accumulates.
End User:
Customer type shapes procurement mechanisms, cold-chain investment requirements, and reimbursement pathways.
- Public Health Clinics:Government-funded immunization delivery through fixed sites and outreach sessions. India's 27,000+ sub-centers and Nigeria's primary health care facilities concentrate demand for thermostable, multi-dose vial presentations.
- Pediatric Centers:Specialized childhood immunization services with combination vaccine preference. Brazil's municipal health secretariats and Indonesia's posyandu networks prioritize hexavalent and pentavalent formulations.
- Travel Medicine Clinics:Pre-departure consultation services for yellow fever, typhoid, and Japanese encephalitis prophylaxis.
- Occupational Health Units:Employer-sponsored hepatitis B and influenza programs for healthcare and manufacturing workforces.
- Military Medical Facilities:Centralized procurement for deployable force protection against biological threats and endemic disease exposure.
Public health clinics command the volume base through Gavi and UNICEF consolidated purchasing. Pediatric centers generate the steepest expansion as middle-income countries transition from Gavi eligibility to domestic financing.
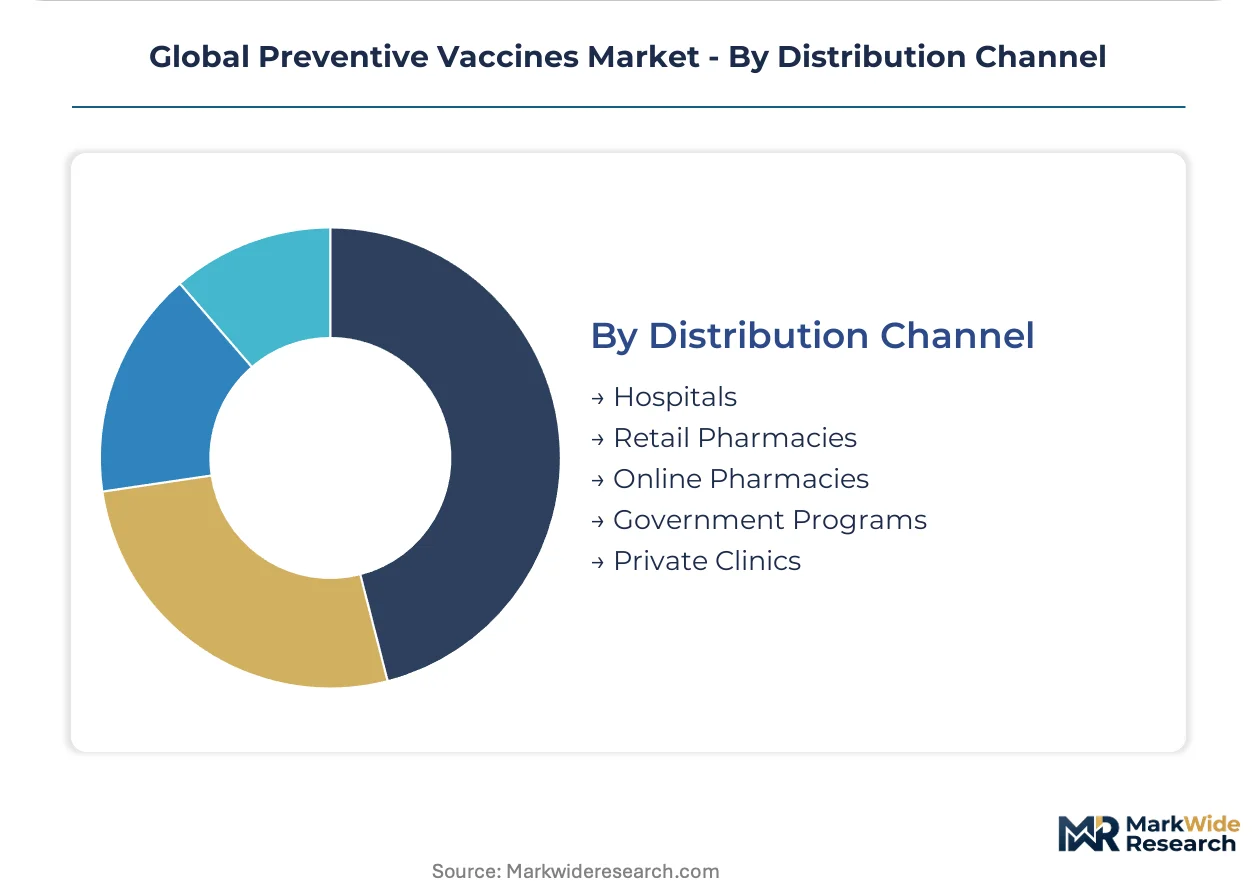
Distribution Channel:
Channel structure determines cold-chain integrity responsibility, patient access convenience, and margin capture allocation.
- Government Programs:Centralized tendering with UN agencies for national immunization program supply. India's PLI scheme and Brazil's Fiocruz fill-finish partnerships reduce import dependence while building regional export capability.
- Retail Pharmacies:CVS, Walgreens, and Boots networks with refrigerated storage for adult boosters, travel vaccines, and shingles immunization. Pharmacy technician vaccination authority expansion in US states and UK provinces extends access beyond physician offices.
- Hospitals:Inpatient and outpatient pharmacy dispensing for immunocompromised patient protocols.
- Online Pharmacies:Digital scheduling with clinic-based administration for travel and occupational health categories.
- Private Clinics:Fee-for-service delivery of non-NHS and non-program vaccines in UK and European markets.
Government programs command the established procurement volume through multi-year antigen supply agreements. Retail pharmacy channels claim the steepest expansion as pharmacist scope-of-practice laws relax and adult immunization schedules complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health procurement agencies in emerging economies concentrate demand through multi-year antigen supply agreements, while mature markets shift toward retail pharmacy channels for adult immunization. India's government tenders anchor volume, Brazil's Fiocruz partnerships build regional export capability, and Germany's CDMO clusters serve platform technology developers.
United States
FDA accelerated approval pathways and BARDA pandemic preparedness contracts drive demand for flexible manufacturing infrastructure. The FDA's rolling review mechanisms compress post-approval modification timelines for mRNA platforms. Massachusetts biotech clusters around Cambridge and the Research Triangle in North Carolina concentrate lipid nanoparticle formulation capacity for respiratory combination candidates.
India
CDSCO regulations and the PLI scheme for biotechnology manufacturing expand domestic fill-finish capacity for national immunization programs. The Serum Institute of India anchors supply for Gavi and UNICEF procurement through its Pune manufacturing network. Hyderabad's vaccine cluster attracts technology transfer partnerships for regional export hub development.
Germany
EMA adaptive licensing frameworks and BioNTech's mRNA manufacturing investments position the country for platform technology leadership. The EMA's rolling review of manufacturing process changes enables real-time CMC updates. Marburg and Idar-Oberstein host specialized CDMO capacity for viral vector and mRNA production serving European supply security.
Brazil
Fiocruz fill-finish partnerships and Ministry of Health multi-year volume commitments reduce import dependence for pentavalent pediatric combinations. ANVISA regulatory convergence with WHO prequalification standards accelerates access to novel adjuvant formulations. São Paulo's Butantan Institute anchors domestic yellow fever and influenza antigen production for Latin American distribution.
Switzerland
Swissmedic oversight and concentrated CDMO infrastructure in Basel and Zurich serve mid-size biotech clients adopting microfluidic continuous manufacturing. The country's neutrality status attracts technology transfer agreements for regional fill-finish partnerships. Geneva-based WHO prequalification processes determine access to consolidated procurement through Gavi and UNICEF channels.
Global Preventive Vaccines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement mechanisms. Government tender winners anchor volume through multi-year antigen supply agreements, while retail pharmacy networks capture margin from adult boosters and travel vaccines. Three archetypes dominate: platform technology developers with flexible bioreactor capacity, established viral vector manufacturers with adjuvant differentiation, and volume-scale fill-finish specialists serving emerging economy procurement. Competitive moves concentrate on strategic partnerships for technology transfer and capacity expansion in regional export hubs.
Within the platform technology tier, Pfizer Inc. and GSK plc exemplify divergent strategic positioning. Pfizer Inc. occupies a position anchored by mRNA lipid nanoparticle partnerships, while GSK plc represents adjuvant system and viral vector capabilities. Serum Institute of India Pvt. Ltd. sits within the volume-scale specialist archetype, serving consolidated procurement through government program supply agreements.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| Sanofi |
| Merck & Co. Inc. |
| Johnson & Johnson Services, Inc. |
| AstraZeneca PLC |
| CSL Limited |
| Serum Institute of India Pvt. Ltd. |
| Novavax Inc. |
| Others |
Supply & Pricing Matrix
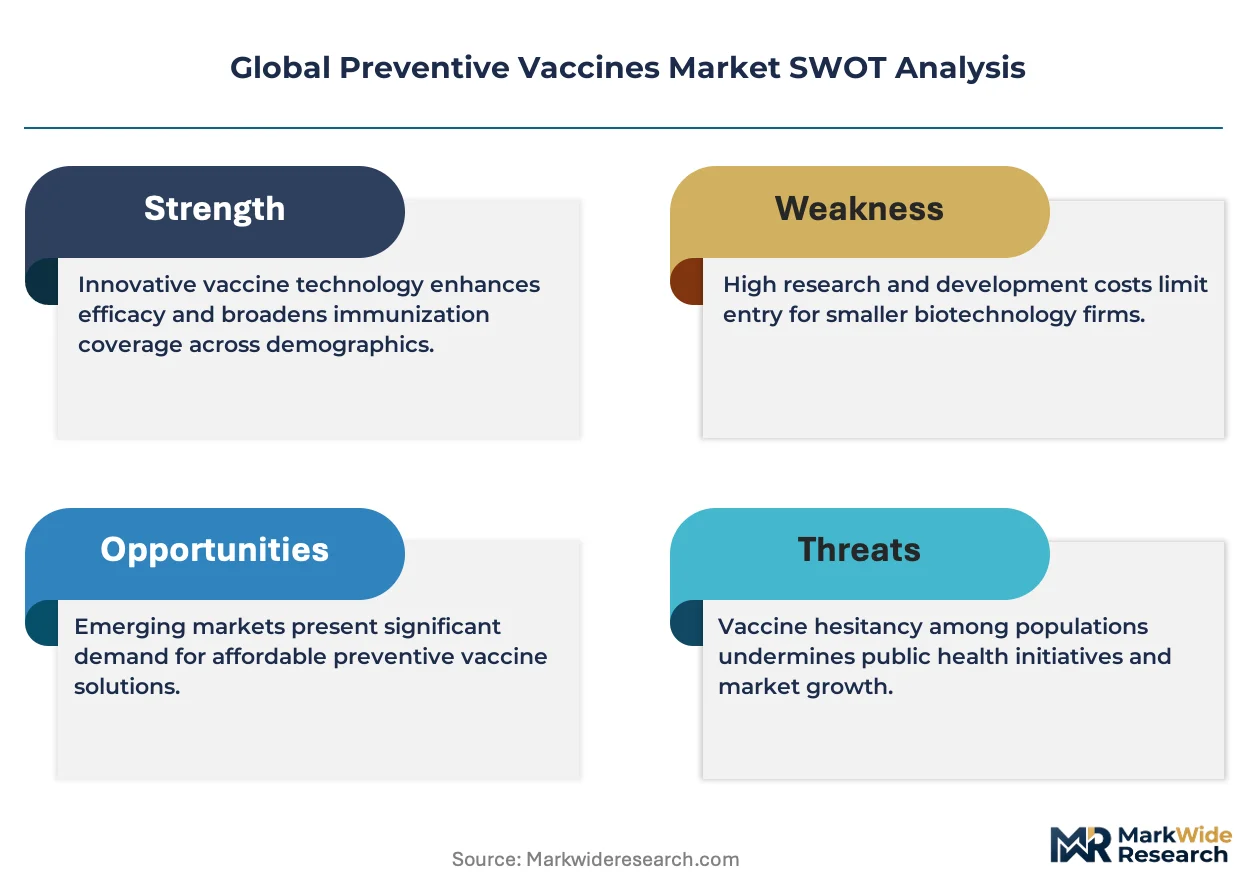
Ultra-low temperature infrastructure scarcity determines both premium-mid-economy pricing differentiation and regional supply chain shape in mRNA vaccine distribution. Single-source dependency on North American bovine serum albumin suppliers compresses margins for emerging economy procurement while creating tiered access based on cold-chain capabilities.
Pricing Analysis
Cost-plus contracts with serum protein indexation dominate Gavi and UNICEF procurement for emerging economy programs. Price differentiation rests on WHO prequalification status and fill-finish certification tier, with accredited facilities commanding premiums over non-prequalified alternatives. Cost compression in standard-tier combination vaccines is intensifying because India's PLI scheme expands domestic manufacturing capacity. Government procurement agencies exhibit highest price sensitivity through consolidated tender mechanisms, while retail pharmacy channels absorb moderate premiums for convenience access.
Supply Chain Analysis
Lonza, Catalent, and Thermo Fisher Scientific hold concentrated contract manufacturing capacity for lipid nanoparticle formulation and viral vector production. Geographic supply concentration centers on Switzerland, Belgium, and Massachusetts for platform technology manufacturing, with India and Brazil building regional fill-finish hubs. Raw material dependencies draw from bovine serum albumin, synthetic lipids, and plasmid DNA templates. Single-source vulnerability in lipid supplier networks creates procurement risk for mRNA scale-up campaigns. Distribution runs through government program central stores, cold-chain logistics providers, and retail pharmacy networks with refrigerated storage capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The preventive vaccines market is entering a cyclical recovery phase. Pandemic preparedness contract replenishment by BARDA and CEPI drives the next investment wave.
For Market Incumbents: Insulate mRNA manufacturing margins by securing captive lipid nanoparticle supply through backward integration into synthetic lipid production. Lock in multi-year government procurement contracts before India's PLI scheme matures domestic competitors. The priority lever is cold-chain infrastructure ownership in emerging economy distribution networks.
For New Entrants and Emerging Players: Build out thermostable formulation capabilities to target Indonesia's archipelago provinces and sub-Saharan Africa's last-mile distribution gaps. The most penetrable segment is self-amplifying RNA platforms requiring lower dose volumes and enabling distributed manufacturing models. Partner with established CDMOs in Switzerland or Massachusetts for rapid technology transfer without capital-intensive facility construction.
For Investors and Strategic Acquirers: EMA adaptive licensing framework expansion reshapes the acquisition landscape by compressing regulatory timelines for platform technology assets. Long-term viability favors CDMOs with parametric release capabilities and continuous manufacturing infrastructure. Target acquisition archetypes are mid-size biotechs with validated mRNA or viral vector platforms lacking commercial scale. The signal to watch is WHO prequalification queue positioning for novel adjuvant formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Lonza's Belgian lipid nanoparticle capacity expansion serves BioNTech-Pfizer respiratory combination candidates. |
| Regulatory Approval Pathway | FDA accelerated approval compresses development timelines for platform technology pandemic preparedness contracts. |
| Long-term Supply Agreement | Brazil's Ministry of Health multi-year pentavalent commitments reduce import dependence through Fiocruz partnerships. |
| Technology Licensing | Serum Institute of India technology transfers from Novavax build regional subunit vaccine export capability. |
| Capacity Expansion | Hyderabad vaccine cluster investments under PLI scheme anchor South Asian fill-finish regional hub development. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and EMA, government procurement managers at Gavi and UNICEF, and cold-chain logistics specialists. Secondary validation drew from FDA filings, EMA adaptive licensing decisions, WHO prequalification databases, and national immunization program tender documents. Bottom-up volume modeling across technology platforms and disease targets was triangulated with top-down market sizing from trade flow analysis.
Calibration against historical platform adoption curves and procurement volume commitments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vaccine type, disease target, end user category, and distribution channel structure. CAGRs were derived from regression analysis of procurement volume trends and capacity expansion announcements. Industry-specific forecast inputs incorporated WHO prequalification timeline assumptions and PLI scheme capacity buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese mRNA entrants or Indian biosimilar specialists would shift outcomes through accelerated price competition. Regulatory divergence between FDA, EMA, and CDSCO on lipid nanoparticle manufacturing standards could compress or extend technology transfer timelines. Quarterly review of Gavi pledge disbursement rates and BARDA pandemic preparedness contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Diuretic Drugs Market