
 North America Maize Seed Treatment Market | 2026-2036
North America Maize Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Maize Seed Treatment Market Analytics
US Midwest formulators is expanding production capacity for bio-based seed coatings as regulatory pressure on conventional chemistry intensifies. Bayer AG leverages its crop science pipeline to sustain leadership in fungicidal seed treatments across the I-States. BASF SE anchors its position through polymer-based film coatings that improve active ingredient adhesion during high-speed planting. Corteva Agriscience differentiates via integrated seed-and-trait bundles that pair proprietary genetics with tailored treatment protocols.
North America maize seed treatment encompasses the application of protective or performance-enhancing agents—typically fungicides, insecticides, or biological inoculants—onto corn seed prior to planting, with formulations designed to achieve uniform coverage at rates of milligrams of active ingredient per seed kernel. The process employs film-coating or encrusting technologies to create a durable layer that withstands mechanical handling during bulk transport and precision planting operations. Fungicides dominate current value capture given established efficacy against Pythium and Fusarium species, while biopesticides represent the fastest-expanding category as EPA registration pathways for microbial and biochemical actives streamline. Liquid formulations occupy the largest share of application method throughput due to compatibility with continuous-treat systems at commercial seed conditioning facilities.
EPA re-registration reviews under FIFRA shape product availability timelines, while the USDA's NRCS conservation standards influence farmer eligibility for cost-share programs when adopting reduced-risk treatments. Health Canada's PMRA maintains parallel regulatory stringency for cross-border seed commerce, creating compliance harmonization imperatives for suppliers operating throughout the Great Plains and Canadian prairies. Stakeholders must track state-level pollinator protection plans and seed-treatment use reporting mandates as these frameworks proliferate beyond current federal baselines.
Market Dynamics
EPA's re-evaluation of neonicotinoid registrations under FIFRA is forcing formulators to accelerate biological alternative development while maintaining efficacy against soil-borne pathogens across the Corn Belt.
Growth Catalysts
- Continuous corn rotations:Iowa and Illinois farmers face amplified pest pressure from Fusarium and Pythium species, justifying premium expenditures on fungicidal seed treatments.
- USDA NRCS conservation standards:Cost-share program eligibility for reduced-risk treatments incentivizes adoption of biopesticide coatings among commercial grain operations.
- Film-coating technology:Polymer-based adhesion systems improve active ingredient retention during high-speed precision planting, reducing off-target loss.
Market Restraints
- Active ingredient supply concentration:Key fungicide intermediates rely on concentrated Asian chemical manufacturing, exposing formulators to tariff and shipping disruptions.
- Registration timeline friction:EPA's 15-18 month review cycle for novel biological actives delays product commercialization relative to grower planting schedules.
- Seed handling infrastructure:Legacy conditioning equipment at smaller cooperatives requires capital retrofit to accommodate liquid biological formulations.
Strategic Opportunities
- Canadian prairie expansion:Manitoba and Saskatchewan corn acreage growth creates underpenetrated demand for treated seed as spring wheat rotations diversify.
- Microbial consortia stacking:Combining Trichoderma species with rhizobia inoculants addresses multiple stressors in single application protocols.
- Direct-to-farm digital channels:E-commerce platforms bypass traditional distributor markups, capturing margin from price-sensitive mid-scale operators.
Industry Challenges
- Biological formulation expertise:Shortage of microbial stabilization chemists delays shelf-life extension for ambient-storage biopesticide products.
- Cross-border compliance synchronization:Divergent EPA and Health Canada PMRA data requirements force redundant toxicology studies for Great Plains suppliers.
- Planter calibration complexity:Variable seed size and coating thickness demand continuous equipment adjustment, increasing operator training burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Maize Seed Treatment Market |
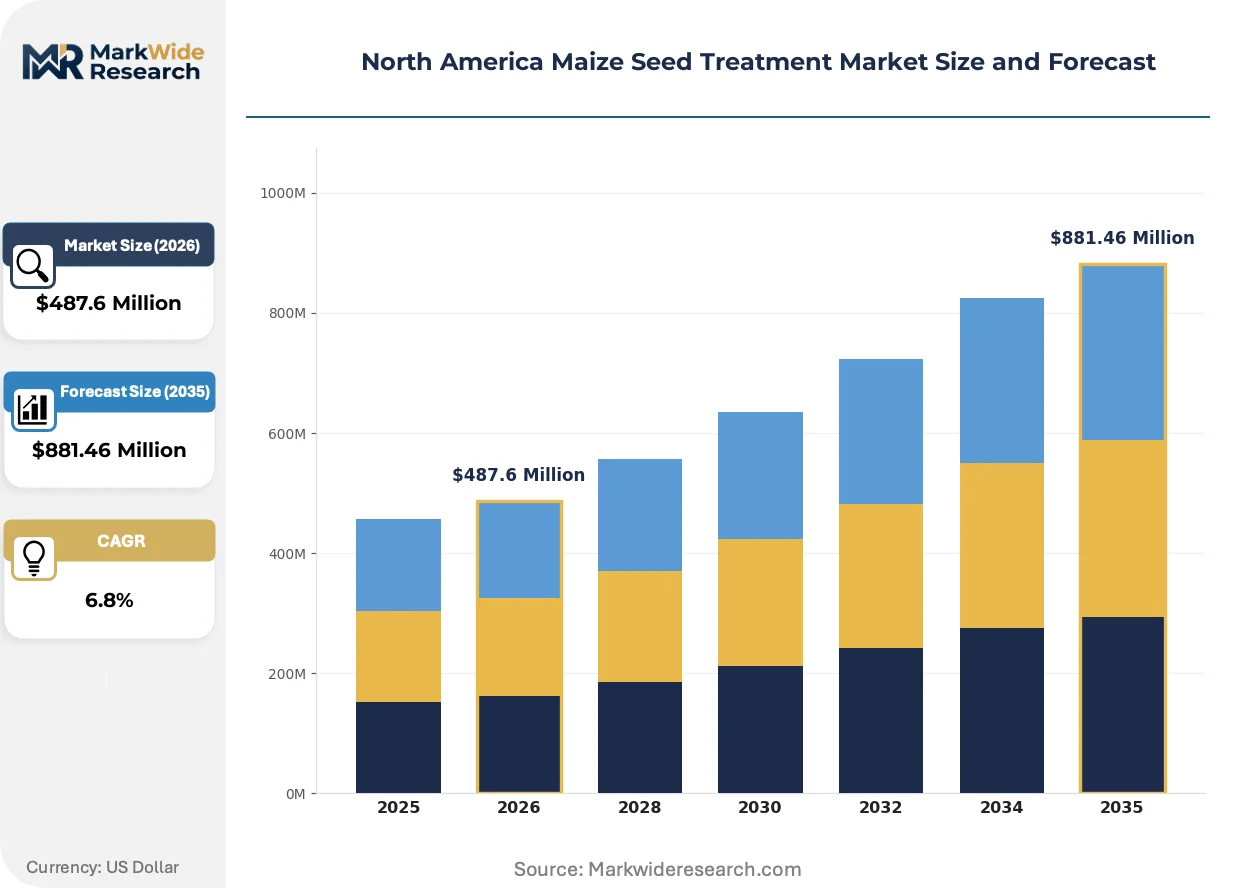
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Nutritional Enhancers, Biopesticides Application Method: Seed Coating, Drenching, Aerial Application, Soil Treatment End User: Farmers, Agricultural Cooperatives, Seed Manufacturers, Research Institutions Formulation Type: Liquid, Granular, Powder, Emulsifiable Concentrates |
| Companies Covered | Corteva Agriscience, Bayer AG, BASF SE, Syngenta Group, UPL Limited, FMC Corporation, Nufarm Limited, Adama Agricultural Solutions, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Maize Seed Treatment Market Evolving Landscape
Biological seed treatment technologies are displacing conventional chemistry across North American corn production, driven by regulatory pressure and end-user sustainability commitments.
RNA interference-based pest suppression is expanding into early-stage maize protection protocols. Large-scale Iowa and Illinois operators pilot these precision biocontrol agents against corn rootworm larvae. The technology is expanding into premium seed bundles as differentiation leverage against commodity-treated alternatives.
Health Canada's PMRA parallel review pathway with EPA is compressing registration timelines for microbial actives. This harmonization reduces redundant efficacy trials for suppliers operating across the US-Canadian border. Prairie provinces and northern tier states benefit most from synchronized product availability.
Outcome-based treatment protocols now tie seed performance guarantees to stand establishment metrics rather than active ingredient rates alone. Commercial grain operations in the Corn Belt negotiate these risk-sharing arrangements with conditioning facilities. Nebraska and Kansas elevators lead this contractual innovation, shifting technical accountability upstream.
North America Maize Seed Treatment Market Segmentation
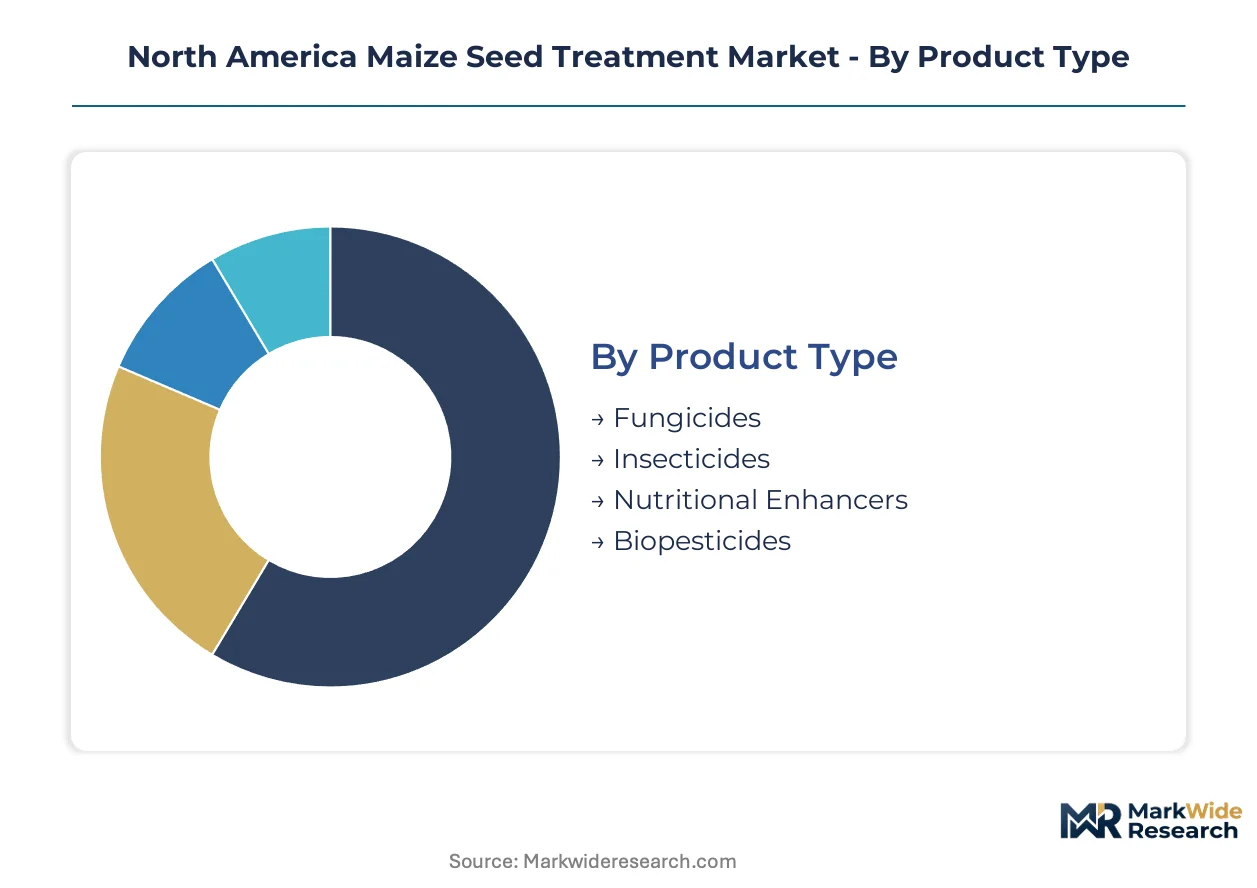
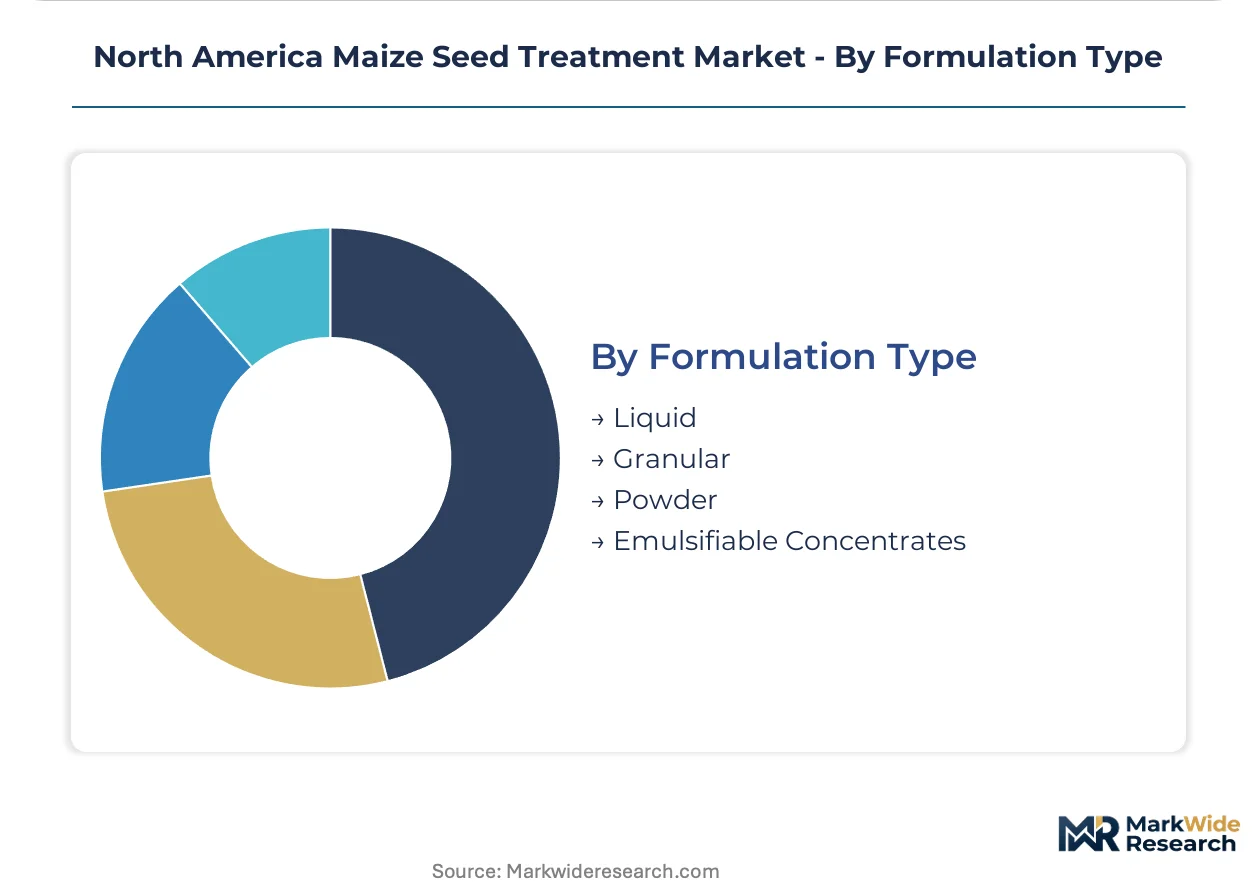
Segmentation in maize seed treatment reveals how product performance requirements vary across Corn Belt farming operations and Canadian prairie expansion zones. Distinct application methods and formulation technologies align with specific equipment capabilities and pest pressure profiles.
Product Type:
The customization-to-standardization spectrum spans from commodity fungicide platforms to precision-engineered biological consortia tailored to local pathogen profiles.
- Fungicides:Azoxystrobin and metalaxyl-based formulations dominate commercial grain operations across Iowa and Illinois, where Pythium and Fusarium pressure from continuous corn rotations justifies premium treatment expenditures. Bayer AG and BASF SE supply the majority of active ingredients for these protective coatings.
- Insecticides:Neonicotinoid-based treatments face EPA re-evaluation pressure under FIFRA, accelerating farmer migration toward diamide alternatives and biological replacements. Demand concentrates in high-rootworm-pressure zones of Nebraska and western Kansas.
- Nutritional Enhancers:Zinc and manganese micronutrient coatings address early-season deficiency risks in calcareous soils of the western Corn Belt.
- Biopesticides:Trichoderma and Bacillus-based microbial treatments represent the fastest-expanding category as EPA registration pathways streamline and NRCS cost-share eligibility expands.
Leading the category by volume: Fungicides. Expanding most quickly: Biopesticides.
Application Method:
Volume throughput and equipment capital intensity create a tiered hierarchy from continuous-treat seed conditioning facilities to specialized aerial operations.
- Seed Coating:Film-coating and encrusting technologies achieve uniform active ingredient distribution at commercial seed facilities across the I-States. Polymer-based adhesion systems from BASF SE improve retention during high-speed precision planting above 15 mph.
- Drenching:On-farm liquid application systems serve mid-scale operators in Minnesota and Wisconsin who purchase untreated bulk seed and apply biological treatments immediately pre-plant.
- Aerial Application:Helicopter and drone-based seed treatment addresses emergency replant scenarios following flood or frost events in the Red River Valley.
- Soil Treatment:In-furrow delivery of fungicide-insecticide combinations targets localized nematode pressure in sandy soils of Michigan and Indiana.
Highest throughput: Seed Coating. Fastest equipment upgrade cycle: Drenching systems for biological compatibility.
End User:
Procurement sophistication and technical specification authority vary sharply across direct farmers, cooperative aggregators, and integrated seed manufacturers.
- Farmers:Commercial grain operations above 5,000 acres in Illinois and Iowa negotiate outcome-based performance guarantees tied to stand establishment metrics rather than active ingredient rates alone.
- Agricultural Cooperatives:Legacy conditioning equipment at smaller cooperatives requires capital retrofit to accommodate liquid biological formulations, creating adoption friction in eastern Nebraska and western Iowa.
- Seed Manufacturers:Corteva Agriscience and Bayer AG integrate proprietary treatment protocols with genetics bundles, capturing margin through differentiated seed-and-trait offerings.
- Research Institutions:University extension services in Kansas and Ohio pilot RNA interference and microbial consortia stacking protocols before commercial release.
Volume concentration: Seed Manufacturers. Procurement innovation leader: Large-scale Farmers.
Formulation Type:
Physical state determines compatibility with existing seed handling infrastructure and ambient storage stability requirements.
- Liquid:Flowable suspensions and micro-emulsions occupy the largest share of commercial throughput due to compatibility with continuous-treat systems at seed conditioning facilities. Formulators face active ingredient supply concentration risks from Asian chemical manufacturing dependencies.
- Granular:Clay-based carriers deliver rhizobia inoculants in Manitoba and Saskatchewan where spring wheat rotations diversify into corn.
- Powder:Dust formulations serve heritage equipment at smaller operations but face handling loss and operator exposure concerns.
- Emulsifiable Concentrates:Solvent-based systems improve penetration of waxy seed coats in specialty corn hybrids but face volatile organic compound scrutiny from EPA.
Dominant formulation: Liquid. Steepest expansion trajectory: Granular for biological stabilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maize seed treatment demand concentrates in the Corn Belt's deep alluvial soils, where continuous cropping intensifies pathogen pressure and justifies protective input expenditures.
United States
Iowa and Illinois farmers drive the majority of regional fungicide seed treatment consumption, with continuous corn rotations amplifying Fusarium and Pythium threats. EPA's FIFRA re-registration reviews for neonicotinoids are accelerating biological alternative adoption across commercial grain operations. Des Moines and Peoria conditioning facilities upgrade polymer-based film-coating equipment to improve active ingredient retention during high-speed planting above 15 mph.
Canada
Manitoba and Saskatchewan corn acreage expansion creates underpenetrated demand as spring wheat rotations diversify into oilseed and grain corn. Health Canada's PMRA maintains parallel regulatory stringency with EPA, enabling synchronized product availability across the northern tier. Winnipeg and Saskatoon seed facilities pilot granular rhizobia inoculant formulations for the expanding prairie corn frontier.
Mexico
Bajío Region irrigated corn production generates concentrated demand for insecticidal seed treatments against fall armyworm and corn rootworm pressure. Mexico's national agricultural health authority SENASICA enforces phytosanitary standards for imported treated seed that align with North American trade protocols. Guanajuato and Jalisco seed distributors expand storage infrastructure for liquid biological formulations targeting the region's expanding commercial farming sector.
North America Maize Seed Treatment Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach, creating a tiered structure where integrated seed manufacturers capture margin through bundled genetics-and-treatment offerings. The vendor base separates into three strategic archetypes: multinational agrochemical conglomerates with crop science pipelines, specialized polymer and coating technology providers, and regional formulators serving cooperative conditioning facilities. Dominant competitive moves include backward integration into active ingredient manufacturing and strategic partnerships with precision planting equipment manufacturers to secure adhesion performance specifications.
Among Germany-based chemical conglomerates, Bayer AG and BASF SE exemplify the integrated agrochemical archetype, with Bayer anchoring fungicidal seed treatment supply and BASF occupying a position in polymer-based film coating systems. Corteva Agriscience represents the seed-manufacturer-integrated model, bundling proprietary genetics with tailored treatment protocols. These three players collectively illustrate how scale and vertical control over R&D pipelines shape competitive positioning in Corn Belt procurement channels.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| BASF SE |
| Syngenta Group |
| UPL Limited |
| FMC Corporation |
| Nufarm Limited |
| Adama Agricultural Solutions |
| Croda International Plc |
| Others |
Value Network & Pricing Analysis
USDA NRCS conservation standards gate qualified supply access for premium-tier biopesticide seed treatments, conditioning which formulators capture margin from commercial grain operations seeking cost-share eligibility. This environmental compliance threshold separates certified biological coating suppliers from commodity fungicide providers, concentrating pricing power among EPA-registered microbial formulators with validated NRCS pathways.
Pricing Analysis
Performance guarantee bundling separates premium treatment protocols from unbundled commodity coatings across Corn Belt procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects active ingredient sophistication, with biological consortia commanding premium positioning over azoxystrobin-based standards. Pricing pressure stems from Asian chemical intermediate dependencies that expose formulators to tariff volatility. Mid-scale cooperatives exhibit highest price sensitivity, while integrated seed manufacturers absorb cost fluctuations through captive genetics margins.
Supply Chain Analysis
Dual-sourcing mandates from major seed manufacturers require formulators to qualify backup suppliers for key fungicide intermediates, extending procurement timelines. Active ingredient manufacturing concentrates in China, India, and Germany, drawing from concentrated petrochemical feedstocks and specialized microbial fermentation capacity. Supply chain risk centers on trans-Pacific shipping chokepoints for liquid formulation components. Distribution runs through commercial seed conditioning facilities in Des Moines and Peoria before farm-level delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into microbial active ingredient production as formulators seek captive supply of Trichoderma and Bacillus strains to offset chemical intermediate volatility.
For Market Incumbents: Deepen polymer-based film-coating R&D partnerships with precision planting equipment manufacturers to lock in adhesion specifications above 15 mph planting speeds. Secure exclusive microbial strain licensing from university extension programs before EPA registration pathways mature. Biological formulation expertise scarcity threatens margin compression for late movers. For New Entrants and Emerging Players: EPA's streamlined registration pathway for microbial actives under FIFRA opens a window for specialized biopesticide formulators to capture share in Manitoba and Saskatchewan prairie expansion zones. Target mid-scale cooperatives in eastern Nebraska requiring capital retrofit for liquid biological compatibility. Pursue direct-to-farm digital channels bypassing traditional distributor markups. For Investors and Strategic Acquirers: Consolidation of conditioning facility networks in Iowa and Illinois is the leading indicator that upstream biological formulation assets will command scarcity premiums. Five-to-ten year viability favors acquirers of microbial stabilization chemists with ambient-storage shelf-life extension capabilities. Watch for EPA neonicotinoid re-evaluation final determinations as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Strain Production | Captive Bacillus and Trichoderma supply insulates formulators from Asian chemical intermediate tariff exposure. |
| Polymer Adhesion Technology Partnership | BASF SE-style film-coating collaborations with John Deere and Precision Planting secure high-speed planting specifications. |
| Prairie Conditioning Facility Acquisition | Winnipeg and Saskatoon seed assets capture underpenetrated demand from spring wheat rotation diversification. |
| Direct-to-Farm E-Commerce Platform Launch | Digital channels bypass cooperative distributor markups among price-sensitive mid-scale operators. |
| RNA Interference Pipeline Investment | Early-stage biocontrol positioning against corn rootworm prepares for post-neonicotinoid regulatory environment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving seed conditioning facility managers, microbial formulation chemists, cooperative procurement directors, and USDA extension agronomists. EPA FIFRA registration databases, Health Canada PMRA submission records, and USDA NRCS cost-share program utilization statistics provided triangulation points against bottom-up volume estimates from Corn Belt seed treater operations.
Granularity-level modeling segmented the market by product type, application method, end-user archetype, and formulation technology, with regional disaggregation across I-States, Canadian prairies, and Mexican irrigated zones. CAGRs were derived from trend-line analysis of historical treatment penetration rates and forward projection of biological adoption curves. Forecast inputs incorporated EPA registration timeline assumptions, planter speed technology diffusion, and prairie corn acreage expansion trajectories.
The model assumes a particular technology adoption path for RNA interference and microbial consortia; alternative pathways for neonicotinoid retention would alter the outlook for conventional chemistry suppliers. Deviation in EPA re-evaluation timelines or NRCS cost-share funding levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Myanmar Rice Seed Market
Seeds
Guar Market
Seeds
Carrot Seed Oil Market
Seeds
Global Forage Sorghum Seed Market
Seeds
North America Chia Seeds Market
Seeds
Global Vegetable Seed Market
Seeds
India Forage Seed Market
Seeds
Europe Forage Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Celery Seed Oil Market
Seeds
Uganda Seeds Market
Seeds
North America Grain Seed Market
Seeds
Global Wheat Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Global Oilseed Market
Seeds
Commercial Seed Market