
 Europe Forage Seed Market | 2026-2036
Europe Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Forage Seed Market Foresight
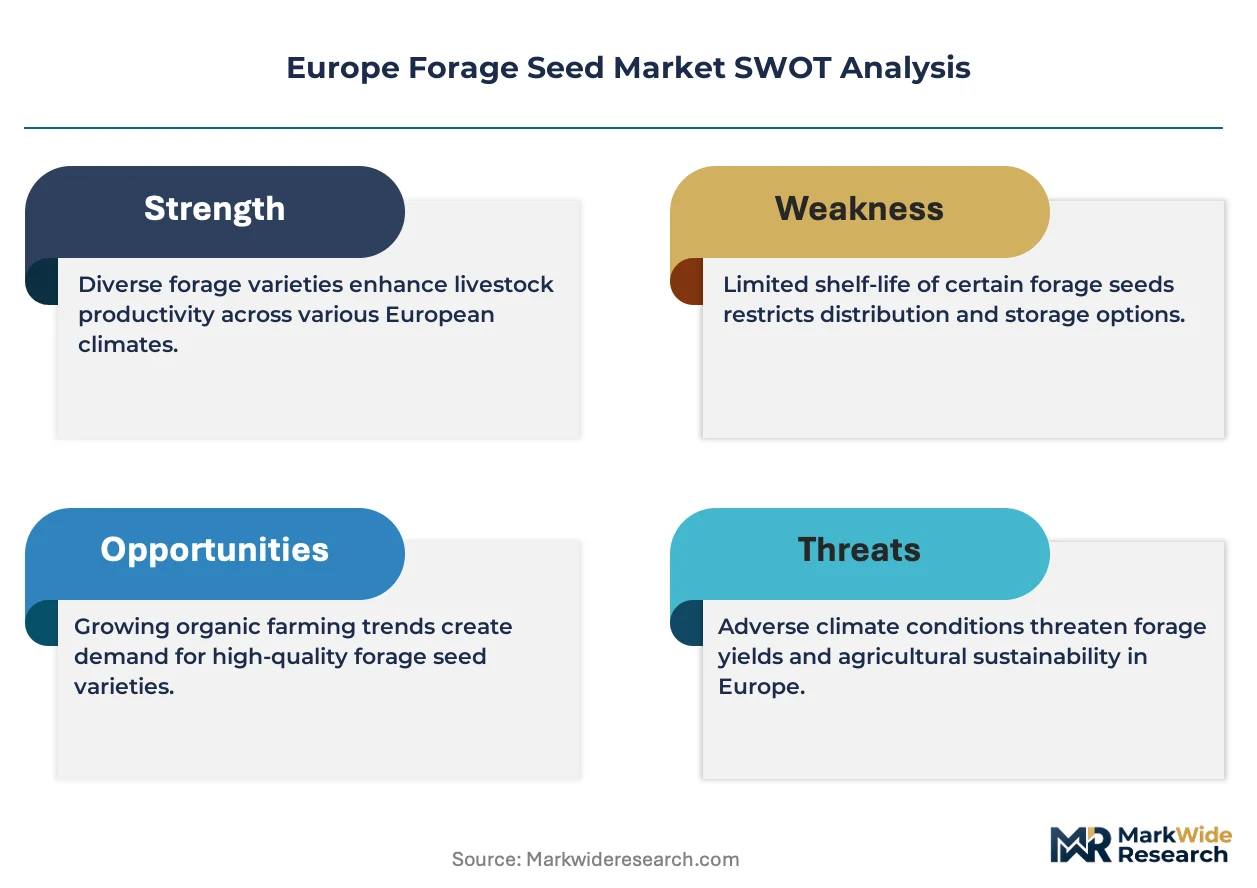
Gene-editing tolerance in varietal development is narrowing the performance gap between conventional breeding and biotech approaches across European forage programs. DLF leverages its Nordic breeding stations to anchor high-digestibility tetraploid ryegrass supply for northwest European dairy systems. Bayer AG competes through its hybrid alfalfa pipeline, while KWS SAAT SE & Co. KGaA specializes in festulolium crosses that extend the grazing season in Atlantic climates.
Forage seed comprises botanically distinct species cultivated specifically for animal consumption rather than grain harvest, with germination rates, crude protein content, and water-soluble carbohydrate levels serving as core quality parameters. Grasses dominate volume throughput across the continent due to established perennial ryegrass demand, yet legumes capture disproportionate margin pools where protein premiums apply to dairy ration formulations. Herbs occupy a nascent structural position within premium mixtures targeting monogastric forage protocols, while agricultural cooperatives remain the principal distribution channel controlling farmer access to certified varieties.
REACH governs phytosanitary inputs across the seed coating supply chain, while the EU Green Deal's nutrient-management benchmarks shape varietal selection toward nitrogen-fixing legumes. EFSA evaluates novel trait submissions for forage crops entering commercial multiplication. Stakeholders must monitor how the EU AI Act's eventual classification of genomic selection algorithms affects breeding program timelines and regulatory submission costs.
Market Dynamics
The EU Green Deal's nitrogen-efficiency mandates are compressing varietal selection windows, forcing seed houses to accelerate breeding cycles while maintaining germination standards and crude protein thresholds.
Growth Catalysts
- EFSA Novel Trait Pathway:Streamlined molecular characterization protocols for gene-edited forage varieties are reducing regulatory submission timelines across the EU-27.
- Loire Valley Dairy Intensification:French cooperative procurement contracts now specify certified tetraploid ryegrass with water-soluble carbohydrate premiums above 18%.
- Perennial Cropping Incentives:CAP Pillar II eco-scheme payments reward multi-year legume-grass mixtures that reduce synthetic nitrogen dependency.
Market Restraints
- Phosphate Coating Input Volatility:REACH-registered seed treatment chemistries face supply interruptions from concentrated Moroccan phosphate rock processing.
- Nordic Breeding Station Concentration:High-digestibility germplasm development clusters in Denmark and southern Sweden, creating single-region genetic bottleneck exposure.
- Conventional Alfalfa Substitution:Soybean meal imports from South American crushing operations undercut domestic protein crop seed demand in ration formulations.
Strategic Opportunities
- Polish Cooperative Channel Expansion:Underpenetrated dairy regions in Masovia and Podlasie lack certified distribution infrastructure for tetraploid varieties.
- EU AI Act Genomic Classification:Breeding algorithm transparency requirements may favor established programs with documented phenotypic databases over new entrants.
- Herb-Grass-Legume Mixtures:Chicory and plantain inclusion protocols for monogastric systems represent margin expansion beyond standard dairygrass portfolios.
Industry Challenges
- Quantitative Geneticist Talent Scarcity:European universities produce insufficient computational breeding specialists to staff expanding genomic selection programs.
- DUS Testing Timeline Compression:Distinctness, uniformity, and stability trials for novel festulolium crosses require 24-36 months, delaying commercial multiplication.
- Legacy Seed Processing Integration:Optical sorting and pelleting equipment from prior certification eras lacks interoperability with blockchain traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Forage Seed Market |
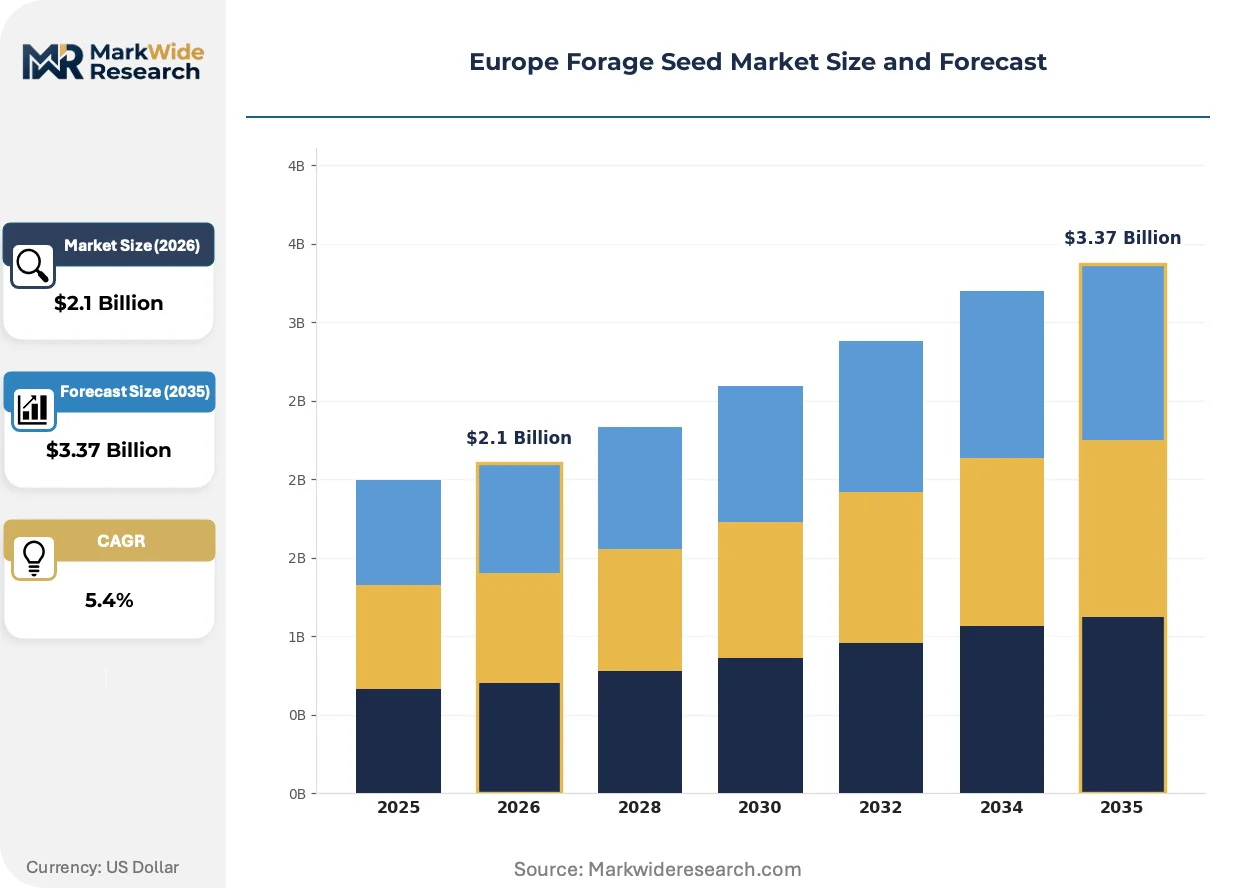
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Legumes, Grasses, Herbs, Mixtures End User: Dairy Farms, Livestock Producers, Crop Farmers, Research Institutes Distribution Channel: Online Retail, Agricultural Cooperatives, Seed Merchants, Direct Sales Packaging Type: Bulk Bags, Retail Packs, Small Packs, Totes |
| Companies Covered | Bayer AG, Euralis Semences, DLF, KWS SAAT SE & Co. KGaA, InVivo, Royal Barenbrug Group, RAGT Group, Advanta Seeds - UPL, Groupe Limagrain, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Forage Seed Market Shifts & Advancements
Gene-editing workflows are compressing the traditional 8-12 year breeding cycle, while regulatory frameworks scramble to classify resulting varieties. Three forces are actively restructuring competitive capability.
CRISPR-Cas9 applications in polyploid ryegrass are collapsing the performance validation timeline from multi-location field trials to controlled-environment phenotyping. DLF and Nordic breeding consortia now deploy high-throughput digestibility assays that compress selection decisions from three seasons to one. This acceleration is collapsing the historical advantage of public research stations with extensive land holdings.
REACH Annex XVII restrictions on neonicotinoid seed coatings are forcing coating houses to reformulate with biological alternatives. ECHA substance evaluation timelines extend 18-24 months for novel biocidal actives, compressing product development windows. French and German distributors now stock dual-certified conventional and biological-coated inventory to hedge regulatory uncertainty.
Dairy cooperative procurement committees are consolidating vendor lists from 12-15 certified suppliers to 4-6 strategic partners with full varietal portfolios. This concentration displaces independent seed merchants in Normandy and Brittany who lack breeding program backing. The shift is most visible in Ireland's Dairygold and Lakeland Dairies operations, where three-year varietal performance contracts now dominate spot purchasing.
Europe Forage Seed Market Segmentation
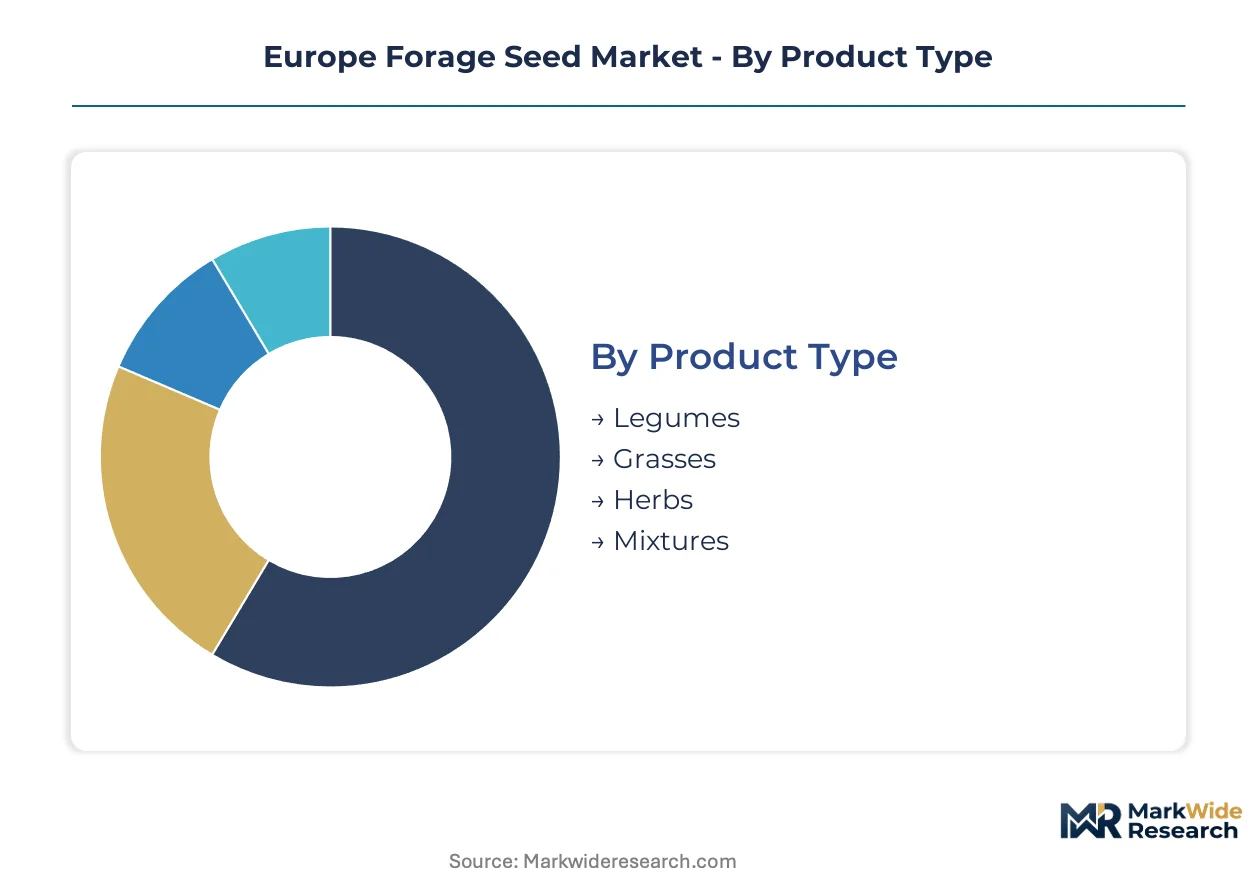
Segmentation in the Europe Forage Seed Market reveals how certified variety access, cooperative procurement power, and dairy ration formulation requirements reshape competitive positioning across distinct supply channels. Breeders and distributors must align germplasm portfolios with specific end-use protein specifications and regional distribution infrastructure.
Product Type:
After-sales agronomic support intensity varies sharply across botanical categories, with legume establishment protocols demanding intensive field advisory while grass varieties require minimal follow-up intervention.
- Legumes:Alfalfa and clover species deliver nitrogen fixation capabilities critical for EU Green Deal compliance, with crude protein levels exceeding 18% in dairy ration formulations. Demand concentrates in France's Normandy region where cooperative procurement contracts specify certified varieties with documented rhizobium inoculation protocols.
- Grasses:Perennial ryegrass dominates volume throughput through established tetraploid and diploid breeding lines, with water-soluble carbohydrate thresholds determining varietal selection. Germany's expanding dairy operations in Lower Saxony prioritize high-digestibility germplasm from Nordic breeding stations for milk yield consistency.
- Herbs:Chicory and plantain inclusion in premium mixtures targets monogastric forage protocols with condensed tannin benefits.
- Mixtures:Legume-grass-herb blends capture CAP Pillar II eco-scheme payments for multi-year sward persistence.
By volume, Grasses leads. By growth pace, Herbs is ahead.
End User:
Cost tier differentiation separates intensive commercial operations from smaller-scale producers, with procurement scale determining access to certified germplasm and varietal performance guarantees.
- Dairy Farms:Large-scale operations in the Loire Valley and Brittany negotiate three-year varietal performance contracts with full agronomic support packages, specifying tetraploid ryegrass with WSC premiums above 18%.
- Livestock Producers:Beef and sheep enterprises in Ireland's Dairygold catchment prioritize festulolium crosses extending the grazing season in Atlantic climates.
- Crop Farmers:Arable operations diversifying into forage production lack established seed supplier relationships and rely on merchant spot purchasing.
- Research Institutes:Public breeding stations in Denmark and Sweden maintain germplasm collections for DUS testing and novel trait evaluation under EFSA protocols.
Procurement concentration favors Dairy Farms for premium volumes, while Livestock Producers expand most quickly in underpenetrated regions.
Distribution Channel:
Customer type fragmentation across cooperative members, independent farmers, and institutional buyers forces parallel inventory strategies with distinct certification and payment terms.
- Agricultural Cooperatives:French and Irish dairy cooperatives now consolidate vendor lists from 12-15 suppliers to 4-6 strategic partners with full varietal portfolios, displacing independent merchants lacking breeding program backing.
- Seed Merchants:Independent distributors in Normandy and Brittany face margin compression as cooperative procurement committees demand documented traceability and blockchain certification.
- Direct Sales:Breeding houses bypass intermediaries for large-scale livestock operations requiring customized mixture formulations.
- Online Retail:Digital channels serve small-scale producers in Poland's Masovia region lacking cooperative infrastructure for certified tetraploid access.
Cooperative channel expansion is climbing the fastest, while Seed Merchants defend position through specialized local agronomic knowledge.
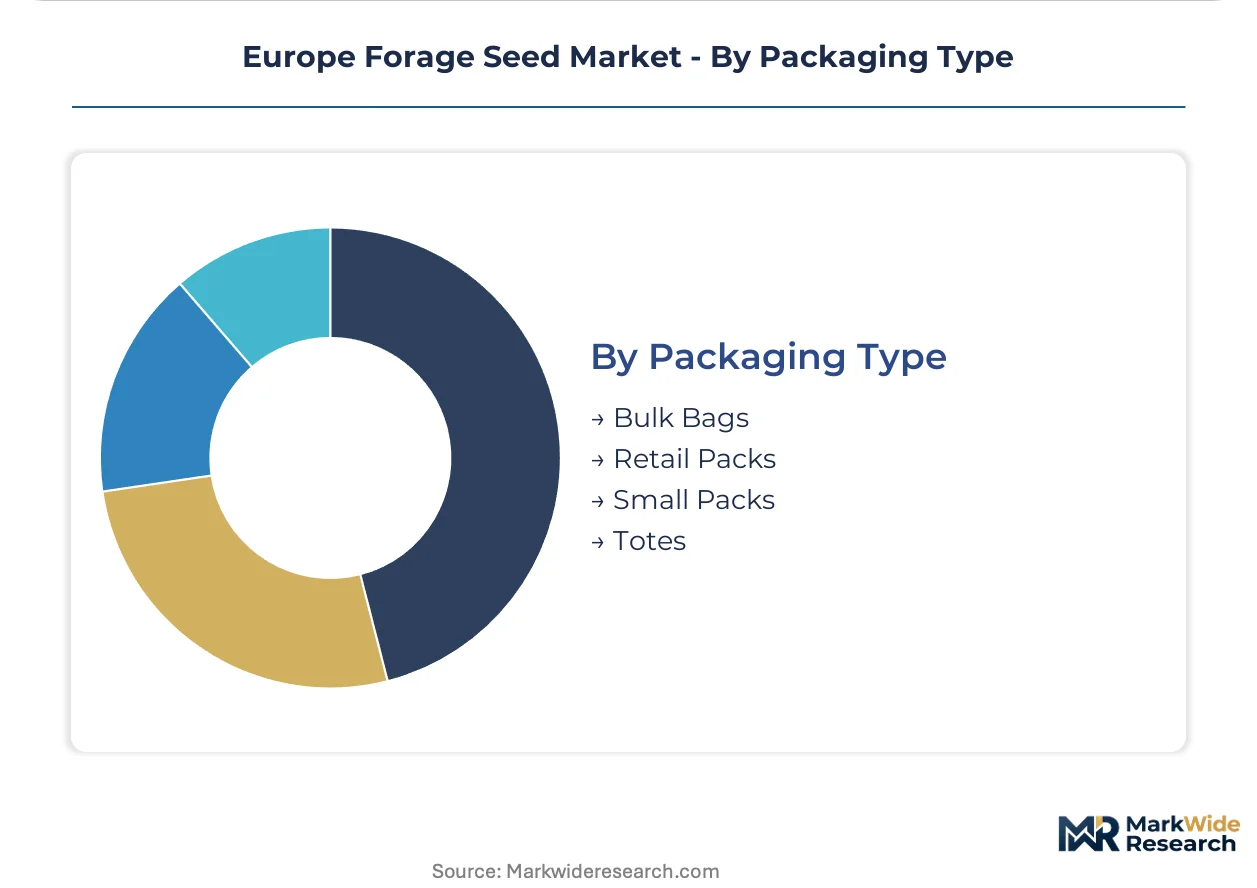
Packaging Type:
Supply concentration in bulk handling infrastructure versus distributed retail networks shapes logistics investment and inventory carrying costs across the value chain.
- Bulk Bags:500-1000kg units serve cooperative procurement and large livestock operations with established seed handling equipment, capturing volume concentration in northwest European dairy systems.
- Retail Packs:20-25kg bags dominate merchant channel sales to crop farmers and smaller livestock producers requiring flexible purchase timing.
- Small Packs:1-5kg units target hobby farmers and research trial plots with premium pricing per kilogram.
- Totes:Intermediate bulk containers offer reduced handling costs for medium-scale operations transitioning from bagged to bulk systems.
By shipment volume, Bulk Bags leads. By format innovation, Totes is gaining share fastest through logistics efficiency improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy cooperative procurement committees in northwest Europe concentrate certified seed demand through multi-year varietal performance contracts, while eastern European regions lack equivalent distribution infrastructure for premium germplasm.
France
Normandy and Brittany dairy cooperatives specify certified tetraploid ryegrass with water-soluble carbohydrate thresholds above 18% in three-year supply agreements. The EU Green Deal's Farm to Fork nitrogen-efficiency standards tighten varietal selection windows for legume-grass mixtures. Loire Valley intensive operations anchor demand for high-digestibility germplasm with documented rhizobium inoculation protocols.
Germany
Lower Saxony's expanding dairy sector prioritizes Nordic-bred perennial ryegrass for milk yield consistency across large-scale operations. REACH Annex XVII restrictions on neonicotinoid seed coatings force coating houses to reformulate with biological alternatives. Bavarian livestock producers increasingly specify festulolium crosses extending the grazing season in Atlantic-influenced climates.
Ireland
Dairygold and Lakeland Dairies consolidate vendor lists from 12-15 suppliers to 4-6 strategic partners with full varietal portfolios and blockchain traceability. CAP Pillar II eco-scheme payments reward multi-year legume-grass mixtures reducing synthetic nitrogen dependency. Munster-based cooperatives displace independent merchants lacking breeding program backing through documented performance guarantees.
Poland
Masovia and Podlasie dairy regions remain underpenetrated for certified tetraploid varieties due to insufficient cooperative distribution infrastructure. Online retail channels serve small-scale producers lacking access to agricultural cooperative procurement systems. Warsaw-based distributors increasingly stock dual-certified conventional and biological-coated inventory to hedge regulatory uncertainty from ECHA substance evaluation timelines.
Denmark
Nordic breeding stations in southern Sweden and Denmark concentrate high-digestibility germplasm development for northwest European dairy systems. EFSA evaluates novel trait submissions for forage crops entering commercial multiplication under streamlined molecular characterization protocols. DLF leverages its regional breeding infrastructure to anchor tetraploid ryegrass supply for export markets.
Europe Forage Seed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market consolidating around breeding-backed suppliers with full varietal portfolios. The vendor base compresses as dairy cooperative procurement committees reduce approved supplier lists and demand blockchain traceability documentation. Three archetypes dominate: integrated breeding houses with proprietary germplasm pipelines, regional distributors with cooperative channel relationships, and specialist merchants with localized agronomic expertise. M&A activity concentrates breeding assets under fewer corporate umbrellas, while capacity expansion focuses on high-throughput seed processing and optical sorting infrastructure.
Within the integrated breeding tier, Bayer AG and KWS SAAT SE & Co. KGaA exemplify the scale-driven archetype with proprietary hybrid development pipelines, while DLF represents the regionally anchored specialist with concentrated Nordic infrastructure. Euralis Semences occupies a position bridging cooperative channel control and varietal diversification. These three entities illustrate how breeding program depth and distribution channel ownership determine competitive positioning.
| Leading Market Players |
|---|
| Bayer AG |
| Euralis Semences |
| DLF |
| KWS SAAT SE & Co. KGaA |
| InVivo |
| Royal Barenbrug Group |
| RAGT Group |
| Advanta Seeds - UPL |
| Groupe Limagrain |
| Others |
Supply & Pricing Matrix
Southern Sweden's Nordic breeding stations anchor high-digestibility germplasm output, concentrating varietal development capacity that translates into pricing power for tetraploid ryegrass across northwest European dairy systems. Their captive control over elite germplasm pipelines lets breeding houses command performance-based premiums in cooperative procurement contracts.
Pricing Analysis
Three-year cost-plus contracts with phosphate indexation dominate large-scale cooperative procurement, linking seed pricing to Moroccan rock processing volatility. Price differentiation separates certified tetraploid varieties with EFSA documentation from uncertified merchant inventory, while after-sales agronomic support bundles capture additional margin. Pricing pressure stems from South American soybean meal substitution eroding domestic legume seed premiums. Small-scale Polish producers exhibit highest price sensitivity, whereas Loire Valley dairy operations prioritize WSC thresholds over unit cost.
Supply Chain Analysis
Export-control scrutiny under REACH Annex XVII restricts neonicotinoid-coated seed flows into northwest European markets, forcing inventory reformulation. Supply concentrates in Denmark, France, and Germany for elite germplasm multiplication, while Morocco anchors phosphate coating chemistry. Raw material dependencies include phosphate rock processing, biological coating actives, and rhizobium inoculant cultures. Single-source vulnerability runs through concentrated Nordic breeding infrastructure. Distribution runs through agricultural cooperatives consolidating vendor lists and displacing independent merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where after-sales agronomic advisory and varietal performance guarantees expand faster than base seed commodity margins. Recurring revenue from three-year field support contracts now exceeds one-time product premiums in cooperative negotiations.
For Market Incumbents: Insulate germplasm pipelines through backward integration into Nordic breeding station capacity and proprietary DUS testing infrastructure. EFSA regulatory submission acceleration represents the critical lever against gene-edited variety competition. Capacity expansion in Poland's Masovia region addresses cooperative channel consolidation while defending against online retail disintermediation. For New Entrants and Emerging Players: Poland's underpenetrated dairy regions in Podlasie represent the most accessible white-space entry point, lacking certified tetraploid distribution infrastructure. Herb-grass-legume mixtures for monogastric protocols offer margin expansion beyond commodity dairygrass portfolios. Digital channels serving small-scale producers bypass cooperative gatekeeper control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors breeding houses with documented phenotypic databases and EFSA pre-submission relationships. Long-term viability across the analysis window rests on genomic selection algorithm transparency compliance under the EU AI Act. Acquisition targets should demonstrate optical sorting infrastructure compatible with blockchain traceability mandates. The signal to watch is ECHA substance evaluation timeline compression for biological coating actives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Breeding Infrastructure | Captive germplasm pipelines insulate against Nordic station concentration risk and accelerate DUS timelines. |
| Biological Coating Reformulation | REACH Annex XVII compliance hedges regulatory uncertainty while opening CAP eco-scheme payment eligibility. |
| Blockchain Traceability Deployment | Cooperative procurement committees now mandate documented certification for vendor list retention. |
| Polish Distribution Channel Buildout | Masovia and Podlasie dairy expansion lacks certified tetraploid access through cooperative infrastructure. |
| Herb-Inclusion Mixture Development | Chicory and plantain protocols for monogastric systems capture premium pricing beyond standard ryegrass. |
Research Methodology
Cross-validation between primary interviews with breeding program directors and secondary analysis of EFSA novel trait submissions anchors the qualitative findings. Conversations with cooperative procurement managers, seed coating chemists, and dairy farm agronomists informed varietal selection dynamics. Bottom-up triangulation against CAP Pillar II payment disbursement records and top-down reconciliation with Nordic breeding station output data validated volume estimates. Trade flow analysis from customs declarations and REACH registration databases supplemented supply chain mapping.
Calibration against historical tetraploid ryegrass adoption curves and ECHA substance evaluation completion patterns refined projection parameters. Segmentation modeling incorporated product type, end-user scale tier, distribution channel concentration, and regional regulatory cluster across the analysis window. CAGRs derived from logistic diffusion curves for gene-edited variety penetration and linear extrapolation for conventional breeding program expansion. Forecast inputs included EFSA submission pipeline visibility and cooperative vendor consolidation velocity.
Practitioners should monitor ECHA biological active substance evaluation timelines and EU AI Act genomic algorithm classification proceedings for early signals. Forecasts reflect assumptions regarding CAP eco-scheme payment continuity and REACH coating chemistry grandfathering provisions. Material shifts in EFSA streamlined molecular characterization protocol adoption or Nordic breeding station climate vulnerability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Forage Seeds Market
Seeds
Thailand Vegetable Seed Market
Seeds
Uganda Seeds Market
Seeds
Americas Seeds Market
Seeds
Global Onion Seed Market
Seeds
Quinoa Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Morocco Seed Market
Seeds
Safflower Seeds Market
Seeds
North America Cannabis Seeds Market
Seeds
North America Alfalfa Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Pumpkin Seeds Market