
 South Africa Forage Seed Market | 2026-2036
South Africa Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Forage Seed Market Analytics
Improved perennial ryegrass cultivars is repositioning product economics across the South Africa forage seed sector by displacing lower-yielding open-pollinated varieties in commercial dairy systems. Allied Seed leverages extensive breeder networks to sustain germplasm access across temperate and subtropical zones. DLF International Seeds anchors its regional footprint through proprietary tetraploid ryegrass lines optimized for summer rainfall conditions. Barenbrug Holding BV differentiates via endophyte-enhanced fescue technologies that reduce livestock toxicity risks in highland grazing areas.
Forage seed comprises botanically distinct species cultivated specifically for animal feed, soil stabilization, or ecological restoration purposes, with certified seed meeting minimum germination thresholds and varietal purity standards established under OECD seed schemes. These seeds function as the biological foundation of pasture-based livestock systems, converting solar energy into digestible biomass through photosynthetic pathways optimized for grazing tolerance and regrowth velocity. Legumes capture expanding margin pools where nitrogen-fixation traits reduce synthetic fertilizer dependency for dairy and beef producers. Grasses dominate volume throughput across wholesale channels serving large-scale commercial ranching operations. Seed treatment categories show structural divergence as coated and inoculated variants command premium positioning against untreated commodity seed in precision farming segments.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces cultivar registration through the Plant Improvement Act, while the National Regulator for Compulsory Specifications monitors seed labeling and quality disclosure obligations. The country's national agricultural regulator coordinates with OECD seed certification protocols to facilitate export market access for certified South African breeders. Stakeholders must monitor evolving drought-tolerance breeding priorities and water-use licensing reforms that will reshape cultivar selection criteria across rainfall-variable production zones.
Market Dynamics
Perennial ryegrass cultivar displacement of open-pollinated varieties is compressing seed economics across South Africa's dairy belt, as commercial operations prioritize germplasm with verified summer rainfall performance and grazing tolerance metrics.
Growth Catalysts
- Irrigation Infrastructure Expansion:KwaZulu-Natal's coastal dairy belt is extending year-round forage production capacity through upgraded water distribution networks serving commercial pasture renovation programs.
- Plant Improvement Act Enforcement:South Africa's cultivar registration mandates under this legislation are standardizing quality disclosure and accelerating certified seed adoption against uncertified commodity alternatives.
- Nitrogen-Fixation Trait Demand:Legume seed categories are capturing expanded margin pools as dairy and beef producers reduce synthetic fertilizer dependency through biological nitrogen capture systems.
Market Restraints
- Water-Use Licensing Reforms:South Africa's evolving water allocation frameworks are creating cultivar selection uncertainty across rainfall-variable production zones in the Eastern Cape and Free State.
- Endophyte Technology Cost Premium:Enhanced fescue varieties with livestock toxicity reduction traits command input cost multiples that constrain adoption among smallholder grazing operations.
- Germplasm Access Concentration:International breeder network dependencies limit domestic cultivar development velocity for subtropical adaptation programs.
Strategic Opportunities
- Highland Grazing Rehabilitation:Endophyte-enhanced tall fescue deployment in Mpumalanga and Drakensberg regions addresses livestock toxicity risks while opening premium positioning channels.
- OECD Seed Scheme Alignment:South Africa's national agricultural regulator coordination with international certification protocols is unlocking export market access for domestic breeding operations.
- Seed Treatment Premium Segmentation:Coated and inoculated variant categories are creating pricing stratification opportunities against untreated commodity seed in precision farming segments.
Industry Challenges
- Drought-Tolerance Breeding Pipeline Delays:Extended cultivar development cycles for water-stress adaptation are compressing competitive response windows against climate variability.
- Certification Compliance Timeline Compression:Plant Improvement Act varietal purity documentation requirements are extending seed-to-market intervals for new cultivar introductions.
- Legacy Open-Pollinated Inventory Clearance:Commercial dairy system upgrading is straining distribution channel capacity for lower-tier seed category phase-out logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Forage Seed Market |
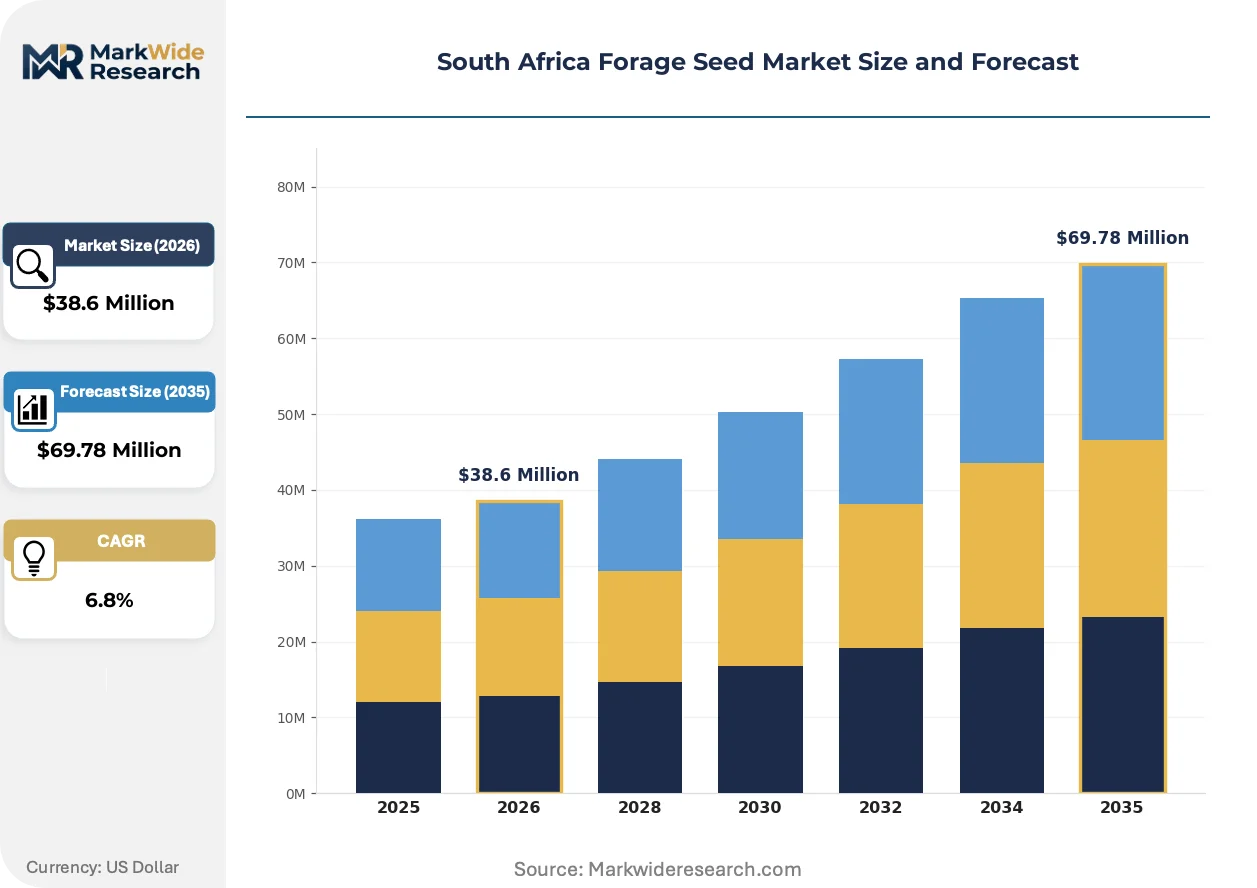
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $69.78 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Legumes, Grasses, Clovers, Brassicas End Use: Dairy Farming, Beef Cattle, Wildlife Habitat, Erosion Control Distribution Channel: Direct Sales, Retail, Online, Wholesale Seed Treatment: Coated, Inoculated, Untreated, Organic |
| Companies Covered | Allied Seed, Dynamic Seeds, DLF International Seeds, Dairyland Seeds, Foster's Seed and Feed, Agricol, Golden Acre Seeds, Barenbrug Holding BV, BrettYoung Seeds Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Forage Seed Market Evolving Landscape
Tetraploid ryegrass genetics and endophyte enhancement technologies are restructuring cultivar value hierarchies, while regulatory alignment with OECD protocols and shifting procurement patterns reshape competitive access routes.
Proprietary tetraploid ryegrass lines optimized for summer rainfall conditions are absorbing margin compression pressure from diploid alternatives through demonstrable dry matter yield advantages. Large-scale commercial ranching operations in the Eastern Cape are accelerating adoption timelines based on verified grazing tolerance data. This genetic platform is absorbing market share from commodity ryegrass categories by delivering measurable feed conversion efficiency improvements in intensive dairy systems.
South Africa's Department of Agriculture, Land Reform and Rural Development is intensifying Plant Improvement Act enforcement scope around cultivar registration documentation and seed labeling accuracy. The National Regulator for Compulsory Specifications is expanding quality disclosure audit frequency across wholesale distribution channels. Certified seed categories are absorbing compliance cost premiums that untreated commodity alternatives cannot sustain, compressing informal market participation in KwaZulu-Natal and Free State supply corridors.
Buyer concentration among commercial dairy cooperatives is consolidating procurement leverage and compressing supplier negotiation cycles. Traditional agricultural merchant channels serving smallholder operations are losing volume share to direct breeder relationships and cooperative bulk purchasing structures. This channel restructuring is most visible in the coastal dairy belt where irrigation infrastructure supports predictable annual forage seed contracting volumes.
South Africa Forage Seed Market Segmentation
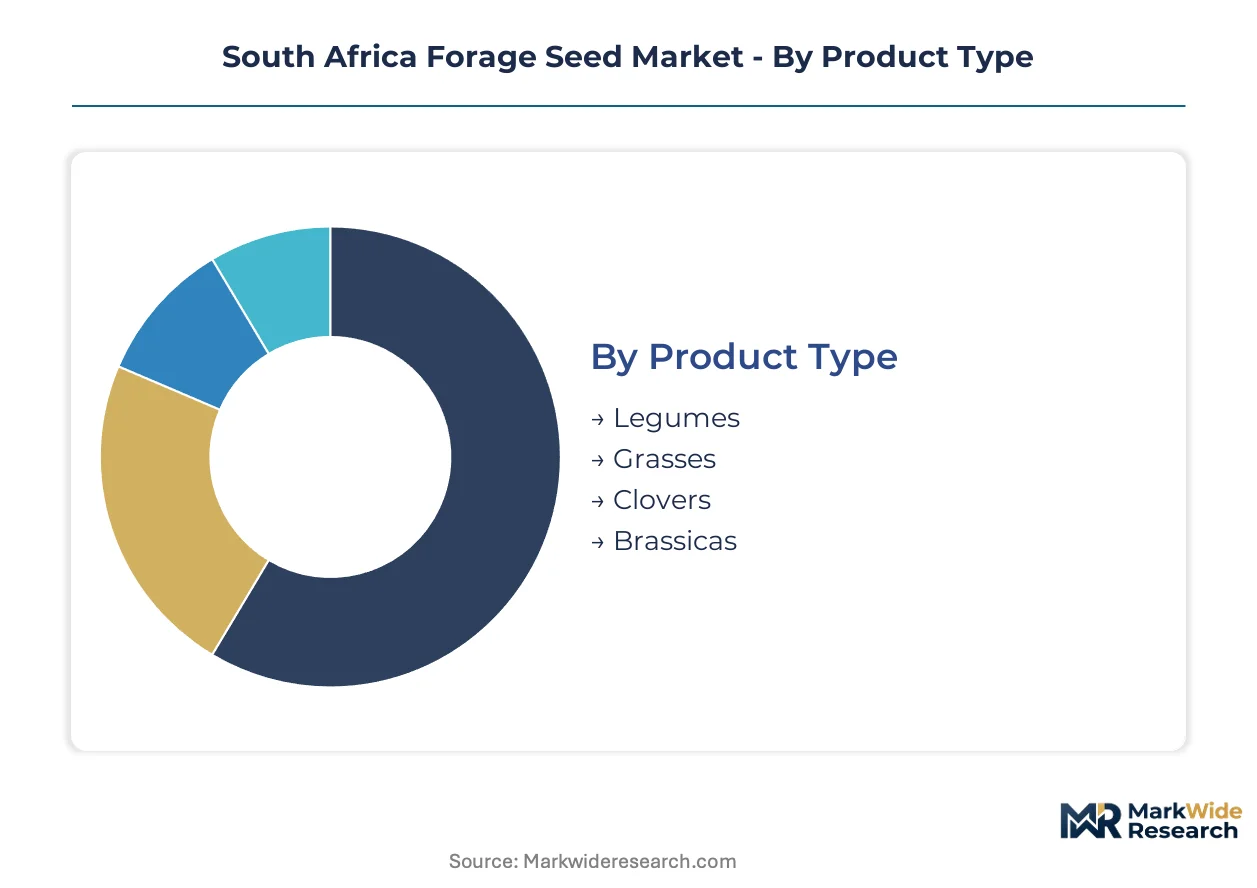
Forage seed procurement decisions in South Africa track closely to livestock system intensity and water security profiles. Buyers segment their cultivar choices based on nitrogen-fixation requirements, grazing tolerance specifications, and certified seed compliance obligations under the Plant Improvement Act.
Product Type:
Dairy and beef producers prioritize germplasm performance under summer rainfall variability and irrigation dependency.
- Legumes:Nitrogen-fixing species including lucerne and white clover reduce synthetic fertilizer input costs for KwaZulu-Natal dairy operations. Demand concentrates in the coastal dairy belt where irrigation infrastructure supports year-round legume pasture persistence.
- Grasses:Perennial and annual ryegrass cultivars dominate commercial ranching procurement volumes across the Eastern Cape. Tetraploid genetics with verified summer rainfall performance are displacing open-pollinated diploid varieties in intensive grazing systems.
- Clovers:Subterranean and red clover species provide complementary forage quality in mixed pasture swards. Adoption tracks dairy cooperative procurement specifications for protein content benchmarks.
- Brassicas:Forage rape and kale cultivars deliver winter feed gaps in highland grazing areas. Mpumalanga and Drakensberg producers deploy these for seasonal nutritional supplementation.
Grasses lead on scale; legumes lead on momentum.
End Use:
Application intensity determines cultivar selection criteria across rainfall-variable production zones.
- Dairy Farming:High-input systems in KwaZulu-Natal demand certified perennial ryegrass with endophyte enhancement for grazing tolerance. Milk production targets drive precision seeding rates and pasture renovation cycles.
- Beef Cattle:Extensive ranching operations in the Free State prioritize drought-tolerant grass cultivars with lower input requirements. Commercial feedlot integration is expanding demand for annual forage varieties.
- Wildlife Habitat:Game reserve restoration programs in Limpopo and North West provinces source native grass and legume mixes. Ecological specifications override agronomic yield metrics in procurement decisions.
- Erosion Control:Land rehabilitation projects deploy quick-establishing annual grasses and deep-rooted perennial species. Soil stabilization contracts channel volume through wholesale distribution networks.
Dairy farming commands premium positioning; wildlife habitat is expanding most quickly.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements for cultivar matching.
- Direct Sales:Breeder-to-producer relationships serve large commercial dairy cooperatives with volume contracting. Technical agronomy support accompanies proprietary tetraploid ryegrass and endophyte-enhanced fescue transactions.
- Retail:Agricultural merchant networks supply smallholder operations with packaged seed and basic cultivation guidance. Storefront presence concentrates in Free State and Eastern Cape grain belt towns.
- Online:Digital procurement platforms are emerging for certified seed documentation and traceability compliance. Younger commercial producers in irrigation-dependent zones trial direct-to-farm delivery models.
- Wholesale:Bulk distribution corridors serve ranching operations and cooperative buying structures across provincial supply chains. Volume consolidation is compressing intermediary margins in KwaZulu-Natal.
Wholesale dominates throughput; direct sales capture steepest expansion trajectory.
Seed Treatment:
Treatment tier selection separates precision farming adopters from commodity-oriented producers.
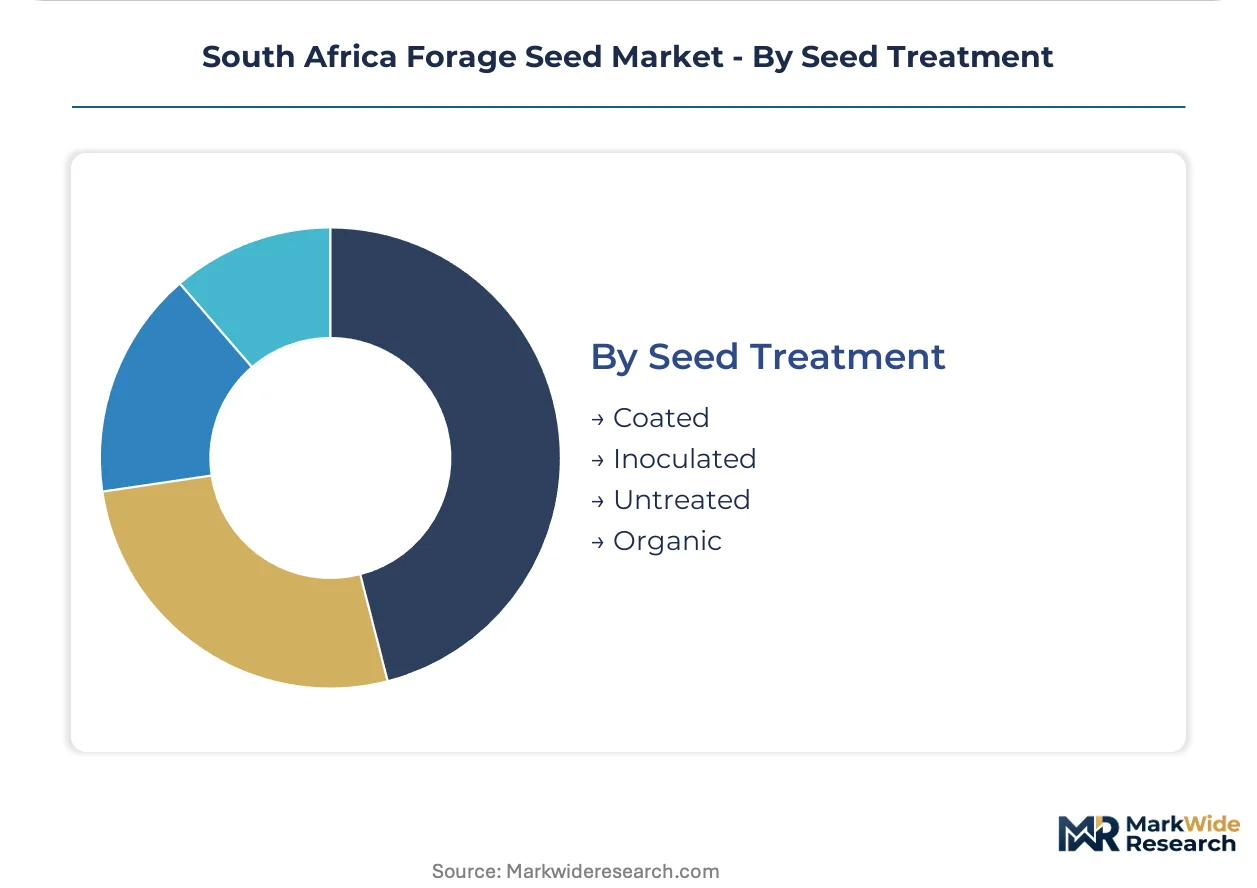
- Coated:Polymer and nutrient coatings improve germination uniformity and early seedling vigor. Commercial dairy systems in irrigation districts absorb treatment cost premiums for establishment reliability.
- Inoculated:Rhizobium inoculation is mandatory for legume seed destined for nitrogen-deficient soils. KwaZulu-Natal coastal dairy belt producers specify inoculation for lucerne and clover pasture renovations.
- Untreated:Commodity seed categories serve price-sensitive smallholder grazing operations. Plant Improvement Act enforcement is compressing untreated seed availability through certified channel requirements.
- Organic:Certified organic treatment protocols exclude synthetic chemical coatings and GMO-derived inoculants. Niche demand emerges from premium dairy supply chain contracts and game reserve restoration specifications.
Untreated seed retains volume leadership; coated variants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KwaZulu-Natal's coastal dairy belt anchors South Africa's forage seed demand through irrigation-dependent commercial pasture systems. Provincial water infrastructure investments sustain year-round production cycles that drive certified seed procurement volumes. The Department of Agriculture, Land Reform and Rural Development coordinates varietal registration across five distinct agro-ecological zones.
Eastern Cape
Commercial ranching operations in the Eastern Cape are accelerating pasture renovation programs with drought-tolerant grass cultivars. The Plant Improvement Act mandates certified seed documentation for all commercial sales, compressing informal market participation. Dairy farming clusters around Makhanda and Gqeberha are displacing open-pollinated varieties with tetraploid ryegrass lines.
Free State
Extensive beef cattle operations in the Free State prioritize lower-input grass species suited to rainfall-variable conditions. Water-use licensing reforms under the National Water Act are creating cultivar selection uncertainty for summer rainfall zones. Wholesale distribution corridors through Bloemfontein serve cooperative buying structures with bulk annual forage varieties.
Mpumalanga
Highland grazing areas in Mpumalanga are deploying endophyte-enhanced fescue technologies to reduce livestock toxicity risks. The National Regulator for Compulsory Specifications monitors seed labeling compliance across wholesale channels serving the region. Commercial producers around Nelspruit are integrating brassica cultivars for winter feed gap management.
Western Cape
Mediterranean climate zones in the Western Cape support lucerne and clover persistence for export-oriented dairy supply chains. The country's national agricultural regulator enforces OECD seed scheme alignment for cultivar certification documentation. Stellenbosch and Paarl agricultural clusters are trialing coated seed treatments for establishment reliability in precision farming segments.
South Africa Forage Seed Market Competitive Landscape
Global majors compete with regional champions across germplasm access and distribution reach in South Africa's forage seed sector. International breeder networks anchor the premium tier through proprietary genetics, while domestic distributors capture volume throughput in wholesale corridors. Three archetypes dominate: multinational germplasm licensors, regional seed treatment specialists, and cooperative-aligned distributors. Competitive moves concentrate on direct-to-farm contracting expansion and certified seed compliance infrastructure.
Among international breeders with South African operations, DLF International Seeds and Barenbrug Holding BV exemplify the germplasm-licensing archetype through their proprietary cultivar pipelines. Allied Seed represents the regional distributor model with extensive breeder network relationships spanning temperate and subtropical adaptation zones. BrettYoung Seeds Limited occupies a position within the mid-tier certified seed segment, while Dynamic Seeds and Golden Acre Seeds anchor domestic distribution capacity across provincial supply corridors.
| Leading Market Players |
|---|
| Allied Seed |
| Dynamic Seeds |
| DLF International Seeds |
| Dairyland Seeds |
| Foster's Seed and Feed |
| Agricol |
| Golden Acre Seeds |
| Barenbrug Holding BV |
| BrettYoung Seeds Limited |
| Others |
Value Network & Pricing Analysis
Raw germplasm licensing fees from international breeder networks cascade through certified seed pricing tiers, with proprietary tetraploid ryegrass genetics commanding substantial premiums over open-pollinated alternatives in KwaZulu-Natal dairy procurement contracts.
Pricing Analysis
Input-cost pass-through from breeder royalty structures shapes three-tier pricing stratification across premium certified, standard registered, and economy untreated seed categories. Certification grade under the Plant Improvement Act and volume scale through cooperative bulk purchasing serve as primary price differentiation drivers. Pricing pressure intensifies as commercial dairy cooperates consolidate procurement leverage and compress supplier margins. Smallholder grazing operations in the Free State exhibit highest price sensitivity, while irrigation-dependent KwaZulu-Natal dairy systems absorb premium positioning for establishment reliability.
Supply Chain Analysis
Warehouse-distribution layers concentrate through Bloemfontein and Pietermaritzburg regional hubs serving provincial cooperative networks and agricultural merchant channels. Breeder operations in the Netherlands, Denmark, and New Zealand anchor upstream germplasm supply, drawing from proprietary cultivar development pipelines and OECD seed scheme certification protocols. Single-source vulnerability concentrates around international breeder network dependencies for subtropical adaptation traits. Distribution runs through wholesale bulk corridors for ranching operations, supplemented by direct-to-farm contracting for large commercial dairy systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in certified seed tiers where Plant Improvement Act enforcement phases out untreated commodity alternatives, compressing informal supply participation and redirecting volume through compliant premium channels.
For Market Incumbents: Deploy endophyte enhancement R&D pipelines to differentiate fescue offerings in Mpumalanga highland zones where livestock toxicity reduction commands measurable premium capture. Consolidate distribution control through cooperative partnership structures in KwaZulu-Natal irrigation corridors. Defensive positioning requires accelerated breeder network exclusivity negotiations before subtropical adaptation germplasm access tightens further.
For New Entrants and Emerging Players: Capture white-space in organic-certified seed treatment protocols serving premium dairy supply chain contracts and game reserve restoration specifications. Target Western Cape precision farming segments where coated seed adoption trials create technical service differentiation opportunities. Go-to-market execution should emphasize digital procurement platforms with certified documentation and traceability compliance infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where domestic distributors lack proprietary germplasm access and depend entirely on licensed breeder relationships for product differentiation. Long-term viability favors vertically integrated operations with captive cultivar development capability or exclusive subtropical adaptation programs. Monitor drought-tolerance breeding pipeline velocity as inflection signal for competitive positioning durability across rainfall-variable production zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Germplasm Licensing | Exclusive tetraploid ryegrass access secures premium positioning in KwaZulu-Natal dairy contracts. |
| Seed Treatment Infrastructure Investment | Coating and inoculation capacity expansion captures margin migration from untreated commodity tiers. |
| Direct-to-Farm Distribution Expansion | Bypassing agricultural merchant channels improves margin retention in commercial cooperative segments. |
| OECD Certification Alignment | Export market access protocols unlock regional expansion for domestic breeding operations. |
| Endophyte Enhancement R&D Partnership | Livestock toxicity reduction technologies differentiate fescue offerings in highland grazing rehabilitation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with seed company breeding directors, agricultural cooperative procurement managers, Department of Agriculture officials, and wholesale distribution channel operators. Secondary validation drew from OECD seed scheme documentation, Plant Improvement Act regulatory filings, customs trade records for germplasm imports, and provincial agricultural extension service reports. Bottom-up cultivar-level volume estimates and top-down sector expenditure analysis underwent iterative triangulation.
Segment-weighting approaches distributed value projections across product type, end-use application, distribution channel, and seed treatment tier dimensions throughout the forecast period. CAGRs derived from historical certified seed adoption trajectories, irrigation infrastructure investment pipelines, and breeder network expansion patterns. Water-use licensing reform timelines and drought-tolerance cultivar development cycles served as scenario sensitivity inputs.
Underlying measurement precision varies by segment; certified seed categories carry tighter precision than informal market estimates due to Plant Improvement Act documentation requirements. Forecast outputs reflect documented assumptions around regulatory enforcement intensity and climate adaptation breeding success rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Africa Peas Market
Seeds
Sesame Seeds Market
Seeds
Fruit Seed Waste Market
Seeds
Russia Seed Market
Seeds
Sri Lanka Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Garden Seeds Market
Seeds
North America Grain Seed Market
Seeds
Ghana Seed Extract Market
Seeds
Drought Tolerant Seeds Market
Seeds
North America Seeds Market
Seeds
Africa Sorghum Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Global Maize Seed Market
Seeds
Global Wheat Seed Market
Seeds
India Seed Market