
 Guar Market | 2026-2036
Guar Market Size, Share, and Industry Trends Forecast 2026-2036
Guar Market Analysis
Oilfield operators is rotating toward guar gum derivatives for high-temperature shale formations, displacing traditional food manufacturers as the dominant buyer archetype. Vikas WSP leverages backward integration from seed procurement to refined gum powder, capturing margin across the value chain. Cargill competes through its global distribution network, supplying food-grade guar to multinational processed food brands. Hindustan Gums & Chemicals anchors the pharmaceutical-grade segment with dedicated refining capacity for USP-compliant hydrocolloids.
Guar comprises a galactomannan polysaccharide derived from the endosperm of Cyamopsis tetragonoloba seeds, with mannose-to-galactose ratios of approximately 2:1 governing viscosity performance in aqueous solutions. Guar Gum dominates value capture due to its irreplaceable role as a thickening and stabilizing agent across hydraulic fracturing, food processing, and pharmaceutical formulations. Oil & Gas represents the fastest-growing application segment, driven by shale operators seeking biodegradable alternatives to synthetic polymers for well-completion fluids. Guar Meal, the protein-rich byproduct of gum extraction, sustains steady demand from animal feed compounders in South Asia and the Middle East.
The EPA regulates guar-based fracturing fluid additives under the Safe Drinking Water Act, while India's BIS mandates IS 14001 quality certification for export-grade gum powder. The EU REACH framework imposes registration requirements on guar derivatives imported for personal care and pharmaceutical applications, conditioning market access for Indian and Pakistani suppliers. Stakeholders must monitor evolving disclosure mandates for chemical constituents in oilfield applications and the divergence between food-grade and industrial-grade certification pathways.
Market Dynamics
Oilfield procurement volumes for hydraulic fracturing fluids now exceed food-sector offtake, reversing a decades-old demand hierarchy rooted in guar's culinary origins. This inversion concentrates purchasing power among shale operators in Texas, North Dakota, and Pennsylvania who specify high-viscosity grades for high-temperature formations.
Growth Catalysts
- Shale Formation Chemistry:Biodegradable guar gum derivatives replace synthetic polymers in well-completion fluids, satisfying operator ESG mandates while maintaining rheological performance under reservoir stress.
- REACH Registration Pathways:EU pharmaceutical and personal care importers now demand REACH-compliant guar hydrocolloids, creating certified supply lanes for Indian exporters who invest in dossier preparation.
- Rajasthan-Jodhpur Cluster Density:Over 80 percent of global gum powder originates from this processing belt, generating scale economies in seed crushing, solvent extraction, and mesh-size classification.
Market Restraints
- Monsoon-Dependent Seed Supply:Rajasthan rainfall variability governs annual seed availability, compressing processor margins during deficit years when raw material costs spike.
- BIS Certification Bottlenecks:India's Bureau of Indian Standards mandates IS 14001 quality certification for export-grade powder, creating documentation delays for smaller processors lacking in-house testing laboratories.
- Xanthan Gum Substitution:Synthetic biopolymer alternatives compete in lower-temperature fracturing applications where thermal stability requirements relax.
Strategic Opportunities
- Pharmaceutical-Grade Refining:USP-compliant hydrocolloid production for oral solid dosage forms remains underdeveloped outside Hindustan Gums & Chemicals, opening capacity expansion potential.
- Guar Meal Protein Concentrates:Animal feed compounders in the Middle East seek higher-protein byproduct fractions, rewarding processors who invest in meal fractionation.
- EPA Chemical Disclosure Alignment:Safe Drinking Water Act transparency mandates favor suppliers with documented additive chains, privileging integrated processors over traders.
Industry Challenges
- Food-Grade versus Industrial-Grade Certification Divergence:Dual-track quality systems strain quality assurance teams as FDA food additive standards and oilfield performance specifications diverge in testing protocols.
- High-Temperature Derivative R&D Talent Scarcity:Formulation chemists capable of engineering galactomannan modifications for 150°C-plus reservoir conditions command premium compensation, constraining mid-cap processor innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guar Market |
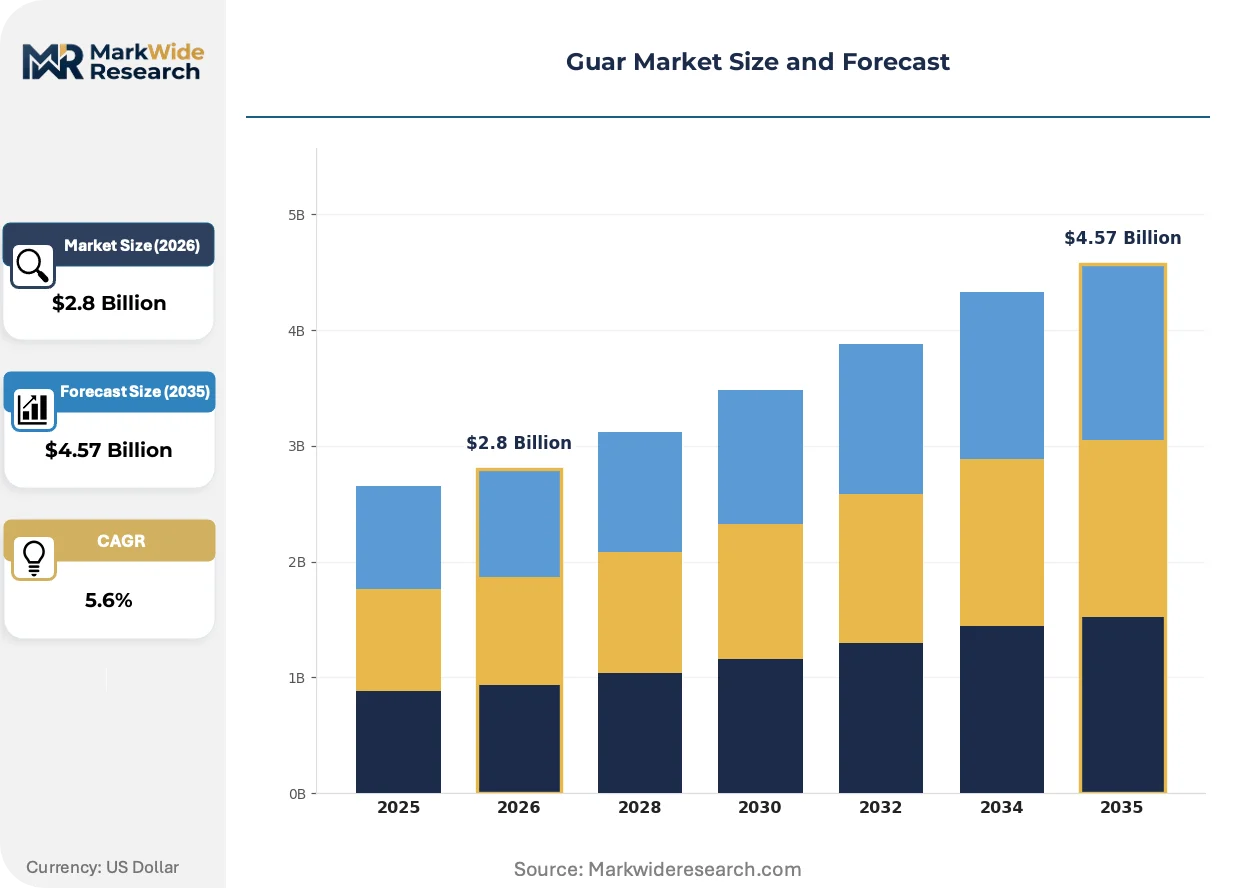
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guar Gum, Guar Meal, Guar Split, Guar Seed Application: Food Industry, Personal Care, Pharmaceuticals, Oil & Gas End User: Food Manufacturers, Cosmetic Companies, Medical Services, Oilfield Operators Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | India Glycols Ltd., Supreme Gums, Cargill, Jai Bharat Gum, Ashland Global Specialty Chemicals, Vikas WSP, Hindustan Gums & Chemicals, Lamberti, Lucid Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guar Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are restructuring competitive advantage toward integrated seed-to-powder operators with certified laboratory infrastructure. Three developments merit particular attention.
Carboxymethyl guar (CMG) derivatives are displacing unmodified gum powder in Permian Basin high-temperature wells, where thermal degradation above 120°C compromises viscosity retention. Apache Corporation and Pioneer Natural Resources have specified CMG in 2024 drilling programs, forcing processors to install etherification reactors or lose share in premium fracturing segments. The technology is displacing commodity-grade powder from the most profitable application tier.
EPA's expanded chemical disclosure rules under the Safe Drinking Water Act now require fracturing fluid constituent reporting at the wellpad level, not merely state aggregate filings. This regulatory shift elevates documentation burdens for traders who source from multiple small processors, while rewarding single-origin suppliers with batch-level traceability systems. Oilfield service companies operating in Texas and New Mexico have responded by contracting directly with BIS-certified Rajasthan processors, shortening supply chains.
Shale operators now consolidate annual guar procurement through master service agreements with integrated oilfield services firms, displacing spot-market purchasing that dominated the 2010-2020 period. Halliburton and Schlumberger negotiate multi-year viscosity-grade specifications directly with Jodhpur processors, locking in volume commitments that smaller food-sector buyers cannot match. This concentration is most pronounced in the Permian Basin, where operator consolidation has reduced the number of active drilling decision-makers by 40 percent since 2019.
Guar Market Segmentation
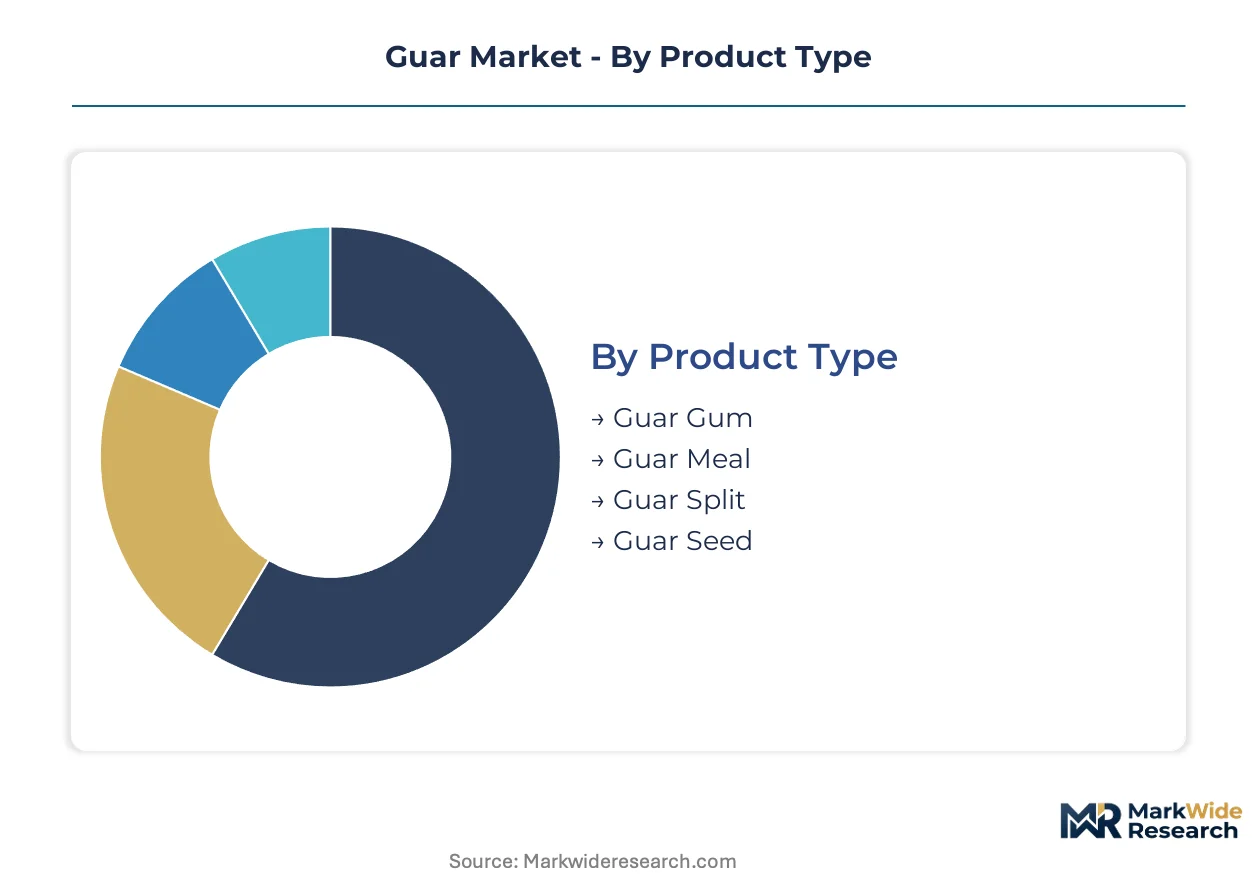
Guar market segmentation reveals how value migrates from commodity seed trading toward refined derivatives serving regulated industries. Each dimension exposes distinct margin structures, certification burdens, and customer concentration patterns that reshape processor strategy.
Product Type:
Margin pools concentrate in downstream refining stages where purity specifications and application-specific modifications command price premiums over raw agricultural commodities.
- Guar Gum:Refined galactomannan polysaccharide extracted from seed endosperm, with viscosity grades ranging from 3,000 to 8,000 cps governing pricing tiers. Oilfield operators in Texas and North Dakota now absorb larger procurement volumes than food manufacturers, reversing historical demand hierarchies as shale fracturing specifications tighten.
- Guar Meal:Protein-rich byproduct of gum extraction containing 40-50 percent crude protein, sold to animal feed compounders. Middle Eastern feed manufacturers seek higher-protein concentrates, rewarding Rajasthan processors who invest in meal fractionation equipment.
- Guar Split:Dehulled and split endosperm segments serving as intermediate feedstock for gum powder production. Jodhpur cluster processors source splits from local crushing units to maintain backward integration control.
- Guar Seed:Raw agricultural commodity harvested across Rajasthan, Gujarat, and Haryana, with annual availability governed by monsoon rainfall variability. Spot trading dominates seed procurement, compressing margins for crushers lacking storage infrastructure.
The dominant share belongs to Guar Gum, while Guar Meal is closing the gap fastest.
Application:
Application segmentation tracks how regulatory intensity and performance requirements fragment demand into distinct procurement channels with diverging certification standards.
- Food Industry:Thickening and stabilizing agent for processed dairy, baked goods, and convenience foods. FDA food additive standards and FSSAI compliance requirements condition supplier qualification for multinational brands.
- Oil & Gas:Rheology modifier for hydraulic fracturing fluids in high-temperature shale formations. Carboxymethyl guar derivatives are displacing unmodified powder in Permian Basin wells above 120°C reservoir conditions.
- Pharmaceuticals:USP-compliant hydrocolloid for oral solid dosage forms and controlled-release matrices. Hindustan Gums & Chemicals anchors this segment with dedicated refining capacity.
- Personal Care:Conditioning and thickening agent for shampoos and lotions. EU REACH registration requirements impose dossier preparation costs on Indian exporters serving European cosmetic formulators.
Oil & Gas captures the steepest expansion trajectory, though Food Industry retains the largest installed base of qualified suppliers.
End User:
End user concentration patterns reveal how customer scale and technical sophistication reshape contract structures and relationship economics.
- Oilfield Operators:Shale producers and integrated oilfield services firms negotiating multi-year master service agreements with viscosity-grade specifications. Halliburton and Schlumberger now contract directly with BIS-certified Rajasthan processors, displacing spot-market purchasing.
- Food Manufacturers:Multinational processed food brands sourcing through Cargill's global distribution network. FSSAI and FDA dual compliance requirements strain smaller processors lacking in-house testing laboratories.
- Cosmetic Companies:European and North American personal care brands demanding REACH-compliant hydrocolloids with documented additive chains. ECHA registration pathways favor integrated processors over traders.
- Medical Services:Pharmaceutical manufacturers requiring USP-grade material for drug formulation. CDSCO and FDA inspections govern supplier qualification for this highest-margin segment.
Oilfield Operators command the dominant procurement volume, while Medical Services delivers the highest margin per kilogram.
Distribution Channel:
Channel structure reflects the tension between traceability requirements favoring direct relationships and cost efficiency driving consolidated purchasing.
- Direct Sales:Processor-to-end-user contracts with batch-level documentation for EPA Safe Drinking Water Act compliance. Oilfield service companies in Texas and New Mexico favor this channel for disclosure mandate alignment.
- Distributors:Regional stocking intermediaries serving food and personal care manufacturers with smaller volume requirements. Inventory carrying costs compress distributor margins during seed price volatility.
- Wholesalers:Commodity aggregators handling guar seed and split volumes for domestic crushers. Rajasthan mandi networks facilitate price discovery but offer limited quality assurance.
- Online Retail:E-commerce platforms for small-lot food-grade and cosmetic-grade purchases. This channel remains peripheral due to certification documentation requirements.
Direct Sales holds the dominant position, while Distributors are gaining share among mid-tier food manufacturers seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports refined guar gum powder to shale operators in the United States and food manufacturers across Europe, with processing concentration in the Rajasthan-Jodhpur belt governing global supply availability.
United States
Permian Basin shale operators in Texas absorb the largest import volumes of high-viscosity guar derivatives for hydraulic fracturing fluids. EPA Safe Drinking Water Act disclosure mandates now require wellpad-level constituent reporting, conditioning procurement on batch-level traceability. Houston-based oilfield service companies contract directly with BIS-certified Rajasthan processors to satisfy transparency requirements.
India
Rajasthan accounts for over 80 percent of global gum powder production, with Jodhpur cluster processors controlling seed crushing, solvent extraction, and mesh-size classification infrastructure. BIS mandates IS 14001 quality certification for export-grade powder, creating documentation bottlenecks for smaller crushers lacking in-house testing laboratories. Monsoon rainfall variability across Rajasthan, Gujarat, and Haryana governs annual seed availability and processor margins.
Germany
Personal care formulators in Hamburg and Düsseldorf import REACH-registered guar hydrocolloids for shampoo and lotion applications. ECHA registration pathways impose dossier preparation costs on Indian exporters, favoring integrated processors with documented additive chains over commodity traders. Frankfurt-based cosmetic brands now specify ECHA-compliant supply lanes in procurement contracts.
China
Shandong Province textile mills and food processors source guar derivatives for sizing applications and processed food stabilization. GB standards for food-grade hydrocolloids condition import acceptance, with Shanghai port inspectors testing viscosity grades against declared specifications. Qingdao-based distributors serve as intermediaries for Rajasthan-origin powder entering domestic manufacturing channels.
Saudi Arabia
Animal feed compounders in Riyadh and Dammam import guar meal protein concentrates from Indian processors for poultry and ruminant nutrition formulations. SFDA feed additive regulations govern import acceptance, with higher-protein fractions commanding price premiums over standard meal grades. Jeddah port logistics infrastructure supports bulk discharge of containerized meal shipments from Mumbai and Mundra.
Guar Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and backward integration depth, producing a tiered structure where scale economies in laboratory accreditation separate integrated processors from commodity traders. Three archetypes dominate: seed-to-powder operators with captive crushing capacity, specialty chemical houses with global distribution networks, and regional crushers dependent on spot-market seed procurement. Competitive moves center on BIS certification acquisition for EPA disclosure alignment and etherification reactor installation for high-temperature derivative production.
Among India-based integrated processors, Vikas WSP and Hindustan Gums & Chemicals occupy positions exemplifying the seed-to-powder archetype with in-house refining infrastructure. Cargill represents the multinational distribution vector, leveraging global logistics networks to supply food-grade material. Ashland Global Specialty Chemicals anchors the specialty chemical tier with derivative modification capabilities. Supreme Gums and Jai Bharat Gum sit within the regional processor segment, competing on Rajasthan cluster proximity and split-sourcing relationships.
| Leading Market Players |
|---|
| India Glycols Ltd. |
| Supreme Gums |
| Cargill |
| Jai Bharat Gum |
| Ashland Global Specialty Chemicals |
| Vikas WSP |
| Hindustan Gums & Chemicals |
| Lamberti |
| Lucid Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Jodhpur cluster processors governs both supply concentration and price floors, as idle crushing lines during monsoon-deficit years compress margins while full-capacity operation enables premium-grade extraction. Oilfield operators in Texas and North Dakota now absorb larger procurement volumes than food manufacturers, shifting pricing power toward shale services firms with multi-year master service agreements.
Pricing Analysis
Commodity-grade guar gum powder versus carboxymethyl guar derivatives versus next-generation hydroxypropyl modifications stratifies pricing across thermal-performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects viscosity-grade certification, with EPA Safe Drinking Water Act disclosure alignment commanding premiums over uncertified commodity powder. Cost compression in standard-grade segments is intensifying because xanthan gum substitution in lower-temperature fracturing applications erodes volume commitments. Food manufacturers exhibit highest price sensitivity due to FSSAI-FDA dual compliance burdens, while oilfield operators demonstrate lowest sensitivity given ESG-mandated biodegradable polymer requirements.
Supply Chain Analysis
India produces over 80 percent of global refined guar gum powder, with Pakistan and limited US domestic crushing anchoring residual supply. Rajasthan seed availability, Gujarat solvent extraction capacity, and Jodhpur mesh-classification infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in the Rajasthan-Jodhpur belt where monsoon rainfall variability governs annual seed supply. Distribution runs through direct processor-to-oilfield-service contracts with batch-level traceability documentation, displacing spot-market purchasing and regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shale formation chemistry disruption is accelerating market restructuring as biodegradable guar derivatives displace synthetic polymers in high-temperature well completion, creating procurement concentration among integrated oilfield services firms.
For Market Incumbents: Compound backward integration control over Rajasthan seed procurement to defend against margin compression during monsoon-deficit years. Invest in BIS IS 14001 certification infrastructure to satisfy EPA Safe Drinking Water Act disclosure mandates that privilege batch-level traceability over trader-sourced volumes. Prioritize carboxymethyl guar etherification reactor installation to retain share in Permian Basin high-temperature specifications above 120°C reservoir conditions. For New Entrants and Emerging Players: Pharmaceutical-grade USP-compliant hydrocolloid production represents an under-served service layer where Hindustan Gums & Chemicals maintains singular dedicated refining capacity. Target animal feed compounders in Saudi Arabia and the Middle East seeking higher-protein guar meal concentrates above standard 40-50 percent crude protein fractions. Pursue REACH dossier preparation partnerships with EU cosmetic formulators as a regulatory-compliant go-to-market pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated seed-to-powder operators with captive crushing infrastructure and in-house testing laboratories over commodity traders lacking certification assets. Long-term viability over the 5-10 year projection horizon rests on EPA disclosure alignment and high-temperature derivative R&D capability. Monitor Halliburton and Schlumberger procurement contract announcements as inflection indicators for volume consolidation trends.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Rajasthan cluster processors capture margin across crushing, extraction, and refining stages. |
| Carboxymethyl Guar Reactor Installation | Apache Corporation and Pioneer Natural Resources specifications displace unmodified powder above 120°C. |
| BIS IS 14001 Certification Acquisition | EPA Safe Drinking Water Act disclosure mandates privilege batch-level traceability systems. |
| Pharmaceutical-Grade Refining Capacity Expansion | USP-compliant hydrocolloid production for oral solid dosage forms remains underdeveloped outside established players. |
| REACH Dossier Preparation Investment | ECHA registration pathways favor integrated processors serving Hamburg and Düsseldorf cosmetic formulators. |
Methodological Framework
Cross-validation between primary interviews with oilfield procurement directors, BIS certification officers at Rajasthan processors, and EU REACH compliance consultants anchors the qualitative findings. Secondary validation draws from EPA Safe Drinking Water Act filings, BIS export certification databases, and ECHA registration dossiers. Bottom-up triangulation across seed availability estimates, crushing capacity utilization, and derivative production volumes reconciles with top-down oilfield services procurement disclosure patterns.
Sensitivity analysis across viscosity-grade specifications, monsoon rainfall scenarios, and regulatory disclosure stringency informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product type tier, application regulatory intensity, end-user concentration pattern, and regional certification cluster. CAGRs derive from volume-weighted averaging across shale operator procurement commitments and food manufacturer offtake trends, with Rajasthan seed yield variability and EPA disclosure expansion serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act disclosure requirements and BIS IS 14001 certification mandates; material policy shifts would require re-modeling. Specific risk factors include xanthan gum substitution acceleration in lower-temperature fracturing, REACH dossier rejection for Indian exporters, and prolonged Rajasthan drought compressing seed supply. Recalibration cycles align with material shifts in shale operator ESG procurement policies and BIS certification pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Grain Seed Market
Seeds
Watermelon Seeds Market
Seeds
Rapeseed Market
Seeds
Global Alfalfa Seed Market
Seeds
Avena Sativa Market
Seeds
Cowpeas Market
Seeds
Indonesia Seeds Market
Seeds
Sweet Corn Seeds Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Global Grain Seed Market
Seeds
Sesame Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
Mexico Vegetable Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
North America Grain Seed Market
Seeds
Dragon Fruit Seeds Market