
 Celery Seed Oil Market | 2026-2036
Celery Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Celery Seed Oil Market Analysis
India is reconfiguring capacity across Uttar Pradesh and Tamil Nadu distillation corridors. Katyani Exports leverages captive herb sourcing to secure raw material continuity. SVA Organics anchors organic certification pipelines for North American buyers. BOS Natural Flavors competes on flavor-house integration with multinational food manufacturers.
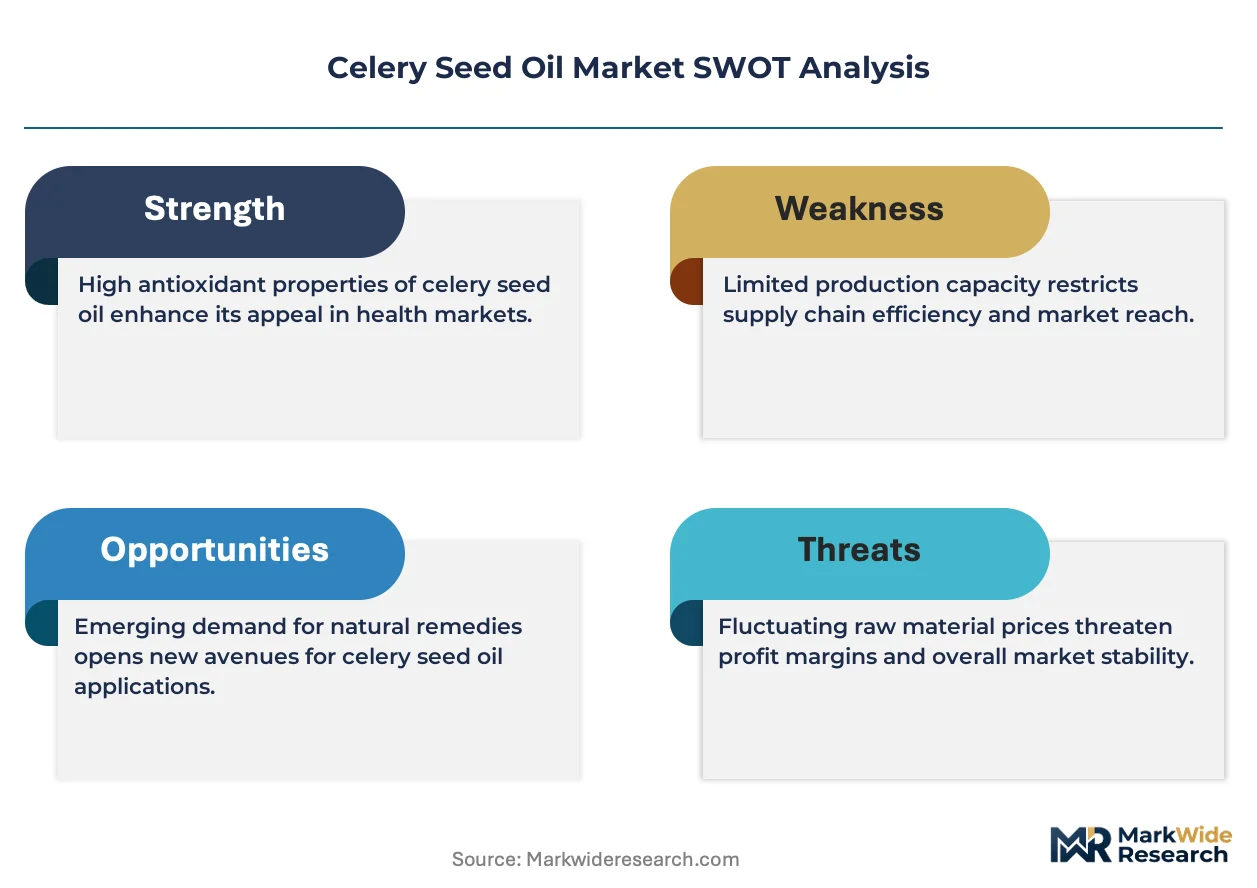
Celery seed oil is a volatile essential oil extracted from Apium graveolens seeds through steam distillation, yielding 2-3% oil content with dominant constituents of sedanolide, sedanonic anhydride, and limonene. The oil functions primarily as a flavoring agent, fragrance fixative, and traditional medicine active with documented anti-inflammatory and spasmolytic properties. Organic oil commands structural premiums as clean-label procurement tightens across European and North American formulations. Pharmaceutical uses represent the fastest-expanding application pool, driven by clinical interest in standardized phytochemical extracts for joint health and metabolic support. Essential oil grades retain the deepest margin pools due to therapeutic-grade certification requirements and limited compliant supply.
FDA oversight of dietary supplement labeling under DSHEA shapes product positioning for US-bound celery seed oil, while EFSA Novel Food assessments govern European market access for non-traditional extract formats. India's FSSAI and CDSCO jointly regulate domestic essential oil quality, with BIS standards for pesticide residues determining export eligibility. Stakeholders must monitor evolving pharmacopeial monograph standards that could bifurcate cosmetic-grade and therapeutic-grade supply chains.
Market Dynamics
Pharmaceutical-grade standardization is compressing supply chains as therapeutic certification requirements harden across North American and European formulation pipelines.
Growth Catalysts
- India's PLI scheme for herbal products:Investment redirects toward standardized essential oil distillation capacity, expanding compliant supply for export markets.
- Clean-label procurement tightening:North American nutraceutical contract manufacturers command premium positioning for certified organic celery seed oil.
- Steam distillation optimization:Yield improvements in seed processing reduce unit costs for therapeutic-grade extraction.
Market Restraints
- Raw material concentration risk:Apium graveolens seed sourcing clusters in specific agro-climatic zones, exposing processors to harvest volatility.
- EFSA Novel Food assessment friction:Non-traditional extract formats face extended market access timelines in European jurisdictions.
- Synthetic limonene substitution:Flavor and fragrance applications face cost-driven displacement from petrochemical alternatives in price-sensitive segments.
Strategic Opportunities
- Joint health formulation expansion:Clinical validation of sedanolide's anti-inflammatory properties opens pharmaceutical white space beyond traditional medicine.
- Direct-to-manufacturer channel development:North American clean-label brands bypass conventional flavor houses for certified organic supply contracts.
- CDSCO therapeutic-grade pathway:India's pharmaceutical regulator offers streamlined monograph recognition for export-grade essential oils.
Industry Challenges
- Pesticide residue compliance:BIS standards for export eligibility require intensive upstream agricultural monitoring and testing infrastructure.
- Therapeutic-cosmetic grade bifurcation:Diverging pharmacopeial standards force dual-track production systems and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celery Seed Oil Market |
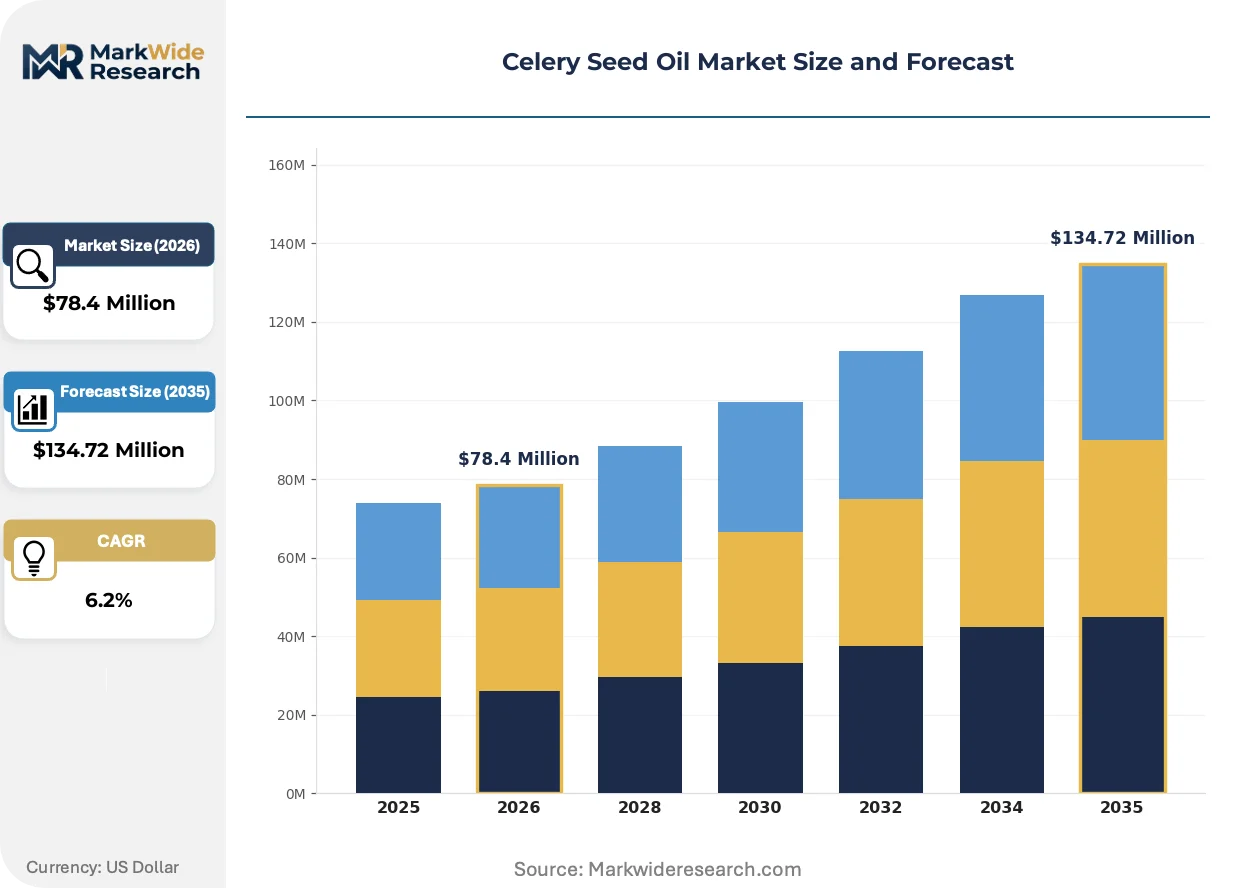
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Oil, Conventional Oil, Refined Oil, Essential Oil Application: Food Industry, Cosmetic Products, Pharmaceutical Uses, Aromatherapy Distribution Channel: Online Stores, Specialty Stores, Supermarkets, Health Shops End User: Manufacturers, Retail Consumers, Healthcare Providers, Cosmetic Brands |
| Companies Covered | Katyani Exports, Indian Spice Oil Industries, Rakesh Sandal Industries, SVA Organics, BOS Natural Flavors, Expo Essential Oils, Imperial Extracts, Sri Venkatesh Aromas, Suminter India Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celery Seed Oil Market Emerging Trajectories
Supercritical CO2 extraction is penetrating premium segments as solvent-free processing becomes a non-negotiable specification for therapeutic-grade procurement.
Supercritical CO2 extraction systems operate at controlled temperature-pressure parameters to isolate sedanolide and sedanonic anhydride without thermal degradation. Pharmaceutical formulators in North America specify this method for new product development. Conventional steam distillation for high-heat-sensitive actives is rendering obsolete in premium therapeutic applications.
REACH registration requirements for botanical substances are tightening substance characterization obligations across European supply chains. ECHA's evolving guidance on essential oil UVCB substances forces additional analytical investment. Small-batch Indian distillers face consolidation pressure as compliance costs escalate beyond standalone capacity.
Certification-driven specification sheets now precede price negotiation in North American buyer-seller relationships. Third-party organic and therapeutic-grade credentials determine vendor pool eligibility before commercial terms are discussed. This pattern concentrates contract volumes with vertically integrated processors in Uttar Pradesh and Tamil Nadu corridors.
Celery Seed Oil Market Segmentation
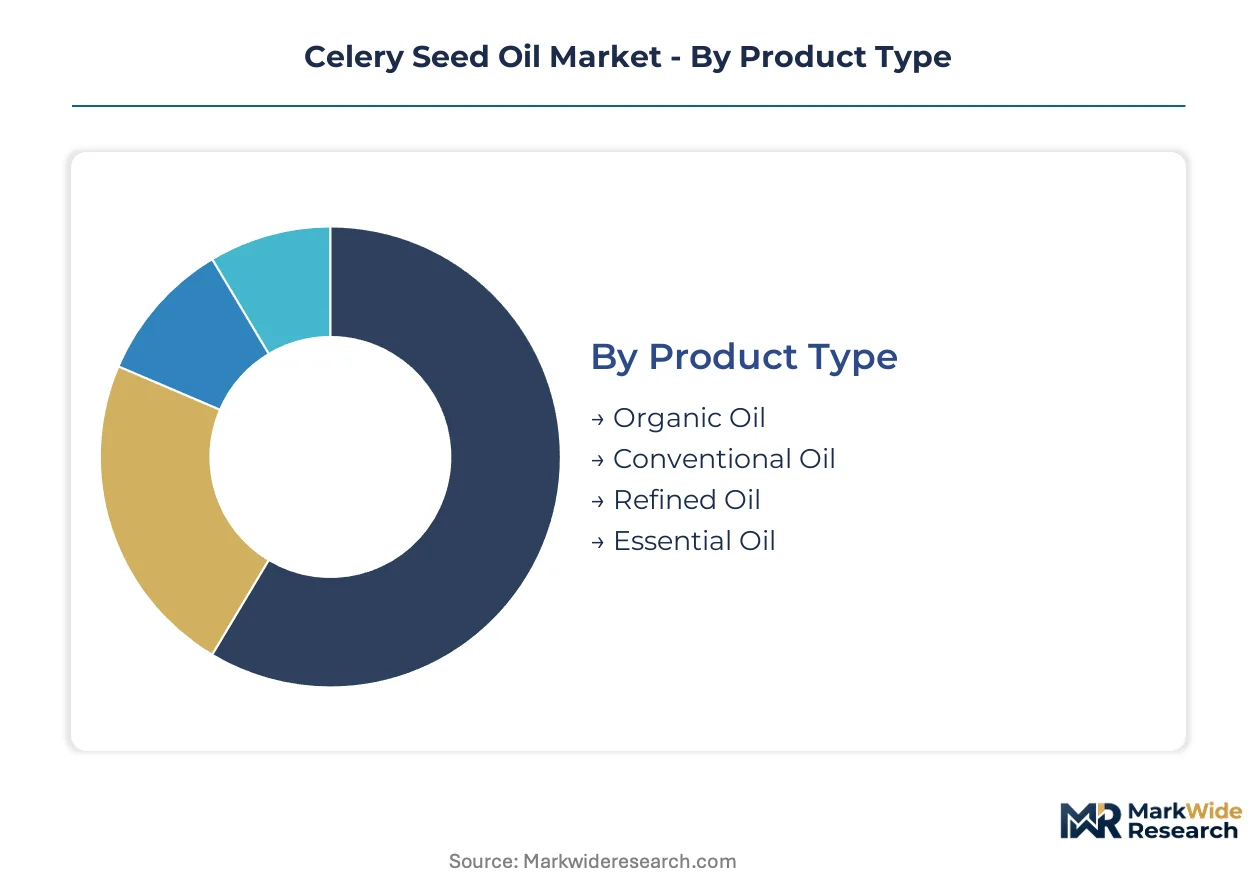
Celery seed oil segmentation reflects divergent purity standards and procurement pathways. Pharmaceutical and clean-label food manufacturers drive specification bifurcation across product grades. Distribution channel evolution is fragmenting traditional flavor-house intermediation.
Product Type:
Mature distillation formats coexist with emerging extraction technologies as certification requirements harden.
- Organic Oil:Certified organic celery seed oil commands structural premiums through clean-label procurement pipelines. North American nutraceutical contract manufacturers specify this grade for premium positioning in joint health formulations.
- Essential Oil:Therapeutic-grade essential oil retains the deepest margin pools due to pharmacopeial monograph compliance and limited compliant supply. Pharmaceutical applications in metabolic support and anti-inflammatory formulations concentrate demand for this segment.
- Conventional Oil:Standard steam-distilled oil serves cost-sensitive flavor and fragrance applications with basic quality specifications.
- Refined Oil:Processed variants undergo additional filtration for color-stable cosmetic and food-grade deployment.
Essential oil handles the majority of throughput; organic oil is the fastest mover on share.
Application:
End-use concentration varies sharply by regulatory pathway and formulation complexity.
- Pharmaceutical Uses:Standardized phytochemical extracts for joint health and metabolic support represent the steepest expansion trajectory. CDSCO monograph recognition and FDA DSHEA compliance frame procurement specifications for export-grade supply.
- Food Industry:Flavor-house integration dominates volume, though clean-label brands increasingly bypass intermediaries for certified organic contracts.
- Cosmetic Products:Fragrance fixative applications favor refined grades with stable color profiles for personal care formulations.
- Aromatherapy:Small-batch therapeutic consumption drives demand for sedanolide-rich essential oil in wellness retail channels.
Food industry absorbs the largest volume base; pharmaceutical uses are climbing the fastest on application share.
Distribution Channel:
Channel structure reflects buyer scale and specification intensity.
- Specialty Stores:Dedicated essential oil retailers curate therapeutic-grade inventory for aromatherapy practitioners and small-scale formulators.
- Online Stores:Direct-to-manufacturer platforms enable North American clean-label brands to secure certified organic supply contracts without conventional intermediaries.
- Supermarkets:Mass-market retail moves conventional and refined grades for culinary and basic cosmetic use.
- Health Shops:Natural products retailers stock organic and therapeutic-grade oils for wellness-focused consumers.
Specialty stores handle the majority of premium throughput; online stores are gaining share fastest among commercial buyers.
End User:
User type determines specification depth and contract structure.
- Manufacturers:Nutraceutical, food, and cosmetic producers drive volume procurement with certificate-of-analysis requirements and multi-year supply agreements.
- Cosmetic Brands:Clean-label positioning demands organic certification and REACH-compliant substance characterization for European market access.
- Healthcare Providers:Integrative medicine practitioners specify therapeutic-grade oil for clinical applications with documented anti-inflammatory properties.
- Retail Consumers:Individual purchasers through health shops and online channels generate fragmented demand with high service requirements.
Manufacturers command the dominant share of commercial throughput; cosmetic brands are expanding their specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of dietary supplement labeling under DSHEA anchors North American procurement specifications for celery seed oil, while India's PLI scheme for herbal products redirects investment toward standardized distillation capacity across Uttar Pradesh and Tamil Nadu corridors.
United States
North American nutraceutical contract manufacturers command premium positioning for certified organic celery seed oil in joint health formulations. FDA DSHEA compliance requirements shape product positioning and certificate-of-analysis specifications for import-bound supply. Greater New York and New Jersey processing clusters handle the deepest volume of therapeutic-grade essential oil for pharmaceutical applications.
India
Domestic demand for standardized phytochemical extracts is deepening as CDSCO therapeutic-grade pathways streamline monograph recognition for export-grade essential oils. India's PLI scheme for herbal products redirects capital toward compliant distillation infrastructure. Uttar Pradesh and Tamil Nadu distillation corridors are reconfiguring capacity to serve North American and European clean-label procurement pipelines.
Germany
Flavor-house integration with multinational food manufacturers concentrates demand for refined celery seed oil grades in metabolic support formulations. ECHA REACH registration requirements for botanical substances tighten substance characterization obligations across supply chains. Bavaria and Baden-Württemberg processing hubs are consolidating analytical investment to meet evolving UVCB substance guidance.
United Kingdom
Clean-label cosmetic brands specify organic certification and REACH-compliant substance characterization for European market access. EFSA Novel Food assessments govern market entry timelines for non-traditional extract formats. London and Southeast England formulation clusters are fragmenting traditional flavor-house intermediation through direct-to-manufacturer procurement channels.
Japan
Integrative medicine practitioners specify therapeutic-grade oil for clinical applications with documented anti-inflammatory properties. METI industrial standards and PMDA pharmaceutical regulations frame import specifications for sedanolide-rich extracts. Kanto and Kansai aromatherapy retail channels generate fragmented demand for small-batch therapeutic consumption.
Celery Seed Oil Market Vendor Landscape
Capability concentration sits with vertically integrated processors holding captive herb sourcing and organic certification pipelines; scale advantage sits with flavor-house integrated suppliers serving multinational food manufacturers. The vendor base separates into three strategic archetypes: Uttar Pradesh and Tamil Nadu-based distillers with backward integration into seed cultivation, certified organic specialists with third-party credential pipelines, and flavor-house integrated processors competing on multinational manufacturer relationships. Dominant competitive moves include capacity expansion in compliant distillation infrastructure and direct-to-manufacturer channel development bypassing traditional intermediaries.
Within the vertically integrated tier, Katyani Exports and SVA Organics occupy positions anchored by captive herb sourcing and organic certification pipelines respectively. BOS Natural Flavors exemplifies the flavor-house integration archetype, competing on relationships with multinational food manufacturers. These three company structures represent the dominant competitive vectors: upstream control over raw material continuity, third-party credential access for premium positioning, and downstream integration with formulation houses.
| Leading Market Players |
|---|
| Katyani Exports |
| Indian Spice Oil Industries |
| Rakesh Sandal Industries |
| SVA Organics |
| BOS Natural Flavors |
| Expo Essential Oils |
| Imperial Extracts |
| Sri Venkatesh Aromas |
| Suminter India Organics |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Uttar Pradesh distillation corridors is compressing supplier margins and amplifying pricing power for certified organic grades. Indian processors facing BIS pesticide-residue compliance costs are passing through quality premiums to North American nutraceutical contract manufacturers, while conventional steam-distilled grades face cost-driven displacement from synthetic limonene alternatives.
Pricing Analysis
Indian-origin organic celery seed oil commands a 40-60% premium over conventional grades in North American procurement pipelines. Three-tier pricing structure across therapeutic-grade, certified organic, and conventional steam-distilled levels reflects certification depth and pharmacopeial compliance. Pricing pressure stems from synthetic limonene substitution in flavor applications, where petrochemical alternatives undercut natural oil on cost. Small-batch aromatherapy buyers exhibit highest price sensitivity; pharmaceutical formulators show lowest sensitivity due to therapeutic-grade specification rigidity.
Supply Chain Analysis
Extended payment terms from North American nutraceutical buyers are straining working capital for small-batch Indian distillers, accelerating consolidation toward vertically integrated processors. Supply concentrates in India, with secondary sourcing corridors in Egypt and China for conventional grades. Raw material dependencies center on Apium graveolens seed availability, steam distillation infrastructure, and organic certification auditing capacity. Single-source vulnerability runs through Uttar Pradesh and Tamil Nadu agro-climatic zones exposed to monsoon harvest volatility. Distribution runs through direct-to-manufacturer channels for premium grades, with flavor-house intermediation persisting for conventional food-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service represents the fastest-expanding recurring-revenue layer, outpacing base oil sales as North American buyers demand third-party credential maintenance and pharmacopeial documentation updates.
For Market Incumbents: Build regulatory moats through CDSCO therapeutic-grade monograph recognition and FDA DSHEA Master File submissions. Secure captive herb sourcing in Uttar Pradesh and Tamil Nadu corridors to defend against harvest volatility. Invest in supercritical CO2 extraction capacity to outpace steam distillation obsolescence in pharmaceutical-grade segments. For New Entrants and Emerging Players: Build out direct-to-manufacturer channel infrastructure targeting North American clean-label brands bypassing conventional flavor-house intermediaries. Target pharmaceutical-grade essential oil white space where therapeutic certification requirements limit compliant supply. Pursue organic certification pipelines as the primary go-to-market credential for premium positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated processors with captive herb sourcing and multi-year supply agreements. Five-to-ten year viability favors processors holding backward integration into seed cultivation and forward integration with formulation houses. Monitor EFSA Novel Food assessment timelines as the key inflection signal for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Capacity Addition | Pharmaceutical formulators in North America specify solvent-free processing for sedanolide-rich extracts. |
| CDSCO Therapeutic-Grade Monograph Recognition | India's pharmaceutical regulator streamlines export-grade essential oil compliance pathways. |
| Direct-to-Manufacturer Channel Development | North American clean-label brands bypass flavor-house intermediaries for certified organic contracts. |
| Captive Herb Sourcing in Uttar Pradesh Corridors | Backward integration into seed cultivation defends raw material continuity against harvest volatility. |
| REACH-Compliant Substance Characterization Investment | ECHA's UVCB guidance forces analytical capabilities for European market access retention. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with essential oil distillers, nutraceutical procurement managers, and regulatory affairs specialists; and secondary validation through CDSCO filings, FSSAI quality standards, FDA DSHEA guidance documents, and EFSA Novel Food assessment records. Bottom-up volume estimates from distillation capacity utilization in Uttar Pradesh and Tamil Nadu corridors were triangulated against top-down demand aggregation from North American contract manufacturer procurement patterns.
Forecast inputs considered therapeutic-grade certification penetration, clean-label procurement tightening, and steam distillation yield improvements across the projection horizon. Segmentation dimensions modeled include product grade tier, application intensity, distribution channel structure, and end-user specification depth. CAGRs were derived from slope analysis of historical price-volume relationships and forward capacity expansion announcements. Industry-specific inputs incorporated PLI scheme disbursement timelines and ECHA REACH registration progression for botanical substances.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Egyptian or Chinese entrants would shift outcomes. Macroeconomic deviation in agricultural input costs, regulatory acceleration in pharmacopeial standards, or technological disruption in synthetic biology substitutes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Uganda Seeds Market
Seeds
Americas Seeds Market
Seeds
Arnica Montana Market
Seeds
Europe Vegetable Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Europe Grain Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Vietnam Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Cannabis Seeds Market
Seeds
Safflower Seeds Market
Seeds
India Vegetable Seed Market
Seeds
Sesame Seeds Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Global Wheat Seed Market
Seeds
India Forage Seed Market