
 Asia-Pacific Cannabis Seeds Market | 2026-2036
Asia-Pacific Cannabis Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cannabis Seeds Market Outlook
Aftermarket service revenue from genetic certification and strain verification is narrowing as seed producers integrate laboratory testing in-house. Cann Group Limited leverages its Australian cultivation licenses to control upstream genetics supply. Green House Thailand anchors its position through tropical strain adaptation programs. Sensi Seeds competes via decades of stabilized breeding lines adapted to controlled-environment agriculture.
Cannabis seeds are sexually reproduced propagules containing diploid embryonic tissue encased in a protective testa, typically exhibiting germination viability of 70-90% under controlled humidity and temperature protocols; their commercial purpose centers on producing standardized cannabinoid profiles for regulated medical and industrial supply chains. Feminized seeds command premium positioning due to their elimination of male chromosome segregation and the resulting efficiency gains in flowering-room utilization. Autoflowering varieties are gaining fastest among small-scale licensed producers seeking compressed harvest cycles. Distribution through agricultural suppliers remains the dominant channel for commercial farmers requiring bulk volume and phytosanitary documentation.
Australia's Therapeutic Goods Administration and Thailand's Food and Drug Administration operate divergent seed import protocols that directly shape cross-border trade flows and domestic breeding investment decisions. India's Narcotics Control Bureau maintains restrictive import licensing that limits formal market development despite favorable agroclimatic zones. Stakeholders must monitor how regulatory harmonization efforts between ASEAN member states reshape seed mobility and intellectual property frameworks for proprietary cultivars.
Market Dynamics
Licensed producers across Australia and Thailand are compressing breeding cycles through controlled-environment agriculture, forcing seed suppliers to integrate phenotyping laboratories directly into their operations rather than relying on third-party certification.
Growth Catalysts
- Thailand's Narcotics Code amendments:The liberalized framework permits commercial hemp cultivation and medical cannabis production, creating formal import channels for certified genetics and domestic breeding infrastructure.
- Feminized seed technology:Elimination of male chromosome segregation through silver thiosulfate protocols delivers 99% female populations, maximizing flowering-room utilization rates for pharmaceutical-grade cultivators.
- Australia's TGA Special Access Scheme:The regulatory pathway for unapproved therapeutic goods sustains demand for standardized, high-THC and high-CBD cultivars with documented stability across generations.
Market Restraints
- Phytosanitary certification complexity:Australia's Department of Agriculture and Thailand's Department of Agriculture impose divergent quarantine protocols on imported seeds, fragmenting cross-border supply chains and extending lead times.
- Genetic stability limitations:Polyploidy induction and tissue culture propagation remain technically demanding for tropical strain adaptation, constraining domestic breeding program output consistency.
- Import licensing concentration:India's Narcotics Control Bureau maintains restrictive seed import controls that block formal market development despite favorable agroclimatic conditions in Karnataka and Himachal Pradesh.
Strategic Opportunities
- ASEAN regulatory harmonization:Proposed alignment of seed mobility frameworks and intellectual property protocols for proprietary cultivars would unlock cross-border breeding collaborations between Thailand, Malaysia, and Vietnam.
- Autoflowering genetics for small-scale producers:Ruderalis-cross varieties offering 10-week seed-to-harvest cycles address the compressed production timelines sought by Thailand's emerging craft cultivation sector.
- Direct-to-farmer digital platforms:E-commerce channels with embedded phytosanitary documentation and genetic verification are displacing traditional agricultural supplier intermediaries for licensed micro-producers.
Industry Challenges
- Certification timeline compression:Australia's Office of the Gene Technology Regulator and Thailand's FDA require multi-year stability testing for novel cultivars, delaying commercialization of elite breeding lines.
- Phenotyping talent scarcity:Controlled-environment agriculture operators face acute shortages of technicians trained in high-throughput cannabinoid profiling and terpene analysis.
- Seed-to-sale traceability integration:Producers must reconcile proprietary breeding records with government-mandated tracking systems, creating data architecture friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cannabis Seeds Market |
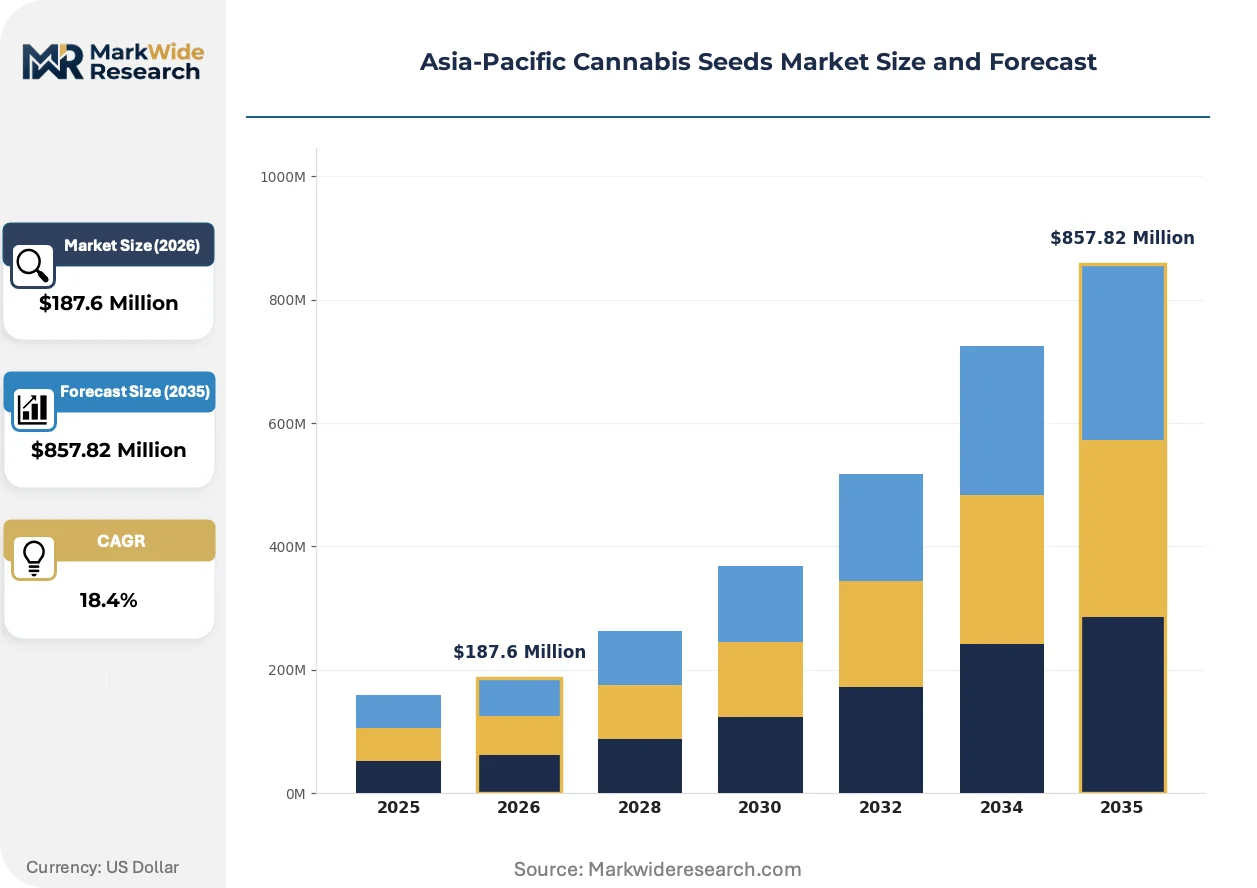
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $857.82 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feminized Seeds, Autoflowering Seeds, Regular Seeds, Hybrid Seeds Application: Medical Use, Recreational Use, Research Purposes, Hemp Production Distribution Channel: Online Retail, Specialty Stores, Dispensaries, Agricultural Suppliers Customer Type: Growers, Commercial Farmers, Research Institutions, Hobbyists |
| Companies Covered | Althea Group, Cann Group Limited, Little Green Pharma, Green House Thailand, PTT Public Company Limited, Christiania Seeds, Barneys Souvenirs BV, Paradise Seeds Family, Sensi Seeds, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cannabis Seeds Market Strategic Shifts
Digital phenotyping platforms and marker-assisted selection are compressing cultivar development timelines while regulatory divergence between Australia and Thailand forces suppliers to maintain parallel compliance architectures.
Marker-assisted selection using single nucleotide polymorphism arrays is virtualizing traditional phenotype-based breeding programs. Australian licensed producers are adopting these platforms at scale to accelerate cannabinoid ratio stabilization. The technology is virtualizing decade-long breeding timelines into 18-month cycles, collapsing the competitive moat of established European seed houses.
Thailand's FDA has issued specific guidance on novel food ingredients derived from hemp seeds, creating a compliance pathway for protein and oil products that diverges from Australia's stricter novel food assessment framework. This regulatory divergence is fragmenting product formulation strategies across the region. Thai processors are responding by developing THC-free hemp seed derivatives for export markets while Australian operators focus exclusively on pharmaceutical-grade flower production.
Small-scale licensed producers are consolidating purchases through cooperative procurement structures to access volume-tier pricing and shared phytosanitary documentation. Agricultural supplier channels serving this segment face margin compression as these buying groups negotiate direct relationships with Dutch and Spanish breeding houses. The shift is most visible in Thailand's northern provinces where craft cultivation licenses have concentrated geographically.
Asia-Pacific Cannabis Seeds Market Segmentation
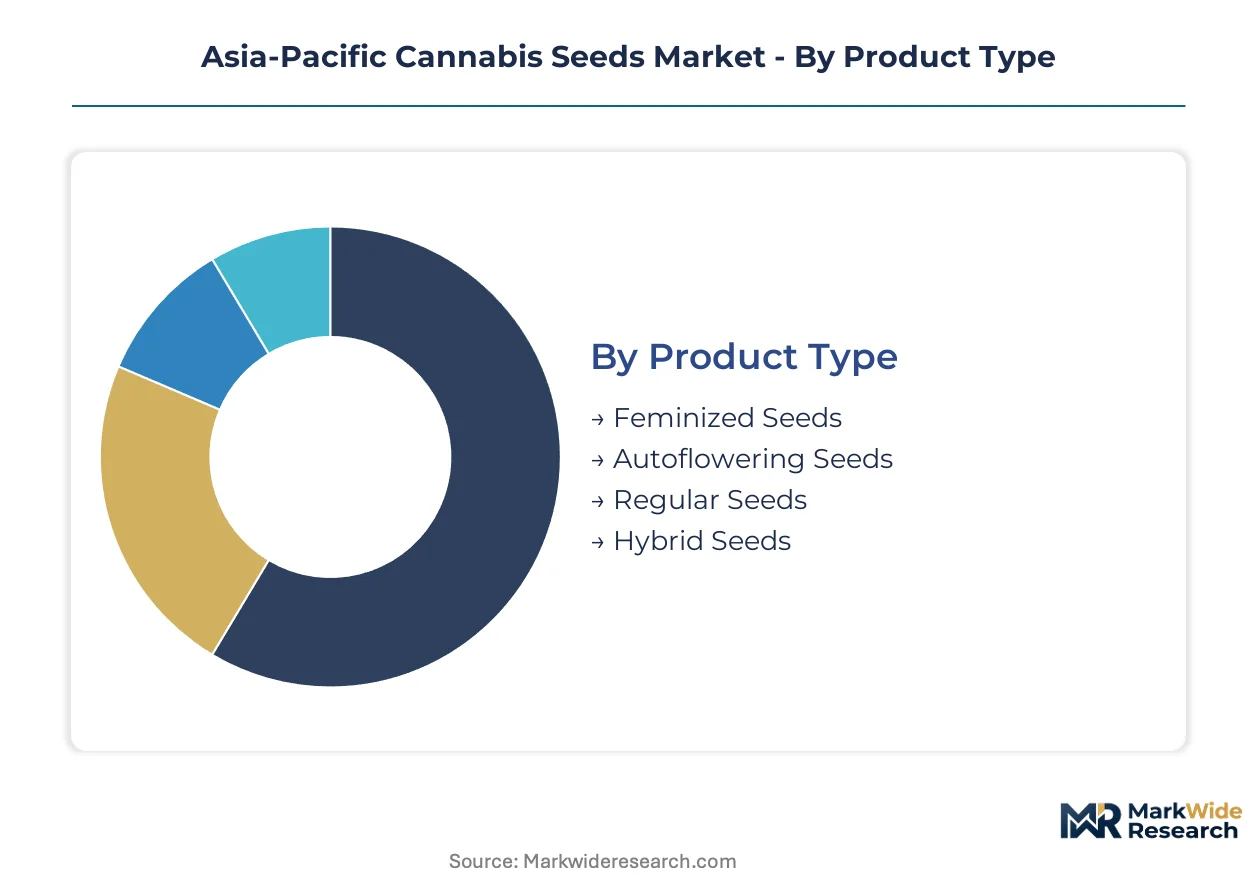
Segmentation in the Asia-Pacific cannabis seeds market reveals how cultivation scale and regulatory intent reshape procurement patterns across Thailand's emerging craft sector and Australia's pharmaceutical-grade facilities. Cycle times vary dramatically by product type and customer sophistication, compressing inventory turns for autoflowering varieties while stabilizing demand for certified medical genetics.
Product Type:
Cycle times range from ten weeks for autoflowering crosses to multi-year stability testing for pharmaceutical-grade feminized lines, creating divergent working capital requirements across seed categories.
- Feminized Seeds:Diploid propagules treated with silver thiosulfate to suppress male chromosome expression, delivering 99% female populations. Australia's TGA-licensed producers anchor demand for these genetics, driven by flowering-room utilization mandates and batch consistency requirements for therapeutic goods manufacturing.
- Autoflowering Seeds:Ruderalis-hybrid varieties carrying photoperiod-independent flowering triggers. Thailand's northern craft cultivation licenses concentrate demand here, compelled by compressed harvest cycles and limited climate-controlled infrastructure among small-scale operators.
- Regular Seeds:Sexually reproduced propagules with standard chromosome segregation patterns. Breeding programs at Thai agricultural universities utilize these for phenotypic selection and genetic diversity preservation.
- Hybrid Seeds:Crosses combining indica, sativa, and ruderalis lineages for targeted cannabinoid ratios. Australian producers seeking novel chemovars for the Special Access Scheme drive specialized demand.
Feminized seeds anchor the volume base while autoflowering varieties gain share at the steepest rate.
Application:
Cost tiers stratify sharply between pharmaceutical-grade cultivation requiring multi-year stability documentation and craft production accepting shorter genetic pedigrees.
- Medical Use:Standardized cultivars with documented THC/CBD ratios and terpene profiles for therapeutic applications. Australia's TGA Special Access Scheme and Thailand's FDA medical cannabis registry shape compliance requirements, with demand concentrating in GMP-certified facilities.
- Hemp Production:THC-compliant varieties for fiber, seed, and extract applications. Thailand's amended Narcotics Code permits commercial hemp cultivation, creating formal demand channels distinct from medical cannabis frameworks.
- Recreational Use:Adult-use cultivation where jurisdictions permit. Limited formal market presence in the Asia-Pacific region due to prevailing prohibition frameworks outside specific Thai licensing windows.
- Research Purposes:Genetic material for cannabinoid biosynthesis studies and agronomic trials. Australian universities and Thai agricultural research stations source specialized phenotypes under controlled substance licenses.
Medical use commands the premium tier while hemp production scales fastest among cost-sensitive segments.
Distribution Channel:
Customer sophistication determines channel selection, with institutional buyers requiring embedded phytosanitary documentation and hobbyists prioritizing genetic variety access.
- Agricultural Suppliers:Bulk volume channels serving commercial farmers with phytosanitary certification, volume-tier pricing, and technical support. Australia's licensed producers and Thailand's hemp cooperatives consolidate purchases through these intermediaries.
- Online Retail:Direct-to-grower platforms with genetic verification and compliance documentation. Thai micro-producers increasingly bypass traditional suppliers through cooperative procurement structures accessing Dutch and Spanish breeding houses.
- Specialty Stores:Physical retail with curated genetics and cultivation consultation. Limited presence in the region due to regulatory restrictions on cannabis-related commerce.
- Dispensaries:Regulated retail channels for licensed medical cannabis patients. Emerging in Thailand's medical cannabis framework with seed sales ancillary to finished product distribution.
Agricultural suppliers dominate transaction value while online retail expands most quickly among small-scale licensed operators.
Customer Type:
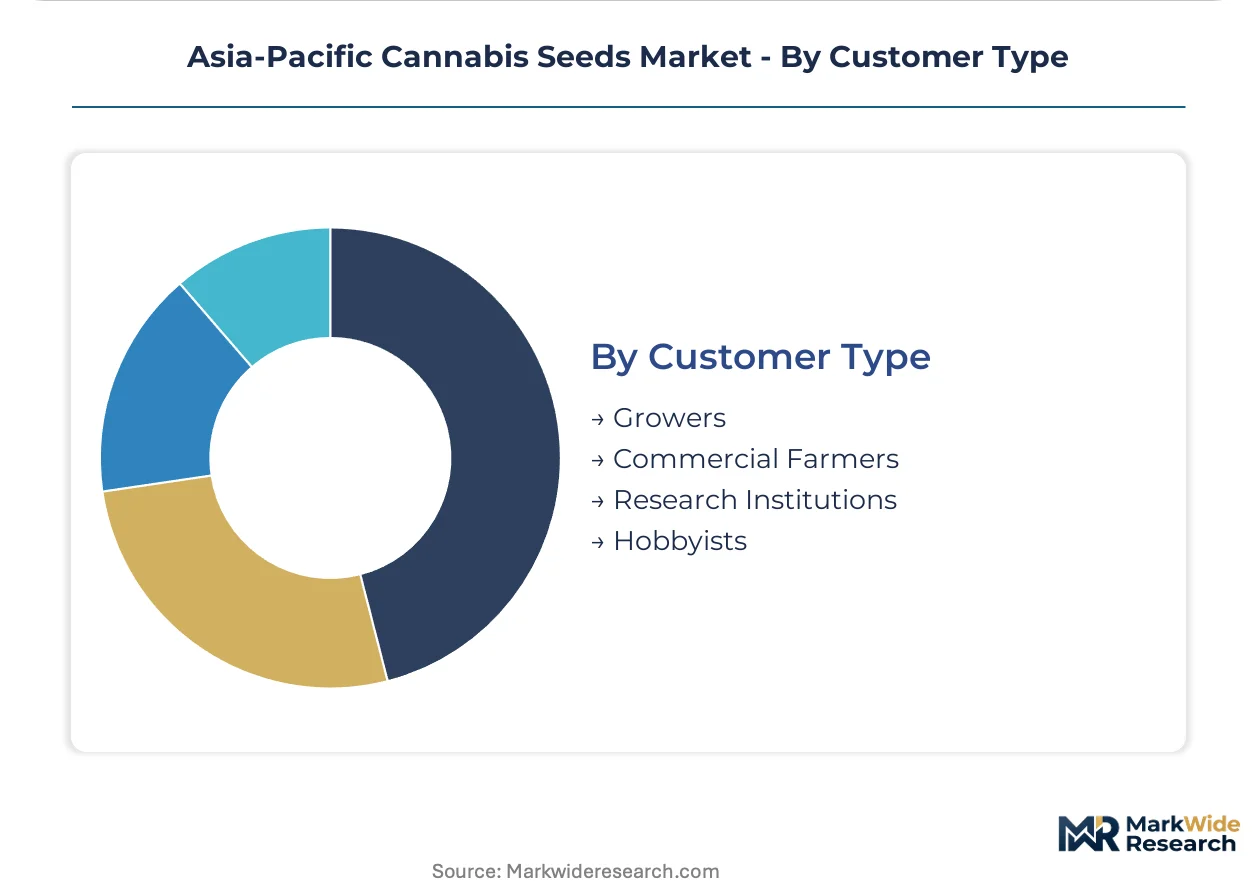
Procurement scale and technical capability create distinct service requirements, from high-throughput phenotyping support for institutional buyers to germination guarantees for novice cultivators.
- Commercial Farmers:Large-scale licensed producers requiring batch consistency, genetic stability documentation, and supply security. Australia's Cann Group and Thailand's Green House Thailand anchor this segment with multi-year offtake arrangements.
- Research Institutions:Universities and agricultural stations conducting breeding programs and agronomic trials. Australia's Office of the Gene Technology Regulator and Thailand's Department of Agriculture impose distinct compliance frameworks on these customers.
- Growers:Mid-scale licensed cultivators with technical capability for phenotypic selection. Thailand's craft cultivation licenses in Chiang Mai and Mae Hong Son provinces concentrate this customer type.
- Hobbyists:Small-scale cultivators with limited technical infrastructure and regulatory exposure. Minimal formal market participation due to licensing requirements across the Asia-Pacific region.
Commercial farmers represent the revenue foundation while research institutions drive breeding innovation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's craft cultivators exhibit the highest price elasticity, squeezing margins on standard genetics, while Australia's pharmaceutical-grade producers absorb premium pricing for certified feminized lines with multi-generational stability documentation.
Australia
Pharmaceutical-grade cultivation facilities anchor demand for high-THC and high-CBD genetics with batch consistency mandates. The Therapeutic Goods Administration's Special Access Scheme requires documented stability across generations, favoring suppliers with in-house phenotyping laboratories. Victoria and New South Wales concentrate licensed production, with Cann Group Limited controlling upstream genetics supply through its cultivation licenses.
Thailand
Liberalized Narcotics Code amendments permit commercial hemp cultivation and medical cannabis production, creating formal import channels for certified genetics. The Food and Drug Administration operates seed import protocols distinct from Australia's quarantine framework. Northern provinces including Chiang Mai and Mae Hong Son concentrate craft cultivation licenses, driving demand for autoflowering varieties with compressed harvest cycles.
India
Favorable agroclimatic conditions in Karnataka and Himachal Pradesh remain underutilized due to restrictive import licensing. The Narcotics Control Bureau maintains controls that block formal market development despite agricultural potential. Domestic demand concentrates in research institutions conducting cannabinoid biosynthesis studies under controlled substance licenses.
Japan
Industrial hemp fiber applications dominate legal cultivation under strict THC thresholds. The Ministry of Health, Labour and Welfare maintains prohibitive frameworks for medical cannabis, limiting seed market development. Hokkaido's agricultural research stations conduct agronomic trials for low-THC varieties suited to northern climates.
South Korea
Medical cannabis imports were legalized in 2018, though domestic cultivation remains prohibited. The Ministry of Food and Drug Safety regulates hemp seed derivatives for cosmetic and food applications. Seoul-based pharmaceutical distributors source certified genetics through international breeding houses for compounding pharmacy supply.
Asia-Pacific Cannabis Seeds Market Competitive Environment
Vertically integrated cultivator-breeders and specialized European seed houses split the market, with the former capturing pharmaceutical-grade contracts and the latter supplying craft-scale operators. Three archetypes dominate: licensed producers with captive genetics programs, established Dutch and Spanish breeding houses with stabilized lineages, and regional distributors with phytosanitary certification capabilities. Competitive moves concentrate on backward integration into laboratory phenotyping and direct-to-farmer digital platform development.
Within the licensed producer tier, Cann Group Limited exemplifies vertical control over upstream genetics through Australian cultivation licenses, while Green House Thailand anchors tropical strain adaptation programs. Among established breeding houses, Sensi Seeds occupies a position representing decades of stabilized genetics for controlled-environment agriculture. These three entities exemplify how regulatory divergence between Australia's TGA framework and Thailand's FDA protocols forces parallel compliance architectures rather than standardized regional offerings.
| Leading Market Players |
|---|
| Althea Group |
| Cann Group Limited |
| Little Green Pharma |
| Green House Thailand |
| PTT Public Company Limited |
| Christiania Seeds |
| Barneys Souvenirs BV |
| Paradise Seeds Family |
| Sensi Seeds |
| Others |
Value Chain & Pricing Dynamics
Phytosanitary certification chokepoints between Australia's Department of Agriculture and Thailand's FDA determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of breeding infrastructure. These regulatory barriers force suppliers to maintain parallel compliance architectures, compressing margins on standard genetics while sustaining premium capture on certified feminized lines with multi-generational stability documentation.
Pricing Analysis
Aftermarket service revenue from genetic verification and strain certification drives lifetime value as seed producers integrate laboratory testing in-house. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade feminized seeds with TGA documentation from craft-scale autoflowering varieties and bulk hemp genetics. Cost compression in Thailand's craft segment intensifies as cooperative procurement structures negotiate direct relationships with Dutch breeding houses. Australia's TGA-licensed producers exhibit lowest price sensitivity due to batch consistency mandates, while northern Thai craft cultivators demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from Australian licensed producers and supply-chain finance facilities for Thai hemp cooperatives anchor working capital dynamics. Breeding infrastructure concentrates in the Netherlands, Spain, and Australia, with tropical adaptation programs emerging in Thailand. The supply chain rests on live tissue cultures, stabilized seed lines, and phenotyping laboratory equipment. Single-source vulnerability runs through European breeding houses for elite genetics. Distribution runs through agricultural suppliers with embedded phytosanitary documentation for institutional buyers, while direct-to-farmer digital platforms displace intermediaries among Thai micro-producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cannabis seeds demand is recovering from regulatory harmonization delays, with Thailand's Narcotics Code amendments and Australia's TGA pathway expansions serving as the cyclical driver.
For Market Incumbents: Build captive genetics moats through in-house phenotyping laboratories and multi-year stability testing infrastructure. Secure backward integration into tissue culture propagation to defend against European breeding house margin compression. Add certified capacity in Victoria and New South Wales to anchor pharmaceutical-grade contracts. For New Entrants and Emerging Players: Pursue white-space opportunities in India's research institution channel under controlled substance licenses, where Narcotics Control Bureau restrictions block incumbent expansion. Target Thailand's autoflowering segment through direct-to-farmer digital platforms with embedded FDA compliance documentation. Launch via cooperative procurement structures in Chiang Mai and Mae Hong Son provinces. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors vertically integrated cultivator-breeders with captive laboratory infrastructure. Long-term viability hinges on intellectual property control over tropical-adapted chemovars. The signal to watch is ASEAN regulatory harmonization progress on seed mobility frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Phenotyping Laboratory Integration | Cann Group Limited's in-house testing compresses third-party certification timelines for TGA submissions. |
| Tropical Strain Adaptation Program | Green House Thailand's ruderalis-cross development addresses compressed harvest cycles in northern provinces. |
| Direct-to-Farmer Digital Platform | Thai cooperative procurement structures bypass agricultural supplier intermediaries for volume-tier pricing access. |
| ASEAN Regulatory Harmonization Lobbying | Alignment of seed mobility frameworks would unlock cross-border breeding collaborations with Vietnamese and Malaysian partners. |
| Autoflowering Genetics Patent Portfolio | Intellectual property control over photoperiod-independent varieties protects margin position in Thailand's craft segment. |
Study Parameters
Operator-level perspectives from cultivation license holders, phytosanitary certification officers, and agricultural procurement managers anchored the qualitative base. Primary interviews with breeding program directors at Thai universities and regulatory affairs specialists at Australia's Office of the Gene Technology Regulator combined with secondary validation from TGA Special Access Scheme documentation, Thai FDA seed import protocols, and ASEAN trade harmonization records. Bottom-up segmentation triangulation across product type, application, and distribution channel informed volume estimates.
Scenario-bracketing framed the analytical approach across the analysis window, with conservative, baseline, and expansion cases reflecting regulatory pace divergence between Australia and Thailand. Segmentation dimensions modeled include seed type, cultivation scale tier, and compliance documentation level. CAGRs derived from installed base growth of licensed producers and per-facility genetics spend trajectories. Forecast inputs incorporated TGA approval timelines for novel cultivars and Thai FDA hemp seed derivative guidance evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European breeding houses establishing direct Thai operations would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Wheat Seed Market
Seeds
Carrot Seed Oil Market
Seeds
South America Forage Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
Europe Forage Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Poppy Seed Market
Seeds
E. Angustifolium Market
Seeds
Hemp Seed Oil Market
Seeds
Myanmar Rice Seed Market
Seeds
North America Forage Seed Market
Seeds
Global Soybean Seed Market
Seeds
Commercial Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
Seed Health Market
Seeds
Africa Grain Seed Market