
 India Forage Seed Market | 2026-2036
India Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
India Forage Seed Market Foresight
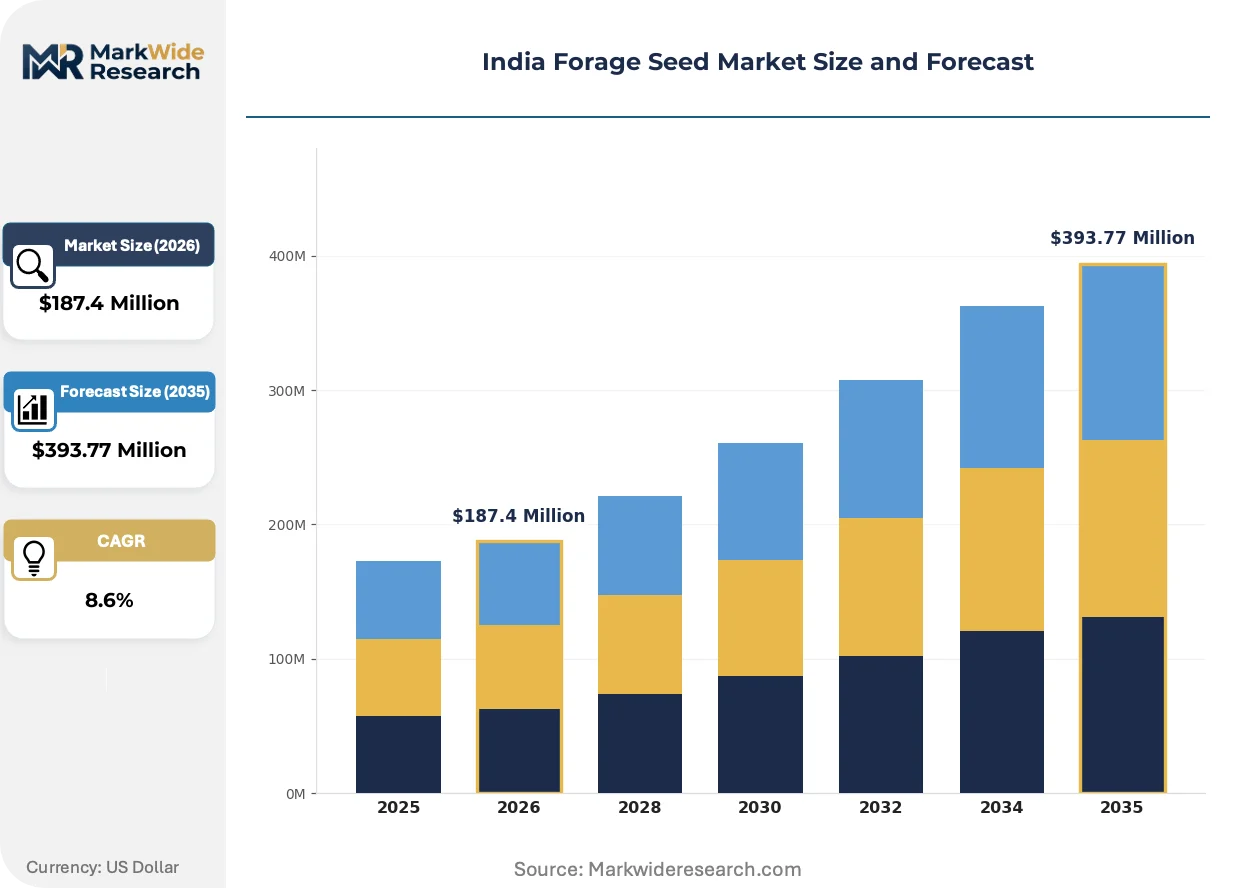
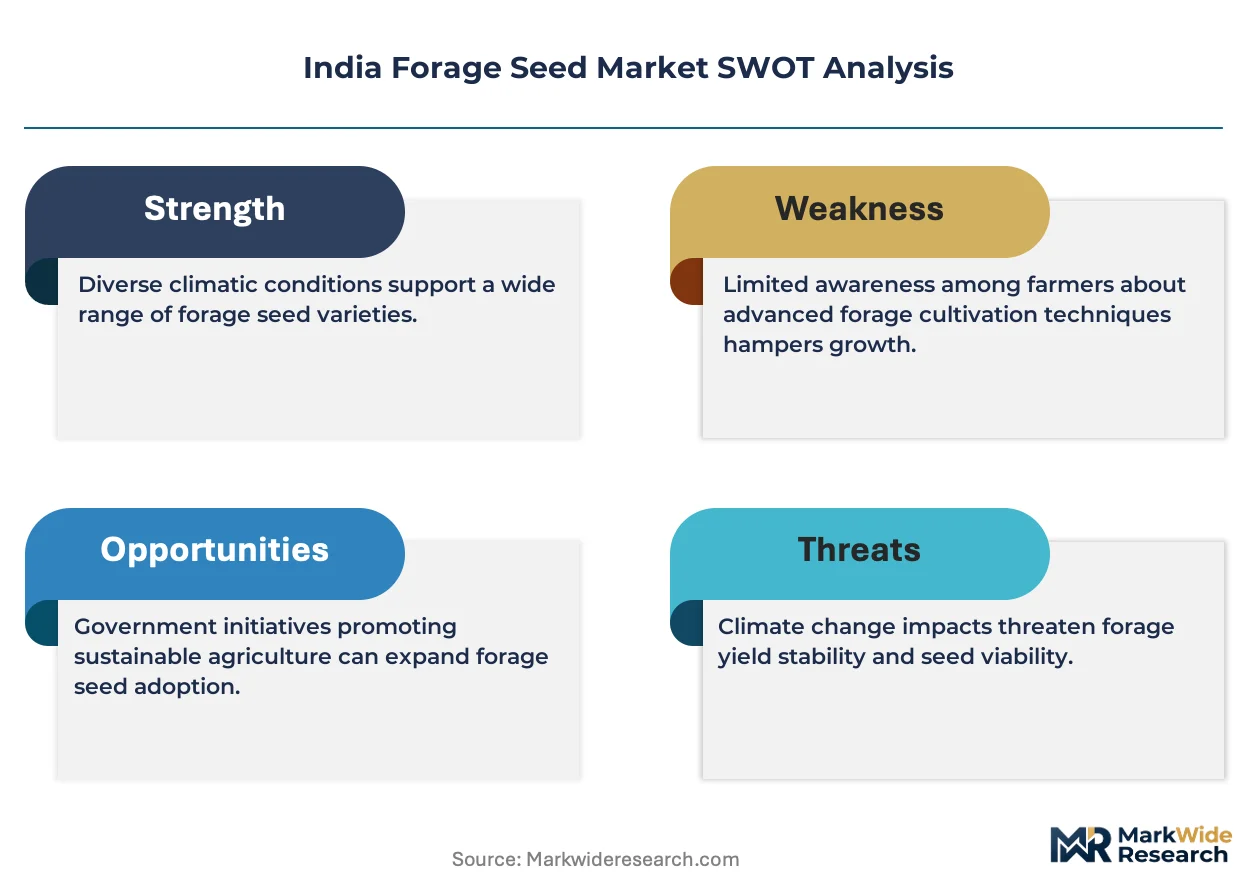
PLI scheme incentives for agriculture inputs is pivoting domestic breeding economics toward scale players. Syngenta Group leverages its global germplasm library to anchor premium hybrid alfalfa lines for Indian dairy systems. Bayer AG sustains molecular marker programs that differentiate disease-resistant varieties for humid tropical zones. Kaveri Seed Company competes through region-specific portfolio depth across South Indian fodder markets.
Forage seeds are botanically verified propagules selected for germination vigor, nutritional metabolite profiles, and stand persistence under grazing pressure, typically processed through certified multiplication chains to maintain genetic purity above foundation standards. Their primary commercial purpose is to establish cultivated pastures and conserved fodder banks that substitute open grazing with measured biomass output. Legumes command margin pools due to nitrogen-fixation premiums in dairy ration formulations, while grasses dominate volume throughput across silage supply chains. Brassicas occupy a narrow but expanding niche in winter-gap feeding systems where crude protein concentration justifies per-unit price premiums.
BIS seed certification standards and FSSAI feed safety norms together determine market access thresholds for commercial forage seed lots. CDSCO oversight on novel trait introductions constrains transgenic pipeline speeds for domestic developers. State agricultural universities and ICAR institutions shape cultivar release calendars through multi-location trial protocols. Stakeholders must monitor how evolving drought-tolerance breeding targets interact with groundwater extraction regulations in northwestern irrigation districts.
Market Dynamics
The PLI scheme for agriculture inputs is reconfiguring domestic breeding economics, tilting investment toward scale players with certified multiplication infrastructure while compressing margins for uncertified seed traders operating in informal channels.
Growth Catalysts
- PLI scheme incentives:Production-linked incentives for agriculture inputs accelerate capital deployment into domestic breeding programs and certified seed multiplication chains.
- Dairy cooperative procurement mandates:Gujarat and Maharashtra dairy federations now specify certified fodder seed in bulk supply contracts, pulling volume through organized channels.
- Groundwater extraction regulations:Northwestern irrigation districts face pumping restrictions that favor drought-tolerant alfalfa and fodder sorghum varieties with higher biomass per liter of water applied.
Market Restraints
- Foundation seed supply concentration:ICAR institutions and state agricultural universities control breeder seed release calendars, creating bottlenecks for private sector multiplication programs.
- Genetic purity verification costs:BIS certification mandates laboratory testing for germination vigor and off-type contamination, adding fixed cost burdens below 50-ton seed lots.
- Open grazing substitution limits:Smallholder dairy operations in rainfed districts continue relying on common pasture access, delaying commercial forage seed adoption.
Strategic Opportunities
- Eastern Uttar Pradesh penetration:Intensive dairy clusters in Gorakhpur and Varanasi divisions remain underserved by certified fodder seed distribution networks.
- Silage supply chain integration:Commercial dairies above 500-head capacity are contracting direct seed-to-silage procurement, bypassing traditional trader intermediaries.
- FSSAI feed safety alignment:Mycotoxin testing protocols for conserved fodder create preference for certified seed with traceable origin documentation.
Industry Challenges
- Seed pathology specialist scarcity:Qualified personnel for smut and rust screening are concentrated at ICAR centers, limiting private laboratory expansion.
- Multi-location trial timelines:CDSCO-style cultivar release protocols require three-year adaptive testing across agro-climatic zones before commercial notification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Forage Seed Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Legumes, Grasses, Brassicas, Others End Use Application: Livestock Feed, Silage Production, Erosion Control, Turf Establishment Packaging Type: Bags, Bulk Bags, Pallets, Containers Distribution Channel: Online Retail, Agro-input Stores, Distributors, Cooperatives |
| Companies Covered | Syngenta Group, Bayer AG, JK Agri Genetics Limited, Kaveri Seed Company, Rasi Seeds Pvt. Ltd., Advanta India Ltd., Kalash Seeds Pvt. Ltd., Mangalam Seeds Limited, Mahyco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Forage Seed Market Shifts & Advancements
Biomass measurement tools and digital traceability systems are restructuring how dairy cooperatives verify fodder quality, shifting procurement criteria from visual inspection to metabolite-verified contracts.
Near-infrared spectroscopy for crude protein and fiber quantification is decentralizing quality verification from centralized laboratories to cooperative collection centers. Gujarat dairy federations deploy portable NIR units at village procurement points, compressing testing turnaround from weeks to hours. This technology is decentralizing seed purchasing authority from district traders to cooperative technical staff who specify variety and certified origin.
FSSAI feed safety norms now mandate aflatoxin limits for conserved fodder entering commercial dairy supply chains. The regulation forces seed producers to document pre-harvest fungal resistance traits and post-harvest storage protocols. Alfalfa and fodder maize seed lots with certified low-mycotoxin genetics command price premiums in Maharashtra procurement tenders.
Cooperative procurement officers increasingly specify variety-specific silage performance in supply contracts rather than accepting generic fodder seed. This behavior compresses the trader-dominated spot market for uncertified seed in Haryana and Punjab dairy belts. Large herd operators in Ludhiana and Karnal districts now contract directly with seed processors for variety-identity-preserved lots with guaranteed dry matter digestibility.
India Forage Seed Market Segmentation
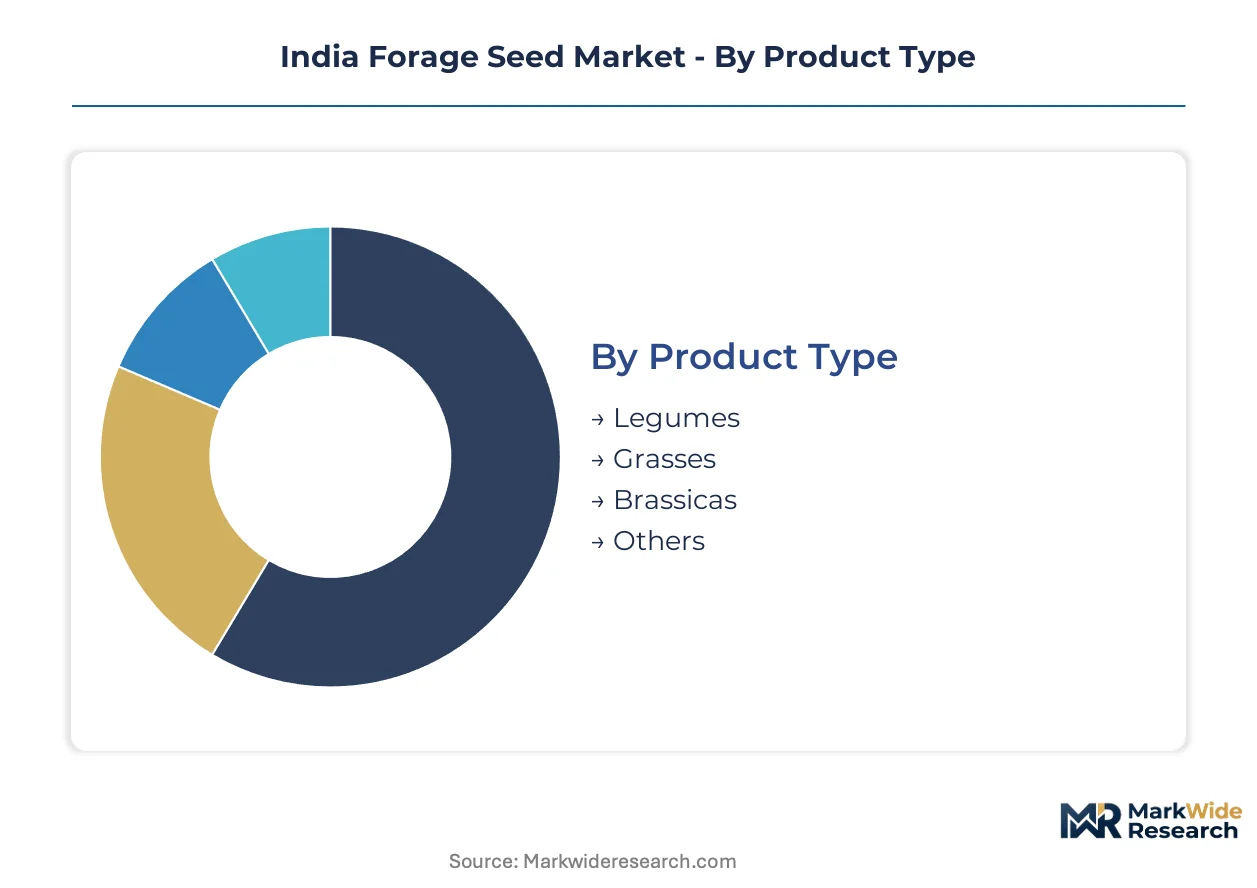
Segmentation in the India forage seed market reveals how procurement authority is fragmenting across traditional trader networks, cooperative technical staff, and direct processor contracts. Breeders must align variety portfolios with the divergent specifications of dairy federations, commercial dairies, and smallholder livestock operations.
Product Type:
Dairy ration formulation economics drive variety selection, with nitrogen fixation premiums and water-use efficiency commanding procurement prioritization.
- Legumes:Alfalfa and berseem clover fix atmospheric nitrogen, reducing synthetic fertilizer outlays for intensive dairy operations in Punjab and Haryana. Gujarat dairy federations specify certified legume seed in bulk supply contracts, pulling volume through organized channels with verified crude protein content.
- Grasses:Fodder sorghum and pearl millet dominate biomass throughput across silage supply chains, with drought-tolerant hybrids gaining preference in northwestern irrigation districts facing groundwater extraction restrictions.
- Brassicas:Winter-gap feeding systems in Uttar Pradesh deploy turnip and rape forage varieties where crude protein concentration justifies per-unit price premiums over conventional fodder.
- Others:Minor forage categories include chicory and plantain mixes for specialized grazing systems in Maharashtra cooperative programs.
Volume sits with Grasses; growth tilts toward Legumes.
End Use Application:
Application-specific performance requirements are compressing the uncertified seed spot market as buyers demand metabolite-verified contracts.
- Livestock Feed:Direct grazing and green fodder chopping systems in smallholder dairy operations across rainfed districts. Open grazing substitution limits delay commercial seed adoption where common pasture access persists.
- Silage Production:Commercial dairies above 500-head capacity in Ludhiana and Karnal districts contract direct seed-to-silage procurement, bypassing traditional trader intermediaries with variety-identity-preserved lots.
- Erosion Control:Watershed development programs in hilly regions of Himachal Pradesh and Uttarakhand specify deep-rooted forage grasses for slope stabilization.
- Turf Establishment:Sports ground and roadside landscaping applications in urban Maharashtra and Karnataka constitute a narrow niche with distinct quality specifications.
Procurement concentrates in Silage Production; expansion accelerates fastest in Livestock Feed as cooperative mandates penetrate underserved districts.
Packaging Type:
Scale of operation and storage infrastructure determine packaging economics, with bulk formats capturing organized channel volume.
- Bags:40-50 kg woven polypropylene units dominate smallholder retail through agro-input stores, with BIS certification labels mandatory for market access.
- Bulk Bags:One-ton flexible intermediate bulk containers serve dairy cooperative procurement, reducing handling costs and enabling traceable lot documentation for FSSAI compliance.
- Pallets:Unitized loads for large commercial dairy operations with mechanized handling capacity in Punjab and Haryana.
- Containers:Specialized climate-controlled bulk containers for high-value hybrid alfalfa seed with specific humidity requirements.
Unit economics favor Bulk Bags for organized procurement; Bags retain penetration in fragmented retail.
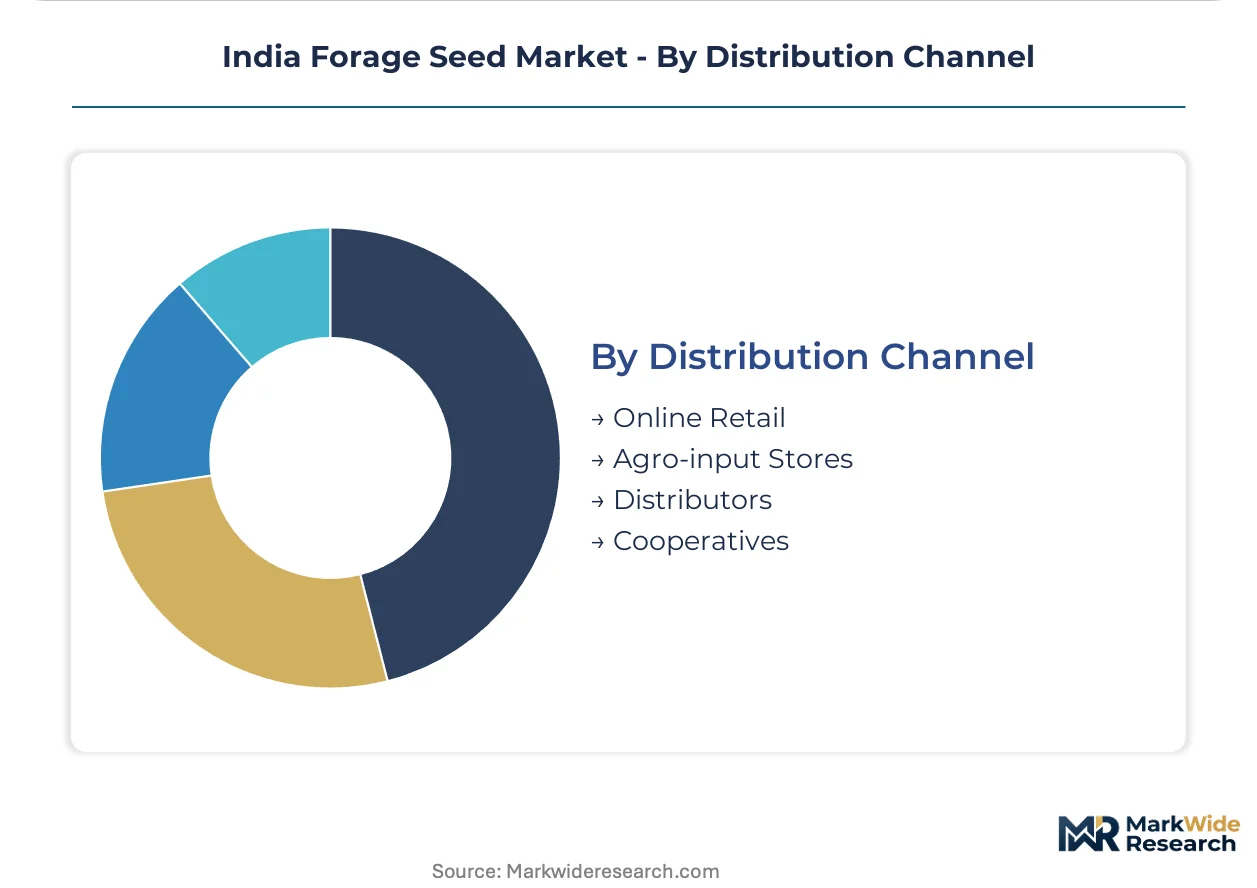
Distribution Channel:
Channel selection reflects the shifting locus of purchasing authority from district traders to cooperative technical staff and direct processor relationships.
- Online Retail:Emerging platform-based procurement for certified seed with origin documentation, accelerating in Maharashtra and Gujarat as digital literacy penetrates dairy cooperative networks.
- Agro-input Stores:Traditional village-level traders face margin compression as BIS certification mandates raise fixed cost barriers below 50-ton seed lots.
- Distributors:Regional stockists with certified multiplication infrastructure capture scale-player volume under PLI scheme incentives.
- Cooperatives:Gujarat and Maharashtra dairy federations deploy technical staff who specify variety and certified origin, displacing visual inspection-based procurement.
Transaction flow concentrates in Cooperatives; channel expansion is steepest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mega Food Parks and PLI-notified zones in Gujarat and Maharashtra concentrate organized procurement infrastructure, pulling certified seed volume through cooperative channels while informal trade persists in rainfed districts.
Punjab
Intensive dairy operations in Ludhiana and Patiala districts drive certified fodder seed consumption for silage production. State groundwater extraction restrictions favor drought-tolerant alfalfa varieties with higher biomass per liter applied. The Ludhiana-Karnal corridor hosts commercial dairies above 500-head capacity contracting directly with seed processors.
Haryana
High-density dairy clusters in Hisar and Karnal mandate certified seed in bulk supply contracts, displacing visual inspection-based procurement. BIS certification standards enforce laboratory testing for germination vigor, raising fixed cost barriers below 50-ton lots. The Karnal district anchors variety-identity-preserved procurement with guaranteed dry matter digestibility specifications.
Uttar Pradesh
Eastern divisions around Gorakhpur and Varanasi remain underserved by certified distribution networks despite intensive dairy concentration. Winter-gap feeding systems in western districts deploy brassica varieties where crude protein concentration justifies price premiums. The state agricultural universities control breeder seed release calendars, creating multiplication bottlenecks for private sector programs.
Gujarat
Dairy cooperatives specify certified fodder seed in procurement mandates, pulling volume through organized channels with verified crude protein content. Portable NIR spectroscopy units at village collection centers compress testing turnaround from weeks to hours. The Anand and Mehsana dairy federations deploy technical staff who specify variety and certified origin, displacing trader-dominated spot markets.
Maharashtra
Cooperative procurement officers specify variety-specific silage performance in supply contracts rather than accepting generic seed. FSSAI feed safety norms mandate aflatoxin limits for conserved fodder, forcing seed producers to document pre-harvest fungal resistance traits. The Pune-Nashik corridor concentrates commercial dairies contracting seed-to-silage procurement with traceable origin documentation.
India Forage Seed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around scale players with certified multiplication infrastructure, mid-tier regional stockists, and informal uncertified traders facing margin compression. Three archetypes dominate: global germplasm holders with premium hybrid lines, domestic breeders with region-specific portfolio depth, and cooperative-linked multipliers serving organized procurement channels. Competitive moves concentrate on backward integration into breeder seed access and cooperative partnership lock-ins.
Within the global germplasm tier, Syngenta Group and Bayer AG occupy positions anchored by molecular marker programs and disease-resistant variety pipelines. Kaveri Seed Company exemplifies the domestic specialist archetype with region-specific portfolio concentration. These three entities represent the competitive spectrum from multinational technology licensing to localized adaptive breeding, with each archetype responding differently to PLI scheme incentives and BIS certification mandates.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| JK Agri Genetics Limited |
| Kaveri Seed Company |
| Rasi Seeds Pvt. Ltd. |
| Advanta India Ltd. |
| Kalash Seeds Pvt. Ltd. |
| Mangalam Seeds Limited |
| Mahyco |
| Others |
Supply & Pricing Matrix
Alfalfa seed futures on the NCDEX commodity exchange cascade through certified multiplication chains into three distinct procurement tiers. Gujarat dairy cooperatives absorb premium-grade hybrid lots with guaranteed germination vigor, while Haryana spot traders liquidate uncertified inventory at compressed margins below BIS testing thresholds.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with Karnal processors paying 15-20% markups for variety-identity-preserved seed delivered within 72 hours of silage planting windows. Pricing stratifies across certified foundation, registered, and uncertified commercial tiers, with FSSAI traceability documentation commanding the widest spreads. Cost compression in the trader-dominated spot tier intensifies as cooperative procurement mandates displace visual inspection-based purchasing. Smallholder dairy operations in rainfed Uttar Pradesh districts exhibit highest price sensitivity, while 500-head commercial dairies in Ludhiana prioritize metabolite-verified contracts over per-kilogram rates.
Supply Chain Analysis
Regional distribution centers in Ahmedabad, Karnal, and Pune anchor hub-and-spoke patterns radiating toward cooperative collection points and commercial dairy clusters. Breeder seed supply concentrates at ICAR institutions in India, with foundation multiplication licensed to state agricultural universities and certified private operators. The chain draws from open-pollinated germplasm repositories, hybrid parent stock imports, and domestic R&D pipelines. Single-source vulnerability sits with ICAR-controlled cultivar release calendars, which constrain private sector multiplication timelines. Distribution runs through cooperative technical staff and direct processor contracts, bypassing traditional agro-input store networks in organized procurement zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS certification mandates and PLI scheme incentives are compressing margins for uncertified traders, forcing consolidation toward scale players with certified multiplication infrastructure.
For Market Incumbents: Deepen cooperative partnership lock-ins through embedded technical staff placements at Gujarat and Maharashtra dairy federations. Expand captive breeder seed access via long-term ICAR licensing agreements to secure cultivar release priority. Invest in portable NIR spectroscopy deployment at village collection centers to displace trader-dominated spot markets with metabolite-verified procurement protocols. For New Entrants and Emerging Players: Eastern Uttar Pradesh dairy clusters in Gorakhpur and Varanasi divisions offer penetrable white space with minimal certified seed distribution presence. Winter-gap brassica varieties for crude protein-concentrated feeding systems command price premiums with limited incumbent competition. Pursue direct seed-to-silage contracting models with 200-500 head commercial dairies seeking traceable origin documentation for FSSAI compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic breeders with region-specific portfolio depth in South Indian fodder markets and established state agricultural university relationships. Five-to-ten year viability hinges on adaptive breeding capabilities for drought-tolerance traits as groundwater extraction regulations tighten across northwestern irrigation districts. Monitor PLI scheme notification expansions for agriculture inputs as the inflection signal for scaled capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Multiplication Infrastructure Expansion | Captures PLI scheme incentives while raising barriers for uncertified traders below 50-ton lots. |
| Cooperative Technical Staff Embedding | Displaces visual inspection procurement with variety-specified, origin-verified contract terms at Gujarat federations. |
| Portable NIR Spectroscopy Deployment | Compresses crude protein testing turnaround from weeks to hours at Maharashtra village collection centers. |
| ICAR Breeder Seed Licensing Agreements | Secures cultivar release calendar priority and reduces multiplication bottlenecks for private programs. |
| Direct Seed-to-Silage Contracting | Bypasses trader intermediaries with guaranteed dry matter digestibility specifications for Haryana commercial dairies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with seed processing plant managers, dairy cooperative procurement officers, ICAR research directors, and FSSAI compliance auditors combined with BIS certification databases, CDSCO cultivar release notifications, and state agricultural university trial reports. Bottom-up variety-level volume estimates triangulated against top-down dairy herd size projections across the analysis window.
Data-stream reconciliation integrated product type segmentation by legume, grass, and brassica categories with end-use application splits across livestock feed, silage production, and erosion control. Distribution channel modeling captured cooperative, distributor, agro-input store, and online retail flows. CAGRs derived from acreage expansion rates, dairy cooperative procurement mandate penetration curves, and certified seed adoption thresholds. Groundwater extraction regulation scenarios and PLI scheme incentive trajectories informed sensitivity bounds.
Revisions become necessary when ICAR cultivar release calendars accelerate, FSSAI feed safety norms expand mycotoxin testing protocols, or drought-tolerance breeding targets shift under revised groundwater policy. Forecasts reflect documented assumptions on cooperative procurement mandate penetration and certified multiplication capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Vegetable Seed Market
Seeds
Africa Sorghum Seed Market
Seeds
Guar Market
Seeds
Global Grain Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Custom Selected Seed Market
Seeds
Avena Sativa Market
Seeds
Sweet Corn Seeds Market
Seeds
Russia Forage Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Africa Peas Market
Seeds
Citrus Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
Rapeseed Market
Seeds
Spain Forage Seed Market