
 Uganda Seeds Market | 2026-2036
Uganda Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Uganda Seeds Market Analytics
Uganda's National Seed Policy is consolidating demand around certified, traceable varieties that meet formal release standards. NASECO leverages its domestic breeding infrastructure to anchor supply across East African highland agro-ecologies. Equator Seeds competes through farmer-extension networks that sustain loyalty among smallholder cooperatives. Bayer Crop Science differentiates via trait integration in hybrid maize, occupying premium segments where drought tolerance commands channel preference.
Seeds are sexually or vegetatively propagated reproductive units containing embryonic plants, nutrient reserves, and protective coats, with germination rates, genetic purity, and moisture content defining commercial grade. Their primary purpose is to establish uniform, high-yielding crops that convert genetic potential into harvestable biomass. Hybrid seeds dominate value pools where yield premiums justify recurrent purchases, while open-pollinated varieties retain share among subsistence growers who practice on-farm seed saving. The agriculture end-use segment leads volume, though horticulture channels generate superior per-unit margins through specialized vegetable and flower seed lines.
The Uganda National Bureau of Standards enforces seed certification protocols that filter informal traders from regulated channels, while the Ministry of Agriculture's Seed Certification Service governs field inspection and labeling compliance. These frameworks elevate product standards but also raise capital barriers for new entrants seeking official variety registration. Stakeholders must monitor how pending amendments to plant variety protection law reshape royalty collection and farmer seed exchange rights.
Market Dynamics
Uganda's National Seed Policy is compressing informal seed channels while elevating certified variety standards, forcing capital investment into breeding infrastructure and traceability systems that smaller traders cannot match.
Growth Catalysts
- Variety Release Protocols:The National Seed Policy tightens field inspection and labeling requirements, filtering substandard seed from regulated channels and consolidating demand around certified suppliers with compliant breeding programs.
- Agro-Dealer Network Expansion:Central Region distribution hubs around Kampala are extending last-mile reach into Eastern and Western provinces, connecting smallholder cooperatives to formal input markets.
- Hybrid Maize Adoption:Drought-tolerant germplasm is displacing open-pollinated varieties in commercial farming zones where yield premiums justify recurrent seed purchases over farm-saved alternatives.
Market Restraints
- Capital Barriers:Official variety registration requires multi-year field trials and laboratory testing that exhausts capital reserves for emerging breeders lacking established revenue streams.
- Seed Saving Practices:Subsistence growers persist with on-farm retention of open-pollinated maize and bean varieties, constraining addressable market for certified hybrid products in remote districts.
- Input Cost Volatility:Fertilizer and crop protection chemical prices fluctuate with import exchange rates, compressing farmer budgets for complementary certified seed investments.
Strategic Opportunities
- Western Region Penetration:Underdeveloped seed processing infrastructure in districts bordering Rwanda and the Democratic Republic of Congo offers first-mover positioning for certified variety distribution.
- Digital Traceability Integration:Mobile-based seed authentication platforms are converging with agro-dealer inventory systems, enabling real-time variety verification and loyalty program enrollment.
- Horticulture Seed Lines:Specialized vegetable and flower germplasm generates superior per-unit margins compared to commodity grains, attracting breeding investment toward greenhouse and export-oriented production clusters.
Industry Challenges
- Field Inspection Backlogs:The Ministry of Agriculture's Seed Certification Service faces staffing constraints that delay variety release timelines, extending payback periods for research and development expenditures.
- Genetic Purity Maintenance:Isolation distance requirements for hybrid seed production compete with smallholder land fragmentation patterns, complicating contract grower network management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uganda Seeds Market |
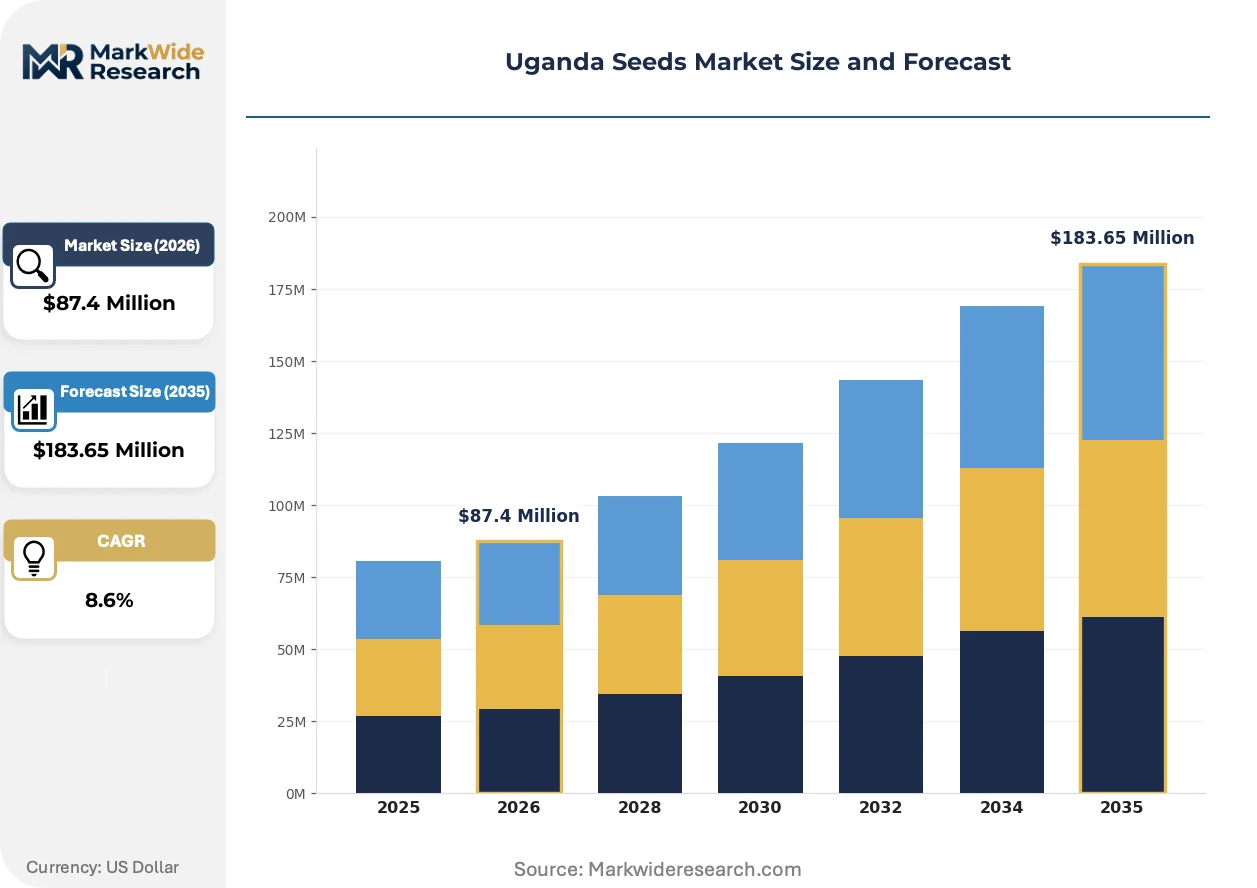
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Organic, Open-Pollinated, GMO End Use: Agriculture, Horticulture, Forestry, Home Gardening Packaging Type: Bags, Containers, Sachets, Bulk Distribution Channel: Retail, Wholesale, Online, Cooperatives |
| Companies Covered | NASECO, Equator Seeds, Bayer Crop Science, House of Seeds Uganda, Kenya Highland Seed, Corteva Agriscience, Seed Co International, Groupe Limagrain, Syngenta Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uganda Seeds Market Evolving Landscape
Digital verification tools and climate-adaptive breeding platforms are restructuring how genetic material reaches smallholder fields, compressing information asymmetries between formal seed systems and farmer knowledge networks.
Marker-assisted selection is expanding into drought tolerance screening for maize and beans, accelerating variety development cycles from eight years to five. NASECO and national agricultural research institutes are adopting these genomic tools to stack multiple stress tolerance traits. The technology is expanding into farmer participatory breeding programs that embed end-user preference data earlier in product design.
The Uganda National Bureau of Standards is enforcing seed certification protocols that mandate lot traceability and germination testing documentation. Industrial consequence includes elevated compliance costs that filter informal traders from regulated channels. Smallholder cooperatives in the Central Region are responding by consolidating procurement through certified agro-dealers with compliant inventory systems.
Agro-dealer loyalty programs are replacing transactional cash purchases with input credit bundled against harvest delivery commitments. The cooperative channel is being disrupted by mobile-enabled aggregator platforms that pre-qualify farmers for certified seed access. Eastern Region maize zones exhibit the most visible shift, where farmer groups now negotiate volume discounts through digital procurement collectives rather than individual retail visits.
Uganda Seeds Market Segmentation
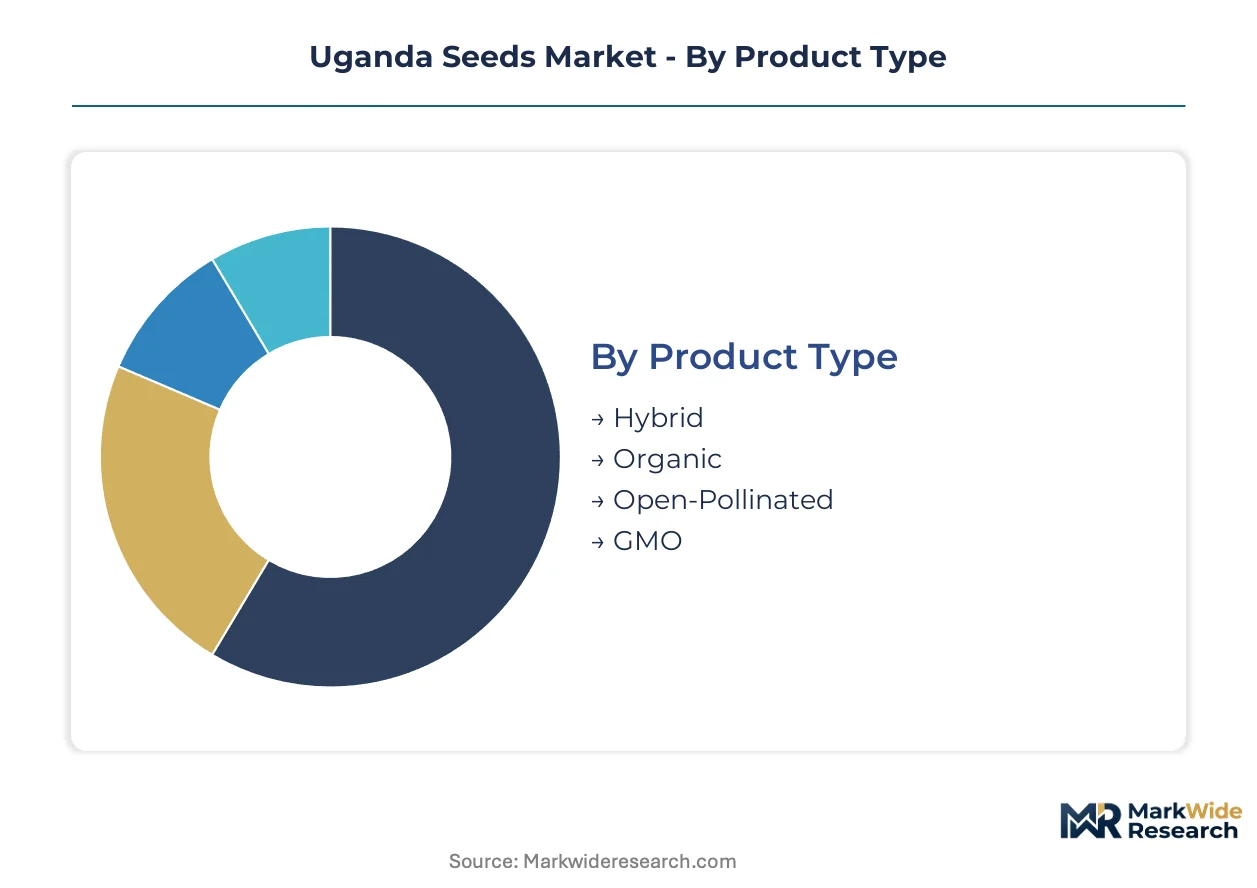
Seed purchasing decisions in Uganda track farmer scale, input budgets, and crop commercialization intensity. Segmentation reveals where certified hybrid premiums displace farm-saved alternatives and which channels capture smallholder loyalty.
Product Type:
Farmer investment capacity determines germplasm selection, with recurrent purchase behavior separating commercial growers from subsistence operators.
- Hybrid:Cross-pollinated varieties delivering 30-50% yield premiums over open-pollinated alternatives through heterosis effects. Demand concentrates in Central Region maize zones where agro-dealer networks finance input packages against harvest delivery.
- Open-Pollinated:Self-fertile varieties allowing on-farm seed saving across generations, retaining genetic stability sufficient for subsistence production. Dominates in remote Western districts where certified seed distribution infrastructure remains sparse and farmer liquidity constraints persist.
- Organic:Germplasm produced without synthetic chemical inputs, certified under national organic standards for export-oriented producer groups.
- GMO:Trait-enhanced varieties incorporating insect resistance or herbicide tolerance, pending regulatory approval under Uganda's National Biosafety Act.
Volume sits with Open-Pollinated; growth tilts toward Hybrid.
End Use:
Commercial intensity and per-unit margin potential segment demand across cultivation systems.
- Agriculture:Field crop establishment for maize, beans, sorghum, and millet production, consuming over 80% of certified seed volume. Procurement runs through cooperative aggregators in Eastern Region zones where farmer groups negotiate volume discounts.
- Horticulture:Specialized vegetable and flower germplasm for greenhouse and open-field production, generating 3-4x per-kilogram margins versus commodity grains. Concentrates around Kampala-Entebbe corridor export clusters.
- Forestry:Tree seed and vegetative propagation material for plantation establishment and agroforestry systems.
- Home Gardening:Small-volume retail packets for urban and peri-urban household consumption.
Agriculture dominates volume; horticulture commands margin expansion.
Packaging Type:
Scale of operation and storage infrastructure shape packaging preferences across the value chain.
- Bags:Woven polypropylene containers holding 2kg to 50kg of seed, standard for commercial farm procurement through agro-dealer networks.
- Sachets:Laminated foil packets of 10g to 500g, enabling affordable access for smallholders purchasing single-crop units. Demand clusters in Central Region peri-urban markets where retail fragmentation requires unitized pricing.
- Containers:Rigid plastic or metal vessels for high-value horticulture germplasm requiring moisture protection.
- Bulk:Loose seed in unbranded quantities, primarily informal channel retention for open-pollinated varieties.
Bags carry institutional volume; sachets penetrate smallholder fragmentation.
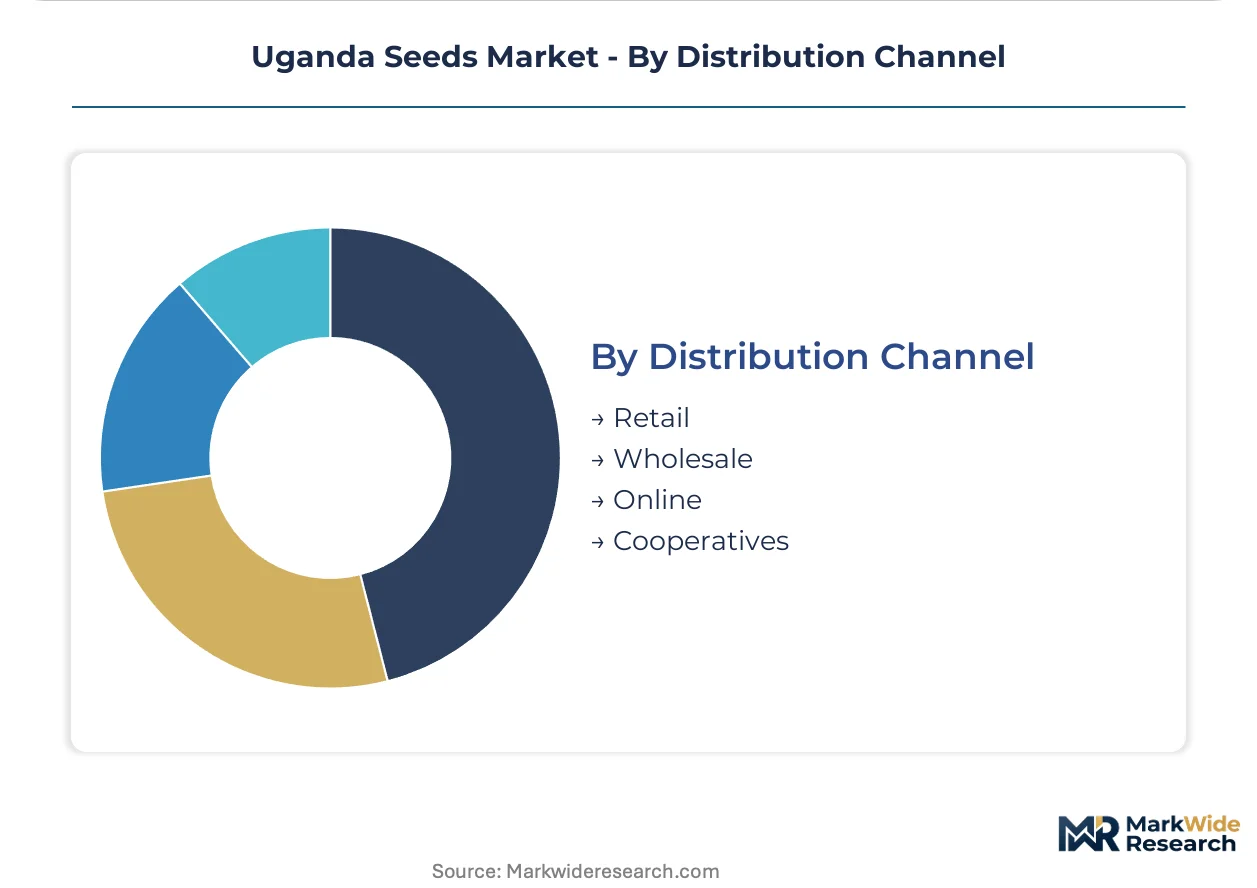
Distribution Channel:
Trust mechanisms and credit access determine channel selection among farmer segments.
- Cooperatives:Member-based procurement aggregating demand for certified seed with input credit bundling. Eastern Region maize cooperatives now pre-qualify farmers through mobile-enabled platforms.
- Retail:Agro-dealer shops providing last-mile access with variety verification and technical advice. Central Region density around Kampala supports 72-hour restocking from processing facilities.
- Wholesale:Volume transactions to institutional buyers and larger commercial farms, bypassing retail markup.
- Online:Mobile-commerce platforms emerging for input ordering with agro-dealer pickup or direct delivery.
Cooperatives consolidate smallholder demand; retail captures commercial farm autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kampala anchors Uganda's seed distribution architecture, hosting the densest concentration of agro-dealer networks and seed processing facilities that feed certified varieties into surrounding agricultural zones.
Central Region
Hybrid maize procurement concentrates around Kampala-Entebbe corridor agro-dealers, where farmer cooperatives negotiate volume discounts against harvest delivery commitments. The Uganda National Bureau of Standards enforces seed certification protocols that filter informal traders from regulated channels. Wakiso and Mukono districts host processing facilities that restock retail networks within 72-hour cycles.
Eastern Region
Maize cooperatives in Mbale and Soroti districts are shifting procurement through mobile-enabled aggregator platforms that pre-qualify farmers for certified seed access. The Ministry of Agriculture's Seed Certification Service governs field inspection compliance for varieties entering formal distribution. Iganga district exhibits the most visible digital procurement collective formation.
Western Region
Underdeveloped seed processing infrastructure in districts bordering Rwanda and the Democratic Republic of Congo constrains certified variety penetration among smallholders who retain open-pollinated seed saving practices. The National Seed Policy's variety release protocols raise capital barriers for emerging breeders lacking established revenue streams. Kasese and Fort Portal sub-regions offer first-mover positioning for distribution network expansion.
Northern Region
Post-conflict agricultural recovery in Gulu and Lira districts is expanding addressable demand for certified sorghum and bean varieties among returning farmer populations. The Ministry of Agriculture's extension services coordinate variety demonstrations that build trust in formal seed systems. Agro-dealer density remains sparse compared to Central Region benchmarks.
Uganda Seeds Market Competitive Landscape
The competitive structure tilts toward domestic breeding specialists with established variety portfolios and multinational trait integrators occupying premium hybrid segments. Capital requirements for official variety registration compress the field to entities with multi-year revenue streams or parent company backing. Two strategic archetypes dominate: domestic breeders leveraging local adaptation knowledge and global agrochemical conglomerates bundling seed with crop protection inputs. Competitive moves center on agro-dealer network expansion and digital traceability platform integration.
Among domestic specialists, NASECO and Equator Seeds exemplify contrasting channel strategies. NASECO anchors supply across East African highland agro-ecologies through breeding infrastructure concentrated in Uganda. Equator Seeds occupies a position within farmer-extension networks that sustain loyalty among smallholder cooperatives. Bayer Crop Science represents the multinational archetype, differentiating through trait integration in hybrid maize where drought tolerance commands channel preference in commercial farming zones.
| Leading Market Players |
|---|
| NASECO |
| Equator Seeds |
| Bayer Crop Science |
| House of Seeds Uganda |
| Kenya Highland Seed |
| Corteva Agriscience |
| Seed Co International |
| Groupe Limagrain |
| Syngenta Group |
| Others |
Value Network & Pricing Analysis
Smallholder cooperative procurement consolidation in the Eastern Region is compressing retail margins and forcing suppliers toward volume-based contract structures that sacrifice per-unit premiums for guaranteed offtake. Uganda's National Seed Policy tightens certification requirements that raise fixed compliance costs, pushing pricing power toward breeders with established laboratory infrastructure and field inspection relationships.
Pricing Analysis
Yield-based value anchoring dominates hybrid maize transactions, where drought-tolerant germplasm commands recurrent purchase premiums over farm-saved alternatives. Three-tier pricing structure across certified hybrid, open-pollinated, and informal saved seed segments reflects germplasm purity and traceability documentation. Cost compression in open-pollinated tiers is intensifying because agro-dealer networks consolidate procurement around certified suppliers. Subsistence growers in Western districts exhibit highest price sensitivity, while commercial maize cooperatives in Central Region zones accept premium positioning for trait-integrated varieties.
Supply Chain Analysis
Parent stock supply rests on proprietary breeding programs concentrated in Uganda, Kenya, and South Africa, with germplasm licensing agreements tethering local multipliers to multinational trait portfolios. Hybrid seed production draws from specialized isolation fields, laboratory testing services, and moisture-controlled storage infrastructure. Single-source vulnerability concentrates in parent line imports subject to phytosanitary clearance delays. Distribution runs through agro-dealer networks with 72-hour restocking cycles from Kampala-anchored processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uganda's National Seed Policy erects a cost-of-compliance barrier that filters informal traders and consolidates returns around certified breeders with multi-year field trial capabilities and laboratory testing infrastructure.
For Market Incumbents: Acquire contract grower networks in Western Region districts bordering Rwanda to preempt first-mover positioning by emerging competitors. Integrate mobile-based seed authentication platforms with agro-dealer inventory systems to deepen channel control against cooperative-led procurement collectives. Defensive positioning requires isolating hybrid parent stock production from smallholder land fragmentation patterns that threaten genetic purity compliance. For New Entrants and Emerging Players: Uganda's pending amendments to plant variety protection law open a window for royalty-collection specialization in horticulture germplasm segments where per-unit margins exceed commodity grain benchmarks. White-space concentration sits in greenhouse vegetable seed lines for Kampala-Entebbe export clusters and in digital procurement platforms for Eastern Region maize cooperatives. Go-to-market execution should anchor through mobile-enabled aggregator partnerships rather than brick-and-mortar agro-dealer buildout. For Investors and Strategic Acquirers: The window for entry favors domestic breeding specialists with established variety portfolios and compliant field inspection track records. Long-term viability hinges on regulatory moat sustainability under tightening National Seed Policy enforcement. Watch for Ministry of Agriculture staffing expansion in Seed Certification Service as inflection signal for variety release timeline compression and R&D payback period improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Parent Stock Capacity Expansion | Captures yield premium demand in Central Region maize zones where drought tolerance commands channel preference. |
| Mobile Traceability Platform Integration | Enables real-time variety verification that satisfies Uganda National Bureau of Standards lot documentation mandates. |
| Horticulture Germplasm Portfolio Buildout | Targets 3-4x margin expansion in Kampala-Entebbe corridor greenhouse and export-oriented production clusters. |
| Western Region Distribution Network Establishment | Secures first-mover positioning in Kasese and Fort Portal sub-regions with underdeveloped seed processing infrastructure. |
| Cooperative Procurement Collective Partnership | Aligns with Eastern Region maize cooperative shift toward mobile-enabled aggregator platforms for certified seed access. |
Research Methodology
Uganda National Bureau of Standards certification records, Ministry of Agriculture Seed Certification Service field inspection reports, and East African Community trade flow databases formed the secondary backbone for supply-side validation. Primary interviews with seed company breeding directors, agro-dealer network managers, cooperative procurement officers, and smallholder cooperative leaders combined with secondary triangulation to calibrate adoption rates and pricing dynamics. Bottom-up variety registration timelines and top-down agricultural input expenditure patterns were reconciled to anchor volume estimates.
Bottom-up modeling tracked certified seed offtake through agro-dealer networks and cooperative channels across hybrid, open-pollinated, and organic product tiers. Top-down validation referenced national agricultural input surveys and seed industry association membership data. Segmentation dimensions included product type, end-use agriculture versus horticulture, packaging format, and distribution channel structure. CAGRs were derived from trend extrapolation of certified seed adoption rates and hybrid penetration patterns across the projection horizon, with specific inputs from drought tolerance trait diffusion curves and digital procurement platform enrollment trajectories.
The model assumes a particular technology adoption path; alternative pathways for marker-assisted selection acceleration would alter the outlook if genomic tools compress variety development cycles below current five-year benchmarks. Forecasts reflect assumptions about National Seed Policy enforcement continuity, phytosanitary clearance efficiency for parent stock imports, and cooperative procurement collective formation velocity. A small set of triggers warrants ongoing watch: Seed Certification Service staffing levels, plant variety protection law amendment passage, and mobile platform penetration rates in Eastern Region maize zones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Drought Tolerant Seeds Market
Seeds
China Forage Seed Market
Seeds
Global Sorghum Seed Market
Seeds
Grass Seed Market
Seeds
Punnet Market
Seeds
United States Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
United States Forage Seed Market
Seeds
Watermelon Seeds Market
Seeds
Global Maize Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Global Sunflower Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Seed Cracker Market
Seeds
Cowpeas Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market