
 Global Oilseed Market | 2026-2036
Global Oilseed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oilseed Market Outlook
Plant-based protein demand from food manufacturers is broadening the end-use vertical mix for oilseed processors. Archer Daniels Midland Company leverages its North American crushing footprint to supply both food-grade oils and high-protein meal fractions. Cargill sustains origination dominance across Brazilian soybean belts through integrated logistics and farmer financing programs. Bunge Limited anchors its margin profile in oil refining and specialty lecithin extraction for industrial food applications.
Oilseeds comprise the dried seeds of cultivated plants—principally soybeans, canola, sunflower, and peanuts—typically containing 18–45% oil by weight and 16–42% protein, extracted through mechanical pressing or solvent extraction using hexane. These commodities serve as the foundational input for edible oils, protein meal for livestock rations, and increasingly for renewable diesel and biodiesel feedstocks. Soybean crushing dominates volume flows, with meal co-product capturing the majority of value in animal nutrition channels while oil fractions command premium pricing in food processing and biofuel applications. Canola maintains structural advantages in cold-press food oil segments across North American and European markets, whereas peanut oil occupies niche positions in high-heat culinary and cosmetic formulations.
The United States Department of Agriculture sets grading standards and oil content minimums that directly determine export eligibility and price premiums for domestic soybeans and sunflower seeds. Brazil's national biosafety regulator, CTNBio, governs genetically modified seed approvals that shape varietal planting decisions across the Cerrado and Matopiba expansion zones. The European Union's F-Gas Regulation and Renewable Energy Directive II constrain conventional biofuel pathways while creating preferential demand for waste and residue-based feedstocks. Stakeholders must monitor evolving low-carbon fuel standards in California, Brazil, and the EU, as certificate premiums increasingly separate compliant from conventional oilseed supply chains.
Market Dynamics
Renewable diesel capacity expansion across the US Gulf Coast and EU North Sea ports is structurally redirecting soybean and rapeseed oil flows away from food processing into fuel feedstock channels, compressing food-grade oil premiums while elevating oilseed crush margins.
Growth Catalysts
- California LCFS certificate premiums:Low-carbon fuel standard credits now trade at sufficient value to offset the feedstock cost gap between virgin vegetable oils and waste fats, pulling additional soybean crush capacity toward renewable diesel offtake.
- Indonesia B35 biodiesel mandate:The Ministry of Energy and Mineral Resources raised blending requirements to 35% palm-based biodiesel, locking in domestic palm oil absorption and tightening global vegetable oil balances.
- Precision fermentation:Microbial protein platforms are automating alternative protein production, creating complementary demand for high-oleic oilseed fractions as fermentation feedstock carriers.
Market Restraints
- Matopiba logistics bottlenecks:Brazilian soybean expansion into the MATOPIBA frontier (Maranhão, Tocantins, Piauí, Bahia) confronts inadequate rail and port infrastructure, concentrating export dependence on Santos and Paranaguá.
- EU F-Gas Regulation constraints:Fluorinated greenhouse gas phase-down schedules limit solvent recovery system designs in hexane-based oil extraction facilities, elevating capex for European crush operators.
- Canola clubroot resistance cycles:Pathogen races are outpacing varietal resistance breeding in Canadian Prairie provinces, threatening yield stability in the dominant export origin.
Strategic Opportunities
- India oilseed self-sufficiency targets:The National Mission on Edible Oils–Oil Palm (NMEO-OP) subsidizes palm oil cultivation in Northeastern states and Andaman Islands, creating origination infrastructure gaps for private investment.
- Blockchain-enabled provenance verification:Distributed ledger systems are converging with satellite imagery to automate deforestation-free certification, unlocking EU Renewable Energy Directive II compliance premiums for Brazilian soy exporters.
- Specialty lecithin fractionation:Phospholipid separation for pharmaceutical and cosmetic emulsifier markets commands 3-4x commodity lecithin pricing, rewarding solvent extraction technology upgrades.
Industry Challenges
- Hexane emission control engineering:US EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) compliance requires continuous monitoring system installation, stretching maintenance technician availability across Midwest crush facilities.
- Non-GMO IP segregation:Identity preservation from farm gate to export elevator demands dedicated storage and transport infrastructure, elevating working capital intensity for organic and non-GMO supply chain participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oilseed Market |
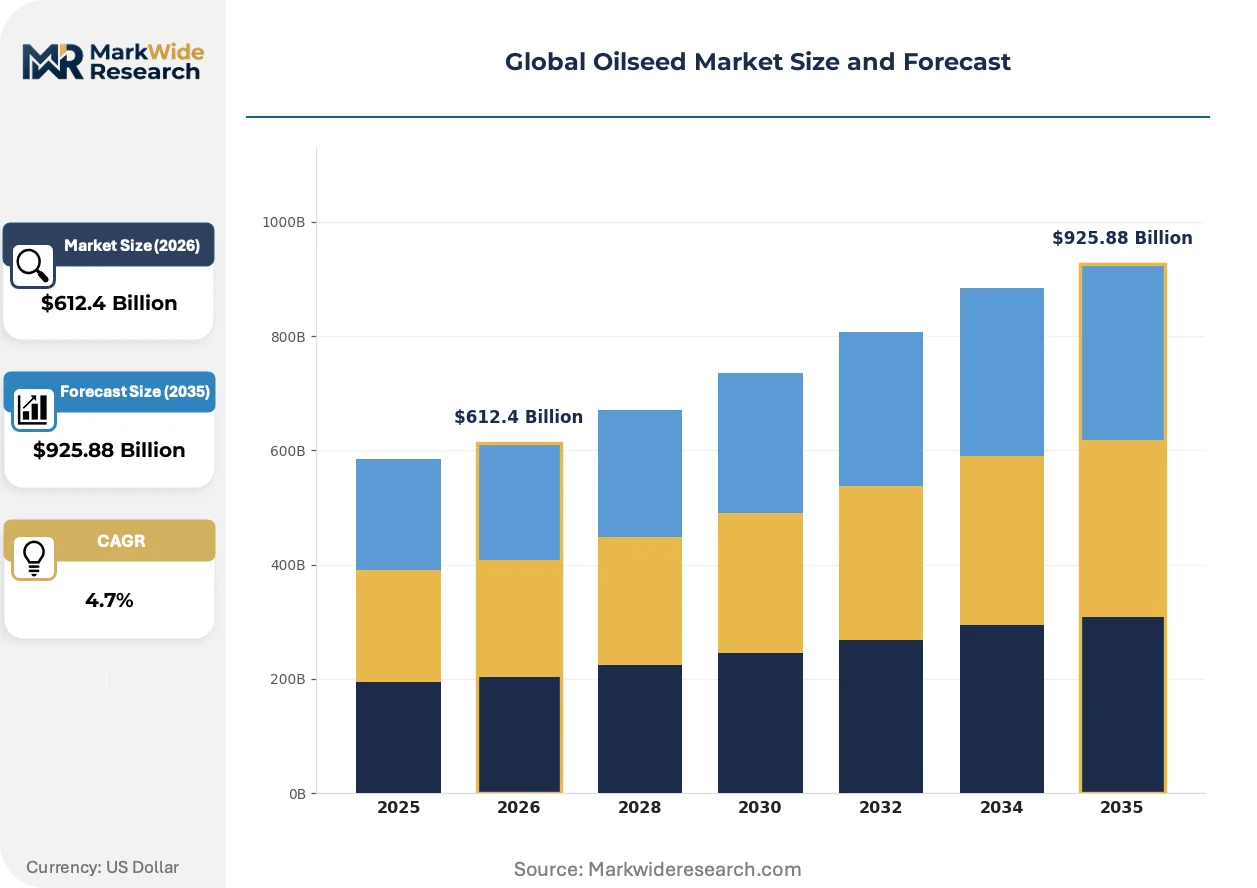
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $925.88 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybeans, Canola, Sunflower, Peanut End Use Industry: Food Processing, Biofuels, Animal Feed, Cosmetics Form: Oil, Meal, Whole Seeds, By-products Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce |
| Companies Covered | Archer Daniels Midland Company, Cargill, Bunge Limited, Wilmar International Limited, Louis Dreyfus Company, CHS Inc., Olam International, Ag Processing Inc., Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oilseed Market Strategic Shifts
Digitalization of crush margin optimization and the convergence of biofuel policy with agricultural commodity markets are restructuring how oilseed processors allocate capacity between food, feed, and fuel channels.
Near-infrared spectroscopy integrated with automated sampling systems is automating real-time oil and protein content measurement at grain elevator intake points. Large-scale handlers in Iowa and Illinois are deploying these platforms to reduce laboratory testing delays from hours to minutes. The compression of quality assessment timelines is enabling dynamic pricing adjustments that align farmer deliveries with crush schedule optimization.
The EU Renewable Energy Directive II sustainability criteria are disqualifying palm oil linked to high indirect land-use change risk from counting toward renewable transport targets. This regulatory exclusion is redirecting European biodiesel feedstock procurement toward used cooking oil and animal fats, tightening the competitive set for oilseed oil displacement. German and Dutch refiners are responding with hydroprocessed ester and fatty acid (HEFA) pathway investments calibrated to waste feedstock specifications.
Food manufacturers are consolidating supplier relationships around certified sustainable sourcing programs that bundle carbon intensity scoring with deforestation-free verification. This buyer concentration is displacing spot-market procurement for premium oil fractions in Northern European and North American packaged food channels. Nestlé and Unilever procurement specifications now mandate mass-balance certification through Roundtable on Sustainable Soy (RTRS) or ProTerra standards, compressing uncertified origin price premiums.
Global Oilseed Market Segmentation
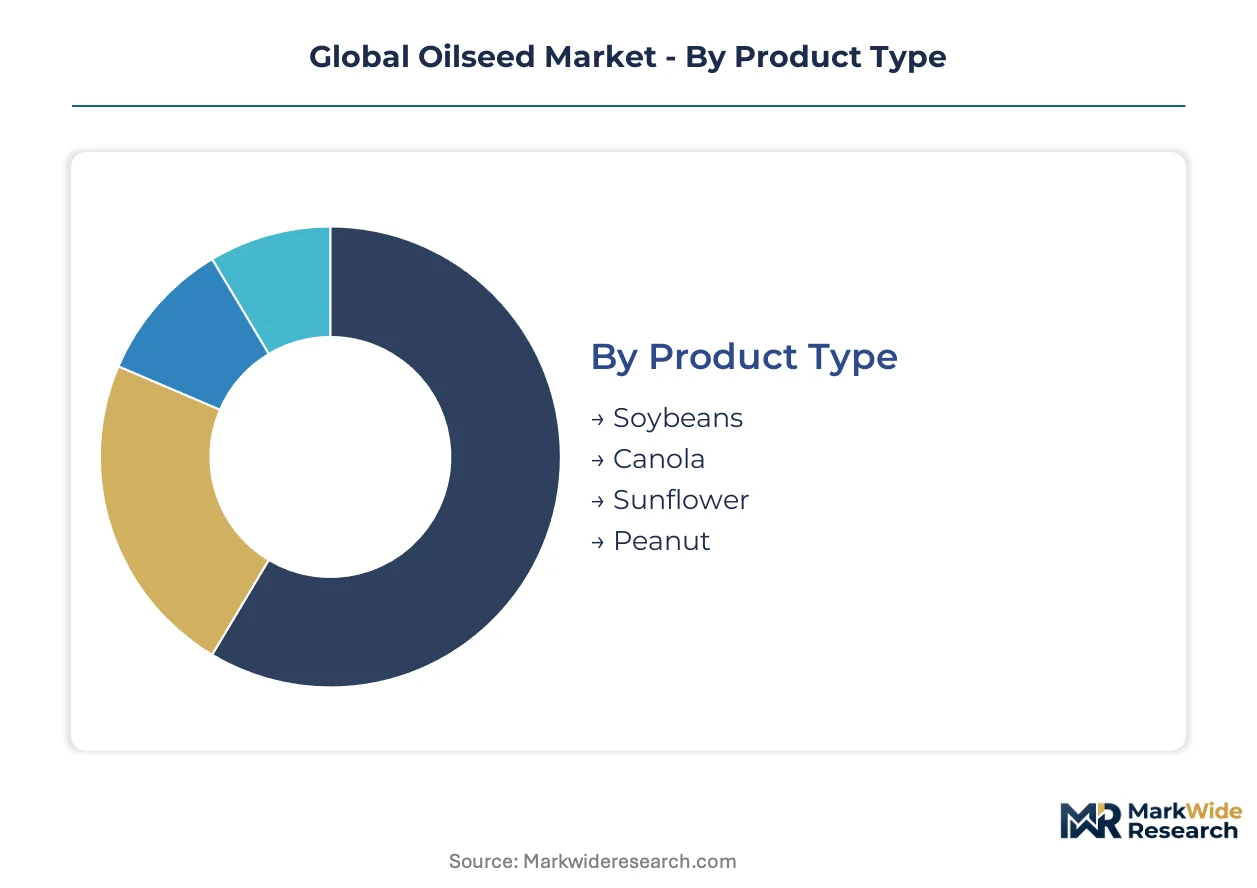
Oilseed segmentation reveals how crush economics allocate capacity between food, feed, and fuel channels. Product type and end-use splits determine margin capture across processing networks.
Product Type:
Volume concentration versus premium positioning splits the competitive map across origins and crush configurations.
- Soybeans:Containing 18-22% oil and 38-42% protein by weight, soybeans dominate crush volume flows worldwide. Demand concentrates in US Gulf Coast and Brazilian Santos corridor export channels, where renewable diesel offtake is redirecting oil fractions away from food processing.
- Canola:Rapeseed varieties bred for low erucic acid content carry 40-45% oil with superior cold-press food oil characteristics. Premium pricing anchors in North American and European food manufacturing, though EU F-Gas Regulation compliance costs constrain crush expansion.
- Sunflower:High-oleic varieties serve confectionery and frying oil segments with oxidative stability advantages.
- Peanut:Niche positioning in high-heat culinary applications and cosmetic emulsifier markets commands specialty premiums.
Mature deployment sits with soybeans. Newer deployment is concentrated in high-oleic sunflower and specialty peanut fractions.
End Use Industry:
Application-driven margin structures separate commodity-scale operations from specialty extraction facilities.
- Food Processing:Refined, bleached, and deodorized oils for packaged foods and foodservice channels require identity preservation and contaminant controls. Nestlé and Unilever procurement mandates now enforce mass-balance certification through RTRS or ProTerra standards, compressing uncertified origin premiums.
- Animal Feed:Soybean meal captures 60-70% of crush value in protein-deficient regions, with formulation demand tracking livestock herd cycles in Vietnam and Bangladesh.
- Biofuels:Renewable diesel capacity expansion across US Gulf Coast and EU North Sea ports is elevating oilseed crush margins while compressing food-grade oil premiums.
- Cosmetics:Phospholipid separation for pharmaceutical and cosmetic emulsifier markets commands multiple premiums over commodity lecithin.
Feed and food applications represent established volume anchors. Biofuels deployment is expanding most quickly across crush capacity additions.
Form:
Processing depth determines value capture and working capital intensity across the supply chain.
- Oil:Crude degummed oil for refining and biodiesel feedstock channels moves in bulk vessel parcels.
- Meal:High-protein soybean meal fractions serve aquaculture and poultry ration formulation, with amino acid profiles determining regional substitution patterns.
- Whole Seeds:Identity-preserved non-GMO and organic seeds command segregation premiums through dedicated storage infrastructure.
- By-products:Lecithin, fatty acid distillates, and hull fractions generate incremental crush margin recovery.
Meal and oil fractions dominate mature processing economics. Whole seed identity preservation is climbing fastest among premium channel participants.
Distribution Channel:
Channel selection reflects buyer scale, certification requirements, and price discovery mechanisms.
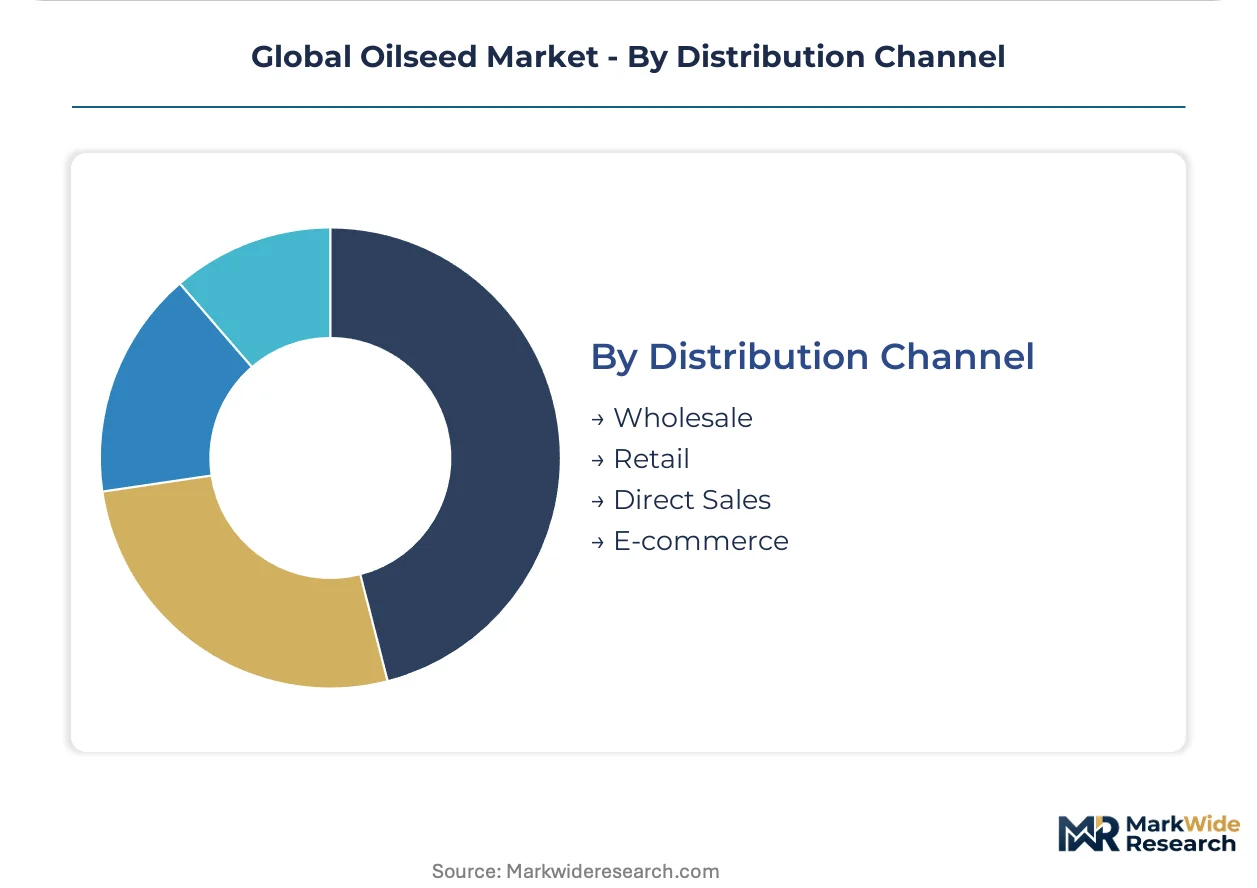
- Wholesale:Bulk vessel and railcar movements serve crush facilities and integrated processors with forward contracting frameworks.
- Retail:Branded bottled oils and packaged seeds reach consumers through supermarket and convenience store networks.
- Direct Sales:Processor-to-manufacturer relationships lock in volume commitments for certified sustainable sourcing programs.
- E-commerce:Specialty and organic oilseed products reach small-scale food manufacturers and direct consumers through platform marketplaces.
Wholesale channels anchor volume flows. Direct sales certification-linked contracts are gaining share fastest among sustainability-mandated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Gulf Coast special economic zones for biofuel processing are concentrating oilseed crush capacity expansion. Brazil's MATOPIBA frontier and Indonesia's palm oil belt anchor origination growth. European sustainability mandates reshape import flows.
United States
Renewable diesel offtake from Gulf Coast refineries is redirecting soybean oil away from food channels. California LCFS certificate premiums now offset feedstock cost differentials for compliant crush operators. Iowa and Illinois elevator networks deploy near-infrared spectroscopy for real-time quality assessment.
Brazil
Santos corridor export capacity anchors global soybean trade flows. CTNBio governs genetically modified seed approvals shaping varietal planting across Cerrado expansion zones. MATOPIBA frontier states confront rail and port bottlenecks concentrating dependence on Paranaguá.
Indonesia
B35 biodiesel mandates lock in domestic palm oil absorption at 35% blending rates. Ministry of Energy and Mineral Resources procurement rules tighten global vegetable oil balances. Sumatra and Kalimantan plantation belts supply feedstock for national mandate fulfillment.
Germany
HEFA pathway investments calibrate to waste feedstock specifications under EU Renewable Energy Directive II. ECHA REACH compliance and F-Gas Regulation phase-down schedules constrain solvent recovery system designs. Hamburg and Rotterdam port clusters handle rapeseed oil flows for North Sea renewable fuel capacity.
India
NMEO-OP subsidies for palm oil cultivation in Northeastern states and Andaman Islands target import substitution. FSSAI food safety standards govern edible oil refining and packaging specifications. Gujarat and Maharashtra processing hubs expand solvent extraction capacity for domestic oilseed supplies.
Global Oilseed Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated trading houses commanding origination-to-processing networks while regional crushers compete on logistics proximity. The vendor base concentrates among agricultural commodity conglomerates with captive farmer financing programs and elevator assets. Three archetypes dominate: global traders with crush assets, regional cooperatives with origination lock-in, and equipment suppliers with extraction technology licensing. Competitive moves center on renewable diesel offtake contracting and blockchain-enabled provenance verification for EU compliance premiums.
Among North American integrated processors, Archer Daniels Midland Company and Cargill represent the trader-crusher archetype with elevator network control. Bunge Limited occupies a position exemplifying oil refining and specialty fractionation focus. These entities anchor the competitive map through origination infrastructure rather than product differentiation alone.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Bunge Limited |
| Wilmar International Limited |
| Louis Dreyfus Company |
| CHS Inc. |
| Olam International |
| Ag Processing Inc. |
| Bühler Group |
| Others |
Value Chain & Pricing Dynamics
Hexane solvent costs cascade through crush margin calculations, compressing returns for European operators facing EU F-Gas Regulation compliance while elevating premiums for US Gulf Coast facilities with renewable diesel offtake contracts.
Pricing Analysis
Short lead-time premiums now separate spot soybean meal deliveries from contracted crush schedules across Brazilian Santos corridor exports. Three-tier pricing structure across certified sustainable, conventional commodity, and uncertified spot grades reflects EU Renewable Energy Directive II compliance requirements. Pricing pressure stems from renewable diesel capacity absorption of food-grade oil fractions, tightening margins for pure-play food processors. Animal feed compounders in Vietnam and Bangladesh exhibit highest price sensitivity, while Nestlé and Unilever procurement teams absorb certification premiums for mass-balance verified supply chains.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian Santos and Paranaguá port clusters, where MATOPIBA frontier expansion concentrates export dependence on inadequate rail capacity. Supply draws from United States, Brazil, and Argentina for soybean origination; Canada and Australia for canola; Indonesia and Malaysia for palm oil. Tariff exposure runs through EU-Indonesia biodiesel trade disputes and US-China oilseed tariff schedules. Distribution runs through bulk vessel charters for crush facilities, with blockchain-enabled provenance verification emerging for certified sustainable channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around crush capacity scale and renewable diesel offtake contracting, with California LCFS certificate economics forcing sub-scale processors toward exit or acquisition.
For Market Incumbents: Deploy blockchain-enabled provenance verification to capture EU Renewable Energy Directive II compliance premiums for Brazilian soy exports. Anchor crush margin defense through long-term renewable diesel offtake contracts with US Gulf Coast refineries, while CTNBio regulatory engagement secures genetically modified seed approval pipelines for Cerrado expansion zones. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and Netherlands opens a window for solvent recovery system technology licensing to European crush operators facing capex constraints. Target India's NMEO-OP subsidized palm oil cultivation zones for origination infrastructure investment, with FSSAI food safety compliance as the entry credential for domestic refining partnerships. For Investors and Strategic Acquirers: California LCFS certificate price inflection is the leading indicator that renewable diesel feedstock demand is structurally outpacing crush capacity additions. Long-term viability favors integrated trader-crushers with captive elevator networks and farmer financing programs. Watch for MATOPIBA logistics bottleneck resolution announcements as the signal for Brazilian origination capacity scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Offtake Contracting | Locks in crush margin premiums through California LCFS certificate value capture. |
| Blockchain Provenance Verification Deployment | Automates EU Renewable Energy Directive II compliance for Brazilian soy exporters. |
| HEFA Pathway Capacity Investment | Calibrates German and Dutch refining assets to waste feedstock specifications. |
| Specialty Lecithin Fractionation Upgrade | Captures pharmaceutical and cosmetic emulsifier premiums through solvent extraction technology. |
| NMEO-OP Zone Origination Infrastructure | Positions for India's palm oil self-sufficiency targets in Northeastern states. |
Study Parameters
Multi-period observation of crush margin spreads, renewable diesel capacity additions, and EU certificate pricing anchored the trend analysis, supplemented by interviews with crush facility operations managers, commodity trading desk heads, sustainability certification auditors, and biodiesel refinery procurement leads. Secondary validation drew from USDA crop reports, EIA biofuel production data, EU Renewable Energy Directive II implementation documents, and CTNBio regulatory filings. Bottom-up crush capacity modeling triangulated against top-down oilseed consumption forecasts.
Input-output matrices mapped soybean, canola, and sunflower flows across product type, end-use industry, and distribution channel dimensions over the projection horizon. CAGRs derived from regression analysis against biofuel policy adoption curves and livestock feed formulation demand. Industry-specific forecast inputs included California LCFS credit price trajectories and Indonesia B35 mandate enforcement schedules.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation protein platforms would alter the outlook for high-oleic oilseed fraction demand. Forecasts reflect assumptions around EU sustainability criteria enforcement and US renewable diesel tax credit continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
China Seed Market
Seeds
North America Vegetable Seed Market
Seeds
Russia Seed Market
Seeds
Rapeseed Market
Seeds
Avena Sativa Market
Seeds
Myanmar Rice Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
Europe Flaxseeds Market
Seeds
Buckwheat Market
Seeds
Sesame Seeds Market
Seeds
Europe Seed Market
Seeds
Apple Seed Oil Market
Seeds
India Rice Seed Market
Seeds
Global Maize Seed Market