
 North America Maize Market | 2026-2036
North America Maize Market Size, Share, and Industry Trends Forecast 2026-2036
North America Maize Market Analytics
The capital-intensity divergence between integrated seed-to-protein conglomerates and specialized biotech input providers is bifurcating competitive dynamics across the North America maize value chain. BASF leverages its crop protection chemistry portfolio to lock in farmer loyalty through bundled input programs. Corteva Agriscience anchors its position through proprietary germplasm pipelines and direct-to-farm distribution networks. NatureWorks specializes in converting dent corn into polylactic acid biopolymers, occupying a narrow but defensible niche with premium offtake contracts.
North America maize comprises Zea mays varieties cultivated at moisture contents of 15-20% for grain harvest, with kernel composition ranging from 72-74% starch, 8-10% protein, and 4-5% oil by dry weight. The crop serves as the primary carbohydrate feedstock for ethanol fermentation, livestock nutrition, and industrial starch extraction across the continent. Dent corn dominates volume flows into biofuel and animal feed channels where margin pools remain thin but scale-dependent. Sweet corn commands disproportionate value in retail and food processing segments despite smaller harvested acreage. The snack foods application within meal production is drawing investment as extrusion technology enables higher-value product formats.
The US EPA administers Renewable Fuel Standard blending obligations that structurally mandate ethanol consumption, while the USDA oversees crop insurance programs and conservation compliance tied to maize acreage decisions. Health Canada and PMRA jointly regulate maximum residue limits for crop protection chemicals on grain destined for food and feed uses. Stakeholders must monitor how evolving carbon intensity scoring in fuel regulations and state-level low-carbon fuel standards reshape the competitive calculus between conventional and cellulosic ethanol pathways.
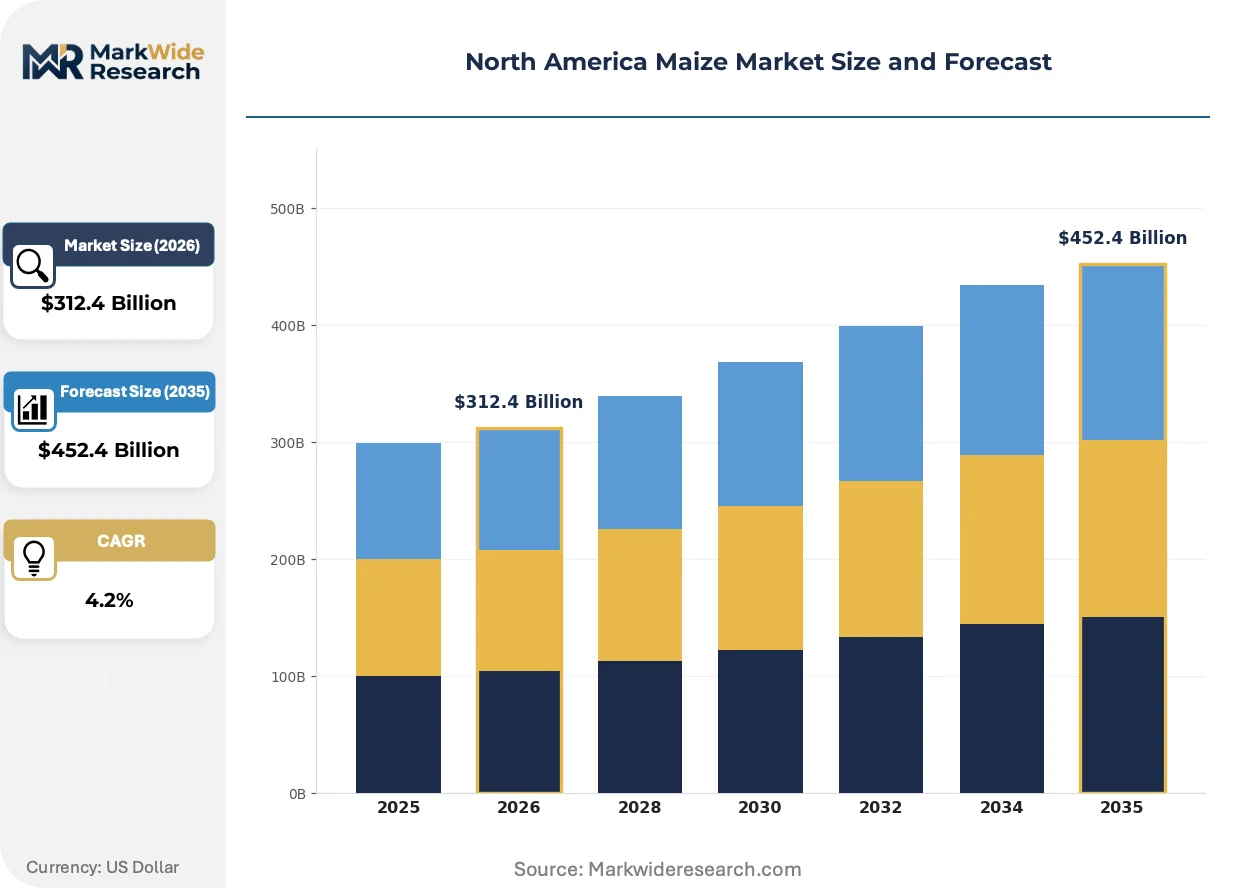
Market Dynamics
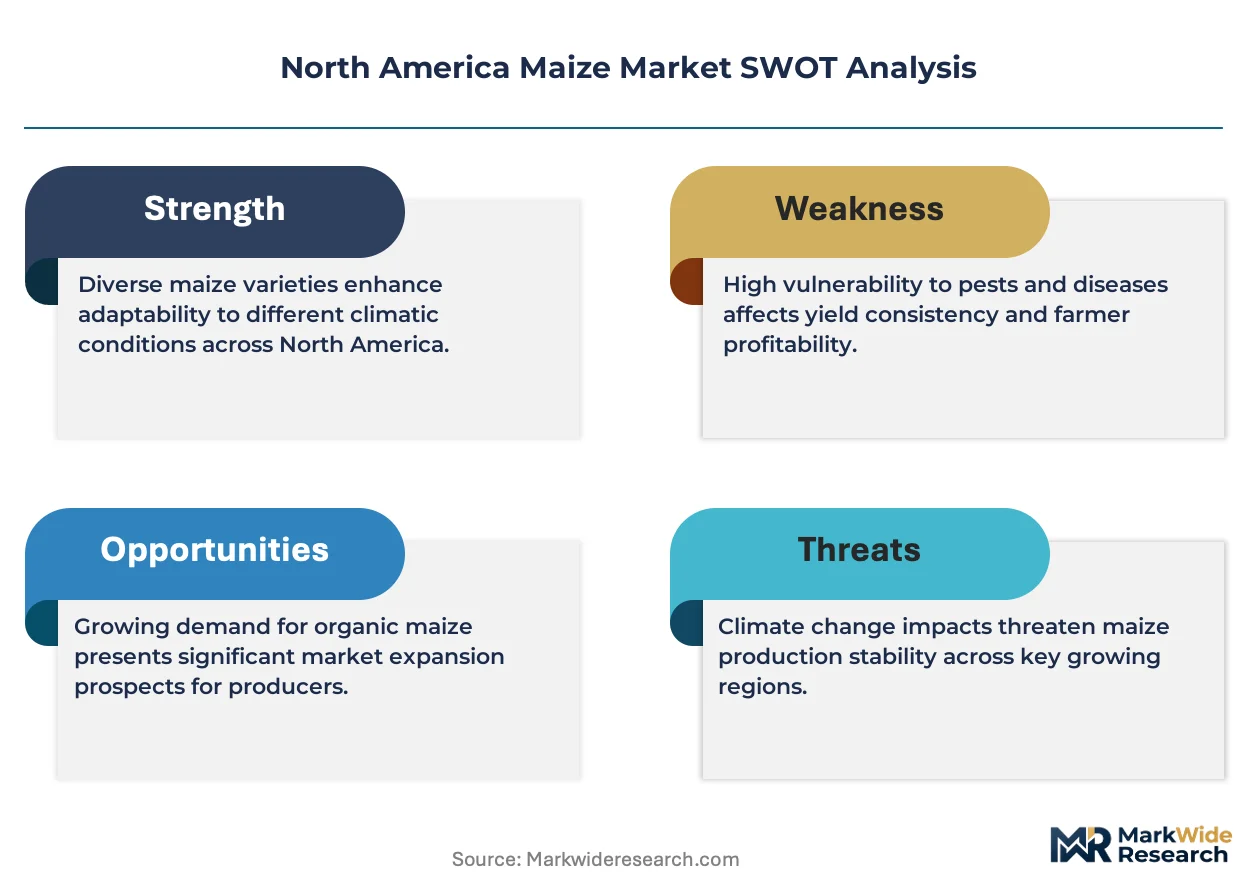
The US EPA Renewable Fuel Standard blending mandates are structurally redirecting maize volume flows toward ethanol channels, compressing traditional feed and food allocation ratios while concentrating procurement power among biofuel processors.
Growth Catalysts
- Ethanol blending mandates:The US EPA Renewable Fuel Standard structurally mandates higher ethanol consumption volumes, locking in baseline maize demand regardless of commodity price cycles.
- Carbon intensity scoring:California's Low Carbon Fuel Standard and similar state-level frameworks create premium offtake channels for lower-carbon ethanol pathways.
- Protein extraction:Wet millers are expanding high-value protein fractionation capacity to serve growing aquaculture and pet nutrition formulations.
Market Restraints
- Input cost volatility:Natural gas and nitrogen fertilizer prices expose farm-level margins to energy market swings.
- Supply concentration risk:Iowa, Illinois, and Nebraska together account for the majority of US production, creating localized weather dependency.
- Regulatory friction:Health Canada and PMRA maximum residue limit reviews delay crop protection chemistry approvals.
Strategic Opportunities
- Underpenetrated geographies:Ontario and Quebec offer expansion headroom for identity-preserved specialty maize with premium contracting structures.
- Biopolymer feedstock:Polylactic acid production from dent corn opens industrial offtake channels beyond fuel and feed.
- Precision fermentation:Converging synthetic biology and carbohydrate supply chains creates novel protein production platforms.
Industry Challenges
- Genetic licensing complexity:Stacked trait IP portfolios create royalty stacking and cross-lic negotiation friction for seed developers.
- Conservation compliance:USDA crop insurance program eligibility ties to wetland and erosion controls that constrain plantable acreage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Maize Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $452.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Corn, Flint Corn, Dent Corn, Pod Corn End Use Industry: Food Processing, Animal Feed, Biofuel, Starch Production Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers Application: Meal Production, Snack Foods, Beverages, Fermentation |
| Companies Covered | BASF, Mars Petcare, Bayer CropScience, Tyson Foods, NatureWorks, Corteva Agriscience, Nestlé Purina, Hendrix Genetics, Syngenta, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Maize Market Evolving Landscape
Gene editing and digital agronomy are compressing breeding cycles while fragmenting competitive advantage sources across the North America maize value chain.
CRISPR-based gene editing is bifurcating trait development economics. Mid-size seed companies adopt edited drought-tolerance alleles without transgenic regulatory burdens. Large integrated players maintain germplasm scale advantages while specialized biotech firms capture royalty streams from edited output traits.
The US EPA is finalizing updated carbon intensity scoring methodologies for the Renewable Fuel Standard. These rules recalculate ethanol lifecycle emissions using updated land-use change assumptions. Corn Belt processors are investing in methane capture and renewable natural gas to improve facility-level carbon scores.
Buyers are consolidating procurement through direct origination contracts that bypass traditional elevator intermediaries. Large pork and poultry integrators in the US Southeast now contract directly with Iowa and Illinois growers for specified moisture and mycotoxin levels. This disintermediation compresses basis spreads and transfers storage risk to farm balance sheets.
North America Maize Market Segmentation
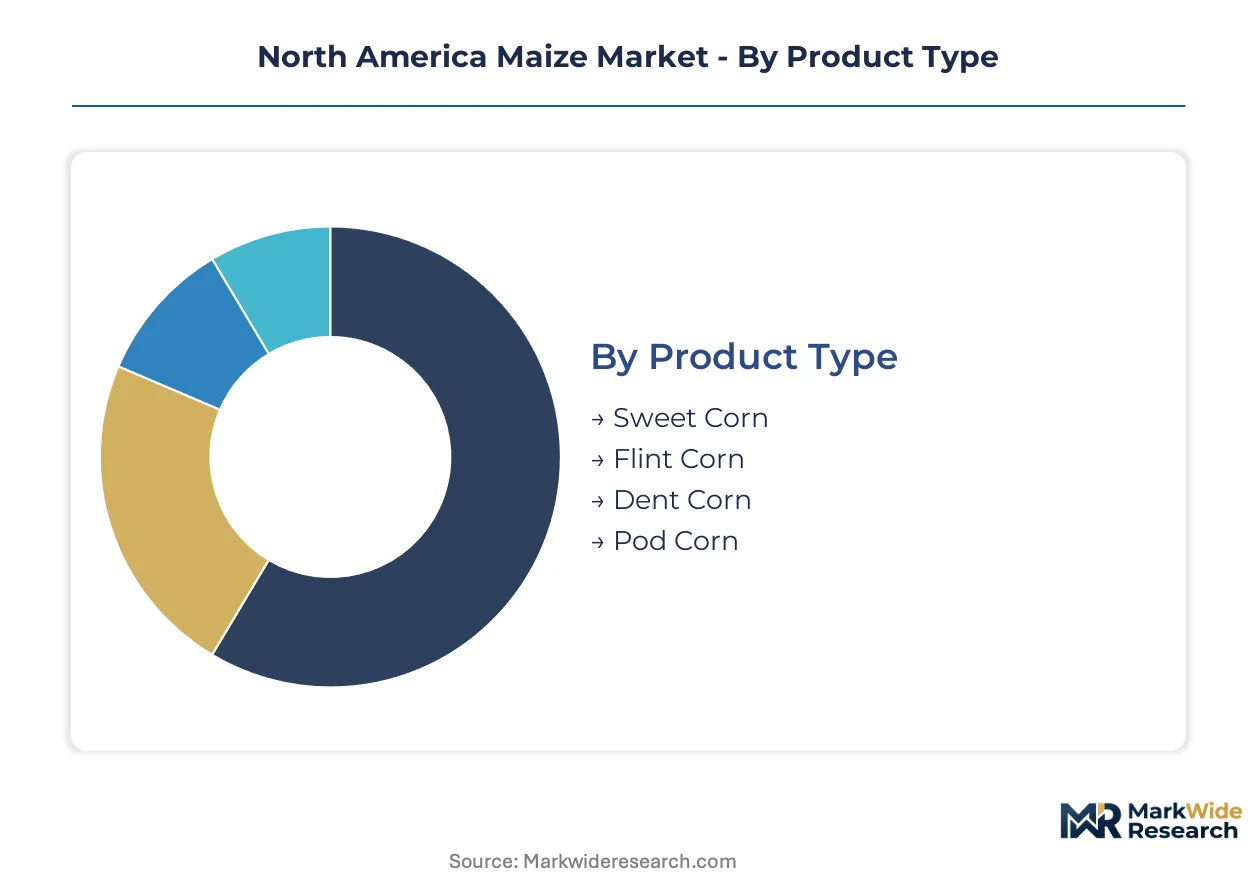
Maize segmentation in North America reflects divergent regulatory pathways across end-use channels. EPA blending mandates, USDA grading standards, and Health Canada residue limits each reshape procurement specifications and value capture potential.
Product Type:
USDA grain standards and Health Canada grading regulations create distinct handling protocols for each varietal category.
- Dent Corn:Kernel composition runs 72-74% starch with pronounced denting at crown maturity from rapid starch deposition. Biofuel processors in Iowa and Illinois concentrate procurement of No. 2 yellow dent for ethanol fermentation, driven by EPA Renewable Fuel Standard blending floors that lock in baseline volume regardless of commodity price cycles.
- Sweet Corn:Sugary enhanced and supersweet genotypes retain elevated sucrose levels at harvest through recessive endosperm mutations. Fresh market demand concentrates in Florida, Georgia, and California growing windows where direct-to-retail contracts specify brix levels and husk appearance standards.
- Flint Corn:Hard vitreous endosperm delivers superior grinding characteristics for traditional masa applications. Tortillerias and snack food processors specify flint-dent crosses for nixtamalization efficiency.
- Pod Corn:Primitive glume-enclosed architecture limits commercial scale but supports heritage seed banking and indigenous food system preservation. Niche growers in Mexico and southwestern US maintain germplasm under slow-food certification protocols.
Established volume favors dent corn; emerging adoption favors sweet corn specialty contracting.
End Use Industry:
Margin structure varies sharply across processing intensity tiers from bulk fermentation to fractionated ingredient recovery.
- Biofuel:Dry-grind ethanol plants consume over one-third of US maize production, with carbon intensity scoring under California LCFS and pending EPA updates reshaping facility-level investment in methane capture and renewable natural gas.
- Animal Feed:Swine and poultry integrators in the US Southeast now contract directly with Corn Belt growers for specified moisture and mycotoxin levels, disintermediating traditional elevator channels.
- Food Processing:Wet millers extract high-value protein fractions for aquaculture and pet nutrition formulations, with fractionation capacity expanding at ADM and Cargill facilities.
- Starch Production:Modified and unmodified starches serve paper, textile, and adhesive applications where industrial buyers specify viscosity and gelatinization temperature profiles.
Feed and fuel dominate volume flows; protein fractionation climbs the fastest.
Distribution Channel:
Channel economics reflect scale thresholds and identity preservation requirements that determine handler margins.
- Direct Sales:Large pork and poultry integrators contract specified quality parameters directly with growers, transferring storage risk to farm balance sheets while compressing basis spreads.
- Wholesalers:Regional grain elevators maintain origination networks across the Corn Belt, blending loads to meet USDA grade standards for export and domestic processor delivery.
- Retail:Sweet corn for fresh consumption moves through supermarket produce departments with cold-chain requirements driving regional sourcing from Florida, Georgia, and California.
- E-commerce:Heritage and specialty maize varieties reach direct-to-consumer channels through seed exchanges and small-batch food producers, with identity preservation commanding premium pricing.
Wholesaler infrastructure anchors bulk grain flows; direct contracting gains share fastest in protein supply chains.
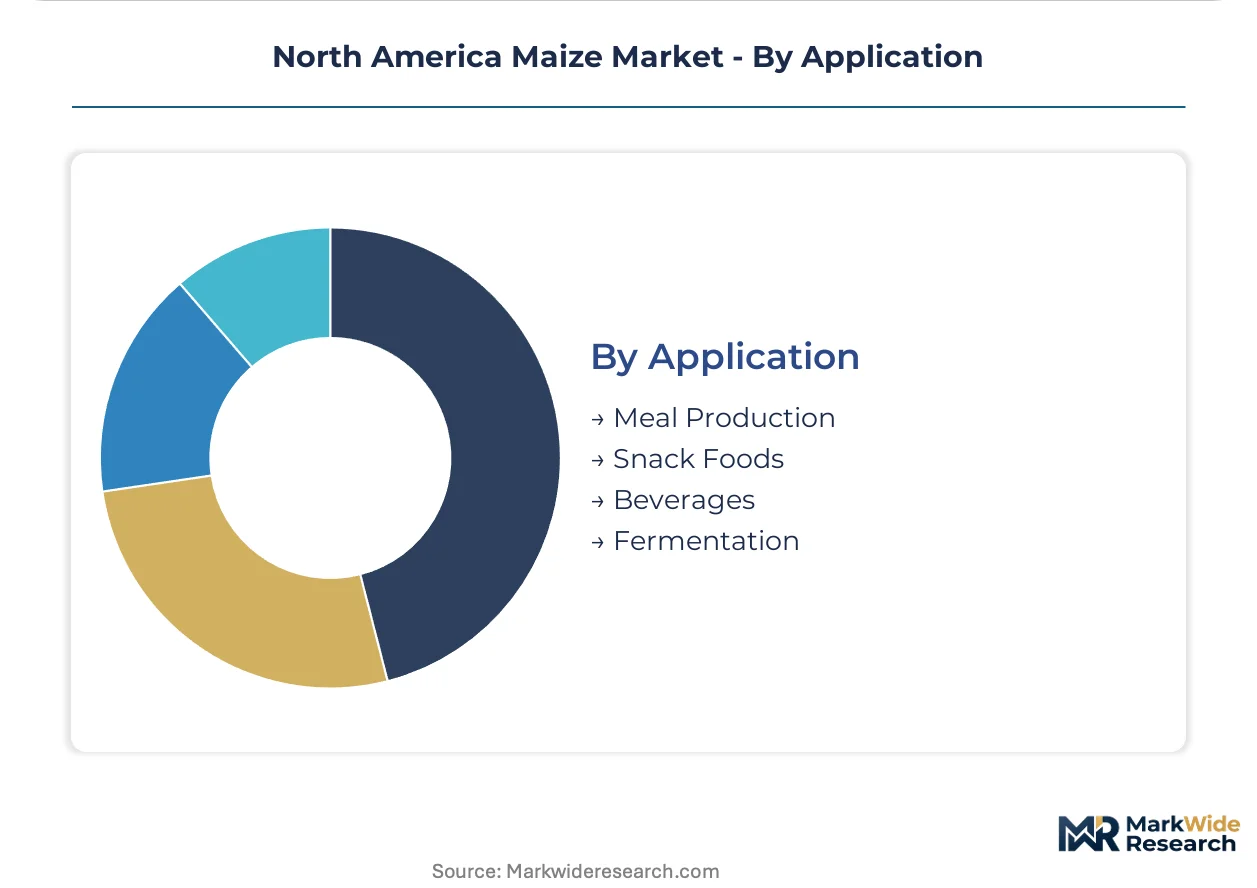
Application:
Processing technology determines value recovery rates across grinding, extrusion, and fermentation pathways.
- Fermentation:Ethanol producers optimize yeast strains and enzyme cocktails for starch-to-ethanol conversion efficiency, with cellulosic pathway development stalled by carbon intensity scoring uncertainties.
- Meal Production:Dry milling yields grits, meal, and flour for brewing and baking applications where particle size distribution determines end-use suitability.
- Snack Foods:Extrusion technology enables higher-value product formats from tortilla chips to puffed snacks, with seasoning and texture innovation driving category expansion.
- Beverages:Brewing adjuncts and distilled spirits production specify low-oil, high-extract varieties with predictable fermentability profiles.
Fermentation commands the largest volume share; snack food extrusion offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Corn Belt while Canadian specialty contracting captures premium spreads. Mexico's import dependency creates arbitrage opportunities across border elevators. Sub-regional dynamics diverge sharply between bulk commodity flows and identity-preserved channels.
United States
Iowa, Illinois, and Nebraska generate the majority of North American maize volume, with EPA Renewable Fuel Standard mandates locking ethanol processors into baseline procurement regardless of price cycles. USDA crop insurance programs and conservation compliance rules constrain plantable acreage decisions. Processing infrastructure clusters around Decatur, Illinois, and Cedar Rapids, Iowa, where ADM and Cargill operate integrated wet milling complexes.
Canada
Ontario and Quebec offer expansion headroom for identity-preserved specialty maize with premium contracting structures. Health Canada and PMRA jointly regulate maximum residue limits for crop protection chemicals on grain destined for food and feed uses. Chatham-Kent and southwestern Ontario concentrate seed multiplication operations serving US Midwest germplasm demand.
Mexico
Import dependency from US suppliers shapes procurement patterns as domestic production satisfies less than half of consumption. SADER administers biosafety protocols for genetically modified maize while maintaining reference prices for tortilla subsidies. Sinaloa and Tamaulipas host the largest domestic production clusters, though irrigation constraints limit expansion.
North America Maize Market Competitive Landscape
Concentration sits with integrated seed-to-protein conglomerates that control germplasm pipelines and processing infrastructure. Three tiers structure competitive dynamics: multinational input providers with bundled chemistry portfolios, specialized biotech firms licensing edited traits, and downstream processors securing origination through direct farm contracts. Dominant competitive moves include backward integration into captive seed supply and geographic expansion of fractionation capacity.
Within the integrated input tier, BASF and Bayer CropScience exemplify archetypes combining crop protection chemistry with seed platforms. Corteva Agriscience anchors the proprietary germplasm segment through direct-to-farm distribution networks. NatureWorks occupies a narrow but defensible niche converting dent corn into polylactic acid biopolymers.
| Leading Market Players |
|---|
| BASF |
| Mars Petcare |
| Bayer CropScience |
| Tyson Foods |
| NatureWorks |
| Corteva Agriscience |
| Nestlé Purina |
| Hendrix Genetics |
| Syngenta |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Iowa and Illinois dry-grind ethanol plants shapes both regional basis spreads and farm-gate price floors, concentrating procurement leverage among biofuel processors while compressing elevator intermediation margins. This scale-driven dynamic locks in thin but volume-dependent returns across the Corn Belt origination network.
Pricing Analysis
Configured-to-order contracting for identity-preserved specialty maize commands spreads of 15-40% above No. 2 yellow dent spot prices. Contract-based long-term offtake dominates biofuel and protein integrator procurement, with price differentiation resting on quality grade and carbon intensity certification under California LCFS. Cost compression in standard dent corn is intensifying because direct origination transfers storage risk to grower balance sheets. Small-scale heritage seed producers exhibit lowest price sensitivity; commodity ethanol processors show highest.
Supply Chain Analysis
Mississippi River barge terminal congestion during fall harvest windows creates seasonal chokepoints that elevate delivered costs to Gulf export elevators. Geographic supply concentration centers on the United States, Canada, and Mexico, with the Corn Belt drawing from nitrogen fertilizer inputs, diesel fuel, and proprietary germplasm licensing. Single-source vulnerability runs through concentrated seed trait IP portfolios controlled by three integrated input providers. Distribution runs through direct farm contracting and regional elevator networks with blending-to-grade protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American maize sits in early-cycle expansion as EPA Renewable Fuel Standard blending floors and state-level low-carbon fuel standards structurally embed demand growth regardless of commodity price cycles.
For Market Incumbents: Secure backward integration into captive renewable natural gas production to improve facility-level carbon intensity scores under evolving EPA methodologies. Lock in multi-year direct origination contracts with Iowa and Illinois growers to defend against disintermediation by protein integrators. Priority lever: methane capture infrastructure at dry-grind plants.
For New Entrants and Emerging Players: Precision fermentation feedstock supply gaps in Ontario and Quebec offer white-space entry where incumbents under-serve identity-preserved contracting demand. Target aquaculture protein fractionation as the most penetrable segment given wet millers' capacity constraints. Go-to-market angle: direct partnerships with Maritime Canada fish farm operators for specified mycotoxin thresholds.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized biotech firms with CRISPR-edited drought-tolerance alleles and freedom-to-operate outside transgenic regulatory frameworks. Long-term viability rests on germplasm scale advantages eroding as gene editing democratizes trait development. Signal to watch: EPA final carbon intensity scoring rules for cellulosic pathway eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RNG Production | Corn Belt processors capture methane emissions to lower EPA carbon intensity scores. |
| Direct Farm Contracting Expansion | Poultry integrators bypass elevators to specify moisture and mycotoxin parameters. |
| Protein Fractionation Capacity Buildout | Wet millers extract high-value aquaculture feed fractions at ADM Decatur complex. |
| CRISPR Trait Licensing Programs | Mid-size seed companies access edited drought alleles without transgenic burdens. |
| Identity-Preserved Specialty Channels | Ontario growers capture premium spreads through slow-food certification protocols. |
Research Methodology
Initial hypotheses were tested against primary input from ethanol plant operations managers, grain elevator procurement leads, seed company R&D directors, and livestock integrator feed formulation specialists and refined through secondary validation against USDA NASS crop production reports, EPA Renewable Fuel Standard compliance data, EIA ethanol production statistics, and Health Canada PMRA residue limit determinations. Bottom-up acreage and yield modeling triangulated against top-down processor capacity and offtake analysis.
Variance decomposition across product type, end-use industry, distribution channel, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from facility-level capacity expansion announcements and regulatory mandate trajectory modeling. Industry-specific inputs included EPA blending obligation schedules and California LCFS credit price forecasting.
Forecasts assume regulatory continuity in EPA Renewable Fuel Standard and California LCFS regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as carbon intensity scoring methodologies and state-level low-carbon fuel standard adoption patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Italy Rice Market
Grains
Wheat Flour Market
Grains
Grain and Cereal Crop Market
Grains
Cultured Wheat Market
Grains
Asia-Pacific Guar Market
Grains
Organic Wheat Flour Market
Grains
Global Rice Market
Grains
Fortified Rice Market
Grains
Asia-Pacific Rice Market
Grains
Grain Dryers Market
Grains
United States Gluten-Free Oats Market
Grains
Precooked Flour Market
Grains
Quinoa Flour Market
Grains
Canada Pulses Market
Grains
Grain Bins Market
Grains
Ancient Grain Market