
 Global Vegetable Seed Market | 2026-2036
Global Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vegetable Seed Market Outlook
Direct-to-farmer digital platforms is reshaping how vegetable seed reaches end users, bypassing traditional multi-tier distribution. Syngenta AG leverages its integrated crop protection portfolio to bundle seed with agronomic advisory services. Bayer AG anchors its position through trait-enhanced germplasm developed for abiotic stress tolerance. Sakata Seed Corporation specializes in solanaceous crop genetics, particularly tomato and pepper lines optimized for protected cultivation systems.
Vegetable seed comprises sexually or vegetatively propagated reproductive material selected for specific agronomic, culinary, or industrial traits, typically delivered with minimum germination rates exceeding 85% and varietal purity standards certified under OECD seed schemes. Its primary commercial purpose is to enable predictable yield outcomes and uniform harvest quality for fresh market and processing supply chains. Hybrid seeds dominate value generation due to proprietary parent line control and first-generation vigor premiums, while open-pollinated varieties retain structural importance in organic and subsistence systems where seed saving remains economically rational. Trait-enhanced seeds, incorporating disease resistance or climate-adaptive genetics, capture expanding margin pools as regulatory pressure on chemical inputs tightens across producing regions.
The OECD Seed Schemes, USDA-APHIS phytosanitary protocols, and EU Plant Health Regulation collectively govern cross-border seed movement, varietal registration, and genetic purity certification, creating compliance thresholds that filter market access for non-specialized suppliers. India's Seeds Act and China's GB seed quality standards impose additional national conformity requirements that shape breeding priorities and testing investments for entrants. Stakeholders must monitor accelerating gene editing regulatory clarity, as jurisdictions diverge on whether CRISPR-derived traits trigger GMO classification and associated approval burdens.
Market Dynamics
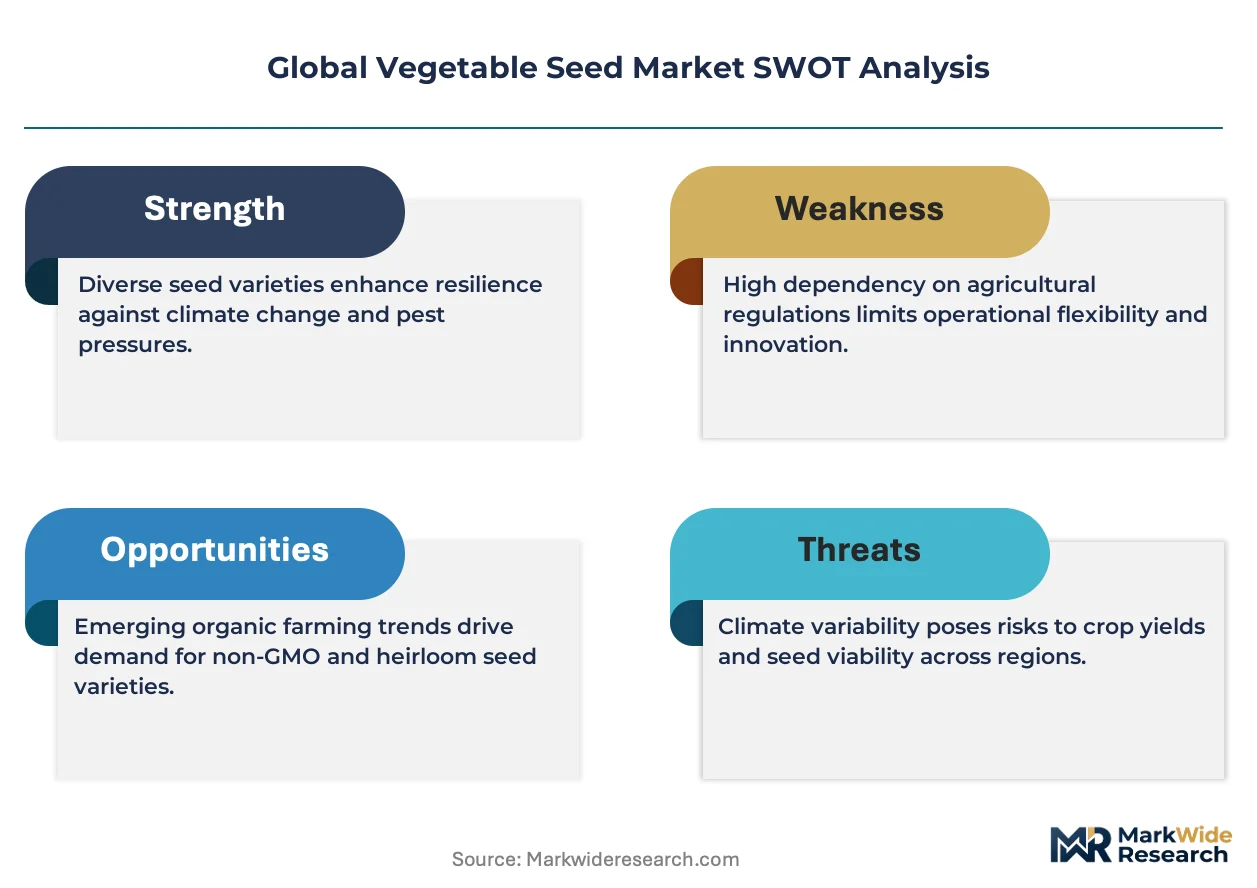
Gene editing regulatory divergence is fragmenting R&D investment flows across jurisdictions, forcing breeders to maintain parallel trait development pipelines for markets with divergent classification frameworks.
Growth Catalysts
- EU Plant Health Regulation:Mandatory varietal registration and phytosanitary certification for seed imports is elevating demand for certified germplasm from OECD-compliant breeding programs.
- Protected cultivation systems:Greenhouse and hydroponic vegetable operations in the Netherlands and Spain require uniform maturation genetics that only hybrid seed delivers.
- India's vegetable belt consolidation:Smallholder cooperative formation accelerates certified seed uptake as aggregated buyers negotiate volume contracts with improved germplasm suppliers.
Market Restraints
- Parent line concentration:Proprietary inbred development requires decade-long breeding cycles concentrated in temperate zone research stations, creating supply bottlenecks for tropical-adapted hybrids.
- Phytosanitary compliance costs:USDA-APHIS and EU Plant Health Regulation testing protocols add 18-24 months to cross-border variety introduction timelines.
- Seed saving economics:Open-pollinated varieties retain viability in subsistence systems where hybrid vigor premiums cannot be monetized through market access.
Strategic Opportunities
- Vietnam's Mekong Delta:Commercial farming expansion in flood-prone alluvial plains creates demand for submergence-tolerant solanaceous germplasm unavailable from domestic breeders.
- Direct-to-farmer digital platforms:Mobile-enabled seed ordering with embedded agronomic advisory bypasses traditional distributor markups in fragmented last-mile markets.
- China's dual carbon goals:National emissions reduction mandates favor drought-tolerant varieties that reduce irrigation energy intensity in water-stressed northern production zones.
Industry Challenges
- Gene editing classification uncertainty:Divergent CRISPR-derived trait regulatory frameworks across USDA, EFSA, and China's NMPA force redundant safety dossier preparation.
- Phenotyping infrastructure gaps:High-throughput field trial automation requires capital deployment that mid-tier breeding programs cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vegetable Seed Market |
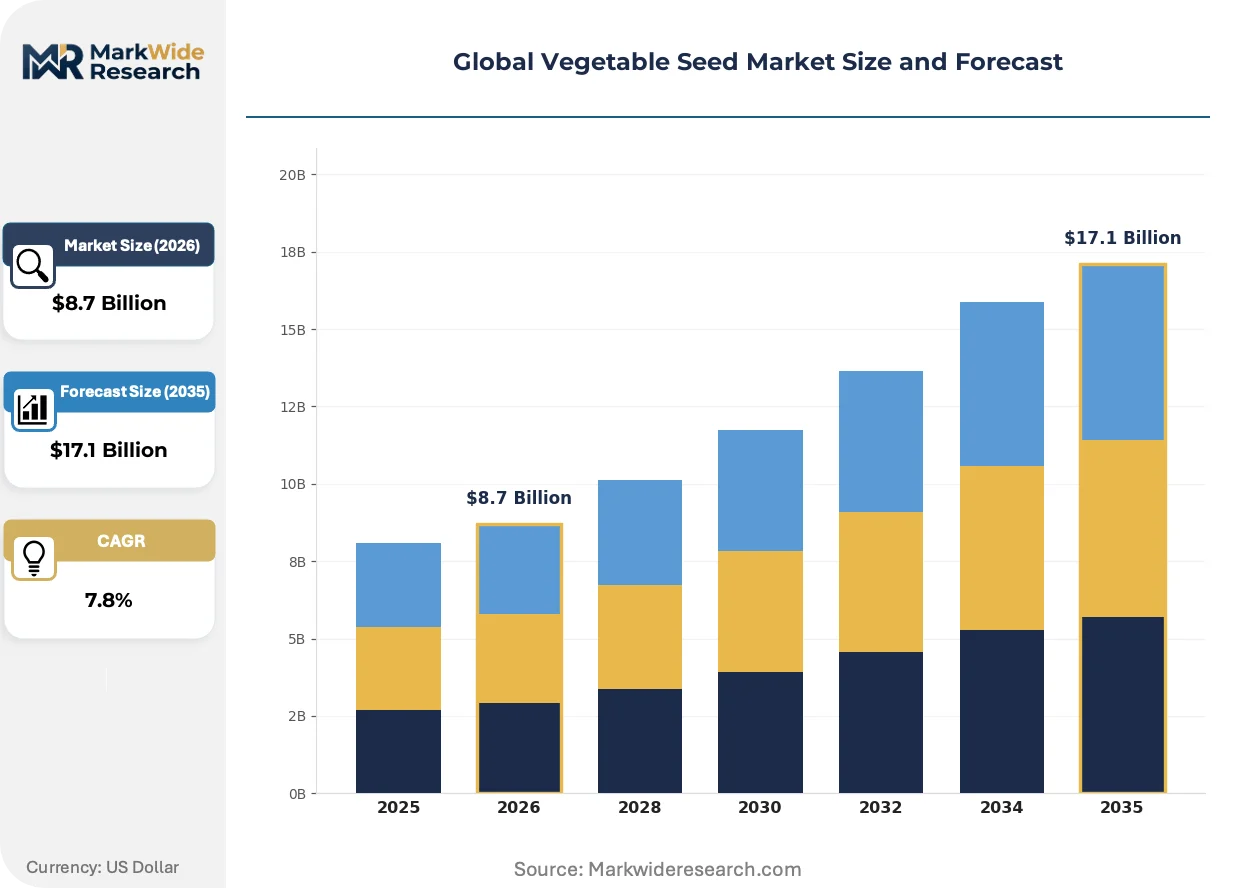
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, Heirloom Seeds, Trait-Enhanced Seeds Crop Type: Tomatoes, Peppers, Cucumbers, Carrots Packaging Type: Bags, Boxes, Jars, Pouches End Use: Commercial Farming, Home Gardening, Research, Agro-forestry |
| Companies Covered | Syngenta AG, BASF SE, Bayer AG, Enza Zaden, East-West Seed, Sakata Seed Corporation, Rijk Zwaan, Takii & Co., Groupe Limagrain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vegetable Seed Market Strategic Shifts
Biotechnology convergence with precision agriculture is redefining how vegetable genetic potential is matched to specific growing environments and supply chain quality specifications.
Marker-assisted selection is accelerating inbred line fixation timelines. Large-scale vegetable processors in California's Central Valley demand varieties with synchronized maturity windows for mechanical harvest compatibility. This capability is hybridizing traditional breeding cycles with genomic prediction, compressing variety development from eight years to four.
REACH chemical authorization restrictions are tightening pesticide availability for vegetable pest management. EU vegetable growers face reduced active ingredient options for soil-borne pathogen control. Seed treatments containing biological control agents now substitute for chemical fumigation in Dutch glasshouse tomato production.
Consolidated retail procurement specifications are reshaping breeder priority lists. European supermarket chains mandate specific Brix levels, shelf-life duration, and cosmetic uniformity that open-pollinated varieties cannot achieve. Indian organized retail expansion in Bangalore and Mumbai accelerates demand for transport-tolerant hybrids over local landraces.
Global Vegetable Seed Market Segmentation
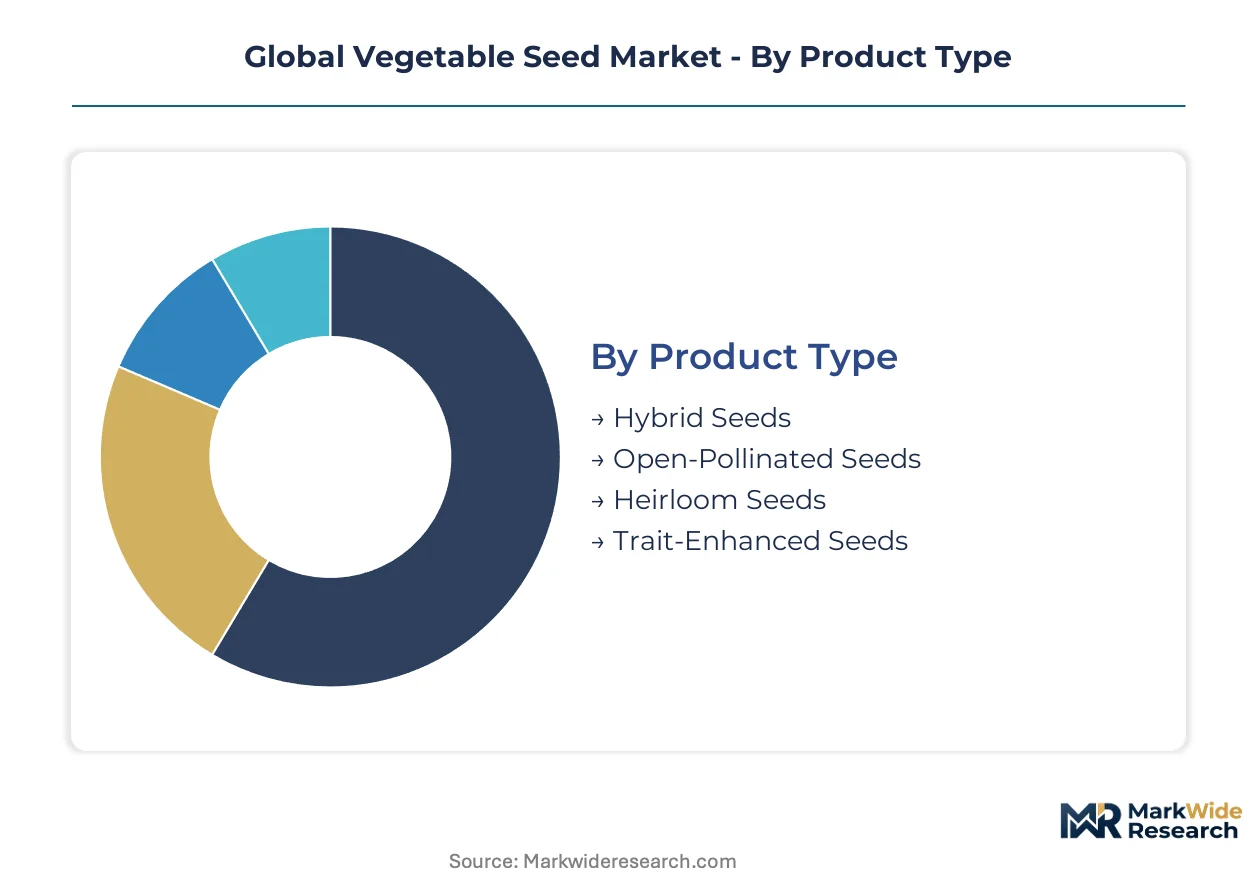
Vegetable seed segmentation reflects divergent breeding investments, distribution economics, and farmer decision-making frameworks across commercial and subsistence production systems. Each dimension captures distinct margin structures, regulatory exposure, and technology adoption curves that shape supplier strategy.
Product Type:
Mature proprietary formats dominate value capture while emerging genetic technologies reset competitive boundaries.
- Hybrid Seeds:First-generation crosses between inbred parent lines deliver heterosis-driven yield premiums and proprietary genetic lock-in through controlled parent line access. Demand concentrates in California's Central Valley processing tomato operations where mechanical harvest synchronization requires uniform maturation genetics unavailable from open-pollinated alternatives.
- Trait-Enhanced Seeds:Germplasm incorporating disease resistance, abiotic stress tolerance, or shelf-life extension through marker-assisted selection or gene editing commands price premiums as EU REACH restrictions reduce chemical input options. Dutch glasshouse pepper growers substitute seed-borne resistance for soil fumigants phased under environmental authorization protocols.
- Open-Pollinated Seeds:Self-fertile varieties retain farmer seed-saving rights and suit organic certification systems prohibiting hybrid dependency. India's Karnataka smallholder cooperatives bulk-procure certified open-pollinated tomato lines to avoid recurring hybrid seed costs.
- Heirloom Seeds:Heritage varieties preserved through generational cultivation supply specialty fresh market niches and seed banking initiatives. Demand localizes in Italy's Campania region for San Marzano tomato provenance protection and EU geographical indication compliance.
Hybrid seeds handle the majority of throughput; trait-enhanced seeds are climbing the fastest on share as regulatory pressure on agrochemicals intensifies.
Crop Type:
Volume concentration tracks processing industry scale while protected cultivation expansion reshapes varietal priorities.
- Tomatoes:Solanaceous genetics command the largest breeding investment pool, spanning determinate processing types for mechanical harvest, indeterminate fresh market lines, and cherry formats for retail snacking segments. Spain's Almería greenhouse cluster drives demand for grafting-compatible rootstocks and soil-borne disease resistance.
- Peppers:Capsicum germplasm spans bell, chili, and specialty pungency categories with distinct capsaicinoid profiles for industrial extraction or culinary use. Mexico's Chihuahua state commercial operations require heat-tolerant hybrids as irrigation water quality deteriorates.
- Cucumbers:Gynoecious hybrid parthenocarpic lines dominate protected cultivation for seedless fruit production. Dutch propagation houses supply grafted cucumber transplants to German and Scandinavian glasshouse operators.
- Carrots:Apiaceae breeding targets nematode resistance and cylindrical root morphology for mechanical harvest compatibility. France's Brittany region processes contract volumes for European baby-cut carrot retail packs.
Tomatoes handle the majority of throughput; peppers are expanding most quickly as global cuisine diversification accelerates.
Packaging Type:
Unit economics and distribution channel requirements determine format selection across wholesale and retail seed flows.
- Bags:Multi-layer laminated structures with moisture barriers and resealability dominate commercial farming bulk procurement. India's Maharashtra vegetable belt receives 500-gram to 5-kilogram bag formats through cooperative aggregation channels.
- Boxes:Rigid paperboard with seed tape or pellet formulations suits precision planting equipment and high-value hybrid distribution. Japan's protected cultivation sector imports tomato and melon seeds in unit-dose box presentations.
- Jars:Glass or polymer containers with desiccant inserts preserve viability for low-volume heirloom and research germplasm. Seed banking networks and gene conservation facilities standardize on jar formats for long-term storage protocols.
- Pouches:Flexible metallized films with zip-lock closures target home gardening retail channels and impulse purchase formats. US big-box garden center chains stock seasonal vegetable pouch assortments from February through May.
Bags handle the majority of throughput; pouches are gaining share fastest as direct-to-consumer digital channels expand.
End Use:
Customer scale and purchasing sophistication create tiered service requirements from commodity bulk to technical advisory.
- Commercial Farming:Large-scale operations demand volume contracting, varietal performance guarantees, and integrated crop protection bundling. Brazil's São Paulo state salad vegetable producers negotiate season-long supply agreements with technical field support.
- Home Gardening:Amateur cultivation segments prioritize visual appeal, simplified growing instructions, and retail availability over yield optimization. UK allotment associations and community garden networks drive open-pollinated and heritage variety demand.
- Research:Public breeding programs and university trials require genetic diversity panels, characterized inbred lines, and disease differential sets. CGIAR centers and national agricultural research systems maintain germplasm exchange protocols under OECD Seed Schemes.
- Agro-forestry:Integrative systems combining vegetable intercrops with tree species demand shade-tolerant and root-competition-adapted genetics. Vietnam's Central Highlands coffee-vegetable intercropping trials test pepper and tomato understory performance.
Commercial farming handles the majority of throughput; home gardening is expanding most quickly as urban food production movements strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's germplasm distribution hub status, handling seed consignments from OECD-certified breeding stations across temperate zones.
United States
California's Central Valley processing tomato operations drive hybrid seed demand for mechanical harvest synchronization. USDA-APHIS phytosanitary protocols mandate 18-24 month testing cycles for imported varieties. The Salinas Valley leafy green cluster contracts proprietary germplasm with embedded disease resistance traits.
Netherlands
Almería greenhouse operators in Spain source grafting-compatible solanaceous rootstocks through Dutch propagation houses. EU Plant Health Regulation tightens phytosanitary certification for seed imports from non-OECD programs. Wageningen University's phenotyping facilities anchor high-throughput trait screening for glasshouse vegetable genetics.
India
Maharashtra's vegetable belt consolidates smallholder procurement through cooperative aggregation channels. India's Seeds Act imposes national conformity requirements on varietal registration and quality certification. Karnataka's tomato-growing districts bulk-procure certified open-pollinated lines to avoid recurring hybrid seed costs.
China
Northern production zones in Hebei and Shandong provinces favor drought-tolerant varieties to reduce irrigation energy intensity under national dual carbon mandates. NMPA gene editing classification frameworks remain unresolved, forcing parallel trait development pipelines. The Yangtze River Delta protected cultivation cluster imports hybrid cucumber and pepper germplasm from Japanese breeders.
Brazil
São Paulo state salad vegetable producers negotiate season-long supply agreements with integrated crop protection bundling. ANVISA phytosanitary protocols align with OECD Seed Schemes for cross-border germplasm movement. The Minas Gerais tomato processing corridor demands determinate varieties compatible with mechanical harvest windows.
Global Vegetable Seed Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream breeding proprietary parent lines. The vendor base concentrates around integrated agrochemical-seed conglomerates and family-held breeding houses with multi-decade germplasm libraries. Three archetypes dominate: diversified life-science conglomerates with crop protection bundling capabilities, specialized vegetable genetics houses with protected-cultivation expertise, and regional seed companies serving smallholder consolidation markets. Competitive moves center on trait-enhanced germplasm licensing and direct-to-farmer digital platform deployment.
Among diversified life-science conglomerates, Syngenta AG and Bayer AG exemplify platform integrators leveraging crop protection portfolios to bundle seed with agronomic advisory services. Sakata Seed Corporation represents the specialized vegetable genetics archetype, with its corporate structure indicating multi-generational investment in solanaceous crop breeding. These three entities anchor distinct competitive vectors: chemical-seed integration, trait-enhanced abiotic stress tolerance, and protected-cultivation germplasm optimization respectively.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer AG |
| Enza Zaden |
| East-West Seed |
| Sakata Seed Corporation |
| Rijk Zwaan |
| Takii & Co. |
| Groupe Limagrain |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in tropical-adapted hybrid parent line development concentrates pricing power with breeders maintaining temperate-zone research stations, forcing buyers to absorb vigor premiums or retreat to open-pollinated alternatives. EU REACH chemical restrictions and India's Seeds Act compliance costs compound supplier leverage, while direct-to-farmer digital platforms fragment traditional distributor markups.
Pricing Analysis
Volume-discount tiering structures stratify across premium trait-enhanced hybrids, standard certified germplasm, and economy open-pollinated lines. Price differentiation rests on OECD Seed Scheme certification grade and bundled agronomic advisory intensity. Cost compression in standard-tier hybrids is intensifying because India's cooperative aggregation channels consolidate procurement leverage. Smallholder cooperatives in Karnataka exhibit highest price sensitivity; greenhouse operators in Spain's Almería cluster show lowest.
Supply Chain Analysis
Contract-manufacturing concentration for parent line maintenance sits with Syngenta AG, Bayer AG, and Sakata Seed Corporation operating proprietary temperate-zone breeding stations. Geographic supply concentration centers on the Netherlands, Japan, and the United States for hybrid germplasm. Raw material dependencies draw from phytosanitary testing infrastructure, cold-chain logistics, and desiccant packaging systems. Single-source vulnerability runs through OECD-certified seed scheme accreditation bottlenecks. Distribution runs through cooperative aggregation channels in India, Dutch propagation houses serving European glasshouse operators, and direct-to-farmer digital platforms in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is materializing as seed-crop protection bundling and embedded agronomic advisory transform discrete transactions into recurring ecosystem relationships. Interoperability between phenotyping data and precision agriculture hardware is locking in supplier switching costs.
For Market Incumbents: Insulate proprietary parent line portfolios through accelerated tropical-zone breeding station expansion in Vietnam and Indonesia. Deepen backward integration into high-throughput phenotyping infrastructure to compress variety development timelines. Gene editing regulatory divergence across USDA, EFSA, and China's NMPA poses compliance fragmentation threats requiring parallel dossier preparation capabilities. For New Entrants and Emerging Players: Pursue white-space opportunities in submergence-tolerant solanaceous germplasm for Vietnam's Mekong Delta flood-prone alluvial plains. Target India's Maharashtra vegetable belt cooperative aggregation channels with certified open-pollinated tomato lines. Deploy mobile-enabled direct-to-farmer platforms with embedded climate-adaptive advisory to bypass incumbent distributor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across trait-enhanced germplasm development as gene editing infrastructure and regulatory compliance costs escalate. Long-term viability favors breeders with multi-decade solanaceous germplasm libraries and OECD Seed Scheme certification track records. Acquisition target archetype: specialized vegetable genetics houses with protected-cultivation expertise and established Asian distribution. Monitor regulatory clarity on CRISPR-derived trait classification across USDA, EFSA, and NMPA as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Trait-Enhanced Germplasm Licensing | EU REACH restrictions on chemical inputs drive substitution demand for seed-borne disease resistance. |
| Direct-to-Farmer Digital Platform Deployment | Mobile-enabled ordering with embedded advisory bypasses traditional multi-tier distributor markups in fragmented markets. |
| Tropical Breeding Station Expansion | Parent line development in Vietnam and Indonesia addresses supply bottlenecks for climate-adapted hybrids. |
| High-Throughput Phenotyping Infrastructure Investment | Wageningen University-style automation compresses variety development timelines from eight years to four. |
| Gene Editing Regulatory Dossier Parallel Preparation | USDA, EFSA, and NMPA divergence forces redundant safety documentation for CRISPR-derived traits. |
Study Parameters
Cross-validation between primary interviews with breeding program directors, cooperative procurement managers, and greenhouse operations heads and secondary validation through OECD Seed Scheme certification databases, EU Plant Health Regulation filings, and USDA-APHIS phytosanitary protocols anchors the qualitative findings. Bottom-up variety-level shipment data triangulates against top-down national seed import statistics from India's DGFT and China's customs records.
Calibration against historical germplasm introduction timelines and certified seed adoption curves in India's vegetable belt shapes the analytical framework across the analysis window. Segmentation dimensions span hybrid versus open-pollinated propagation formats, solanaceous versus cucurbit crop categories, and commercial farming versus home gardening end uses. CAGRs derive from parent line availability constraints, phytosanitary compliance cycle durations, and cooperative channel penetration rates.
Macroeconomic conditions sit as an overlay; deviation in irrigation energy costs, smallholder credit access, and EU chemical authorization timelines would shift the trajectory. Quarterly review of gene editing regulatory rulings, tropical breeding station capacity announcements, and cooperative aggregation channel formation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Garlic Chive Seeds Market
Seeds
Asparagus Seeds Market
Seeds
Pigeon Pea Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Agricultural Seeder Market
Seeds
Ghana Seeds Market
Seeds
Grass Seed Market
Seeds
Sesame Seeds Market
Seeds
Global Seed Market
Seeds
Americas Seeds Market
Seeds
United States Vegetable Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
Russia Forage Seed Market
Seeds
Global Sports Turf Seed Market
Seeds
South America Forage Seed Market