
 North America Grain Seed Market | 2026-2036
North America Grain Seed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Grain Seed Market Analytics
Market Context
Certified seed standards under the Association of Official Seed Certifying Agencies (AOSCA) is redrawing competitive eligibility across the North American landscape. Bayer CropScience leverages its vertically integrated trait pipeline to sustain germplasm leadership in corn and soybeans. Corteva Agriscience anchors its position through broad distribution reach and proprietary CRISPR-edited varieties. Beck's Superior Hybrids differentiates via regional breeding programs tailored to Midwestern growing conditions.
Technical Definition and Structural Segments
Grain seed comprises genetically stable reproductive material for cereal and oilseed crops, typically meeting minimum germination thresholds of 80-90% and varietal purity standards exceeding 95% for certified commercial sale. Its primary purpose is to establish crop stands that optimize yield potential, grain quality, and harvest uniformity for downstream food, feed, and fuel applications. Hybrid seed commands the dominant value share due to proprietary genetic lock and farmer replant restrictions, while trait-enhanced seed captures accelerating demand from herbicide-tolerant and insect-resistant trait stacks. Organic seed remains a niche margin pool constrained by limited varietal availability and lower yield parity.
Regulatory Framework and Outlook
The USDA Animal and Plant Health Inspection Service (APHIS) governs biotechnology regulation through streamlined Part 340 exemptions, while EPA reviews pesticide-producing plant registrations and tolerance settings for trait-enhanced crops. Canadian Food Inspection Agency (CFIA) seed certification requirements and US state seed laws collectively shape cross-border market access and product labeling obligations. Stakeholders must monitor pending revisions to APHIS Part 340 and evolving state-level dicamba restrictions that could reroute trait development investments and farmer seed selection criteria.
Market Dynamics
Trait-enhanced seed approvals through USDA APHIS Part 340 exemptions are compressing time-to-market for biotech varieties and redrawing competitive eligibility across the Corn Belt. Commercial feedlot operators are consolidating germplasm procurement around stacked-trait corn and herbicide-tolerant soybeans.
Growth Catalysts
- USDA Biotechnology Deregulation:Streamlined Part 340 review timelines accelerate commercialization of CRISPR-edited and transgenic varieties, reducing regulatory lag for trait developers.
- Feedlot Operator Consolidation:Large-scale cattle finishing operations in Nebraska and Kansas are contracting directly for high-yield corn with specified protein and energy content profiles.
- EPA Pesticide Tolerance Reviews:Expedited tolerance settings for novel trait stacks enable faster farmer adoption of herbicide-resistant and insect-protected seed platforms.
Market Restraints
- Proprietary Germplasm Concentration:Three entities control over 70% of US corn and soybean genetics, limiting farmer choice and locking in trait licensing fees.
- Seed Production Input Volatility:Isolated acres in Idaho and Oregon face irrigation water allocation cuts from Bureau of Reclamation shortages, squeezing certified seed yields.
- Organic Yield Parity Gap:Non-GMO and organic varieties average 15-25% lower bushel-per-acre performance, constraining adoption despite price premiums.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Manitoba spring wheat and canola markets remain underpenetrated by US trait-enhanced platforms, offering first-mover positioning.
- Carbon Credit Integration:USDA Climate-Smart Commodities grants incentivize cover crop and reduced-tillage seed bundles that qualify farmers for offset markets.
- Direct-to-Farm Digital Channels:E-commerce platforms and satellite imagery-based prescription services are bypassing traditional dealer networks in Iowa and Illinois.
Industry Challenges
- APHIS Part 340 Compliance Timeline:Exemption petitions for gene-edited varieties still require 12-18 month review cycles, delaying product launches against competitive windows.
- Trait Licensing Complexity:Stacked-trait corn varieties require cross-licensing agreements across multiple patent holders, fragmenting royalty structures and farmer transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Grain Seed Market |
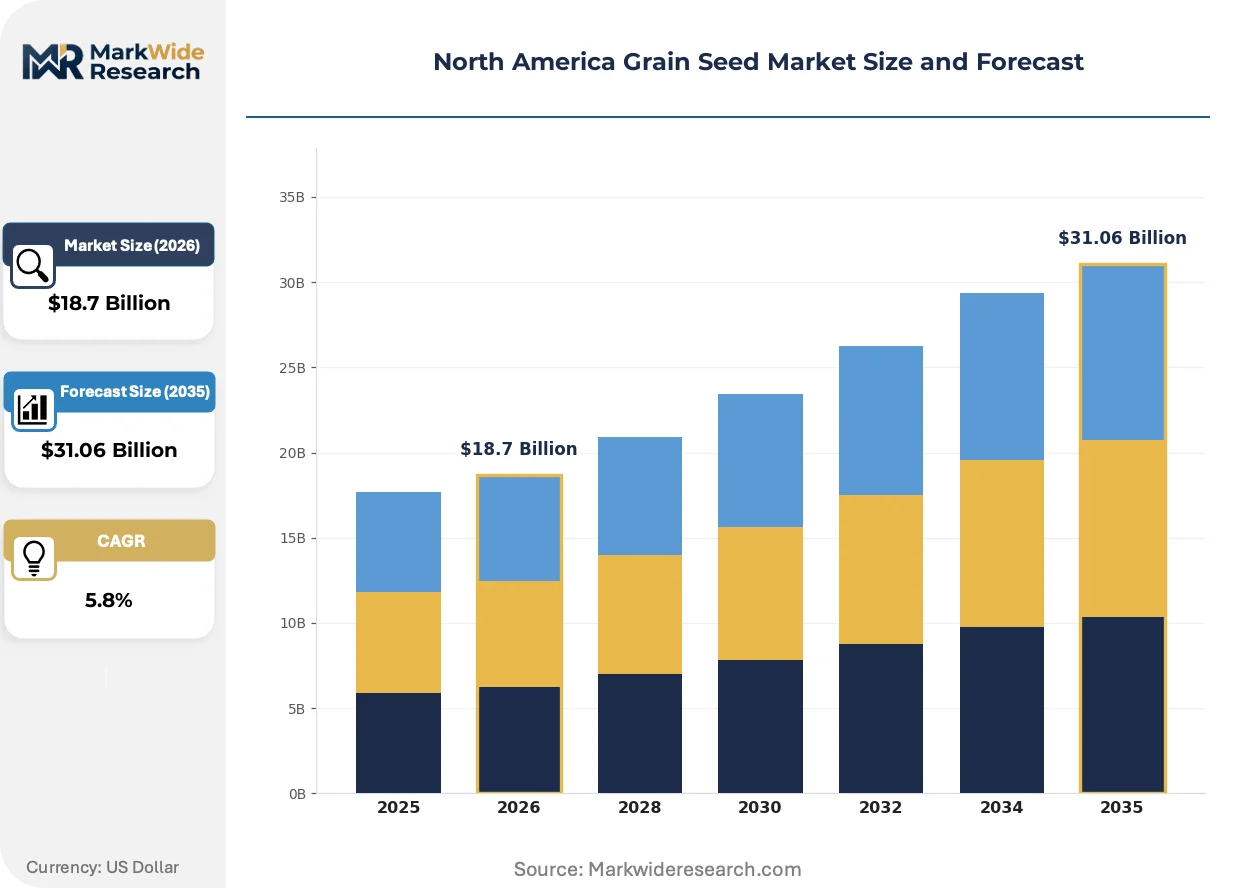
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seed, Open-Pollinated Seed, Trait-Enhanced Seed, Organic Seed Distribution Channel: Retail Stores, Online Platforms, Agricultural Cooperatives, Direct Sales Cultivation Method: Conventional Farming, Organic Farming, Precision Agriculture, Sustainable Agriculture End User: Farmers, Agricultural Companies, Research Institutions, Grain Processors |
| Companies Covered | BASF, Limagrain, Bayer CropScience, Land O'Lakes, KWS SAAT, Corteva Agriscience, AgReliant Genetics, Beck's Superior Hybrids, Syngenta, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Grain Seed Market Evolving Landscape
Gene editing platforms are collapsing the development cycle for novel agronomic traits, while regulatory sandboxes and digital distribution channels are rewiring how seed reaches the farm gate across the US and Canada.
CRISPR-Cas9 and base editing systems are decomposing the traditional 8-12 year breeding timeline for drought tolerance and disease resistance traits. Regional seed companies in the Midwest are licensing these platforms from technology providers to accelerate proprietary variety development. The structural consequence is compressing competitive moats around germplasm innovation speed rather than germplasm scale alone.
USDA APHIS finalized its revised Part 340 framework in 2020, exempting certain gene-edited crops from biotechnology regulation if they could be produced through conventional breeding. Seed developers are now routing more products through this exemption pathway to avoid EPA and FDA dual review. The Iowa and Illinois corn markets are seeing the fastest pipeline acceleration as companies prioritize stacked-trait platforms for the Corn Belt.
Large-scale corn and soybean growers are consolidating seed purchasing through cooperative buying groups and direct manufacturer contracts, displacing independent dealer relationships. These aggregators negotiate volume-based trait licensing and agronomic service bundles. The shift is most pronounced in Nebraska and Indiana, where 5,000-plus acre operations now represent the dominant procurement voice.
North America Grain Seed Market Segmentation
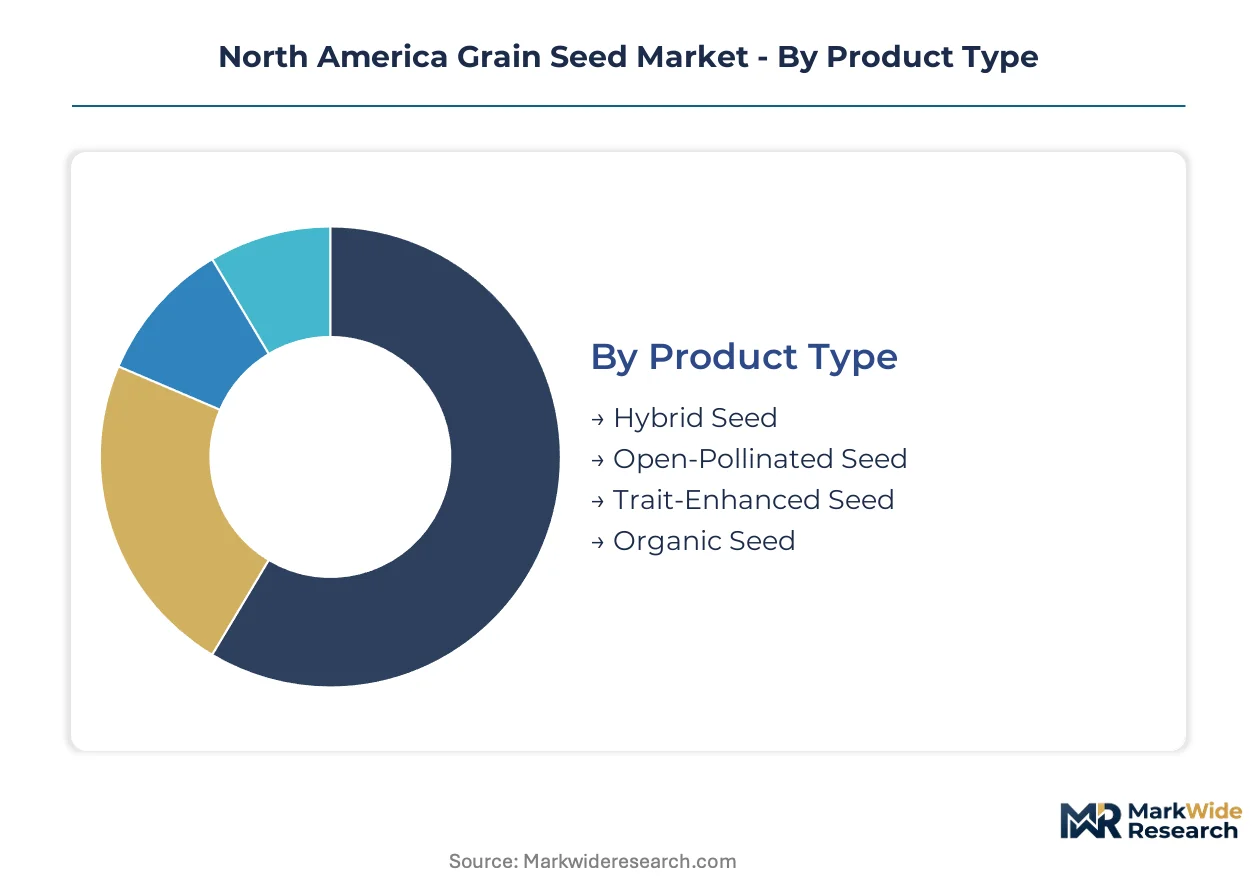
Grain seed segmentation in North America reflects divergent procurement patterns between domestic Corn Belt operators and export-oriented Prairie producers. Understanding these splits allows suppliers to align trait development, pricing architecture, and distribution investments with distinct farmer value chains.
Product Type:
Domestic demand concentrates in hybrid and trait-enhanced platforms for Iowa and Illinois corn-soy rotations, while organic and open-pollinated varieties serve niche export markets and specialty crop contracts.
- Hybrid Seed:Proprietary F1 crosses with genetic lock preventing farmer replant, commanding premium positioning through yield consistency and harvest uniformity. Demand clusters with large-scale Nebraska and Indiana operations contracting directly with breeders for volume-based trait licensing.
- Trait-Enhanced Seed:Stacked-trait platforms incorporating herbicide tolerance and insect resistance through transgenic or gene-edited insertion. USDA APHIS Part 340 exemptions are accelerating pipeline velocity for Corn Belt deployment.
- Open-Pollinated Seed:Self-pollinating varieties allowing farmer seed saving, concentrated in wheat and barley segments across the Canadian Prairies where farm-saved seed laws permit retention.
- Organic Seed:Certified non-GMO material meeting National Organic Program standards, supply-constrained by limited varietal availability and 15-25% yield parity gaps against conventional alternatives.
Hybrid seed holds the largest share; momentum sits with trait-enhanced platforms as gene-edited varieties compress development timelines.
Distribution Channel:
Channel selection tracks farm scale and digital maturity, with cooperatives dominating mid-tier acreage while direct channels capture enterprise operations above 5,000 acres.
- Retail Stores:Independent dealers and farm supply retailers providing localized agronomic support and credit terms. Share is eroding in Illinois and Iowa as cooperative buying groups consolidate procurement leverage.
- Agricultural Cooperatives:Member-owned purchasing alliances negotiating volume discounts and bundled agronomic services. CHS and Land O'Lakes networks anchor cooperative seed distribution across the Upper Midwest.
- Direct Sales:Manufacturer-to-farm contracts eliminating dealer margins, fastest-expanding channel for stacked-trait corn in Nebraska and Kansas feedlot supply chains.
- Online Platforms:E-commerce portals with satellite imagery-based prescription services, penetrating younger operator demographics in Indiana and Ohio.
Agricultural cooperatives retain the largest share; direct sales channels are expanding most quickly as large operators consolidate procurement.
Cultivation Method:
Method segmentation reflects input cost pressures and sustainability incentive structures, with precision agriculture adoption tracking farm size and equipment capitalization capacity.
- Conventional Farming:Synthetic input-dependent systems utilizing standard tillage and broadcast application, still dominant across Kansas and Missouri dryland corn.
- Precision Agriculture:Variable-rate seeding and input application guided by GPS and yield mapping, concentrated in Iowa and Illinois where equipment cooperatives reduce technology adoption barriers.
- Sustainable Agriculture:Reduced-tillage and cover crop integration qualifying for USDA Climate-Smart Commodities grants, expanding in Minnesota and Wisconsin.
- Organic Farming:Synthetic input prohibition with mandatory three-year transition, constrained by certification costs and limited organic grain handling infrastructure.
Conventional farming holds the largest share; precision agriculture is gaining share fastest as equipment financing and data analytics mature.
End User:
End-user structure differentiates between price-taking farmers and price-making grain processors, with research institutions serving as gatekeepers for varietal release decisions.
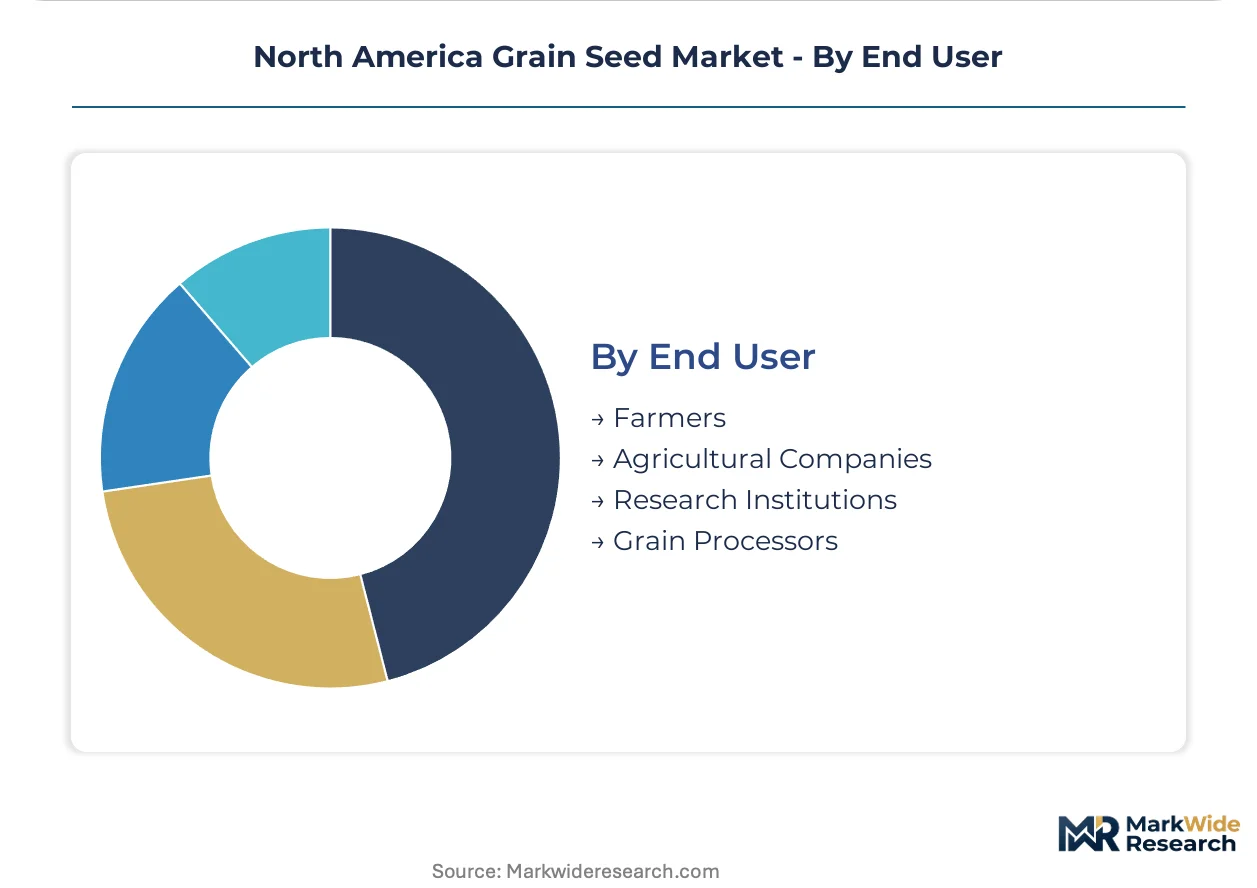
- Farmers:Primary decision-makers for seed selection, segmented by acreage scale from sub-500 acre part-time operations to 10,000-plus acre enterprises in the Red River Valley.
- Grain Processors:End-user processors and exporters contracting for specific protein, oil, or starch profiles, increasingly specifying certified seed provenance for identity-preserved supply chains.
- Agricultural Companies:Corporate farming operations and farm management companies centralizing seed procurement across dispersed landholdings.
- Research Institutions:Land-grant universities and USDA ARS stations conducting varietal trials that determine commercial release eligibility through state crop improvement associations.
Farmers hold the largest share; grain processors are expanding influence fastest through identity-preserved contracting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA biotechnology deregulation through APHIS Part 340 exemptions accelerates trait-enhanced seed commercialization across the continent. Canadian Food Inspection Agency seed certification requirements and US state seed laws shape cross-border market access. Demand concentrates in the Corn Belt and Canadian Prairies where large-scale operators drive procurement consolidation.
United States
Commercial feedlot operators in Nebraska and Kansas contract directly for high-yield corn with specified protein profiles. EPA pesticide tolerance reviews expedite stacked-trait approvals for herbicide-resistant platforms. Iowa and Illinois seed markets anchor Corn Belt demand where cooperative buying groups displace independent dealer relationships.
Canada
Saskatchewan and Manitoba spring wheat and canola markets remain underpenetrated by US trait-enhanced platforms. Canadian Food Inspection Agency seed certification requirements govern varietal registration and cross-border product labeling. Prairie farm operations above 5,000 acres centralize procurement through direct manufacturer contracts.
Mexico
Import-dependent grain production drives demand for US hybrid corn seed in Sinaloa and Sonora irrigation districts. Mexico's national seed certification system aligns with OECD varietal testing protocols for cross-border trade. Bajío Region feedlot expansion contracts for specified energy-content corn from US germplasm suppliers.
North America Grain Seed Market Competitive Landscape
Player mix skews toward vertically integrated multinationals controlling proprietary trait pipelines and germplasm libraries. Three entities dominate over 70% of US corn and soybean genetics, creating tiered competitive structure with regional specialists occupying niche positions. Strategic archetypes include trait-platform licensors, regional breeding specialists, and cooperative-backed distributors. Competitive moves center on gene-editing platform licensing and direct-to-farm digital channel expansion.
Within the multinational tier, Bayer CropScience and Corteva Agriscience anchor market structure through integrated trait development and broad distribution infrastructure. Among cooperative-aligned entities, Land O'Lakes occupies a position linking farmer ownership with seed procurement scale. Regional specialists exemplified by Beck's Superior Hybrids sit within the Midwest-focused breeding segment.
| Leading Market Players |
|---|
| BASF |
| Limagrain |
| Bayer CropScience |
| Land O'Lakes |
| KWS SAAT |
| Corteva Agriscience |
| AgReliant Genetics |
| Beck's Superior Hybrids |
| Syngenta |
| Others |
Value Network & Pricing Analysis
Thousand-acre seed production blocks in Idaho's Treasure Valley create scale efficiencies that compress unit costs for certified hybrid corn, simultaneously concentrating germplasm supply in irrigation-dependent geographies and establishing price floors that smaller breeding programs cannot match. This concentration dynamic locks procurement leverage with multinationals while exposing regional specialists to input cost volatility.
Pricing Analysis
Certification tier under the Association of Official Seed Certifying Agencies creates the primary spread between foundation seed and registered commercial classes. Three-tier pricing structure across elite genetics, standard certified, and farm-saved retention levels segments farmer willingness-to-pay by acreage scale and replant restrictions. Cost compression in standard certified tiers is intensifying because irrigation water allocation cuts in Oregon's Willamette Valley are squeezing production yields. Price sensitivity concentrates among sub-500-acre part-time operators in Missouri and Kansas, while Nebraska feedlot contractors show inelastic demand for specified protein-profile hybrids.
Supply Chain Analysis
Idaho, Oregon, and California's Central Valley anchor North American certified seed multiplication, with isolated acreage climates enabling genetic purity maintenance through spatial isolation. The supply chain draws from captive parent seed stocks, contracted grower networks, and climate-controlled storage infrastructure. Single-source vulnerability runs through Bureau of Reclamation water allocations that govern irrigation availability across the Snake River Plain. Distribution runs through agricultural cooperatives and direct manufacturer contracts, with cooperative buying groups displacing independent dealers across Iowa and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germplasm innovation velocity now outpaces capital deployment capacity, creating selective scarcity around CRISPR platform access and trait-stack licensing expertise. Incumbents and challengers face divergent capability gaps that reshape competitive positioning.
For Market Incumbents: Shield proprietary trait pipelines through accelerated Part 340 exemption filings that compress competitor launch windows. Deepen backward integration into Idaho and Oregon seed production acreage to secure irrigation-dependent capacity against Bureau of Reclamation allocation volatility. Channel control through direct-to-farm digital platforms represents the priority lever for displacing cooperative buying group intermediation.
For New Entrants and Emerging Players: Differentiate on regional adaptation speed by licensing gene-editing platforms for Midwestern-specific disease resistance traits that multinationals deprioritize. Saskatchewan and Manitoba spring wheat markets offer the most penetrable geography, with Canadian Food Inspection Agency registration pathways creating first-mover positioning ahead of US trait-enhanced platform expansion. A cooperative-backed distribution partnership with Land O'Lakes or CHS networks provides credible go-to-market scale without captive germplasm libraries.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional breeding specialists with licensed CRISPR access and established varietal performance data in underpenetrated geographies. Acquisition targets should demonstrate proprietary yield trial networks and state crop improvement association relationships that accelerate commercial release eligibility. The signal to watch is USDA APHIS Part 340 petition filing velocity as an indicator of pipeline competitiveness against streamlined regulatory pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Platform Licensing | Accelerates proprietary variety development timelines for regional adaptation traits. |
| Direct-to-Farm Digital Channel Buildout | Bypasses cooperative buying groups in Iowa and Illinois to capture enterprise acreage. |
| Canadian Prairie Registration Push | Secures CFIA varietal approval ahead of US competitor trait-enhanced platform entry. |
| Idaho-Oregon Production Acreage Expansion | Locks irrigation-dependent certified seed capacity against Bureau of Reallocation shortages. |
| USDA Climate-Smart Bundle Integration | Qualifies farmer customers for carbon credit offset markets through cover crop seed pairing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed breeding directors, cooperative procurement managers, feedlot nutritionists, and USDA APHIS regulatory leads. Secondary validation drew from Association of Official Seed Certifying Agencies certification databases, EPA pesticide tolerance dockets, SEC 10-K filings of publicly traded agribusiness entities, and state seed law compendia. Bottom-up acreage deployment models and top-down germplasm revenue estimates were triangulated to constrain forecast variance.
Across the analysis window, projections integrate product type segmentation by genetic class, distribution channel evolution by farm scale tier, and cultivation method adoption curves for precision agriculture platforms. CAGRs were derived from historical certified seed shipment volumes and forward-looking trait penetration assumptions. Key forecast inputs include USDA biotechnology deregulation pipeline velocity and Canadian Food Inspection Agency registration timeline compression.
Decision-makers should treat outputs as directional under sustained EPA tolerance review expedition and stable irrigation water allocation baselines; material deviation would warrant model refresh. Specific risk factors include pending state-level dicamba restriction expansions and organic transition acreage acceleration that could reroute conventional seed demand. Recalibration cycles align with material shifts in Part 340 exemption petition approval velocity and Prairie province trait-enhanced platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Perilla Seed Oil Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Cherry Tomato Seeds Market
Seeds
Seed Cracker Market
Seeds
Quinoa Seed Market
Seeds
Europe Cannabis Seeds Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Fruit Seed Waste Market
Seeds
South America Quinoa Seeds Market
Seeds
Europe Seed Market
Seeds
Mexico Seed Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
North America Seeds Market
Seeds
Wax Gourd Seed Market
Seeds
Dragon Fruit Seeds Market