
 Ferrofluid Market | 2026-2036
Ferrofluid Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrofluid Market Intelligence
The ferrofluid supply base is rebalancing between premium synthetic formulations and commodity hydrocarbon grades as semiconductor OEMs impose tighter particle-size tolerances. Ferrotec Holdings Corporation leverages its captive magnetite sourcing to control batch consistency across Asian fabrication lines. American Elements anchors North American supply through domestic rare-earth refining and custom alloy capabilities. Evonik Industries differentiates via surface-chemistry IP that extends fluid stability in high-vacuum sealing environments.
Ferrofluid comprises nanoscale magnetite or cobalt ferrite particles suspended in carrier liquids and stabilized by surfactant coatings, typically exhibiting saturation magnetization between 100 and 400 Gauss for industrial sealing and damping functions. Oil-based ferrofluid dominates current volume owing to thermal stability in loudspeaker voice-coil cooling and rotary seal applications, while biomagnetic fluid commands the steepest value premiums in cell separation and targeted drug delivery protocols. Spintronic devices represent the fastest-growing technology segment as magnetic tunnel junction research accelerates at university-industry consortia.
EPA oversight of volatile organic compounds in carrier solvents and REACH registration of ferrofluid surfactants are elevating compliance costs for non-European exporters seeking European electronics and semiconductor access. Japan's METI maintains JIS standards for magnetic fluid seals in precision equipment that constrain import specifications for foreign suppliers. Stakeholders must monitor evolving semiconductor equipment OEM qualification protocols and dual-use export control expansions affecting magnetite nanoparticle shipments.
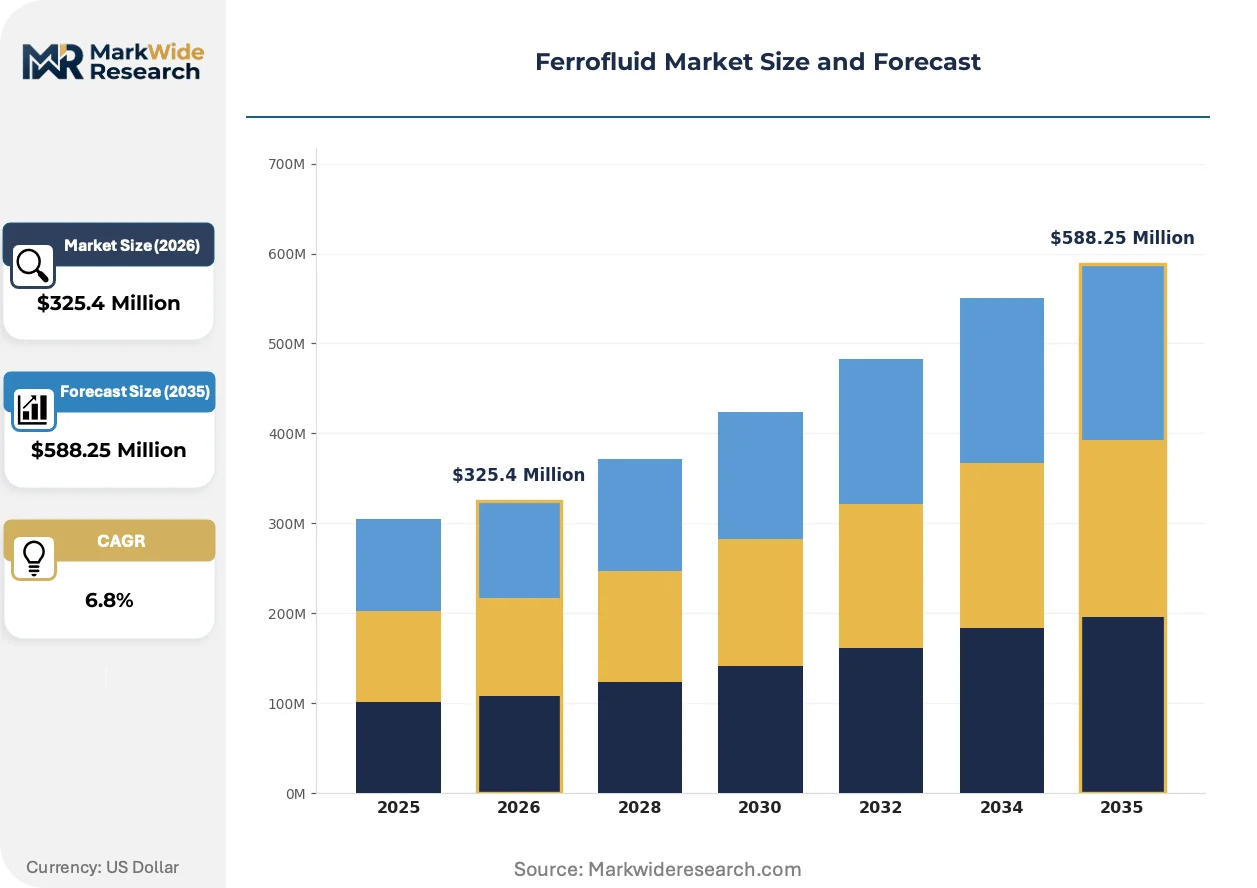
Market Dynamics
Semiconductor OEMs are tightening particle-size tolerances for magnetic sealing fluids, forcing suppliers to rebalance between premium synthetic formulations and commodity hydrocarbon grades while navigating REACH and EPA surfactant chemistry mandates.
Growth Catalysts
- Wafer Processing Complexity:Advanced lithography nodes below 7nm require higher-precision ferrofluid seals in vacuum chambers, pulling demand from Taiwanese and South Korean fabrication clusters.
- REACH Registration Requirements:European electronics manufacturers now mandate certified surfactant chemistries, creating qualification barriers that favor established suppliers with ECHA-compliant dossiers.
- Spintronic Device Research:University-industry consortia accelerating magnetic tunnel junction development are consuming specialized cobalt ferrite formulations for prototype testing.
Market Restraints
- Rare Earth Concentration:Magnetite nanoparticle feedstock depends on Chinese rare-earth refining capacity, exposing non-integrated formulators to export quota volatility.
- Carrier Solvent Costs:EPA oversight of volatile organic compounds in hydrocarbon bases is elevating formulation costs for loudspeaker cooling applications.
- Biomagnetic Fluid Substitution:Polymer-based magnetic beads in cell separation protocols are displacing oil-based ferrofluid in certain diagnostic workflows.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are creating first-mover advantages for ferrofluid seal suppliers qualifying with BIS standards.
- Targeted Drug Delivery:Surface-functionalized biocompatible ferrofluid for hyperthermia oncology treatment represents unpenetrated clinical trial partnerships.
- Dual-Use Export Controls:Expanding magnetite nanoparticle shipment restrictions are creating technical service revenue streams for compliance documentation.
Industry Challenges
- Surfactant Chemistry Talent:Formulators with expertise in high-vacuum stability optimization are concentrated among retiring Japanese specialists.
- OEM Qualification Timelines:Semiconductor equipment manufacturers impose 18-24 month validation protocols that freeze supplier switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrofluid Market |
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $588.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Based Ferrofluid, Water-Based Ferrofluid, Biomagnetic Fluid, Hollow Magnetic Fluid Application: Sealing, Loudspeakers, Dampers, Medical Imaging, Precision Bearings, Heat Transfer Technology: Magnetorheological, Electroferrohydrodynamic, Magnetic Colloids, Spintronic Devices End User Industry: Electronics & Semiconductors, Automotive OEMs, Aerospace Assemblers, Biotech Laboratories |
| Companies Covered | American Elements, Ioniqa Technologies, Ferrotec Holdings Corporation, DOWA Electronics Materials, Evonik Industries, Parker Hannifin Corporation, Sigma-Aldrich Corporation, Moretec, Liquids Research Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrofluid Market Strategic Shifts & Innovations
Active reformulation of carrier liquids and surfactant architectures is compressing product lifecycles while regulatory chemistry disclosure requirements are rewriting competitive moats.
Synthetic ester-based ferrofluid with enhanced thermal stability above 200°C is overtaking traditional hydrocarbon grades in rotary seal applications. German precision bearing manufacturers are specifying these formulations for vacuum pump assemblies. The shift is compressing margins for commodity-grade suppliers locked into mineral oil chemistries.
REACH registration of ferrofluid surfactants under ECHA's 2023 updated guidance is forcing reformulation of legacy products. Non-European exporters face elevated compliance costs to maintain European electronics and semiconductor market access. Japanese suppliers with pre-registered dossiers are capturing qualification-driven substitution opportunities.
Semiconductor OEMs are consolidating supplier panels from six to three qualified ferrofluid sources per equipment platform. Equipment manufacturers in South Korea are demanding captive inventory agreements and localized blending capacity. This concentration is most visible in the Hsinchu Science Park cluster, where TSMC suppliers face dual-sourcing mandates.
Ferrofluid Market Segmentation
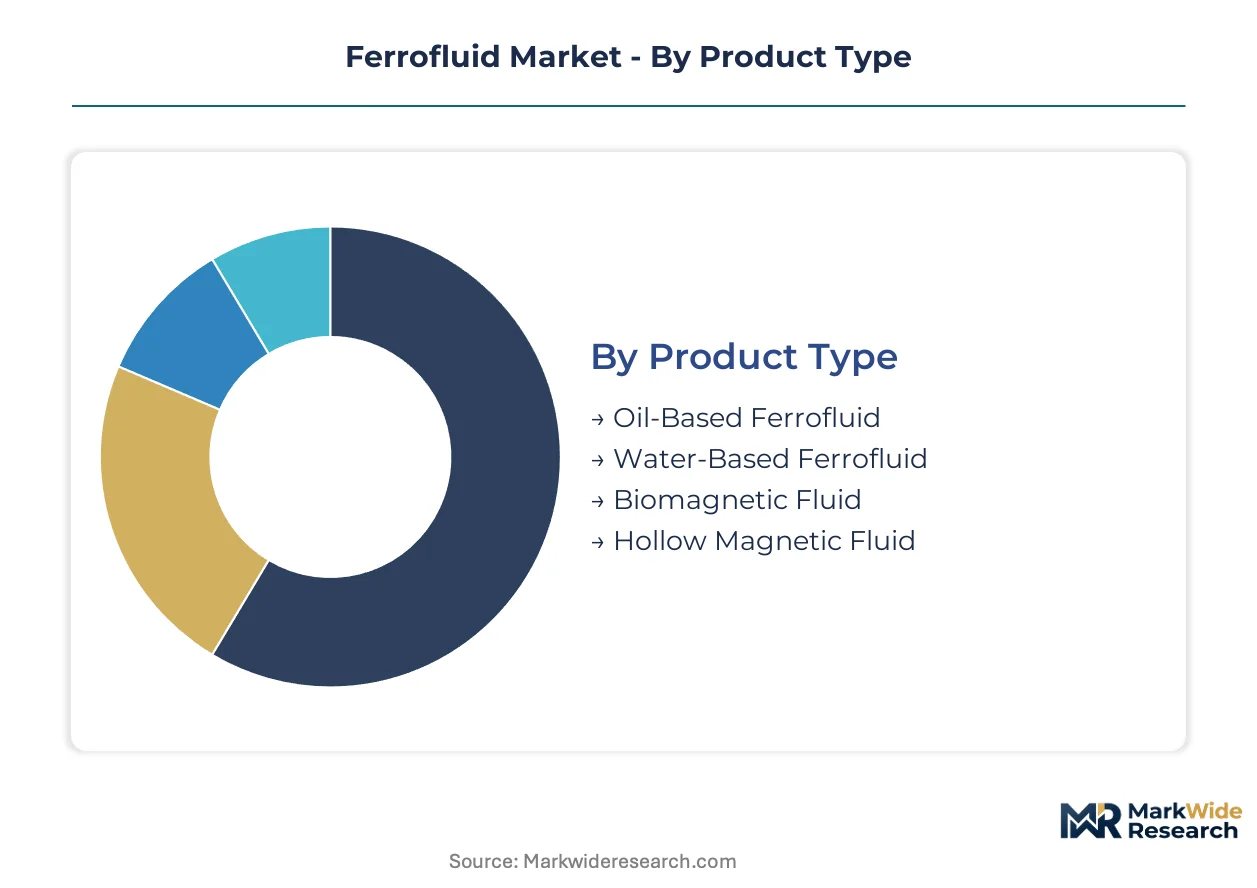
Ferrofluid formulations diverge sharply between commodity hydrocarbon grades and precision-engineered synthetics. Semiconductor OEM qualification protocols and surfactant chemistry regulations are compressing the viable supplier base across each segment tier.
Product Type:
Oil-based formulations dominate current shipment volumes, while water-based and biomagnetic variants command escalating premiums in specialized applications.
- Oil-Based Ferrofluid:Mineral oil and synthetic ester carriers suspend magnetite nanoparticles at 100-400 Gauss saturation magnetization. Taiwanese and South Korean semiconductor fabrication clusters consume these formulations for rotary vacuum seals as wafer processing nodes shrink below 7nm.
- Biomagnetic Fluid:Surface-functionalized dextran or PEG coatings enable biocompatibility for hyperthermia oncology protocols and magnetic cell separation. Clinical trial partnerships at university medical centers are pulling demand faster than manufacturing scale-up can match.
- Water-Based Ferrofluid:Aqueous surfactant systems serve environmental monitoring and educational demonstration markets where hydrocarbon volatility is restricted.
- Hollow Magnetic Fluid:Microbubble-encapsulated formulations target buoyancy-driven separation processes in mining tailings recovery and wastewater treatment.
Mature deployment sits with oil-based grades in loudspeaker voice-coil cooling. Newer deployment is concentrated in biomagnetic fluid for targeted drug delivery pipelines.
Application:
Sealing functions anchor industrial demand, while medical and precision bearing applications are climbing the fastest as tolerance requirements tighten.
- Sealing:Rotary shaft seals in vacuum chambers leverage ferrofluid response to magnetic fields for zero-leakage performance. South Korean equipment manufacturers specify captive inventory agreements for qualified seal formulations.
- Loudspeakers:Voice-coil gap cooling in high-fidelity audio drivers consumes commodity hydrocarbon grades. EPA volatile organic compound oversight is elevating formulation costs for mineral oil carriers.
- Dampers:Magnetorheological shock absorption in precision instrumentation benefits from millisecond viscosity modulation under field excitation.
- Medical Imaging:Contrast enhancement in MRI protocols utilizes superparamagnetic nanoparticle suspensions with optimized relaxivity profiles.
- Precision Bearings:German vacuum pump manufacturers are specifying synthetic ester ferrofluids with thermal stability above 200°C for bearing assemblies.
- Heat Transfer:Thermal management in closed-loop cooling systems exploits field-controllable convection patterns.
Volume concentration remains in sealing and loudspeaker cooling. Steepest expansion trajectory belongs to precision bearings as thermal specifications harden.
Technology:
Magnetic colloid stability IP separates incumbent suppliers from commodity blenders, while spintronic research is opening adjacent demand channels.
- Magnetic Colloids:Surfactant-stabilized magnetite or cobalt ferrite nanoparticles in carrier liquids constitute the foundational manufacturing architecture. Japanese specialists with high-vacuum stability expertise are retiring, constraining talent availability.
- Spintronic Devices:Magnetic tunnel junction prototypes consume specialized cobalt ferrite formulations from university-industry consortia. Research acceleration at Asian and North American laboratories is outpacing commercial production scale.
- Magnetorheological:Field-responsive viscosity modulation serves automotive damper and industrial vibration isolation applications.
- Electroferrohydrodynamic:Combined electric and magnetic field manipulation enables microfluidic pumping in lab-on-chip diagnostic platforms.
Commercial revenue concentrates in magnetic colloid formulations. Device-level integration is advancing fastest in spintronic research programs.
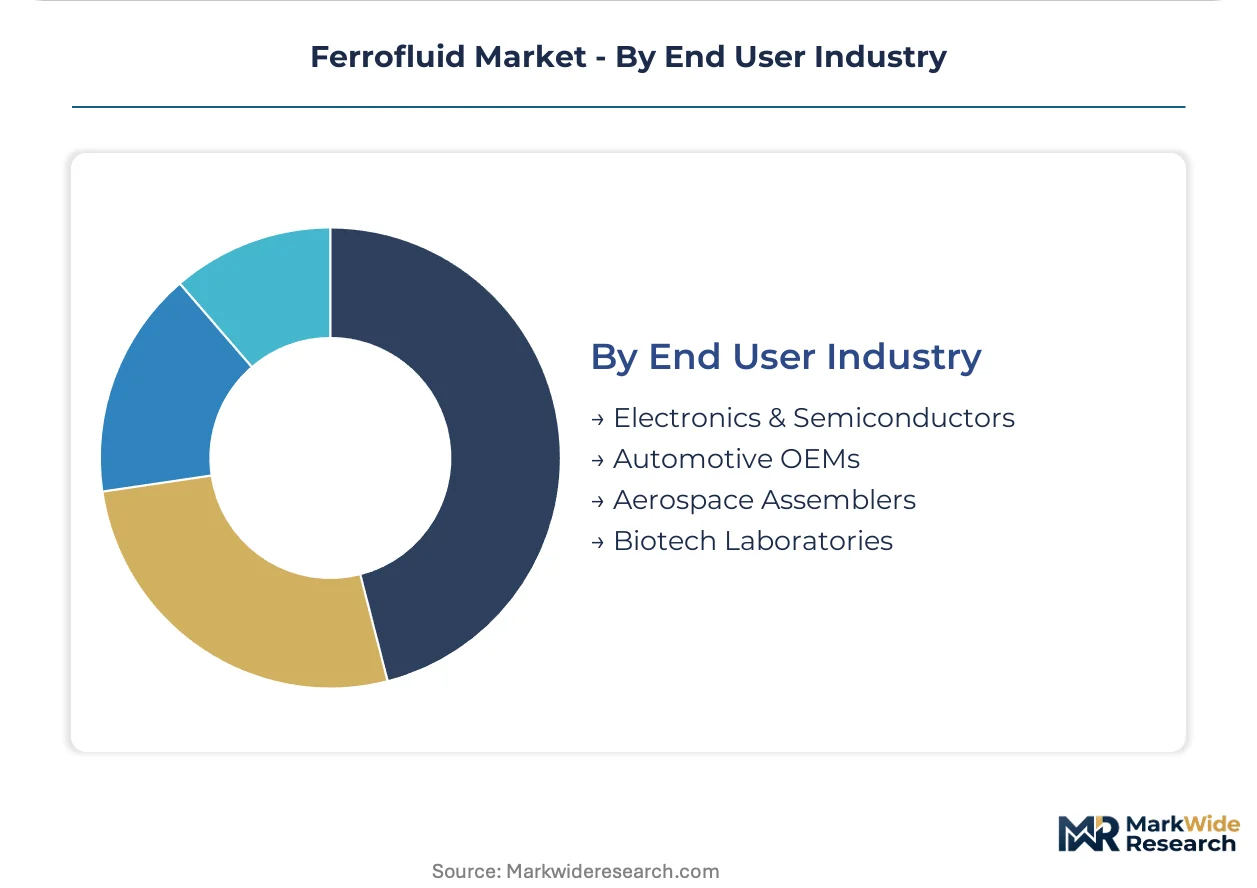
End User Industry:
Electronics manufacturing qualification timelines freeze supplier relationships, while biotech partnerships remain underpenetrated.
- Electronics & Semiconductors:Equipment OEMs impose 18-24 month validation protocols that consolidate supplier panels from six to three qualified sources per platform. TSMC suppliers in Hsinchu face dual-sourcing mandates.
- Biotech Laboratories:Cell separation and diagnostic workflows are displacing oil-based ferrofluid with polymer magnetic beads in certain protocols, constraining growth.
- Automotive OEMs:Magnetorheological damper applications in premium vehicle suspensions require field-proven batch consistency.
- Aerospace Assemblers:Satellite bearing and gyroscope damping specifications demand radiation-hardened ferrofluid stability.
Locked-in procurement characterizes electronics and semiconductor relationships. Partnership formation is accelerating fastest in biotech laboratories as clinical trial pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan concentrates the world's most demanding ferrofluid specifications as TSMC and its supplier ecosystem enforce dual-sourcing mandates for magnetic sealing fluids in vacuum chambers.
United States
Domestic rare-earth refining at American Elements anchors North American magnetite nanoparticle supply for semiconductor OEMs. EPA oversight of volatile organic compounds in hydrocarbon carrier solvents elevates formulation costs for loudspeaker cooling applications. The Pacific Northwest hosts precision bearing manufacturers specifying synthetic ester ferrofluids with thermal stability above 200°C.
Japan
METI maintains JIS standards for magnetic fluid seals in precision equipment that constrain import specifications for foreign suppliers. Retiring Japanese specialists with high-vacuum stability expertise are creating talent scarcity for surfactant chemistry optimization. The Chubu region around Nagoya houses vacuum pump manufacturers consolidating supplier panels from six to three qualified ferrofluid sources.
South Korea
Samsung and SK Hynix fabrication clusters demand captive inventory agreements and localized blending capacity for rotary seal formulations. Equipment manufacturers impose 18-24 month validation protocols that freeze supplier switching once qualified. The Suwon-Yongin corridor represents the densest concentration of ferrofluid specification activity outside Taiwan.
Germany
REACH registration under ECHA's updated 2023 guidance forces reformulation of legacy surfactant chemistries for European electronics market access. German precision bearing manufacturers specify synthetic ester-based ferrofluids overtaking traditional hydrocarbon grades in vacuum pump assemblies. The Baden-Württemberg industrial belt drives qualification-driven substitution opportunities for ECHA-compliant dossier holders.
India
PLI scheme incentives for semiconductor packaging create first-mover advantages for ferrofluid seal suppliers qualifying with BIS standards. Domestic electronics manufacturing clusters in Karnataka and Tamil Nadu are establishing initial ferrofluid specification relationships as packaging capacity expands. The Bengaluru-Chennai corridor represents the fastest-emerging demand node for magnetic sealing applications in South Asia.
Ferrofluid Market Key Industry Players
Premium-margin players sit above commodity-margin players across surfactant chemistry sophistication and OEM qualification depth. The supplier base compresses into three qualified sources per equipment platform as semiconductor manufacturers consolidate panels. Three archetypes dominate: integrated magnetite refiners with captive nanoparticle supply, specialty chemical houses with surface-chemistry IP, and precision component specialists with seal assembly integration. Competitive moves concentrate on backward integration into rare-earth refining and geographic expansion through localized blending capacity.
Within the integrated-refiner archetype, Ferrotec Holdings Corporation exemplifies players leveraging captive magnetite sourcing to control batch consistency across Asian fabrication lines. Among specialty chemical houses, Evonik Industries occupies a position defined by surface-chemistry IP extending fluid stability in high-vacuum sealing environments. At the materials-supply tier, American Elements anchors North American presence through domestic rare-earth refining capabilities.
| Leading Market Players |
|---|
| American Elements |
| Ioniqa Technologies |
| Ferrotec Holdings Corporation |
| DOWA Electronics Materials |
| Evonik Industries |
| Parker Hannifin Corporation |
| Sigma-Aldrich Corporation |
| Moretec |
| Liquids Research Limited |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between REACH-registered synthetic esters and commodity hydrocarbon bases manifests in divergent margin structures and procurement patterns across semiconductor OEMs and industrial buyers. Premium formulations command value-based pricing anchored to vacuum chamber uptime guarantees, while mineral oil grades compete on volume scale in loudspeaker cooling applications. This tier divergence reshapes supplier investment priorities toward ECHA dossier maintenance and captive magnetite refining capacity.
Pricing Analysis
Value-based pricing tied to equipment uptime performance dominates semiconductor sealing applications, with synthetic ester formulations carrying thermal stability premiums over commodity hydrocarbon grades. Price differentiation separates ECHA-compliant REACH dossier holders from non-registered exporters facing qualification barriers in European electronics markets. Cost compression in loudspeaker voice-coil cooling intensifies as EPA volatile organic compound oversight elevates mineral oil carrier formulation expenses. Contract manufacturers in Taiwanese fabrication clusters exhibit lowest price sensitivity due to dual-sourcing mandates and captive inventory requirements, while educational and demonstration markets drive hard bargains on water-based ferrofluid volumes.
Supply Chain Analysis
Direct-to-OEM channels handle semiconductor equipment manufacturer demand through qualified supplier panels consolidated from six to three sources per platform. Geographic supply concentration centers on Chinese rare-earth refining for magnetite nanoparticle feedstock, Japanese high-vacuum stability expertise for surfactant chemistry, and German precision bearing integration for synthetic ester formulations. Raw material dependencies include rare-earth oxide concentrates, synthetic ester carrier liquids, and specialized surfactant polymers. Single-source vulnerability in Chinese magnetite refining exposes non-integrated formulators to export quota volatility and dual-use control expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ferrofluid market is becoming a vertical-integration race as players pursue captive magnetite sourcing to secure batch consistency and insulate margin structures from rare-earth export volatility.
For Market Incumbents: Cement qualification depth through backward integration into rare-earth refining and localized blending capacity in South Korean and Taiwanese fabrication corridors. Defend panel positions by accelerating surfactant chemistry talent retention programs as Japanese high-vacuum specialists retire. Prioritize ECHA dossier updates ahead of evolving REACH guidance to maintain European electronics market access against emerging competitors. For New Entrants and Emerging Players: Launch via clinical trial partnerships in hyperthermia oncology protocols where biomagnetic fluid manufacturing scale-up lags demand pull. Target Indian semiconductor packaging clusters under PLI scheme incentives before incumbent qualification timelines freeze supplier relationships. Pursue white-space in hollow magnetic fluid formulations for mining tailings recovery applications underserved by established oil-based suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated magnetite refiners possessing captive nanoparticle supply and pre-registered REACH dossiers given tightening European surfactant chemistry mandates. Long-term viability across the analysis window favors suppliers with dual-use export control compliance infrastructure and university-industry consortium relationships in spintronic device research. Monitor OEM validation protocol completion rates as inflection indicators for supplier panel consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Captive magnetite supply insulates Ferrotec and American Elements from Chinese export quota volatility. |
| REACH Dossier Registration and Maintenance | ECHA-compliant surfactant chemistry secures European electronics market access against non-registered competitors. |
| Localized Blending Capacity Expansion | South Korean equipment manufacturers demand captive inventory agreements and regional formulation presence. |
| Surfactant Chemistry Talent Acquisition | Retiring Japanese high-vacuum stability specialists constrain formulation optimization capabilities industry-wide. |
| Clinical Trial Partnership Formation | University medical center collaborations in hyperthermia oncology pull biomagnetic fluid demand faster than manufacturing scale-up. |
Research Approach
Trade databases, ECHA registration filings, and semiconductor equipment OEM technical specifications formed the secondary backbone, cross-referenced against primary interviews with surfactant chemistry formulators, vacuum pump procurement leads at German precision bearing manufacturers, and regulatory affairs directors at specialty chemical houses. Plant managers at Taiwanese fabrication facilities and Japanese magnetic fluid seal specialists provided operational validation. Bottom-up shipment estimates triangulated against top-down rare-earth oxide consumption trends.
Historical trendline analysis of synthetic ester adoption rates in rotary seal applications and mineral oil displacement patterns in loudspeaker cooling established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type tiers, application-specific thermal stability requirements, end-user industry qualification timelines, and regional regulatory cluster variations. CAGR derivation rested on equipment OEM capex cycles, wafer processing node transition schedules, and surfactant chemistry reformulation waves.
The model assumes a particular technology adoption path; alternative pathways for cobalt ferrite spintronic device commercialization would alter the outlook for specialized formulation demand. Forecasts reflect base-case assumptions regarding REACH enforcement consistency, rare-earth export quota stability, and semiconductor capital expenditure continuity. Periodic stress-testing of base assumptions is recommended against dual-use control expansion announcements and surfactant chemistry talent migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Magnetostrictive Materials Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Magnetic Plastics Market