
 Fertilizer Spreader Market | 2026-2036
Fertilizer Spreader Market Size, Share, and Industry Trends Forecast 2026-2036
Fertilizer Spreader Market Analysis
Subscription-based telemetry and software-defined application mapping is recalibrating how fertilizer spreaders deliver value beyond hardware sales. Deere & Company leverages its precision agriculture platform to anchor recurring revenue streams across installed equipment bases. AGCO Corporation sustains competitive position through deep specialization in variable-rate control systems for broadcast spreaders. Kubota Corporation extends its geographic footprint in compact and mid-size tractor-integrated spreader configurations across Asian and North American markets.
A fertilizer spreader is a mechanized agricultural implement designed to distribute granular, powdered, or liquid nutrient formulations across soil surfaces at calibrated rates, typically featuring hopper capacities ranging from 50 to 2,000 liters and spreading widths from 6 to 42 meters depending on configuration. Its primary commercial purpose centers on optimizing crop yield potential through uniform nutrient placement while minimizing environmental runoff and input waste. Broadcast spreaders occupy the dominant share of volume due to their compatibility with large-field row-crop operations and lower per-acre operating costs. Electronic spreaders represent the fastest-expanding technology segment as GPS-guided rate control and section-shutoff capabilities command premium positioning and expand margin pools for manufacturers.
The United States EPA enforces nutrient management standards under the Clean Water Act that constrain application timing and rates near watersheds, directly shaping spreader specifications for runoff prevention. The EU Green Deal and F-Gas Regulation indirectly pressure equipment efficiency through broader farm sustainability audits, while ISO 12100 machinery safety standards govern guard design and operator interface requirements across export markets. Stakeholders must monitor how tightening nutrient-use-efficiency mandates in multiple jurisdictions will redefine the baseline feature set for market-accessible spreader models.
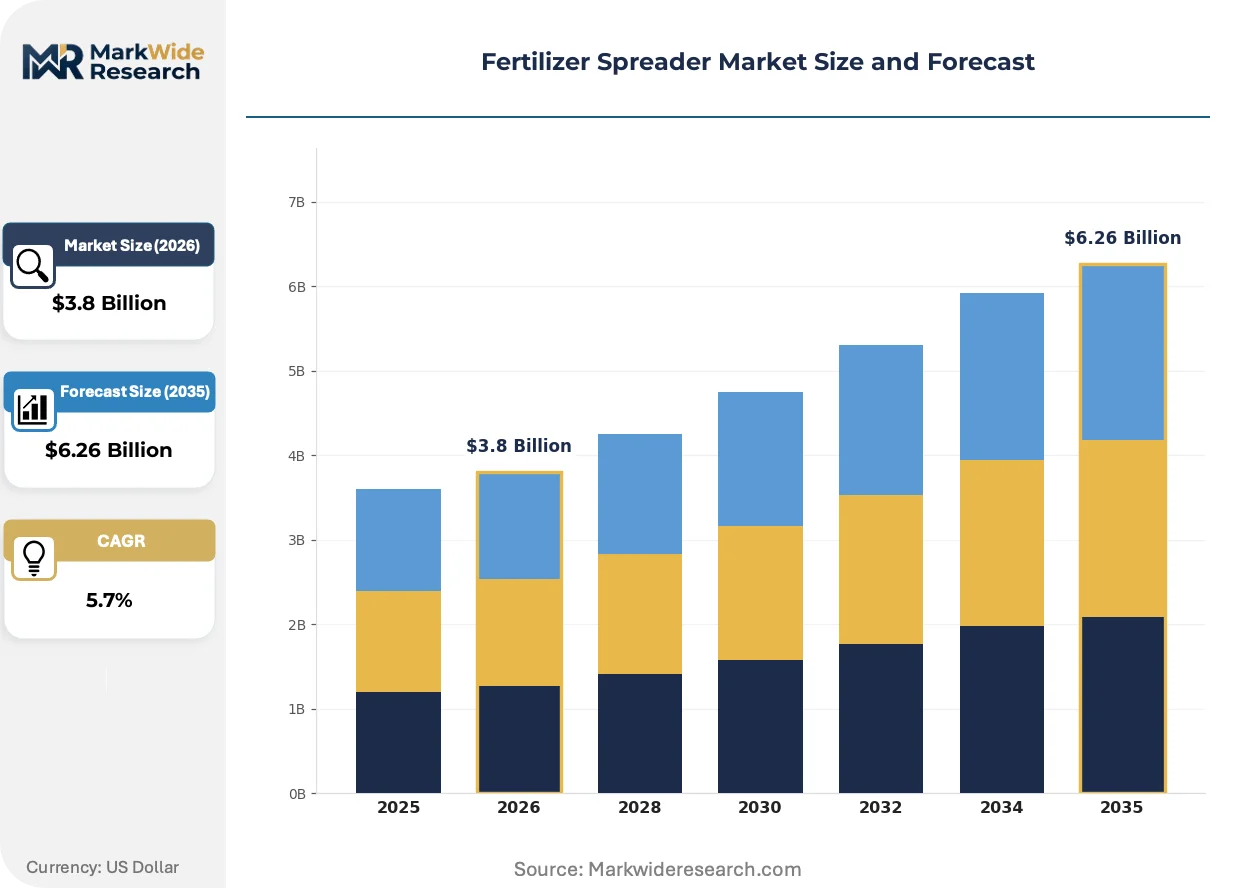
Market Dynamics
Precision agriculture telemetry is compressing equipment replacement cycles as farm operators upgrade to GPS-guided variable-rate systems that satisfy tightening nutrient-efficiency mandates. Large-scale consolidation in the United States Corn Belt concentrates purchasing power among fewer buyers demanding integrated software-hardware bundles.
Growth Catalysts
- EU Green Deal nutrient protocols:Mandatory application efficiency audits across member states force equipment upgrades toward section-shutoff and rate-control capabilities.
- Consolidated row-crop operations:Farm scale expansion in Iowa, Illinois, and Nebraska generates concentrated demand for high-capacity broadcast spreaders with telemetry integration.
- Variable-rate technology:GPS-enabled prescription mapping reduces input waste and commands premium positioning in equipment procurement specifications.
Market Restraints
- Steel and aluminum input volatility:Hopper and frame fabrication costs fluctuate with commodity metal pricing, squeezing manufacturer margins on fixed-price contracts.
- Electronic component supply concentration:GPS modules and rate controllers depend on concentrated Asian semiconductor fabrication, creating lead-time vulnerability.
- Clean Water Act enforcement:EPA nutrient management standards restrict application windows near watersheds, compressing annual equipment utilization rates.
Strategic Opportunities
- Subscription telemetry services:Recurring revenue from application mapping software creates margin expansion beyond one-time hardware sales.
- Compact tractor integration:Mid-size equipment segments in Japan and South Korea remain underpenetrated by precision-enabled spreader configurations.
- Section 45Z biofuel incentives:IRA credit programs for low-carbon crop production accelerate demand for documented nutrient placement accuracy.
Industry Challenges
- Precision agriculture technician shortage:Farm equipment dealers struggle to hire technicians capable of calibrating GPS-guided rate control systems.
- ISO 12100 compliance timelines:Machinery safety certification for guard design and operator interfaces delays new model introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertilizer Spreader Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broadcast Spreaders, Drop Spreaders, Tow-Behind Spreaders, Handheld Spreaders End User: Agricultural Producers, Lawn Care Companies, Landscapers, Home Gardeners Distribution Channel: Online Retail, Agricultural Supply Stores, Direct Sales, Garden Centers Technology: Mechanical Spreaders, Pneumatic Spreaders, Electronic Spreaders, Hybrid Spreaders |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Kubota Corporation, KUHN Group, CLAAS KGaA mbH, Adams Fertilizer Equipment, Mahindra & Mahindra Ltd., Bogballe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertilizer Spreader Market Emerging Trajectories
Electrification and software-defined functionality are reconfiguring how spreader manufacturers capture value, shifting competition from hardware specifications to integrated data-service ecosystems. Equipment buyers now evaluate total cost of ownership through lens of input optimization and regulatory compliance documentation.
Electric drive systems for spinner disc and belt conveyor mechanisms are electrifying traditional hydraulic-powered spreader architectures. Large-scale corn and soybean operations in Minnesota and Indiana are specifying electric drives for reduced maintenance intervals and precise RPM control. This electrification is compressing the service revenue model for dealer networks while enabling real-time torque feedback for obstruction detection.
REACH chemical registration requirements are extending to coating materials and corrosion inhibitors used in hopper construction. European manufacturers must reformulate surface treatments and document substance safety across supply chains. Broadcast spreader exporters targeting Germany and France are accelerating material substitutions to maintain market access.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale operations seeking to transfer technology obsolescence risk. Dealer networks in the Dakotas and Kansas are piloting per-acre spreading agreements bundled with agronomic advisory. This model concentrates most visibly among 500-2,000 acre farms lacking capital allocation flexibility for precision upgrades.
Fertilizer Spreader Market Segmentation
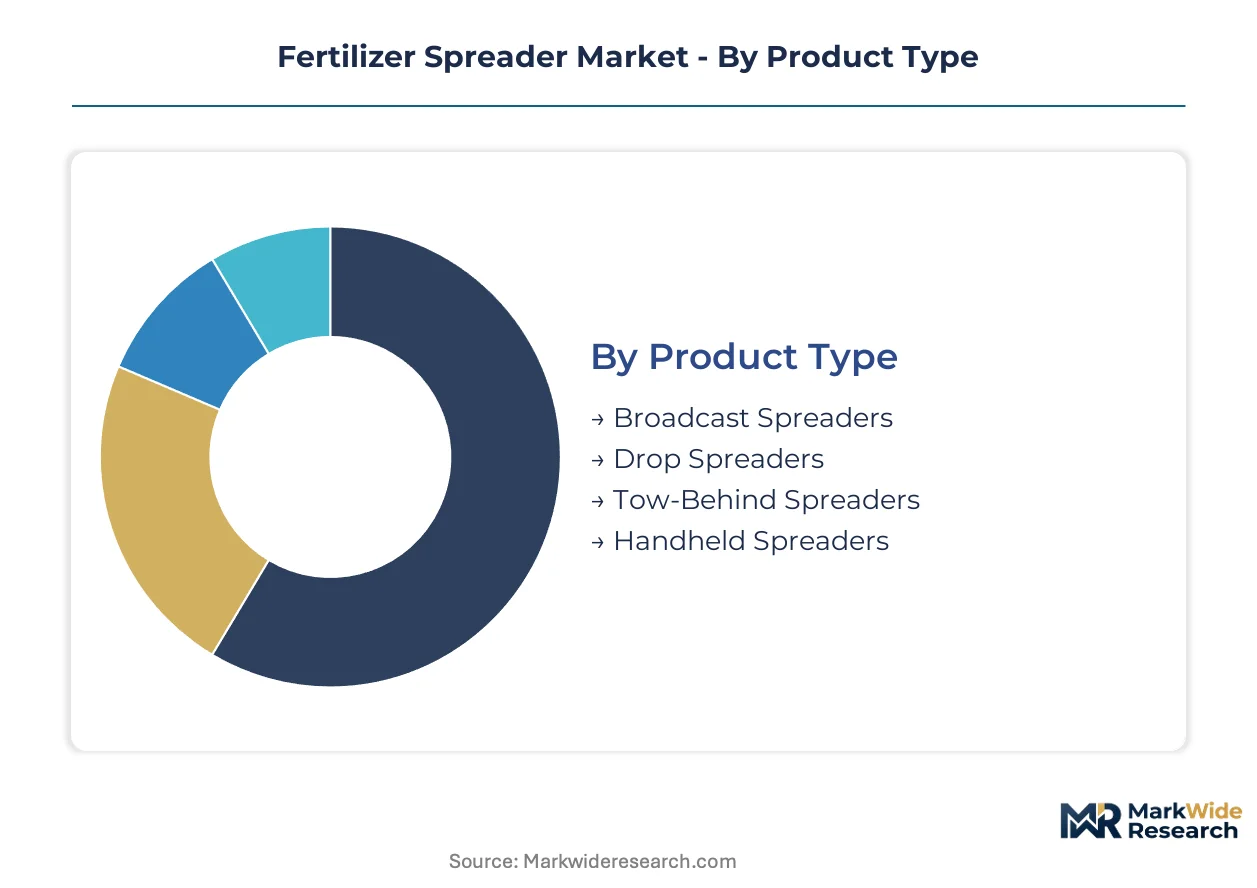
Equipment specification varies sharply across farm scale and precision requirements. Broadcast configurations dominate row-crop acreage while compact formats serve fragmented holdings. Technology tier selection directly correlates with regulatory compliance burdens and input cost optimization priorities.
Product Type:
Volume leadership sits with wide-swath broadcast equipment, while premium positioning concentrates in precision drop configurations.
- Broadcast Spreaders:Spinner disc or pendulum mechanisms distribute material across 12-42 meter widths from high-capacity hoppers. Demand concentrates in Iowa, Illinois, and Nebraska where corn-soybean operations exceeding 2,000 acres prioritize per-acre throughput and minimal labor input.
- Drop Spreaders:Gravity-fed systems release nutrients through calibrated openings directly beneath the unit, ensuring precise placement without drift. Lawn care companies in suburban Minneapolis and Kansas City corridors specify these for ornamental turf and athletic field applications where boundary precision is non-negotiable.
- Tow-Behind Spreaders:Trailed configurations attach to compact and mid-size tractors for operations lacking dedicated self-propelled equipment.
- Handheld Spreaders:Manual rotary units serve residential gardeners and small-scale landscaping maintenance.
Mature deployment sits with Broadcast Spreaders. Newer deployment is concentrated in Drop Spreaders as precision requirements tighten.
End User:
Customer procurement patterns split between capital-intensive agricultural enterprises and service-based maintenance operations.
- Agricultural Producers:Row-crop and specialty crop operations purchase equipment as depreciable farm assets with telemetry integration for compliance documentation. Consolidated operations in the Dakotas negotiate fleet pricing through dealer networks while leveraging Section 45Z biofuel incentives for documented nutrient placement accuracy.
- Lawn Care Companies:Commercial maintenance contractors prioritize equipment durability across high-cycle seasonal use. Franchised operations in Florida and Texas specify stainless steel hopper construction for corrosion resistance in humid climates.
- Landscapers:Design-build and maintenance contractors require versatile equipment transitioning between hardscape and turf applications.
- Home Gardeners:Residential consumers select based on storage footprint and seasonal use frequency.
Equipment-as-a-service contracting is expanding fastest among Lawn Care Companies. Direct ownership concentration remains highest among Agricultural Producers.
Distribution Channel:
Channel selection reflects purchase scale, technical support requirements, and financing complexity.
- Online Retail:E-commerce platforms capture handheld and compact tow-behind segments with transparent pricing and rapid fulfillment. Amazon and specialized agricultural marketplaces serve home gardeners and small landscapers in secondary markets lacking dealer infrastructure.
- Agricultural Supply Stores:Multi-line dealerships provide calibration services, warranty administration, and trade-in programs. John Deere and AGCO dealer networks in the Corn Belt anchor precision spreader sales with bundled telemetry subscriptions.
- Direct Sales:Manufacturer field representatives engage operations exceeding 10,000 acres with custom specification and volume pricing.
- Garden Centers:Seasonal retail locations serve impulse and replacement purchases for residential segments.
Complex precision equipment flows through Agricultural Supply Stores. Simplified products are migrating fastest toward Online Retail.
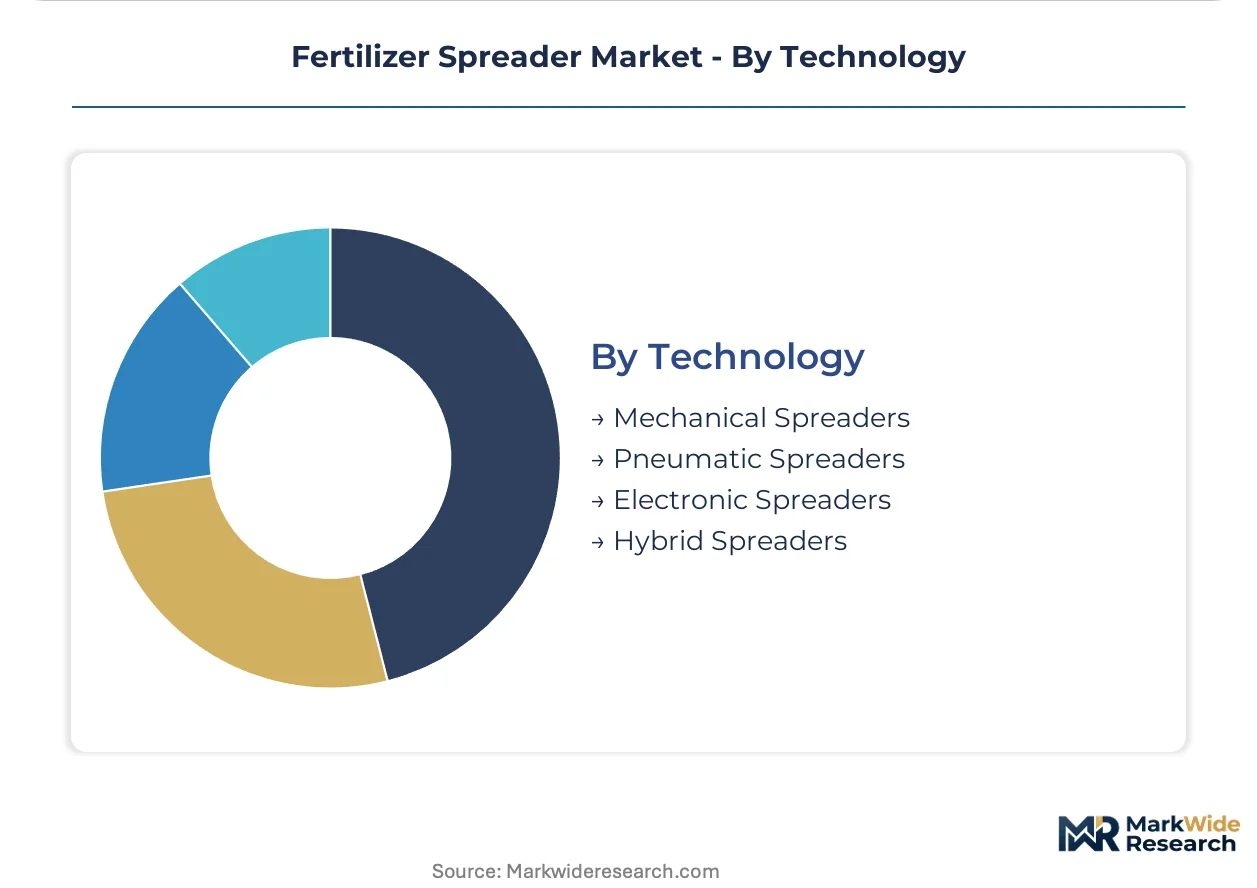
Technology:
Control architecture determines margin structure and replacement cycle velocity.
- Electronic Spreaders:GPS-guided rate control, section-shutoff, and prescription mapping enable variable-rate application with automatic documentation. These systems command premium positioning as EU Green Deal nutrient protocols and EPA Clean Water Act enforcement tighten application efficiency mandates across Germany, France, and watershed-adjacent US counties.
- Mechanical Spreaders:Ground-drive or PTO-powered units with fixed-rate calibration serve cost-sensitive operations and developing markets. Demand persists in Eastern European markets where capital constraints limit precision agriculture adoption.
- Pneumatic Spreaders:Air-assisted delivery systems achieve uniform distribution across irregular terrain and variable wind conditions.
- Hybrid Spreaders:Combined mechanical-electronic architectures offer upgrade pathways for existing equipment bases.
Electronic Spreaders are climbing the fastest as regulatory compliance documentation becomes mandatory. Mechanical Spreaders retain share in price-sensitive market tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers in Germany and the United States dominate production capacity, while consumption concentrates in grain-exporting belts where farm scale justifies capital-intensive precision systems. Regulatory divergence between EPA watershed rules and EU Green Deal nutrient protocols is fragmenting product specifications across Atlantic markets.
United States
Farm consolidation across Iowa, Illinois, and Nebraska drives demand for high-capacity broadcast spreaders with telemetry integration. The EPA enforces Clean Water Act nutrient management standards that restrict application timing near watersheds, compressing equipment utilization windows. Dealer networks in the Corn Belt anchor sales through bundled software-hardware procurement packages.
Germany
Precision agriculture adoption among large-scale arable operations in Lower Saxony and Bavaria accelerates replacement cycles toward GPS-guided variable-rate systems. The EU Green Deal mandates application efficiency audits that force upgrades to section-shutoff capabilities. Manufacturers in Baden-Württemberg specialize in corrosion-resistant hopper construction for export compliance.
Brazil
Soybean expansion across Mato Grosso and Rio Grande do Sul generates demand for wide-swath equipment suited to tropical field conditions. ANVISA chemical registration requirements extend to coating materials used in hopper fabrication, complicating import specifications. Regional equipment assemblers in São Paulo state integrate precision modules from German and US suppliers.
France
Wheat and sugar beet producers in Île-de-France and Hauts-de-France prioritize documented nutrient placement for sustainability audit compliance. REACH chemical registration governs surface treatments and corrosion inhibitors in hopper construction. Equipment distributors in the Paris Basin pilot subscription telemetry services for mid-scale operations lacking capital for outright purchase.
China
Mechanization policy targets in the North China Plain and Northeast grain belt expand addressable market for tractor-integrated spreader configurations. The Ministry of Ecology and Environment tightens agricultural non-point source pollution controls that shape equipment specifications. Domestic manufacturers in Shandong and Heilongjiang provinces compete on cost-adapted mechanical systems for price-sensitive cooperatives.
Fertilizer Spreader Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated agricultural equipment conglomerates anchor premium positioning and regional specialists capture price-sensitive segments. The vendor base stratifies across three archetypes: full-line manufacturers with precision agriculture platforms, specialized spreader fabricators with deep application expertise, and emerging Asian producers leveraging cost-adapted mechanical architectures. Consolidation pressure intensifies as telemetry subscriptions recalibrate revenue models toward recurring service streams, while capacity expansion concentrates in tractor-integrated configurations for Asian market penetration.
Among diversified agricultural equipment manufacturers, Deere & Company and AGCO Corporation exemplify the platform-anchored archetype, bundling spreader hardware with precision agriculture software ecosystems. Kubota Corporation occupies a position bridging compact equipment specialization with geographic expansion across Asian and North American mid-size tractor markets. These three companies represent contrasting strategic postures: integrated software-hardware bundling, broadcast application system depth, and regional scale fabrication respectively.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Kubota Corporation |
| KUHN Group |
| CLAAS KGaA mbH |
| Adams Fertilizer Equipment |
| Mahindra & Mahindra Ltd. |
| Bogballe |
| Others |
Supply Flow & Price Mechanics
Precision agriculture technician concentration in Iowa and Illinois creates labor-cost differentials that widen pricing spreads between GPS-enabled electronic spreaders and mechanical units. Tiered pricing structures across premium telemetry-integrated, standard variable-rate, and economy mechanical configurations reflect these regional skill premiums and calibration service availability.
Pricing Analysis
Margin tightening in economy mechanical tiers traces to steel and aluminum commodity volatility squeezing fixed-price contract profitability. Three-tier pricing structure across premium electronic, standard hybrid, and economy mechanical levels differentiates by GPS certification grade and after-sales telemetry bundling. Pricing pressure intensifies in mid-range segments as Asian manufacturers enter with cost-adapted mechanical architectures. Agricultural producers exceeding 2,000 acres show lowest price sensitivity due to Section 45Z biofuel incentive documentation requirements, while lawn care companies in fragmented markets exhibit highest elasticity.
Supply Chain Analysis
Welding and fabrication labor availability in Germany, the United States, and China determines hopper production capacity allocation across precision and mechanical product lines. Supply chains draw from Taiwanese semiconductor fabs for GPS modules, South Korean battery cell manufacturers for electric drive systems, and domestic steel mills for frame and hopper fabrication. Single-source vulnerability concentrates in Asian semiconductor fabrication for rate controller components. Distribution runs through agricultural supply store networks in the Corn Belt for complex precision equipment, with online retail capturing compact tow-behind segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA Clean Water Act nutrient management standards and EU Green Deal application efficiency audits erect regulatory moats favoring telemetry-integrated incumbents with certification documentation capabilities.
For Market Incumbents: Cement market position by deepening backward integration into GPS rate controller firmware development to reduce Asian semiconductor supply exposure. Prioritize certification investment for ISO 12100 machinery safety compliance to accelerate new model introductions against delayed competitors. Defensive consolidation through captive supply of corrosion-resistant hopper coatings addresses REACH chemical registration requirements extending to European export markets.
For New Entrants and Emerging Players: Begin with compact tractor-integrated spreader configurations in Japan and South Korea where mid-size equipment segments remain underpenetrated by precision-enabled systems. Target equipment-as-a-service contracting models for 500-2,000 acre farms in the Dakotas and Kansas lacking capital allocation flexibility for outright telemetry upgrades. Go-to-market through dealer network partnerships offering bundled agronomic advisory rather than hardware-only positioning.
For Investors and Strategic Acquirers: The window for entry favors specialized spreader fabricators with deep broadcast application expertise and existing precision agriculture software integration. Long-term viability hinges on recurring telemetry subscription revenue streams displacing one-time hardware sales. Monitor Section 45Z biofuel incentive program expansion as inflection signal for documented nutrient placement accuracy demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Deere & Company anchors recurring revenue through software-defined application mapping across installed equipment bases. |
| Backward Integration into Semiconductor Sourcing | AGCO Corporation reduces GPS module lead-time vulnerability through direct supplier relationships with Taiwanese fabs. |
| Compact Tractor Configuration Expansion | Kubota Corporation extends geographic footprint across Asian and North American mid-size equipment segments. |
| Equipment-as-a-Service Contracting | Dealer networks in Kansas pilot per-acre spreading agreements transferring technology obsolescence risk from farm operators. |
| Corrosion-Resistant Material Certification | European manufacturers in Baden-Württemberg reformulate hopper coatings to maintain REACH-compliant market access. |
Methodological Framework
Document review covered SEC 10-K filings from agricultural equipment manufacturers, EPA Clean Water Act enforcement records, and EU Green Deal nutrient protocol documentation, complemented by interviews with precision agriculture product managers, farm equipment dealer principals, and agronomic advisory service directors. Secondary validation drew from USDA mechanization surveys, customs trade data for spreader component imports, and ISO machinery safety certification databases. Bottom-up equipment shipment modeling triangulated against top-down farm expenditure analysis across the Corn Belt and European arable regions.
Historical volume trajectories cross-referenced against panel input from OEM procurement teams and aftermarket service heads informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type, technology tier, farm scale, and regional regulatory cluster. CAGRs derived from slope analysis of replacement cycle compression rates and precision agriculture adoption curves. Industry-specific forecast inputs incorporated Section 45Z biofuel incentive program eligibility expansion and EU application efficiency audit implementation timelines.
Underlying measurement precision varies by segment; electronic spreader volumes carry tighter precision than mechanical tiers due to telemetry subscription tracking granularity. Forecasts reflect documented assumptions regarding farm consolidation velocity and semiconductor supply normalization. Material deviation in EPA enforcement intensity or REACH chemical registration scope expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Nano Fertilizer Market
Fertilizers
France Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market